
 Intravascular Stents Market | 2026-2036
Intravascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Intravascular Stents Market Analytics
A shift from single-source cobalt-chromium alloy procurement to multi-source supply networks is repositioning how manufacturers secure raw materials for stent production. Abbott Laboratories leverages captive polymer coating capabilities to differentiate its drug-eluting portfolio. Medtronic anchors its competitive stance through integrated R&D across balloon and stent platforms. Boston Scientific Corporation sustains manufacturing scale advantages in nitinol self-expanding stent categories.
Intravascular stents are tubular metallic or bioresorbable scaffolds deployed via catheter-based delivery systems to restore luminal patency in narrowed or occluded blood vessels, typically manufactured from cobalt-chromium, platinum-iridium, or poly-L-lactic acid with strut thickness ranging from 60 to 140 micrometers. Their primary purpose is to prevent acute vessel closure and reduce restenosis following percutaneous transluminal angioplasty. Coronary stents occupy the dominant revenue position due to high procedural volumes in acute myocardial infarction settings, while peripheral stents represent the fastest-expanding category driven by rising endovascular treatment of femoropopliteal disease. Drug-eluting delivery mode configurations command premium positioning because paclitaxel and sirolimus analog coatings demonstrably lower target lesion revascularization rates compared with bare-metal alternatives.
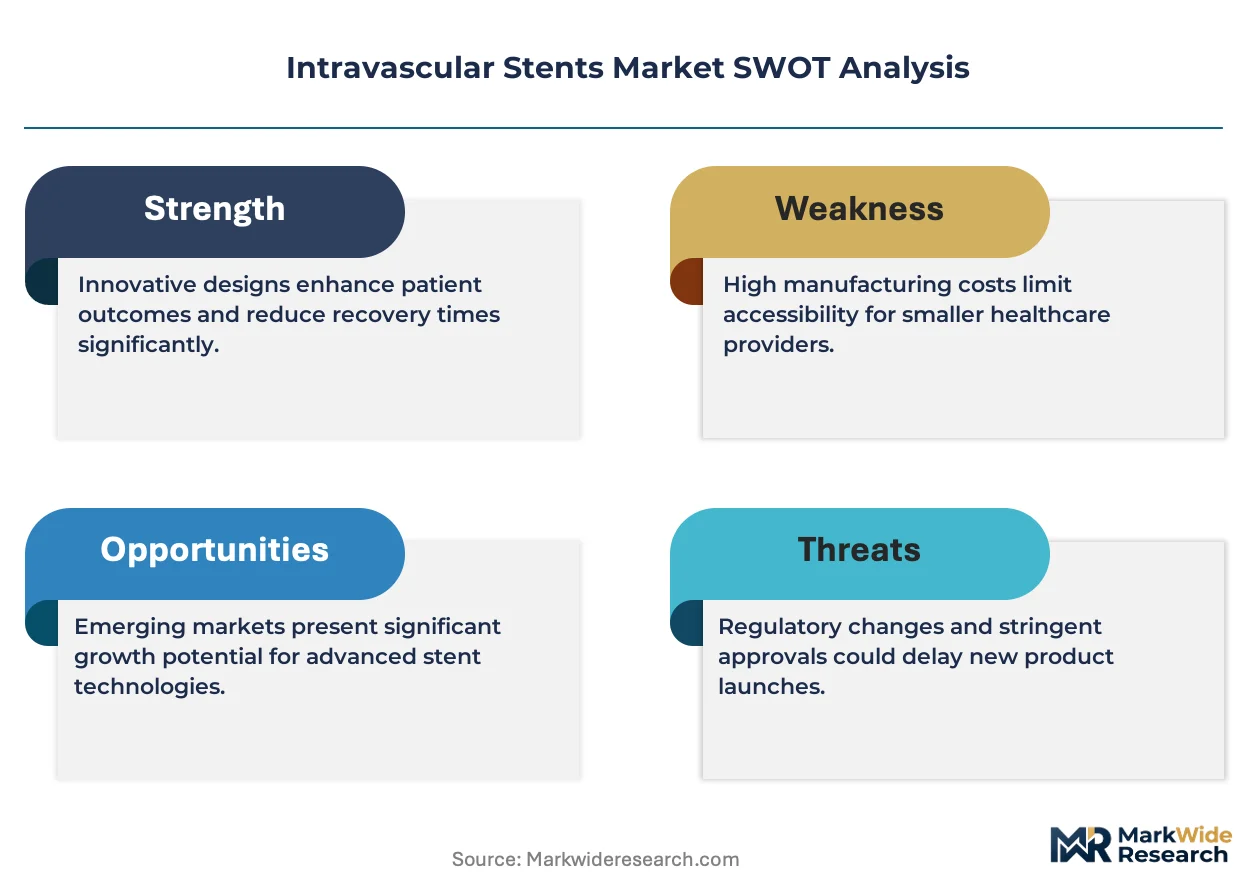
The FDA premarket approval process and European Medical Device Regulation (MDR) conformity assessment requirements create substantial barriers to market entry for novel stent technologies, directly influencing clinical trial investment thresholds and commercialization timelines. Japan's Ministry of Health, Labour and Welfare (MHLW) through the Pharmaceutical and Medical Devices Agency (PMDA) maintains distinct reimbursement listing procedures that shape product launch sequencing across Asia-Pacific. Stakeholders must monitor evolving health technology assessment methodologies as payer organizations tighten evidentiary standards for incremental clinical benefit relative to predicate devices.
Market Dynamics
The FDA's evolving premarket submission pathways for drug-eluting devices are compressing development timelines while forcing manufacturers to front-load clinical evidence generation, fundamentally restructuring how stent portfolios reach commercialization.
Growth Catalysts
- Cardiac catheterization lab expansion:United States hospital systems are building dedicated interventional cardiology centers to handle rising percutaneous coronary intervention volumes, directly expanding stent addressable demand.
- European Medical Device Regulation (MDR) harmonization:Streamlined conformity assessment procedures across EU member states are reducing redundant testing burdens for cobalt-chromium stent platforms.
- Femoropopliteal disease endovascular pivot:Japan's aging demographic is driving procedural shifts from bypass surgery toward nitinol self-expanding peripheral stent deployment.
Market Restraints
- Cobalt-chromium alloy supply concentration:Three specialty foundries control premium-grade medical alloy output, exposing stent manufacturers to input price volatility and allocation risk.
- Bioresorbable scaffold technical limitation:Poly-L-lactic acid degradation kinetics remain unpredictable in diabetic patient populations, constraining addressable indications.
- PMDA reimbursement friction:Japan's Ministry of Health, Labour and Welfare maintains extended listing timelines that delay commercial recovery for novel drug-eluting technologies.
Strategic Opportunities
- Rural United States interventional cardiology deserts:Mobile catheterization lab deployment models are creating access points in underserved secondary markets.
- Paclitaxel-sirolimus combination coating convergence:Dual-drug polymer matrices are opening premium positioning above single-agent drug-eluting stents.
- India's PLI scheme medical device incentive:Production-linked incentive frameworks are attracting contract manufacturing investment for bare-metal stent export capacity.
Industry Challenges
- Polymer coating specialist talent scarcity:Drug-eluting stent R&D pipelines compete for limited formulation chemists with ophthalmic and orthopedic device sectors.
- ISO 13485 certification timeline compression:Notified body backlogs are extending quality management system audit queues to 14-18 months.
- Strut thickness standardization delays:Absent harmonized metrology protocols, manufacturers face redundant validation testing across FDA, PMDA, and Health Canada submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravascular Stents Market |
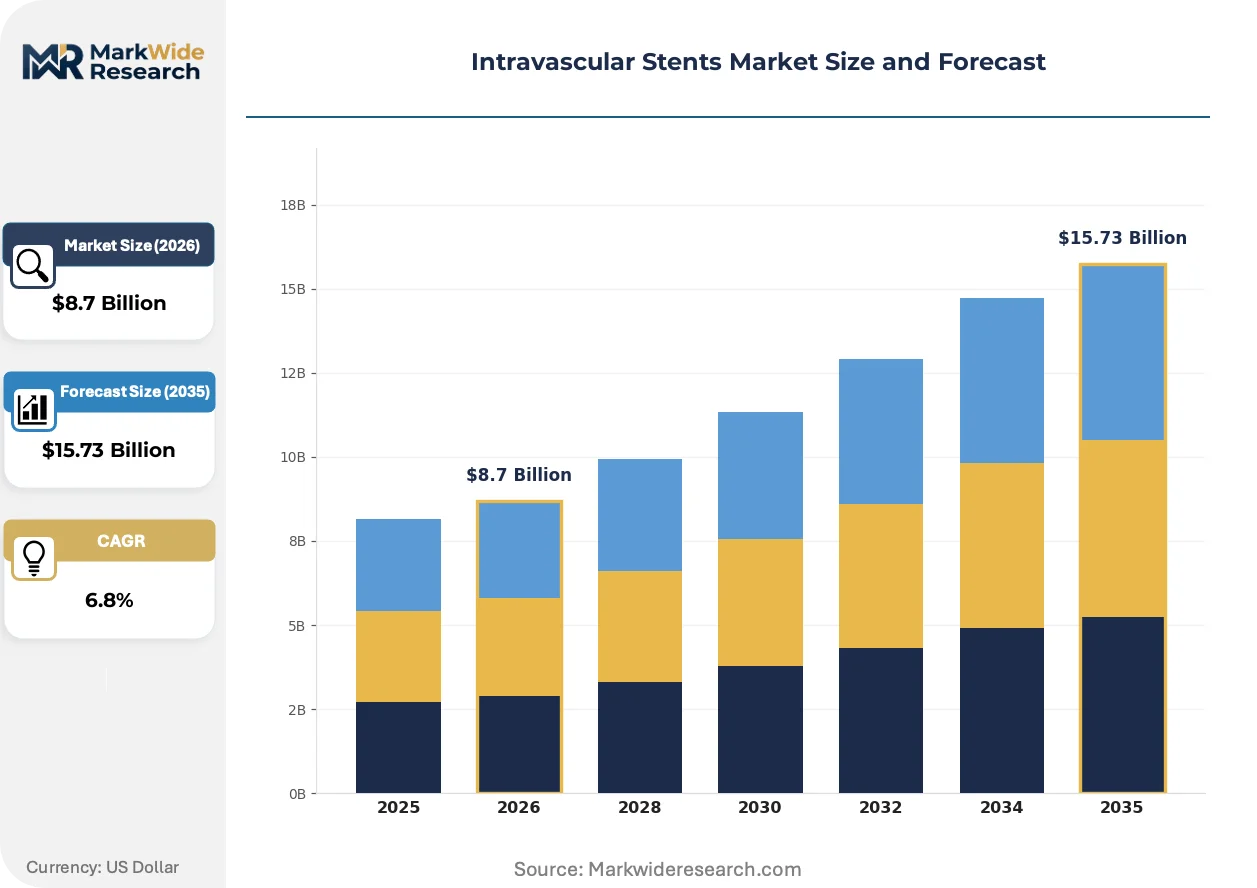
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Stents, Peripheral Stents, Carotid Stents, Renal Stents Delivery Mode: Balloon-Expandable, Self-Expanding, Bioabsorbable, Drug-Eluting End User: Hospitals, Catheterization Labs, Specialty Clinics, Research Institutions Material: Metallic, Drug-Coated, Polymer-Based, Hybrid |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Terumo Corporation, B. Braun SE, BIOTRONIK SE & Co. KG, MicroPort Scientific Corporation, Meril Life Sciences Pvt. Ltd., W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravascular Stents Market Evolving Landscape
Bioresorbable scaffold technology is absorbing capital allocation previously directed toward incremental bare-metal improvements, while regulatory convergence and procurement centralization are simultaneously reshaping competitive entry points.
Thin-strut cobalt-chromium platforms with sub-70 micrometer profiles are absorbing procedural preference in complex coronary lesion subsets. Interventional cardiologists in Germany and Japan are adopting these platforms for bifurcation and calcified vessel cases at accelerating rates. The technology is absorbing market share from thicker-strut predecessors by demonstrating reduced side-branch jailing and improved deliverability through tortuous anatomy.
The European Medical Device Regulation (MDR) is forcing systematic clinical evidence updates for legacy drug-eluting stent approvals. Manufacturers must now submit post-market clinical follow-up data on paclitaxel and sirolimus analog safety profiles to maintain CE marking validity. High-risk class III devices face the steepest compliance burden, with several predicate stent families requiring prospective registry supplementation.
Hospital procurement consortia in the United States are consolidating stent purchasing through single-source framework agreements. Integrated delivery networks in Texas and Florida are replacing physician preference item autonomy with value-analysis committee oversight. This concentration is most visible in acute myocardial infarction settings where standardized formularies now govern 60-70 percent of drug-eluting stent selection.
Intravascular Stents Market Segmentation
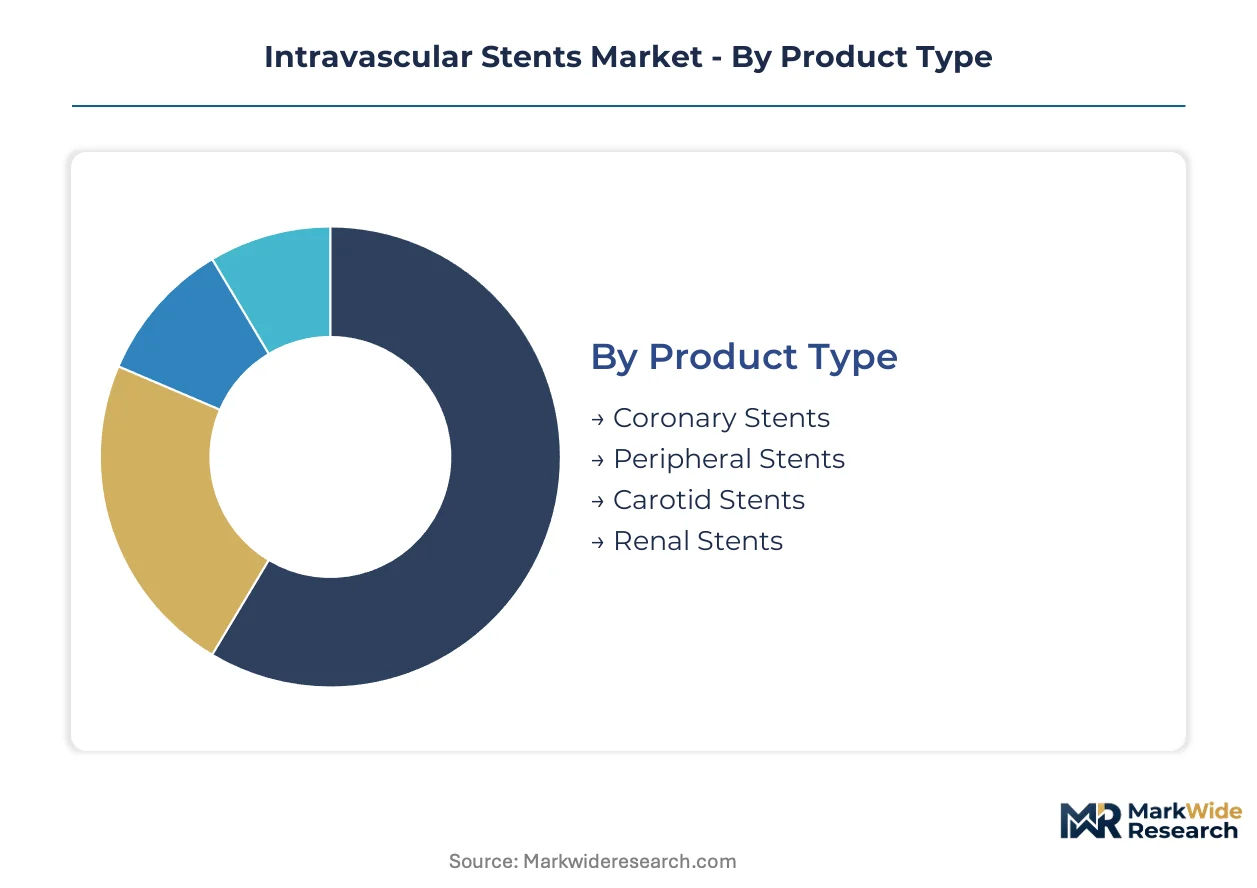
Stent segmentation reveals how clinical application, deployment mechanism, and material science intersect to determine pricing power and regulatory pathway complexity. Manufacturers configure product portfolios across these dimensions to capture differential margin pools in acute versus chronic intervention settings.
Product Type:
Customization intensity spans from standardized coronary platforms to patient-matched peripheral geometries, with procedural volume and lesion complexity driving specification divergence.
- Coronary Stents:Cobalt-chromium and platinum-iridium tubular scaffolds with 60-100 micrometer strut thickness dominate percutaneous coronary intervention volumes. Demand concentrates in United States hospital systems building dedicated interventional cardiology centers to handle acute myocardial infarction caseloads.
- Peripheral Stents:Nitinol self-expanding designs with enhanced flexibility navigate tortuous femoropopliteal anatomy. Japan's aging demographic is driving procedural shifts from bypass surgery toward endovascular deployment in this segment.
- Carotid Stents:Embolic protection-integrated systems address stroke prevention in extracranial carotid artery stenosis cases.
- Renal Stents:Short-segment balloon-expandable platforms target atherosclerotic renal artery disease with diameter-specific sizing.
Most installed capacity flows through Coronary Stents. Expansion is steepest in Peripheral Stents.
Delivery Mode:
Cost tier stratification separates premium drug-eluting configurations from commoditized bare-metal alternatives, with reimbursement coding directly influencing adoption thresholds.
- Balloon-Expandable:Stainless steel or cobalt-chromium platforms crimped onto compliant balloons deliver precise diameter control in coronary bifurcations. Germany's interventional cardiologists are adopting thin-strut sub-70 micrometer variants for calcified vessel cases at accelerating rates.
- Self-Expanding:Shape-memory nitinol scaffolds deploy without balloon inflation, conforming to vessel wall irregularities in peripheral anatomy. Demand is concentrating in femoropopliteal disease settings where vessel tortuosity exceeds balloon deliverability limits.
- Bioabsorbable:Poly-L-lactic acid scaffolds degrade over 24-36 months, restoring vessel vasomotion after initial support.
- Drug-Eluting:Polymer matrices releasing paclitaxel or sirolimus analogs demonstrably lower target lesion revascularization rates versus bare-metal alternatives.
Balloon-Expandable systems carry the highest shipment volumes. Drug-Eluting configurations are climbing the fastest as FDA premarket pathways compress development timelines.
End User:
Customer type determines purchasing modality, with integrated delivery networks imposing formulary constraints that physician-owned catheterization labs escape.
- Hospitals:Acute care institutions with 24/7 interventional cardiology coverage handle STEMI and complex multivessel disease. United States hospital systems in Texas and Florida are consolidating stent purchasing through single-source framework agreements.
- Catheterization Labs:Dedicated outpatient facilities focus on elective percutaneous coronary intervention with streamlined throughput.
- Specialty Clinics:Peripheral vascular centers concentrate on endovascular limb salvage and claudication management.
- Research Institutions:Academic medical centers conduct first-in-human trials and post-market surveillance registries.
Catheterization Labs absorb the majority of coronary procedures. Specialty Clinics are gaining share fastest in peripheral vascular intervention.
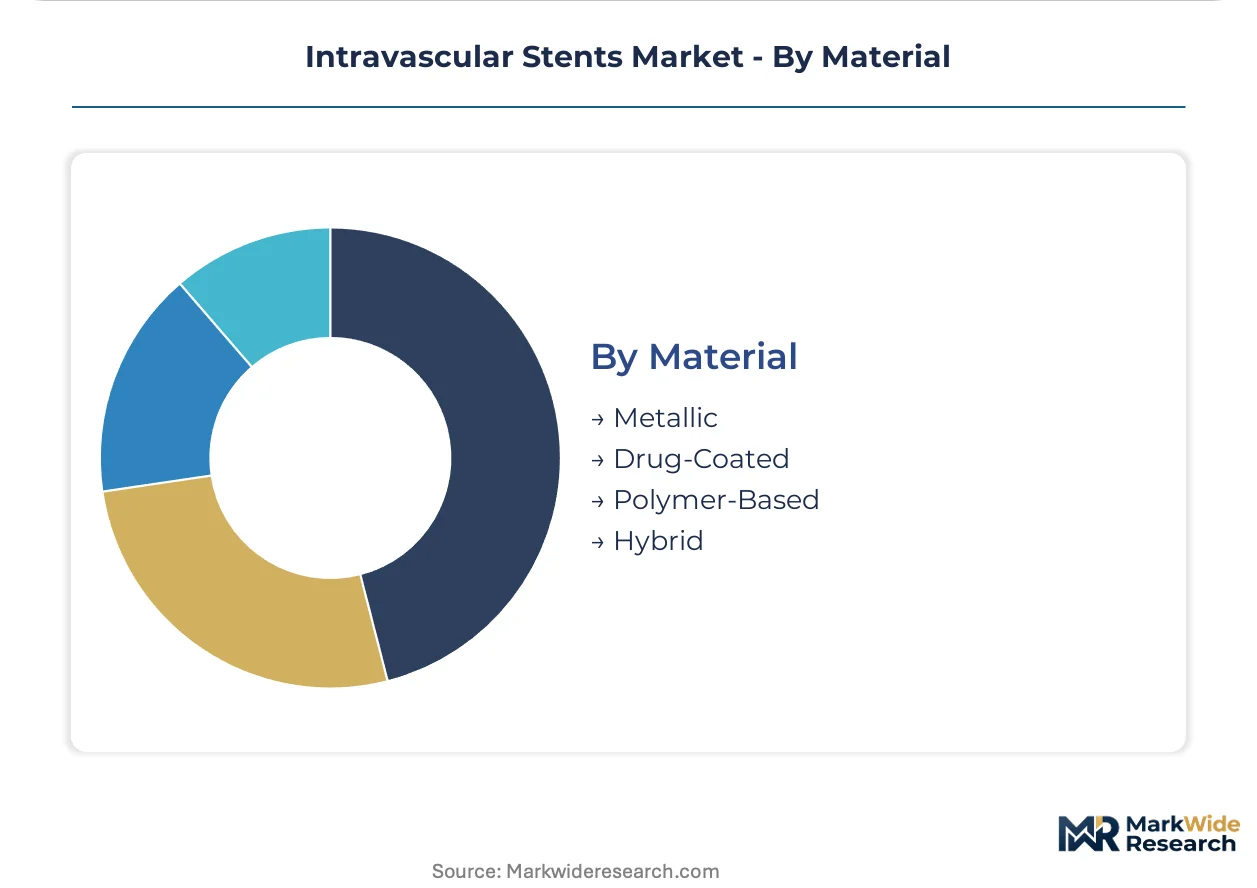
Material:
Supply concentration in specialty alloy foundries and polymer coating specialists creates input cost divergence across material categories.
- Metallic:Cobalt-chromium, stainless steel, and nitinol provide radial strength with proven long-term biocompatibility. Three specialty foundries control premium-grade medical alloy output, exposing manufacturers to allocation risk.
- Drug-Coated:Active pharmaceutical ingredient integration requires polymer formulation chemistry expertise that competes with ophthalmic and orthopedic device sectors for scarce talent.
- Polymer-Based:Poly-L-lactic acid and polyglycolic acid scaffolds enable complete bioresorption but face unpredictable degradation kinetics in diabetic populations.
- Hybrid:Composite architectures combining metallic strength with drug-eluting polymer layers balance mechanical performance and therapeutic delivery.
Metallic platforms retain dominant installed base. Drug-Coated configurations are expanding most quickly as European MDR harmonization streamlines conformity assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac catheterization lab density in the United States determines global procedural volume distribution. Germany's interventional cardiology infrastructure anchors European demand. Japan's aging demographic accelerates peripheral stent adoption. India's production-linked incentive schemes attract contract manufacturing investment.
United States
Hospital systems in Texas and Florida are building dedicated interventional cardiology centers to handle rising acute myocardial infarction caseloads. The FDA's evolving premarket submission pathways for drug-eluting devices are compressing development timelines while front-loading clinical evidence requirements. Integrated delivery networks in these states are consolidating stent purchasing through single-source framework agreements that replace physician preference item autonomy.
Germany
Interventional cardiologists are adopting thin-strut sub-70 micrometer cobalt-chromium platforms for bifurcation and calcified vessel cases at accelerating rates. The European Medical Device Regulation (MDR) is forcing systematic clinical evidence updates for legacy drug-eluting stent approvals through post-market clinical follow-up submissions. Medical device clusters in Baden-Württemberg and Bavaria concentrate specialty foundry capacity for premium-grade cobalt-chromium alloy output.
Japan
The aging demographic is driving procedural shifts from bypass surgery toward nitinol self-expanding peripheral stent deployment in femoropopliteal disease settings. The Ministry of Health, Labour and Welfare through the Pharmaceutical and Medical Devices Agency (PMDA) maintains extended reimbursement listing timelines that delay commercial recovery for novel drug-eluting technologies. Tokyo and Osaka metropolitan areas concentrate the majority of specialized interventional cardiology centers handling complex multivessel cases.
India
Production-linked incentive frameworks under the PLI scheme are attracting contract manufacturing investment for bare-metal stent export capacity expansion. The Central Drugs Standard Control Organization (CDSCO) regulates medical device quality standards while streamlining import substitution pathways. Manufacturing clusters in Maharashtra and Gujarat are developing captive polymer coating capabilities to serve regional demand.
China
Domestic manufacturers are capturing share in coronary stent categories through cost-competitive cobalt-chromium platforms. The National Medical Products Administration (NMPA) maintains distinct registration pathways for drug-eluting versus bare-metal configurations. Yangtze River Delta medical device clusters in Shanghai and Suzhou concentrate nitinol processing capacity for self-expanding peripheral applications.
Intravascular Stents Market Competitive Landscape
Global majors compete with regional champions across technology licensing and distribution reach. The vendor base stratifies into three tiers: integrated multinationals with captive polymer coating capabilities, mid-scale specialists with alloy processing expertise, and emerging contract manufacturers leveraging India's PLI incentives. Two dominant competitive moves define current positioning: backward integration into specialty alloy foundries to secure cobalt-chromium supply, and strategic partnerships with academic medical centers to generate post-market clinical follow-up data for MDR compliance.
Among integrated multinationals, Abbott Laboratories, Boston Scientific Corporation, and Medtronic exemplify the premium-tier archetype through differentiated technology portfolios. Abbott's captive polymer coating capabilities position it within the drug-eluting specialization vector. Boston Scientific occupies a scale-driven position in nitinol self-expanding categories. Medtronic anchors the integrated R&D archetype across balloon and stent platform convergence. These three represent the structural concentration through which regulatory convergence and procurement centralization filter competitive entry.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| B. Braun SE |
| BIOTRONIK SE & Co. KG |
| MicroPort Scientific Corporation |
| Meril Life Sciences Pvt. Ltd. |
| W. L. Gore & Associates |
| Others |
Value Network & Pricing Analysis
Polymer formulation chemist scarcity in Massachusetts and Minnesota widens labor-cost differentials between premium drug-eluting stent tiers and commoditized bare-metal alternatives, compressing margins at the economy tier while sustaining pricing power for dual-drug coating configurations.
Pricing Analysis
Input-cost pass-through from cobalt-chromium alloy procurement dominates pricing structures across balloon-expandable and self-expanding stent categories. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy contract-manufactured tiers separates FDA-approved configurations from CE-marked alternatives and Indian PLI-sourced bare-metal platforms. Cost compression in the economy tier is intensifying because Maharashtra-based contract manufacturers absorb cobalt-chromium price volatility to capture export volume. Hospital procurement committees exhibit highest price sensitivity in acute myocardial infarction settings where standardized formularies govern bulk purchasing, while specialized interventional cardiology centers retain lowest sensitivity for thin-strut sub-70 micrometer platforms.
Supply Chain Analysis
Workforce-availability constraints in Baden-Württemberg specialty foundries and Yangtze River Delta nitinol processing clusters tether stent manufacturing capacity to regional labor pools with polymer coating expertise. Supply concentrates in Germany, China, and India for cobalt-chromium alloy output, nitinol shape-memory scaffold fabrication, and bare-metal contract assembly respectively. Raw material dependencies span premium-grade medical alloys, paclitaxel and sirolimus analog active pharmaceutical ingredients, and compliant balloon catheter substrates. Single-source vulnerability in cobalt-chromium alloy supply exposes manufacturers to allocation risk when three specialty foundries control premium-grade output. Distribution runs through hospital procurement consortia in Texas and Florida, integrated delivery network value-analysis committees, and government tenders in Maharashtra and Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intravascular stents market functions as a stable compounder anchored by demographic-driven procedural volume expansion in aging populations requiring femoropopliteal and coronary intervention.
For Market Incumbents: Anticipate procurement consolidation by securing backward integration into cobalt-chromium specialty foundries to defend against alloy allocation risk, while accelerating post-market clinical follow-up data generation for European MDR compliance to maintain CE marking validity against predicate device displacement threats. For New Entrants and Emerging Players: Enter via India's PLI scheme medical device incentives to establish bare-metal stent export capacity serving secondary markets, targeting rural United States interventional cardiology deserts through mobile catheterization lab partnerships as the most penetrable access point. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with alloy processing expertise but lacking captive polymer coating capabilities, positioning them for acquisition to complete drug-eluting technology portfolios. Long-term viability over a five-to-ten year horizon rests on reimbursement listing velocity with Japan's PMDA as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | FDA's evolving drug-eluting device submission requirements compress development timelines while front-loading clinical evidence investment. |
| CE Marking Pathway | European MDR post-market clinical follow-up mandates force systematic evidence updates for legacy stent approvals. |
| Hospital System Partnership | Single-source framework agreements with Texas and Florida integrated delivery networks secure volume commitment against procurement consolidation. |
| Backward Integration | Captive cobalt-chromium alloy foundry investment insulates manufacturers from three-supplier concentration risk. |
| Reimbursement Strategy | PMDA listing timeline acceleration unlocks commercial recovery velocity for novel drug-eluting technologies in Japan. |
Research Methodology
Multiple input streams — primary interviews with interventional cardiologists and hospital GPO contracts managers, secondary validation through FDA 510(k) and PMA filings, CMS Medicare procedure databases, and European MDR notified body documentation — were reconciled through bottom-up shipment volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product type, delivery mode, end user, and material segmentation dimensions anchored value projections over the analysis window. CAGRs were derived from procedural volume growth trajectories in acute myocardial infarction and femoropopliteal disease settings, cross-referenced with stent price elasticity assumptions and reimbursement coding evolution.
The model holds under stable regulatory pathway timelines and alloy supply continuity; deviation in FDA premarket review duration, PMDA reimbursement listing velocity, or cobalt-chromium foundry allocation would shift commercialization trajectory assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market