
 LAMEA Cardiac Surgical Devices Market | 2026-2036
LAMEA Cardiac Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Cardiac Surgical Devices Market Analytics
Buyer concentration among hospital procurement groups across Latin America and the Middle East is shifting toward centralized purchasing agreements. Medtronic PLC leverages its broad perfusion portfolio to anchor relationships with these consolidated buyers. Abbott Laboratories differentiates through transcatheter valve platforms that compete for shelf space in tier-one cardiac centers. Edwards Lifesciences specializes in tissue valve technologies that sustain premium positioning within constrained reimbursement environments.
LAMEA cardiac surgical devices encompass mechanical and bioprosthetic implants, perfusion circuits, and precision instrumentation engineered for procedures requiring cardiopulmonary support at flow rates typically exceeding four liters per minute. These systems restore or replace cardiac function during open-chest, minimally invasive, or robotic-assisted interventions. Heart valve replacements command the deepest margin pools due to bioprosthetic durability requirements and replacement cycle economics. Minimally invasive technology segments expand fastest as training programs proliferate in São Paulo, Dubai, and Johannesburg surgical centers. Vascular closure devices occupy a mature growth trajectory where price sensitivity limits expansion in public-sector tenders.
Brazil's ANVISA, South Africa's SAHPRA, and Saudi Arabia's SFDA enforce divergent clinical evidence standards that shape registration timelines and market access costs across the LAMEA region. CE-marked devices often satisfy Middle Eastern regulators through abbreviated conformity pathways, while African markets rely on WHO prequalification or reference country approvals to accelerate adoption. Stakeholders must monitor harmonization initiatives between Gulf Cooperation Council regulators and African Medicines Agency frameworks to anticipate shifting compliance burdens.
Market Dynamics
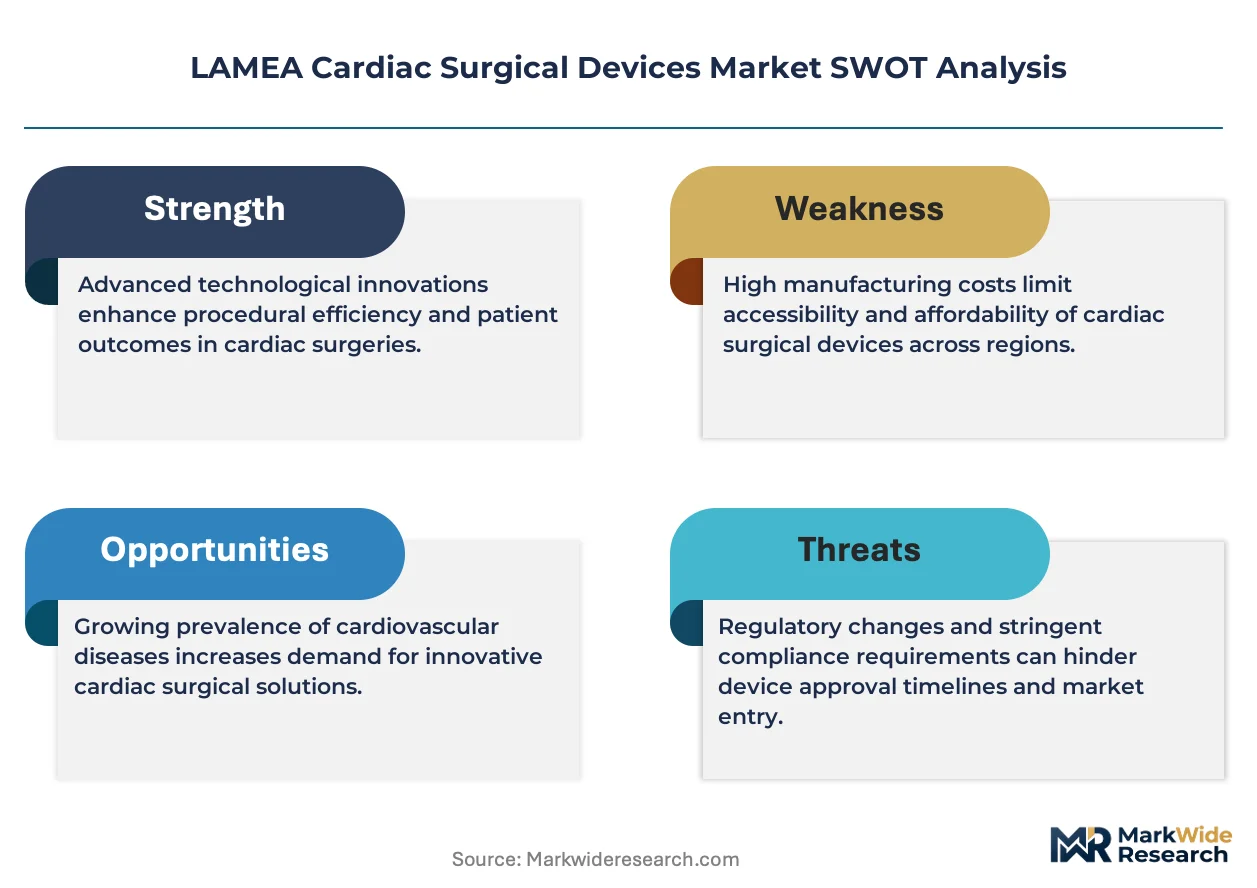
Hospital procurement consolidation across Latin America and the Middle East is compressing vendor margins while elevating technical service requirements as the primary competitive differentiator in cardiac surgical device selection.
Growth Catalysts
- Minimally Invasive Surgical Training:São Paulo, Dubai, and Johannesburg surgical centers now host structured fellowship programs that expand the addressable physician base for transcatheter valve and robotic-assisted procedures.
- CE-Mark Pathway Recognition:Saudi Arabia's SFDA and Gulf Cooperation Council regulators accept European conformity documentation, truncating registration timelines for devices already cleared under EU MDR frameworks.
- Bioprosthetic Valve Replacement Cycles:Tissue valve durability economics create recurring revenue streams as patient populations age into secondary intervention windows across Brazilian metropolitan hospital networks.
Market Restraints
- Input Material Concentration:Bovine pericardial tissue sourcing depends on Brazilian and Argentine abattoir supply chains vulnerable to foot-and-mouth disease quarantine protocols.
- Public-Sector Price Compression:Brazil's SUS unified health system tenders impose mandatory 25-30% domestic content requirements that inflate landed costs for imported precision instrumentation.
- Substitution Threat from Transcatheter Platforms:Transcatheter aortic valve replacement procedures in eligible patients reduce open-chest surgical volumes for mechanical and tissue valve implants.
Strategic Opportunities
- Underpenetrated African Markets:Nigeria, Kenya, and Egypt maintain surgical volumes below 150 cardiac procedures per million population versus Brazil's 800, creating expansion corridors for perfusion circuit distributors.
- Remote Proctoring Networks:Real-time surgical guidance platforms enable case-volume growth in tier-two Saudi and Emirati hospitals without relocating specialist physicians.
- WHO Prequalification Acceleration:Reference country approval pathways through South Africa's SAHPRA unlock preferential tender access across African Medicines Agency member states.
Industry Challenges
- Perfusionist Talent Scarcity:Cardiopulmonary bypass operation requires certified technicians; training program capacity in LAMEA markets lags equipment installation rates by 40-60%.
- Multi-Jurisdictional Registration Burden:Divergent clinical evidence standards between ANVISA, SAHPRA, and SFDA force redundant trial designs that extend time-to-revenue by 18-24 months.
- Legacy System Integration Friction:New robotic surgical platforms require retrofitting existing hybrid operating suites, complicating capital deployment in constrained Middle Eastern hospital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Cardiac Surgical Devices Market |
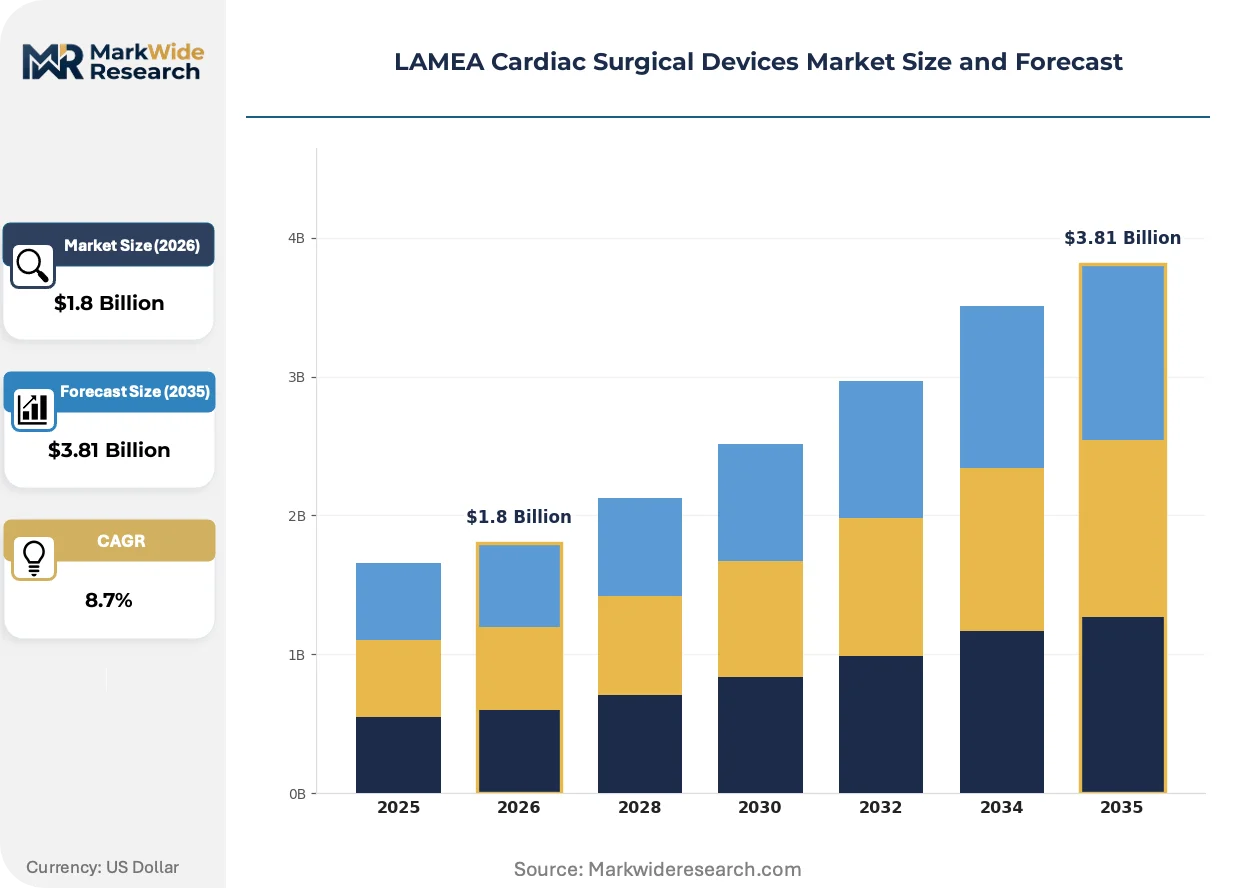
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valve, Cardiopulmonary Bypass, Surgical Instrumentation, Vascular Closure Devices End User: Hospitals, Surgical Centers, Clinics, Cardiology Institutions Technology: Minimally Invasive, Robotic-Assisted, Open-Heart Surgery, Hybrid Technology Application: Coronary Artery Bypass, Mitral Valve Repair, Aortic Aneurysm Surgery, Congenital Heart Defects |
| Companies Covered | Medtronic PLC, Boston Scientific Corporation, Abbott Laboratories, Terumo Corporation, B. Braun Melsungen AG, Cardinal Health, Inc., Edwards Lifesciences, LivaNova PLC, Stryker Corporation, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Cardiac Surgical Devices Market Evolving Landscape
Digital perfusion monitoring and AI-augmented surgical planning are compressing procedure variability while regulatory harmonization initiatives reshape market access economics across the LAMEA region.
Sensor-embedded extracorporeal circulation systems is integrating real-time hematocrit, oxygen saturation, and bubble detection into unified dashboard interfaces. Tier-one cardiac centers in São Paulo and Riyadh are deploying these platforms during high-complexity redo operations. The technology is integrating perfusion safety protocols with anesthesia workflow management, reducing unplanned circuit interruptions and associated neurological complications.
Gulf Cooperation Council regulators are advancing mutual recognition agreements that collapse duplicate technical documentation requirements between Saudi Arabia, UAE, and Qatar. Device manufacturers now submit single dossiers for multi-market clearance, cutting registration expenditures by approximately one-third. Bioprosthetic valve suppliers with established CE-mark portfolios capture first-mover advantage as abbreviated pathways prioritize reference-country approvals.
Centralized hospital procurement consortia in Brazil and Mexico are unbundling device supply from technical training and long-term service contracts. Standalone capital purchases give way to multi-year performance agreements where vendors retain ownership of perfusion consoles and charge per-procedure utilization fees. This shift concentrates purchasing power among three to four dominant hospital groups while marginalizing smaller distributors lacking service infrastructure.
LAMEA Cardiac Surgical Devices Market Segmentation
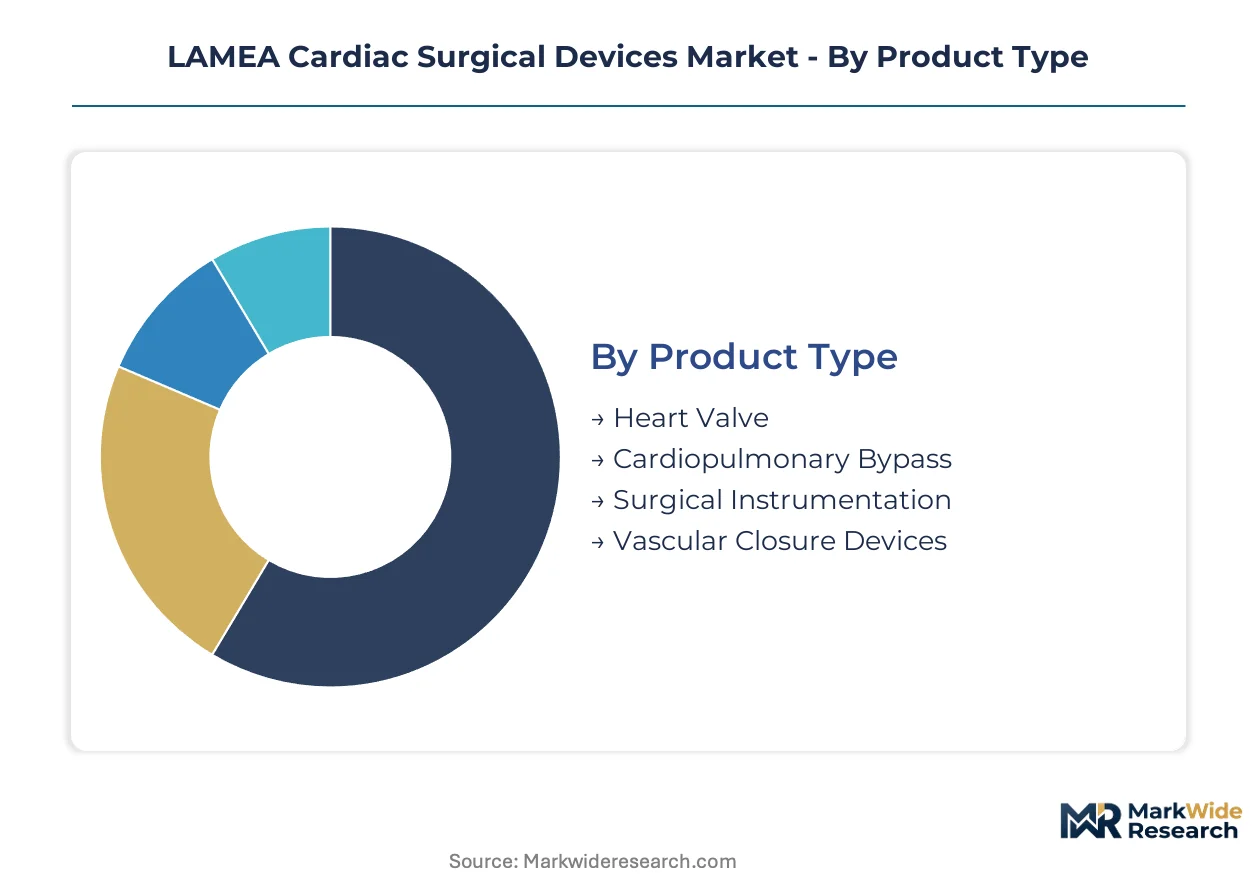
Segmentation in the LAMEA cardiac surgical devices market reveals how capital deployment, regulatory exposure, and reimbursement mechanics concentrate profit pools unevenly across product and customer categories. Understanding these fault lines enables vendors to prioritize R&D budgets and field service investments where returns compound fastest.
Product Type:
Capital intensity varies dramatically across this category, with perfusion infrastructure requiring seven-figure installed bases while disposable instrumentation demands lighter upfront commitment.
- Heart Valve:Bioprosthetic and mechanical valve platforms incorporate bovine pericardial tissue or pyrolytic carbon occluders engineered for hemodynamic performance across 15-20 year replacement cycles. São Paulo's metropolitan hospital networks concentrate demand as aging patient cohorts age into secondary intervention windows.
- Cardiopulmonary Bypass:Extracorporeal circulation systems integrate roller or centrifugal pumps with oxygenators, heat exchangers, and arterial filters capable of sustaining four-to-six liter-per-minute flow rates during cross-clamp intervals. Johannesburg and Dubai surgical centers are expanding perfusion program capacity fastest, though certified technician scarcity constrains equipment utilization rates.
- Surgical Instrumentation:Precision sternal saws, retractors, and needle holders fabricated from surgical-grade stainless steel support tissue manipulation across open-chest and minimally invasive approaches.
- Vascular Closure Devices:Suture-mediated and clip-based systems enable femoral artery hemostasis following catheter-based interventions, competing on compression time reduction in high-throughput Brazilian catheterization labs.
Cardiopulmonary bypass absorbs the bulk of installed capacity; heart valve platforms are expanding most quickly.
End User:
Procurement authority concentrates among consolidated hospital groups, fragmenting across independent surgical centers and clinic networks with divergent technical service requirements.
- Hospitals:Tier-one cardiac centers in Brazil, Saudi Arabia, and South Africa maintain hybrid operating suites, dedicated perfusion teams, and fellowship training programs that anchor complex valve and bypass procedure volumes.
- Surgical Centers:Ambulatory facilities in Mexico City and Santiago concentrate same-day vascular closure and diagnostic catheterization, requiring portable, lower-footprint equipment configurations.
- Clinics:Community-based cardiology practices in Nigeria and Kenya perform preoperative diagnostics and postoperative monitoring, referring surgical candidates to regional hospital hubs.
- Cardiology Institutions:Academic medical centers in Cairo and Riyadh combine research mandates with high-complexity case volumes, prioritizing robotic-assisted platforms for trainee exposure.
Hospitals command the deepest equipment investment; surgical centers are climbing the fastest as ambulatory reimbursement expands.
Technology:
Training infrastructure and capital requirements stratify adoption curves, with robotic platforms demanding dedicated fellowship pipelines absent across most African markets.
- Minimally Invasive:Thoracoscopic and transcatheter approaches reduce sternotomy trauma through port-access valve repair and endoscopic vein harvesting, proliferating fastest where ANVISA and SFDA have cleared specific device platforms.
- Robotic-Assisted:Telemanipulation systems enable mitral valve repair through millimeter-scale incisions with tremor-filtered instrument control, concentrated in Saudi and Emirati centers with dedicated training consortia.
- Open-Heart Surgery:Conventional median sternotomy remains the default for complex redo operations and multi-vessel bypass, dominating public-sector tender volumes across Brazil's SUS network.
- Hybrid Technology:Combined surgical-catheterization suites integrate imaging and perfusion capabilities for single-stage valve and coronary interventions, requiring retrofit capital that only consolidated hospital groups deploy.
Open-heart surgery retains the largest installed base; minimally invasive platforms are gaining share fastest as training programs mature.
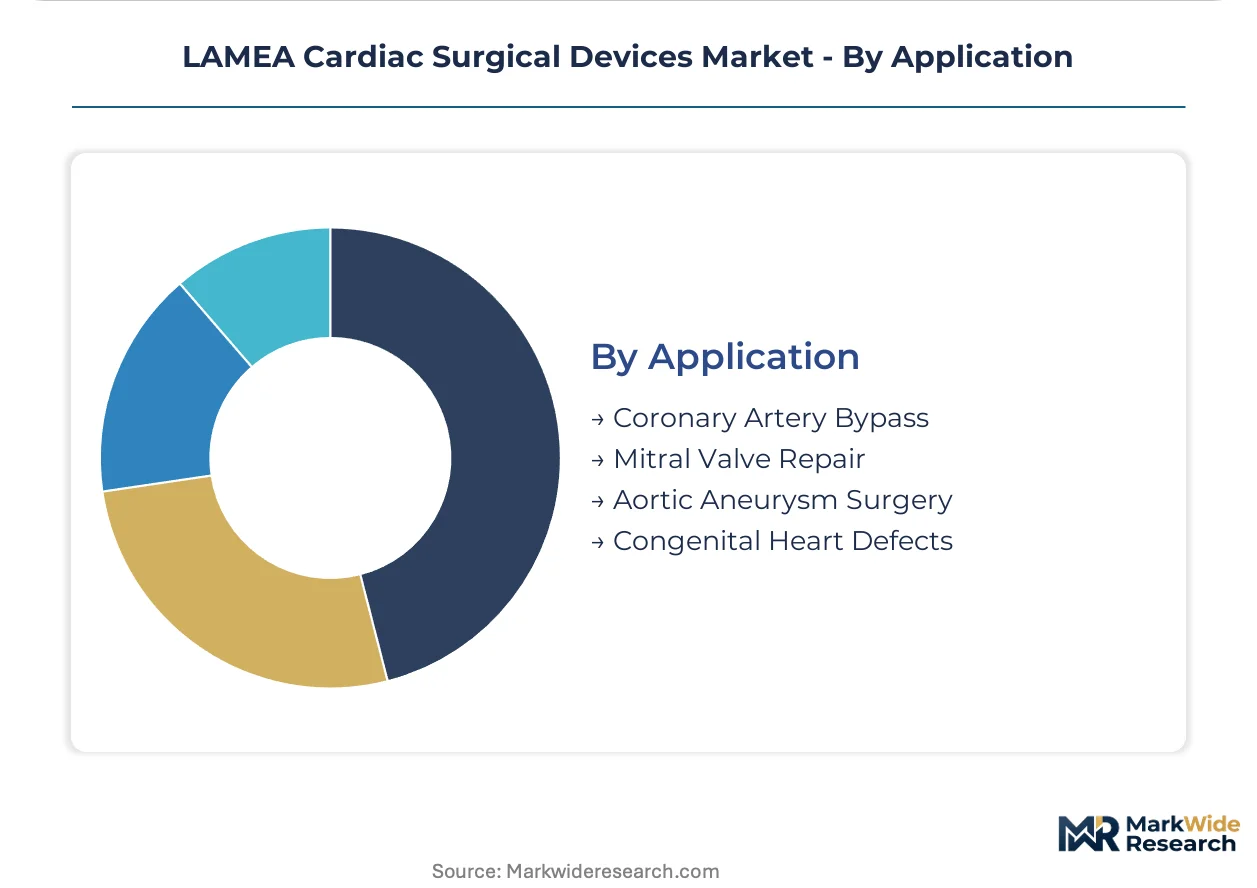
Application:
Procedure complexity and reimbursement rates determine equipment amortization timelines, with congenital cases requiring specialized pediatric perfusion circuits that extend payback periods.
- Coronary Artery Bypass:Saphenous vein and internal mammary artery grafting to restore myocardial perfusion dominates surgical volumes across Brazilian and South African referral networks.
- Mitral Valve Repair:Annuloplasty ring implantation and chordal reconstruction preserve native valve geometry, commanding premium pricing in private Saudi and Emirati facilities.
- Aortic Aneurysm Surgery:Bentall procedures and arch replacements require deep hypothermic circulatory arrest protocols, concentrating in Johannesburg and Cairo centers with specialized perfusion capabilities.
- Congenital Heart Defects:Pediatric septal defect closure and valve reconstruction depends on miniaturized circuits and specialized cannulae, with demand fragmented across academic centers in Cape Town and Nairobi.
Coronary artery bypass absorbs the majority of procedure volume; mitral valve repair is expanding most quickly as repair-versus-replace algorithms penetrate tier-one centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates cardiac surgical device demand across São Paulo, Riyadh, and Johannesburg metropolitan networks. Tier-one cardiac centers in these cities anchor complex valve and bypass procedure volumes. Regulatory divergence between ANVISA, SAHPRA, and SFDA shapes divergent market access timelines.
Brazil
São Paulo's metropolitan hospital networks drive bioprosthetic valve demand as aging cohorts enter secondary intervention windows. ANVISA enforces mandatory 25-30% domestic content requirements in SUS unified health system tenders. Rio de Janeiro cardiac centers expand perfusion program capacity to capture referral flows from underserved northern states.
Saudi Arabia
Riyadh and Jeddah academic medical centers prioritize robotic-assisted platforms for trainee exposure in mitral valve repair. SFDA accepts CE-marked documentation through abbreviated conformity pathways that truncate registration timelines. Eastern Province hospital consortia deploy hybrid operating suites for single-stage valve and coronary interventions.
South Africa
Johannesburg surgical centers expand cardiopulmonary bypass program capacity fastest in the region. SAHPRA enforces strict device registration requirements that reference WHO prequalification standards. Cape Town academic centers concentrate pediatric congenital defect procedures requiring miniaturized perfusion circuits.
United Arab Emirates
Dubai and Abu Dhabi tier-one hospitals host structured fellowship programs for transcatheter valve and robotic-assisted procedures. MOHAP aligns with Gulf Cooperation Council mutual recognition agreements that collapse duplicate technical documentation. Sharjah medical clusters attract cardiac surgery tourism from underpenetrated African markets.
Mexico
Mexico City ambulatory surgical centers concentrate same-day vascular closure and diagnostic catheterization volumes. Federal health procurement reforms consolidate purchasing authority among three to four dominant hospital groups. Monterrey cardiac centers expand minimally invasive training infrastructure to capture referral flows from Central American markets.
LAMEA Cardiac Surgical Devices Market Competitive Landscape
United States and European producers anchor the premium tier; Japanese and German specialists hold perfusion circuit and precision instrumentation positions. Market structure concentrates among five to seven diversified conglomerates with full cardiac surgery portfolios, while mid-scale regional distributors compete on service proximity. Strategic archetypes span integrated perfusion platform vendors, transcatheter valve technology specialists, and disposable instrumentation pure-plays. Dominant competitive moves include multi-year performance agreements replacing standalone capital purchases and remote proctoring networks expanding case volumes without physician relocation.
Within the diversified conglomerate tier, Medtronic PLC and Abbott Laboratories exemplify portfolio breadth strategies that anchor relationships with consolidated procurement groups. Edwards Lifesciences occupies a position representing tissue valve technology specialization that sustains premium positioning within constrained reimbursement environments. These three companies illustrate how vendor scale and service infrastructure concentration marginalize smaller distributors lacking technical training capabilities.
| Leading Market Players |
|---|
| Medtronic PLC |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Cardinal Health, Inc. |
| Edwards Lifesciences |
| LivaNova PLC |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Captive bovine pericardial tissue sourcing through Argentine and Brazilian abattoir partnerships anchors both bioprosthetic valve supply security and premium pricing power for manufacturers with integrated tissue processing capabilities. This backward integration insulates tier-one suppliers from foot-and-mouth disease quarantine volatility while sustaining margin pools that fragmented distributors cannot replicate.
Pricing Analysis
Volume concentrates in open-heart mechanical valves at compressed margins, while bioprosthetic tissue platforms command premium positioning through durability guarantees and replacement cycle economics. Three-tier pricing structure across premium CE-marked, standard reference-country approved, and economy WHO-prequalified levels stratifies procurement in Brazilian SUS tenders. Cost compression in public-sector segments intensifies because domestic content mandates inflate landed costs for imported precision instrumentation. Tier-one Saudi and Emirati private hospitals exhibit lowest price sensitivity, prioritizing technical service bundling over unit economics.
Supply Chain Analysis
Reverse-logistics networks for refurbished perfusion consoles and remanufactured oxygenators extend equipment lifecycles in underpenetrated African markets where capital constraints dominate procurement. Manufacturing concentration centers on Germany, Japan, and the United States for precision instrumentation, while bovine tissue sourcing draws from Argentine and Brazilian agricultural supply chains. Single-source vulnerability pervades heat exchanger membrane production, exposing distributors to extended lead time disruptions. Distribution runs through consolidated hospital procurement consortia in São Paulo, Riyadh, and Johannesburg that unbundle capital purchases from per-procedure service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA cardiac surgical devices market sits in a technology-transition phase where transcatheter valve platforms displace open-chest mechanical implants across eligible patient populations.
For Market Incumbents: Hedge substitution exposure by deepening service infrastructure in perfusion circuit maintenance and remote proctoring networks that lock in hospital relationships beyond device transactions. Anchor backward integration into bovine tissue processing to secure bioprosthetic supply chains against Argentine quarantine disruptions. Prioritize CE-marking investments that unlock abbreviated SFDA pathways before Gulf Cooperation Council harmonization matures. For New Entrants and Emerging Players: CE-mark recognition in Saudi Arabia opens a window for mid-scale European manufacturers to bypass lengthy ANVISA trials and establish beachheads in Riyadh and Jeddah academic medical centers. Target underpenetrated Nigerian and Kenyan cardiac surgery markets where surgical volumes remain below 150 procedures per million population versus Brazil's 800. Pursue WHO prequalification acceleration through South African reference-country approvals to unlock preferential African Medicines Agency tender access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified conglomerates seeking perfusion platform breadth or transcatheter valve technology gaps. Long-term viability hinges on service infrastructure density rather than standalone device IP, favoring targets with established technician training programs and multi-year hospital performance agreements. Monitor Gulf Cooperation Council mutual recognition agreement implementation velocity as inflection indicator for registration cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Abbreviated SFDA conformity recognition truncates Saudi registration timelines for European-cleared devices. |
| Hospital System Partnership | Multi-year performance agreements with São Paulo consolidated groups displace standalone capital purchases. |
| Software Companion Development | AI-augmented surgical planning platforms differentiate tier-one cardiac centers in Dubai and Riyadh. |
| Reimbursement Strategy | WHO prequalification unlocks preferential tender access across African Medicines Agency member states. |
| Remote Proctoring Network | Real-time surgical guidance expands case volumes in tier-two Saudi hospitals without physician relocation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that this study cross-referenced with primary interviews across perfusion program directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. ANVISA submission databases, SFDA clearance registries, SAHPRA approval records, and WHO prequalification lists supplied segmentation granularity. Bottom-up equipment installation tracking and top-down cardiac procedure volume estimates triangulated market sizing.
Data-stream reconciliation between manufacturer shipment records, hospital procurement databases, and national health statistics produced consistent volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology platform, application, end-user facility tier, and regional regulatory cluster dimensions. CAGRs derived from procedure volume growth curves, replacement cycle economics, and training program expansion rates. Transcatheter valve adoption trajectories and perfusionist workforce development timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted mitral valve repair would alter the outlook if training consortium capacity outpaces current projections. Forecasts reflect documented assumptions regarding Gulf Cooperation Council harmonization timing and African Medicines Agency operationalization. Practitioners should monitor CE-mark pathway expansion announcements and bovine tissue quarantine protocol changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Perfusion Systems Market