
 Point-Of-Care Cholesterol Monitoring Device Market | 2026-2036
Point-Of-Care Cholesterol Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Cholesterol Monitoring Device Market Outlook
Silicon is consolidating its role in electrochemical biosensor substrates, displacing legacy ceramic platforms in next-generation cholesterol test strips. Roche leverages vertical integration across reagent chemistry and handheld reader production to sustain margin capture. Abbott anchors its competitive stance through channel control in hospital emergency departments, while SD Biosensor specializes in cost-engineered strip architectures for pharmacy-dispensed systems.
Point-of-care cholesterol monitoring devices are portable diagnostic instruments that measure total cholesterol, HDL, LDL, and triglycerides from capillary blood samples using enzymatic reactions read by electrochemical or photometric sensors, delivering results within 60 to 180 seconds for immediate clinical decision-making. Handheld devices dominate volume shipments due to their compatibility with waived-test protocols in non-laboratory settings, while integrated systems command premium placement in hospital-based rapid-response workflows. Electrochemical technology leads installed base expansion because of its lower power requirements and miniaturization potential, whereas fluorescent detection methods occupy high-sensitivity niches in research applications.
FDA 510(k) pathways and Clinical Laboratory Improvement Amendments waivers govern device complexity classification and site-of-use permissions in the United States, while the EU Medical Device Regulation enforces post-market surveillance and notified body oversight for European market access. ISO 15197 standards for blood glucose monitoring have extended informally to cholesterol assay performance benchmarking, pressuring manufacturers to tighten coefficient-of-variation specifications. Stakeholders must monitor evolving reimbursement codes for preventive cardiovascular screening, as coverage determinations by Medicare and national health technology assessment bodies will decide whether home-care deployment accelerates or stalls.
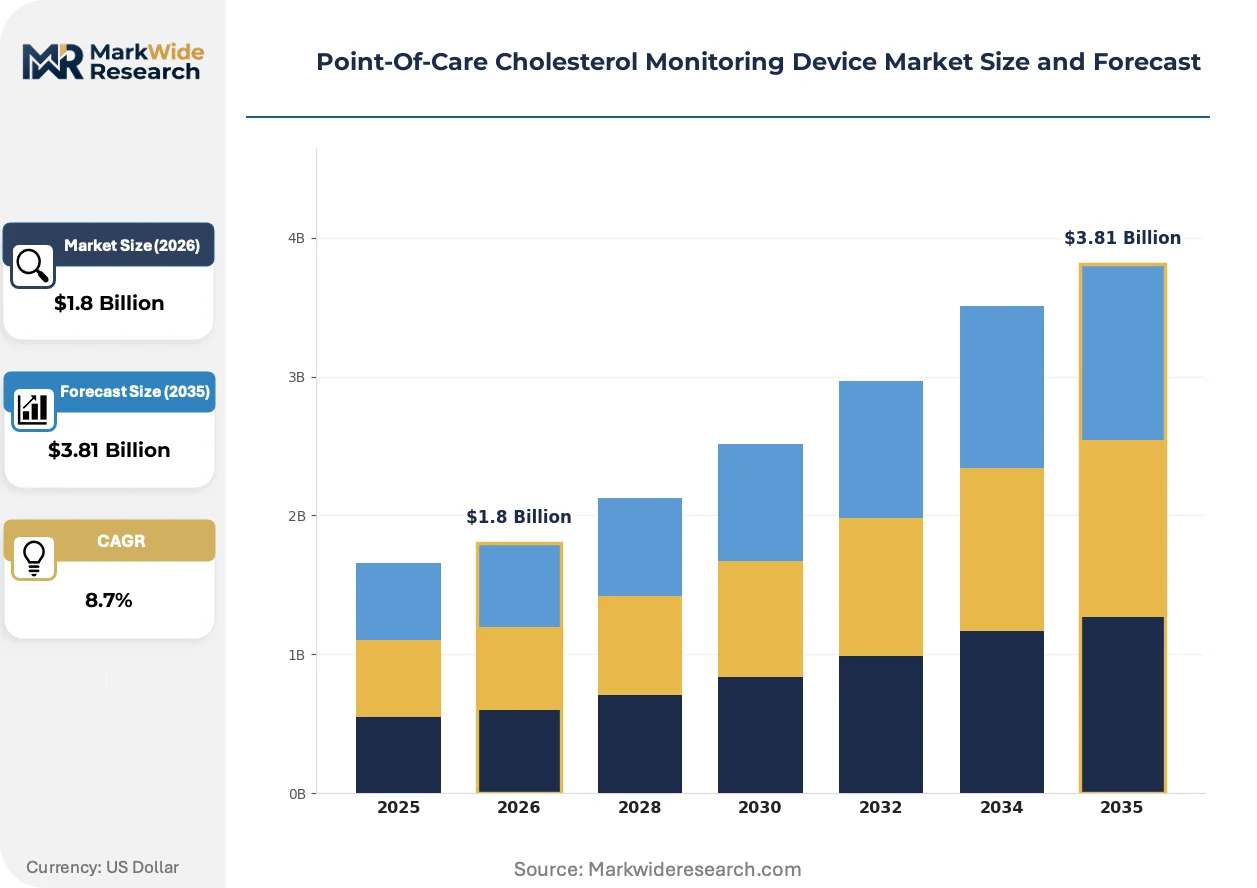
Market Dynamics
Silicon substrate migration is compressing manufacturing costs for electrochemical biosensors while FDA waived-test designations expand permissible site-of-use for cholesterol monitoring devices.
Growth Catalysts
- CLIA Waived-Test Expansion:FDA streamlined pathways for moderate-complexity device reclassification enable placement in primary care clinics and retail pharmacies without laboratory certification.
- Preventive Cardiovascular Screening Mandates:Germany's statutory health insurance system now reimburses rapid lipid panels performed outside hospital laboratories, accelerating clinic-based deployment.
- Enzymatic Assay Miniaturization:Solid-state electrochemistry reduces power requirements and reader footprint, enabling battery-operated handheld systems for home-care settings.
Market Restraints
- Precious Metal Input Volatility:Palladium and platinum price swings in electrochemical sensor electrodes compress strip manufacturing margins unpredictably.
- Single-Source Reagent Dependency:Proprietary enzyme formulations for HDL fractionation concentrate in Japanese and German chemical suppliers, creating supply vulnerability.
- Photometric Method Obsolescence:Legacy optical detection platforms face displacement by electrochemical alternatives, stranding installed base investments in hospital laboratories.
Strategic Opportunities
- Pharmacy Channel Penetration:United States retail chains seek in-store diagnostic services to drive prescription volume, creating demand for waived-complexity cholesterol systems.
- Telehealth Integration:Bluetooth-enabled readers transmitting encrypted results to electronic health records enable remote patient monitoring reimbursement under Medicare remote physiologic monitoring codes.
- Silicon Photonics Convergence:Integration of CMOS-compatible optical waveguides with microfluidic channels promises multi-analyte panels from single capillary samples.
Industry Challenges
- Biochemist Talent Scarcity:Formulation expertise for stable enzyme immobilization on polymer matrices concentrates in aging specialist cohorts with limited pipeline replacement.
- 510(k) Predicate Device Navigation:Manufacturers face extended FDA review cycles when seeking clearance for novel detection chemologies lacking established predicate comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Cholesterol Monitoring Device Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Integrated Systems, Test Strips, Analyzers Technology: Colorimetric, Electrochemical, Spectrophotometric, Fluorescent End User: Clinics, Pharmacies, Hospitals, Home Care Application: Routine Screening, Risk Assessment, Research, Patient Monitoring |
| Companies Covered | Sinocare, Abaxis, Roche, Bioptik, SD Biosensor, Abbott, DiaSys Diagnostic Systems, PTS Diagnostics, ACON Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Cholesterol Monitoring Device Market Strategic Shifts
Electrochemical sensor architectures are displacing legacy platforms while regulatory frameworks adapt to decentralized testing models and procurement patterns fragment across care settings.
Silicon-based electrochemical transducers with nanostructured platinum working electrodes are electrifying cholesterol detection sensitivity, enabling quantification from sub-10 microliter capillary samples. Emergency departments in tertiary hospitals are adopting these systems for rapid cardiac risk stratification of chest pain presentations. The technology is compressing time-to-result from minutes to seconds, eliminating laboratory queue bottlenecks during high-acuity periods.
EU Medical Device Regulation post-market surveillance requirements are forcing manufacturers to establish systematic vigilance systems for device failures and adverse events. Notified body oversight now extends to software updates and algorithm modifications in connected readers. European distributors are consolidating supplier relationships to manage enhanced technical documentation burdens and clinical evidence requirements.
Hospital procurement committees are unbundling device acquisition from reagent supply contracts, reversing historical captive-consumable models. Third-party logistics providers now manage just-in-time strip replenishment across multi-site health systems in the United States. This pattern is most visible in integrated delivery networks seeking operational flexibility without capital commitment to single-vendor ecosystems.
Point-Of-Care Cholesterol Monitoring Device Market Segmentation
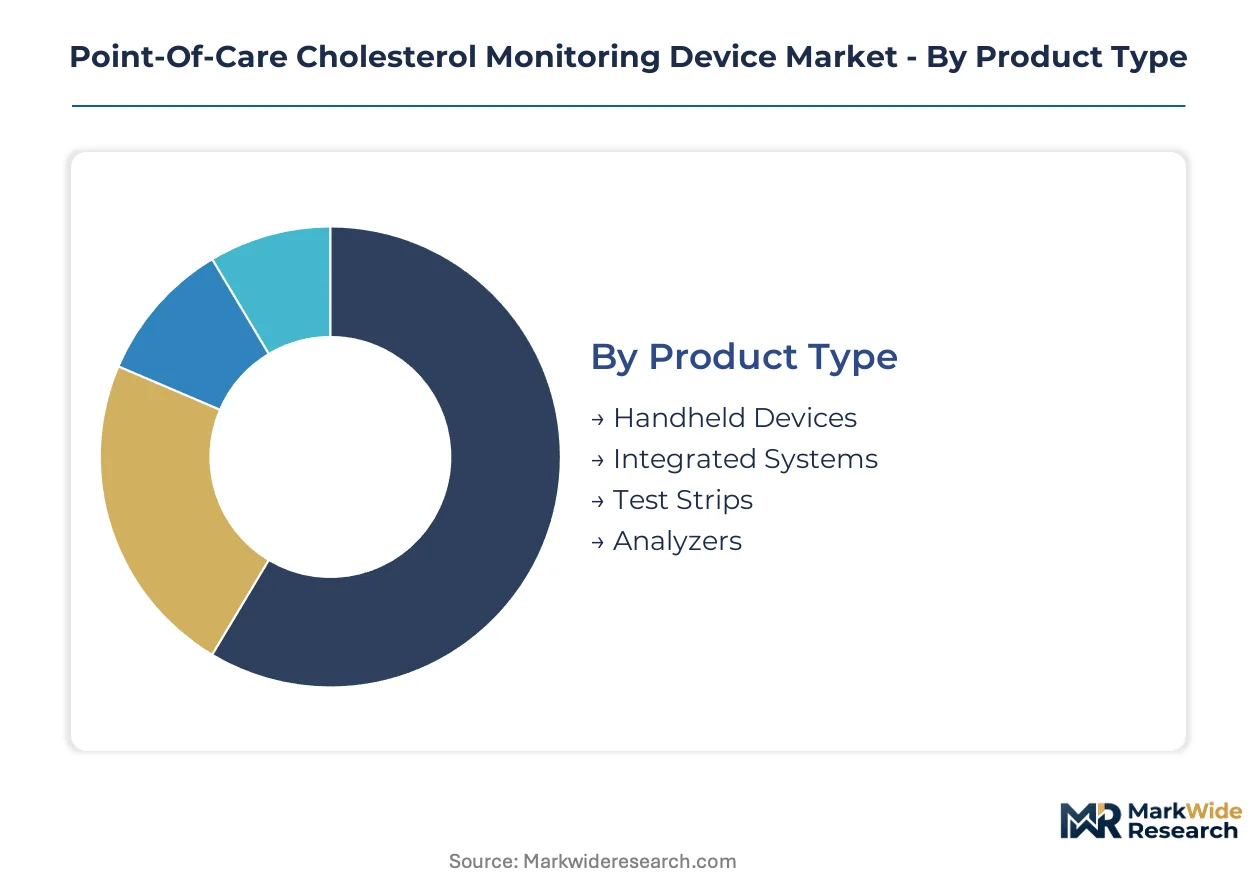
Point-of-care cholesterol monitoring devices fragment across four intersecting dimensions that determine reimbursement pathways, regulatory classification, and procurement economics. Product form factor and detection chemistry together dictate whether systems qualify for waived-test protocols or require laboratory oversight.
Product Type:
Handheld configurations dominate unit shipments while integrated systems capture premium placement in acute care settings.
- Handheld Devices:Battery-operated readers with single-use test strips enable CLIA-waived operation in retail pharmacies and primary care clinics without laboratory certification. Demand concentrates in United States pharmacy chains seeking in-store diagnostic services to drive prescription volume and patient loyalty programs.
- Integrated Systems:Multi-analyte platforms with automated sample handling and data connectivity command placement in hospital emergency departments and cardiac catheterization labs. Germany's statutory health insurance reimbursement for rapid lipid panels performed outside hospital laboratories is accelerating clinic-based deployment of compact integrated units.
- Test Strips:Disposable enzymatic reagent carriers with electrochemical transducers represent the recurring revenue engine for device ecosystems.
- Analyzers:Benchtop instruments with higher throughput capabilities serve reference laboratories and research institutions requiring batch processing.
Mature deployment sits with analyzers in centralized laboratories. Newer deployment is concentrated in handheld devices for decentralized screening programs.
Technology:
Cost tier separation runs from commodity colorimetric methods to precision fluorescent detection systems.
- Electrochemical:Solid-state biosensors with nanostructured platinum working electrodes reduce power requirements and reader footprint, enabling battery-operated handheld systems. United States emergency departments in tertiary hospitals are adopting these platforms for rapid cardiac risk stratification of chest pain presentations.
- Colorimetric:Enzymatic reaction visualization through reflectance photometry dominates low-cost pharmacy-dispensed systems in price-sensitive markets.
- Spectrophotometric:Optical density measurement at specific wavelengths retains installed base in legacy hospital laboratories facing displacement pressure from electrochemical alternatives.
- Fluorescent:High-sensitivity detection methods occupy research applications and specialized lipid fractionation assays requiring precise quantification of lipoprotein subfractions.
Volume leadership belongs to electrochemical platforms expanding through waived-test designations. Fluorescent systems retain niche premium positioning in academic medical centers.
End User:
Customer type determines regulatory burden and reimbursement code eligibility.
- Clinics:Primary care and cardiology practices drive adoption of waived-complexity devices for same-visit lipid management and statin therapy monitoring.
- Pharmacies:United States retail chains including CVS and Walgreens are deploying point-of-care cholesterol systems to create clinical service revenue streams and improve medication adherence.
- Hospitals:Emergency departments and rapid response teams require integrated systems with electronic health record connectivity for acute cardiac care protocols.
- Home Care:Bluetooth-enabled readers transmitting encrypted results to electronic health records enable remote patient monitoring reimbursement under Medicare remote physiologic monitoring codes.
Procurement concentration sits with hospitals through capital equipment budgets. Fastest expansion is occurring in pharmacies leveraging existing foot traffic for diagnostic service conversion.
Application:
Use case maturity separates preventive screening from emerging connected monitoring models.
- Routine Screening:Population-level cardiovascular risk assessment programs in Germany and China are scaling deployment of portable lipid panels in community health settings.
- Risk Assessment:Acute chest pain protocols in United States emergency departments require rapid total cholesterol and HDL quantification for immediate treatment decisions.
- Research:Academic medical centers and pharmaceutical trials employ high-precision fluorescent systems for lipoprotein subfraction analysis and drug efficacy endpoints.
- Patient Monitoring:Telehealth-integrated home monitoring enables longitudinal lipid tracking for familial hypercholesterolemia patients and post-myocardial infarction management.
Established utilization centers on routine screening for preventive cardiovascular programs. Patient monitoring represents the fastest-climbing application as remote care models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate electrochemical biosensor manufacturing for export markets. Germany's medical technology clusters anchor European device assembly. India's pharmaceutical special economic zones attract strip reagent formulation operations.
United States
CVS and Walgreens deploy waived-complexity cholesterol systems across 9,000 retail locations to convert foot traffic into clinical services. FDA 510(k) pathways and CLIA waiver designations determine site-of-use permissions for pharmacy-based screening. The Minneapolis medical device corridor houses precision electrochemical reader engineering operations serving hospital emergency departments.
Germany
Statutory health insurance reimbursement for rapid lipid panels performed outside hospital laboratories accelerates clinic-based device deployment. EU Medical Device Regulation post-market surveillance requirements enforce systematic vigilance for device failures across the single market. The Baden-Württemberg precision engineering cluster produces miniaturized enzymatic assay components for handheld systems.
China
Community health centers in tier-2 cities scale preventive cardiovascular screening programs using cost-engineered point-of-care lipid panels. NMPA clearance pathways for Class II medical devices govern domestic market access for electrochemical biosensors. The Suzhou biomedical industrial park hosts contract manufacturers producing test strip substrates for export to Southeast Asian markets.
Japan
Aging demographics and familial hypercholesterolemia prevalence drive home-care monitoring demand for Bluetooth-enabled readers. PMDA regulatory frameworks classify cholesterol monitoring devices based on software connectivity and algorithm complexity. The Kobe medical device cluster specializes in stable enzyme immobilization chemistry for premium test strip formulations.
India
Primary health centers under the National Health Mission integrate portable lipid panels into non-communicable disease screening protocols. CDSCO medical device rules govern import licensing and local manufacturing incentives for diagnostic instruments. The Hyderabad pharmaceutical corridor attracts reagent formulation operations seeking cost advantages in enzyme chemistry production.
Point-Of-Care Cholesterol Monitoring Device Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational diagnostics conglomerates commanding hospital procurement channels while regional fabricators supply pharmacy-dispensed systems. The vendor base organizes into three tiers: integrated life science conglomerates with captive reagent chemistry, mid-scale device specialists focusing on reader hardware, and contract manufacturers producing strip substrates under private label. Consolidation pressure intensifies as procurement committees unbundle device acquisition from consumable supply contracts. Strategic moves center on backward integration into enzyme formulation and geographic licensing partnerships for waived-test protocol expansion.
Among integrated life science conglomerates, Roche and Abbott exemplify archetypes of vertical control spanning reagent chemistry through handheld reader production. SD Biosensor occupies a position within the Asia-Pacific cost-engineering tier, representing specialists in high-volume strip manufacturing for price-sensitive pharmacy channels. DiaSys Diagnostic Systems anchors the European mid-scale segment, exemplifying regional players competing through notified body relationships and EU MDR compliance infrastructure.
| Leading Market Players |
|---|
| Sinocare |
| Abaxis |
| Roche |
| Bioptik |
| SD Biosensor |
| Abbott |
| DiaSys Diagnostic Systems |
| PTS Diagnostics |
| ACON Laboratories |
| Others |
Value Chain & Pricing Dynamics
Palladium electrode costs cascade through three pricing tiers for electrochemical cholesterol test strips, with Japanese and German enzyme suppliers commanding premium placement while Chinese substrate fabricators anchor economy-tier pharmacy-dispensed systems. Spot palladium price volatility on the London Metal Exchange compresses strip manufacturing margins unpredictably, forcing procurement committees toward multi-year reagent supply contracts with embedded price adjustment clauses.
Pricing Analysis
Short lead-time premiums apply to CLIA-waived handheld readers for emergency department deployment, while spot inventory discounts concentrate in pharmacy-channel test strips sold through third-party logistics aggregators. The dominant structure is tiered pricing separating premium integrated systems from standard handheld devices and economy single-use strips. Price differentiation rests on FDA 510(k) clearance tier and ISO 15197 performance certification rather than brand premium alone. Pricing pressure stems from hospital procurement committees unbundling device acquisition from captive consumable contracts. Pharmacy chains exhibit highest price sensitivity due to thin diagnostic service margins, while tertiary hospital emergency departments prioritize time-to-result over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement committees mandate qualified suppliers for both platinum-group metal electrodes and proprietary HDL fractionation enzymes, preventing single-source lock-in with Japanese or German chemical houses. Manufacturing concentrates in China for electrochemical biosensor substrates, Germany for precision enzymatic assay components, and the United States for handheld reader assembly. Raw material dependencies center on palladium and platinum for working electrodes, proprietary enzyme formulations for lipoprotein separation, and silicon wafers for solid-state transducers. Single-source vulnerability in specialty enzyme chemistry creates supply risk during geopolitical trade disruptions. Distribution runs through third-party logistics providers managing just-in-time strip replenishment across multi-site health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point-of-care cholesterol monitoring device market is consolidating around backward integration into enzyme formulation chemistry, with players racing to secure captive supply of stable immobilization expertise as aging biochemist cohorts retire without pipeline replacement.
For Market Incumbents: Deploy channel control levers to lock in hospital emergency department placement before procurement committees complete unbundling of device and reagent contracts. Consolidate defensive positions through exclusive GPO agreements with integrated delivery networks and accelerated FDA 510(k) submissions for next-generation silicon photonics platforms. Electrochemical detection sensitivity improvements from nanostructured platinum electrodes threaten to obsolete legacy fluorescent installed bases, requiring rapid reader refresh cycles to prevent displacement. For New Entrants and Emerging Players: Begin with pharmacy-dispensed waived-complexity systems in United States retail chains seeking in-store diagnostic service revenue, where regulatory barriers are lowest and volume scale is highest. White-space concentration sits in Bluetooth-enabled home monitoring devices eligible for Medicare remote physiologic monitoring reimbursement codes. Telehealth integration partnerships with electronic health record vendors offer the most penetrable go-to-market angle against entrenched hospital channel incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European device specialists with established EU MDR notified body relationships and existing CLIA-waived product portfolios, particularly those concentrated in Germany's Baden-Württemberg precision engineering cluster. Long-term viability over the next decade hinges on backward integration into enzyme formulation chemistry rather than hardware assembly scale. Watch for FDA moderate-complexity reclassification announcements as the signal indicating accelerated site-of-use expansion and corresponding valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Expansion | FDA streamlined reclassification enables pharmacy placement without laboratory certification infrastructure. |
| Enzyme Formulation Backward Integration | Captive supply of HDL fractionation chemistry reduces dependency on Japanese and German specialty suppliers. |
| Bluetooth-Enabled Reader Development | Medicare remote physiologic monitoring codes unlock reimbursement for telehealth-integrated home monitoring. |
| Silicon Photonics Convergence R&D | CMOS-compatible optical waveguides enable multi-analyte panels from single capillary samples. |
| Third-Party Logistics Partnership | Just-in-time strip replenishment contracts secure operational flexibility for unbundled procurement committees. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital GPO contract awards, complemented by interviews with point-of-care device product managers, CLIA compliance officers at retail pharmacy chains, biomedical engineers in tertiary hospital emergency departments, and enzyme formulation chemists at specialty reagent suppliers. Secondary validation drew from SEC filings of listed diagnostics conglomerates, CMS Medicare reimbursement code determinations, and ISO 15197 performance benchmarking studies. Bottom-up test strip volume estimates and top-down device revenue figures were triangulated against import-export trade data for electrochemical biosensor substrates.
Segment-level projections across product type, detection technology, end-user setting, and geographic market were generated through regression analysis of historical placement data and regulatory approval timelines. CAGRs were derived from installed base expansion rates in waived-test sites and replacement cycles for legacy photometric platforms. Industry-specific forecast inputs included palladium price volatility indices, CLIA waiver approval velocity, and statutory health insurance reimbursement expansion trajectories in Germany and China.
Palladium supply disruptions, FDA predicate device navigation delays, and biochemist talent scarcity are the dominant revision risks to the projection framework. Deviation in enzyme formulation supplier consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Cannulas Market