
 Remote Endarterectomy Devices Market | 2026-2036
Remote Endarterectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Endarterectomy Devices Market Analytics
Aftermarket service revenue is rewriting how vascular device manufacturers capture lifetime value from remote endarterectomy installations. Medtronic plc leverages its broad catheter portfolio to sustain recurring instrument sales across hospital networks. Boston Scientific Corporation anchors its position through specialized training programs that lock in physician preference. LeMaitre Vascular competes by dominating niche mechanical guide segments where larger rivals underinvest.
Remote endarterectomy devices are precision instruments designed to remove atherosclerotic plaque from arterial walls through minimally invasive access, typically employing catheter-based systems with working diameters under 10 French to navigate tortuous vasculature. These tools restore luminal patency in peripheral and carotid territories while avoiding open surgical exposure, reducing procedural morbidity for high-risk surgical candidates. Catheter systems command the largest installed base among product types, though balloon-assisted platforms show the fastest upgrade cycle as centers replace first-generation equipment. Mechanical technology retains the dominant share of procedures performed, while radiofrequency-enhanced systems capture premium pricing in complex calcified lesions where standard tools fail.
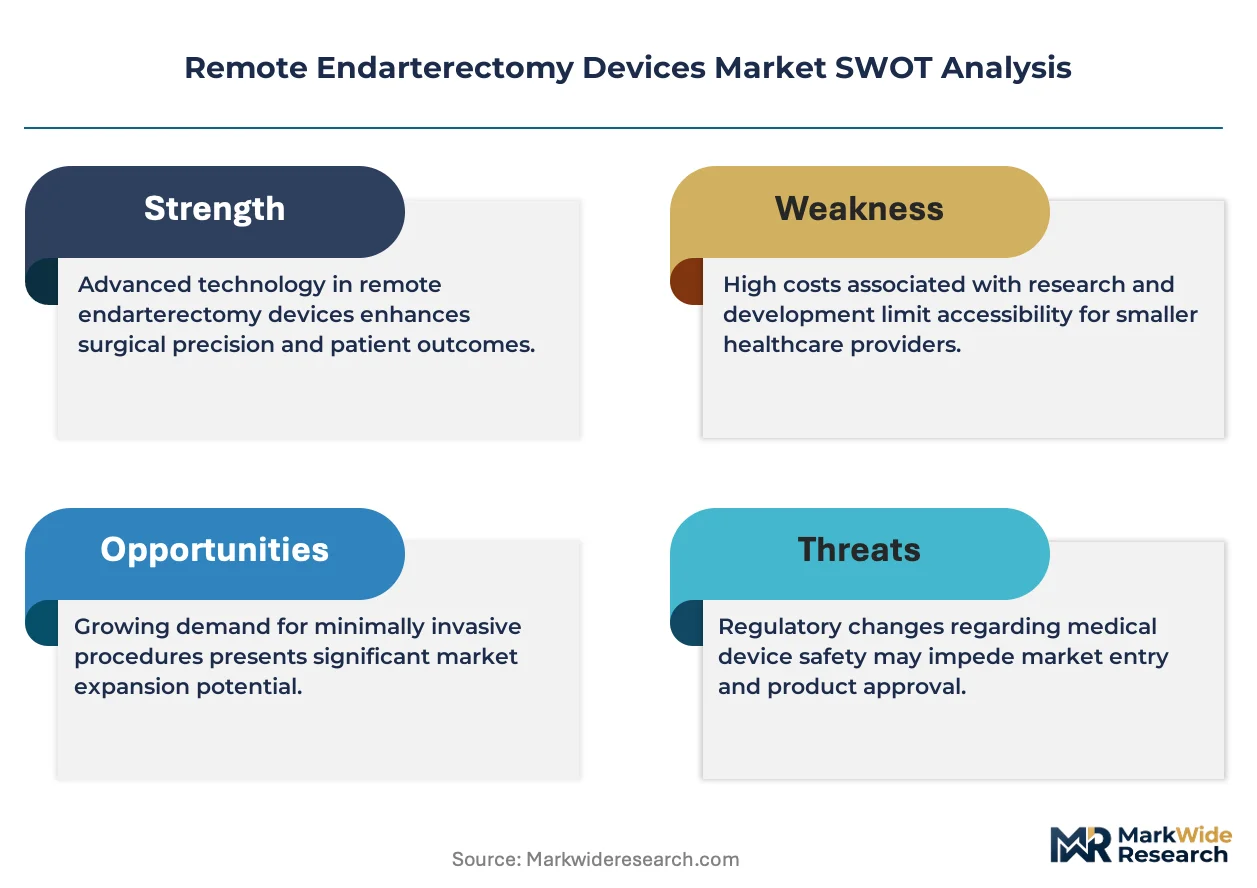
FDA premarket notification requirements and EU MDR technical documentation mandates shape device development timelines and commercialization costs for manufacturers seeking dual-territory approval. Japan's PMDA enforces distinct clinical evidence standards that delay market entry but reward compliant firms with sustained competitive insulation. Stakeholders must monitor reimbursement decisions by Medicare and Germany's G-BA, as these determinations directly dictate hospital capital allocation toward remote endarterectomy programs versus alternative revascularization modalities.
Market Dynamics
Catheter-based plaque excision technology is compressing procedural timelines and forcing hospitals to consolidate vendor relationships around integrated platform suppliers rather than discrete instrument sourcing.
Growth Catalysts
- EU MDR technical documentation mandates:Manufacturers investing early in clinical evidence packages gain accelerated market access across notified body jurisdictions, creating first-mover insulation in dual-territory approvals.
- Japan's aging surgical population:PMDA's emphasis on high-risk patient data rewards firms with robust Japanese clinical programs, concentrating demand among compliant device portfolios.
- Radiofrequency-enhanced catheter systems:Complex calcified lesion capability expands addressable procedures beyond standard mechanical tools, capturing premium reimbursement tiers in hospital outpatient departments.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster through limited specialty metal processors, exposing device manufacturers to input cost volatility and allocation risk.
- FDA 510(k) predicate device requirements:Novel mechanism-of-action submissions face elongated review cycles when substantial equivalence pathways narrow, delaying commercialization timelines for next-generation platforms.
- Drug-coated balloon substitution:Endovascular specialists in select centers pivot toward pharmacological intervention for moderate lesions, compressing mechanical atherectomy case volumes in specific anatomical territories.
Strategic Opportunities
- Germany's G-BA innovation funding:Reimbursement pilot programs for minimally invasive vascular procedures create capital allocation tailwinds for centers investing in remote endarterectomy training infrastructure.
- Artificial intelligence-guided catheter navigation:Convergence of machine learning with real-time intravascular imaging enables autonomous lesion characterization, opening procedural access to lower-volume interventionists.
- Direct-to-hospital service contracts:Bypassing traditional distributor networks through manufacturer-employed clinical specialists captures margin compression from intermediaries while deepening account penetration.
Industry Challenges
- Interventional radiology fellowship pipeline:Declining specialized training program enrollment constrains operator availability, limiting procedural expansion even where device access and reimbursement align.
- ISO 13485:2016 transition audits:Quality management system recertification demands divert engineering resources from product development cycles, compressing innovation throughput during compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Endarterectomy Devices Market |
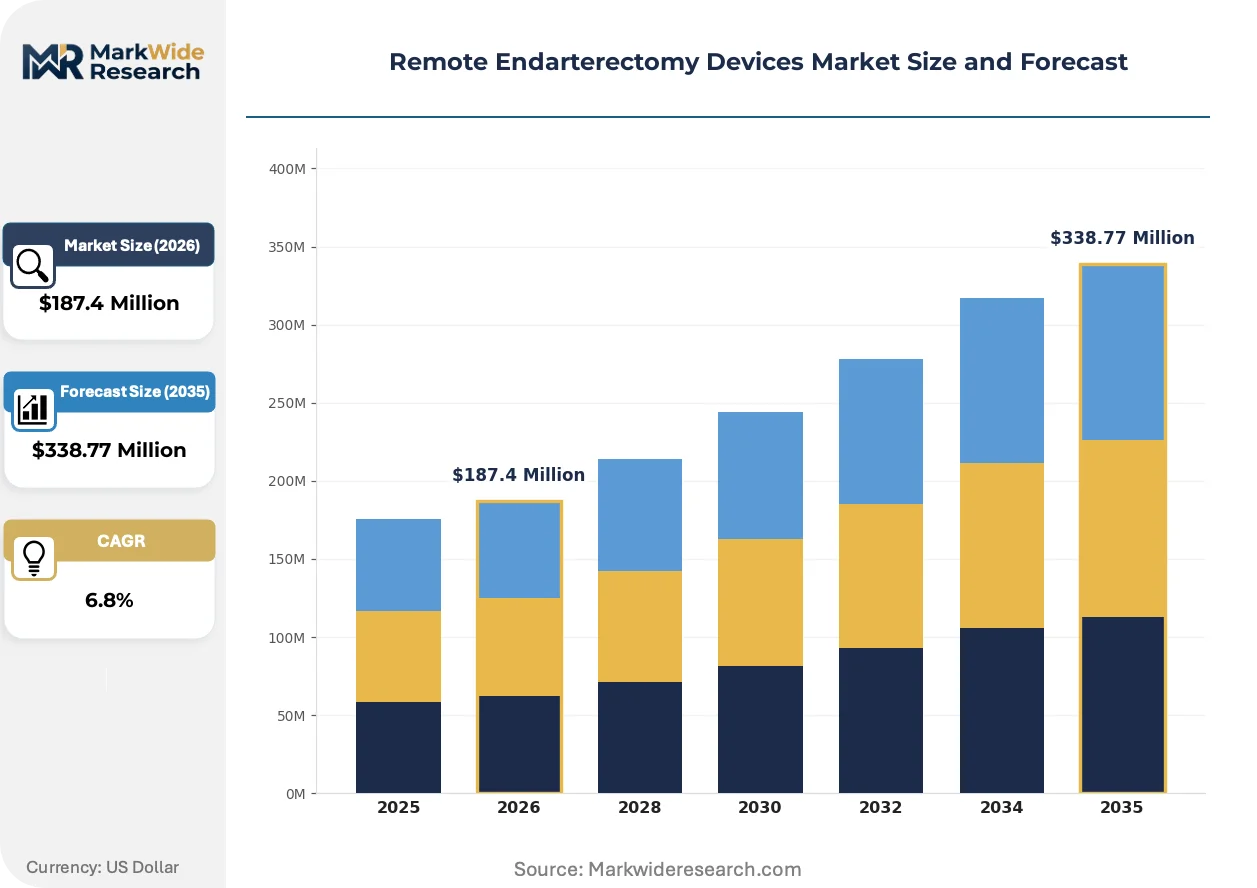
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Guides, Balloon Systems, Sheaths Technology: Laser, Mechanical, Radiofrequency, Ultrasound End User: Hospitals, Outpatient Centers, Specialty Clinics, Surgical Centers Application: Carotid Artery, Peripheral Artery, Coronary Artery, Other |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Scanlan International, LeMaitre Vascular, Cardiovascular Systems, Inc. (CSI), Terumo Corporation, Getinge AB, Abbott Laboratories, Philips Image-Guided Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Endarterectomy Devices Market Evolving Landscape
Real-time imaging integration and autonomous navigation algorithms are compressing the skill gap between specialist and generalist operators, reshaping how hospitals deploy vascular intervention programs.
Intravascular ultrasound-guided catheter systems is digitizing plaque characterization workflows. Community hospitals without dedicated vascular imaging specialists are adopting these platforms at accelerated procurement cycles. The technology is digitizing pre-procedural planning and reducing fluoroscopy exposure, compressing training requirements for new operator onboarding.
Japan's PMDA post-market surveillance expansion now mandates longitudinal patient outcome tracking for all newly approved peripheral vascular devices. Manufacturers must maintain dedicated Japanese clinical affairs teams to manage adverse event reporting. Catheter-based atherectomy systems face heightened scrutiny relative to balloon platforms, favoring firms with established local regulatory infrastructure.
After-sales service unbundling from capital equipment contracts is disrupting traditional distributor relationships. Hospital procurement committees now negotiate preventive maintenance and training separately from device acquisition. This pattern concentrates in United States integrated delivery networks where centralized supply chain offices standardize vendor management across multiple facilities.
Remote Endarterectomy Devices Market Segmentation
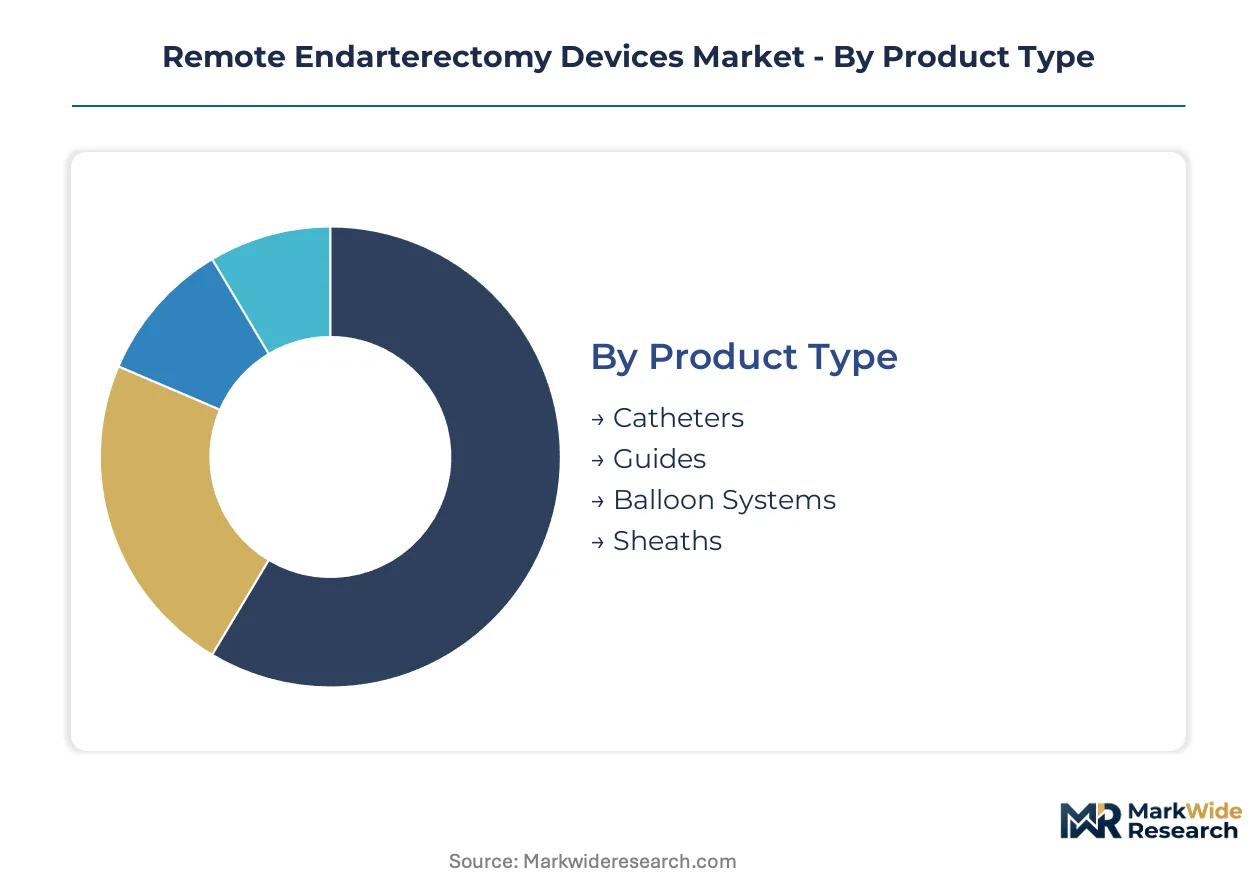
Device segmentation in remote endarterectomy markets determines procurement patterns across hospital networks. Product architecture and energy modality choices directly influence reimbursement tiers and operator training requirements.
Product Type:
Cost tier differentiation separates capital-intensive platform systems from disposable instrument revenue streams.
- Catheters:Working diameters under 10 French navigate tortuous vasculature through integrated cutting or ablation tips. United States hospital networks concentrate demand here as catheter-based platforms anchor integrated vendor contracts and lock in recurring instrument sales.
- Guides:Mechanical guide systems deliver steerable support for plaque excision tools through proprietary rail designs. Germany's G-BA reimbursement pilots favor guide-compatible platforms that reduce fluoroscopy time and procedure duration in outpatient settings.
- Balloon Systems:Balloon-assisted platforms enable controlled vessel occlusion during plaque removal.
- Sheaths:Access sheaths provide hemostatic entry ports for multi-instrument exchange.
Catheter systems command the established base. The steepest expansion runs through balloon-assisted platforms.
Technology:
Application severity dictates energy modality selection across lesion complexity spectra.
- Mechanical:Rotational or orbital cutting heads physically debulk atherosclerotic plaque through catheter-delivered abrasion. Japan's PMDA post-market surveillance requirements impose heavier documentation burdens on mechanical systems relative to energy-based alternatives.
- Radiofrequency:Thermal ablation systems vaporize calcified deposits through controlled RF energy delivery. United States hospital outpatient departments capture premium reimbursement tiers for complex calcified lesions where mechanical tools fail.
- Laser:Excimer laser platforms photablate plaque through ultraviolet pulsed energy.
- Ultrasound:Ultrasonic cavitation systems emulsify thrombotic and fibrotic material.
Mechanical technology retains the dominant procedure volume. Radiofrequency-enhanced systems are gaining share fastest in calcified lesion indications.
End User:
Customer type stratification reflects capital intensity tolerance and procedure volume thresholds.
- Hospitals:Academic medical centers and community hospitals host the bulk of installed base through integrated catheterization laboratory infrastructure. Medicare reimbursement decisions directly dictate capital allocation toward remote endarterectomy programs versus competing revascularization modalities.
- Outpatient Centers:Ambulatory surgical centers pursue faster procedural throughput with lower fixed-cost platforms. Germany's aging surgical population expands addressable patient pools for minimally invasive same-day discharge protocols.
- Specialty Clinics:Dedicated vascular intervention clinics concentrate high-volume operators.
- Surgical Centers:Multi-specialty surgical facilities integrate vascular programs alongside orthopedics and general surgery.
Hospitals command the established base. Outpatient centers represent the fastest volume expansion trajectory.
Application:
Anatomical territory determines device specification requirements and regulatory pathway complexity.
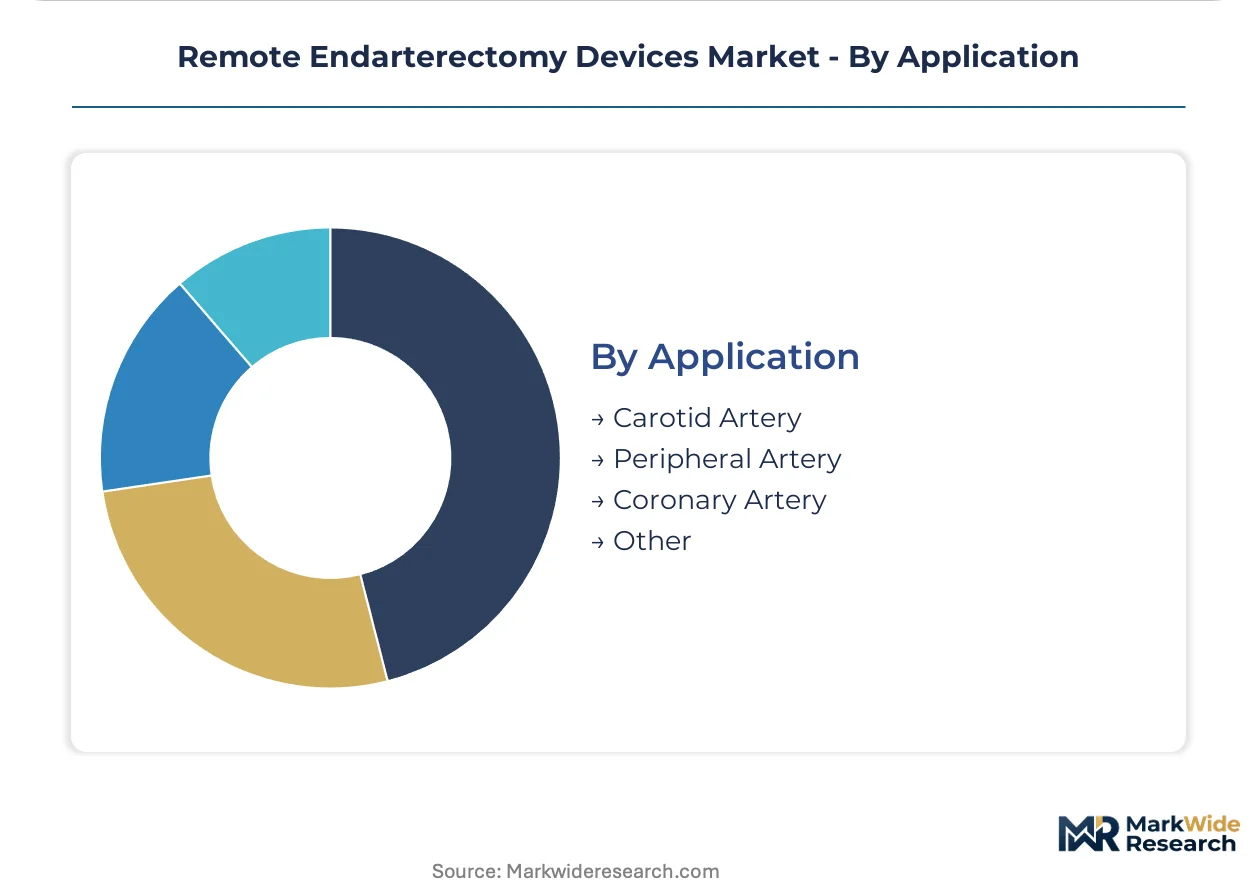
- Peripheral Artery:Femoropopliteal and infrapopliteal interventions demand flexible catheter designs for lengthy tortuous segments. United States demand concentrates here as peripheral artery disease prevalence expands with diabetic and aging demographics.
- Carotid Artery:Cervical carotid procedures require embolic protection integration and precise plaque control near cerebral circulation. Japan's PMDA enforces distinct clinical evidence standards for neurovascular proximity devices that delay market entry but reward compliant firms.
- Coronary Artery:Cardiac applications face heightened safety benchmarks from FDA and EU MDR requirements.
- Other:Renal, mesenteric, and subclavian territories represent niche indications.
Peripheral artery applications command the established base. Carotid interventions are climbing the fastest as embolic protection technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospitals prioritize catheter-based platforms for integrated lab workflows. German outpatient centers favor guide-compatible systems for same-day discharge protocols. Japanese regulators impose distinct clinical evidence burdens that reshape competitive entry.
United States
Medicare reimbursement decisions and aging diabetic demographics drive hospital capital allocation toward peripheral artery interventions. FDA 510(k) predicate requirements elongate review cycles for novel mechanism-of-action submissions. Minnesota and Massachusetts host concentrated medical device clusters where catheter system innovation accelerates through integrated lab partnerships.
Germany
G-BA innovation funding for minimally invasive vascular procedures creates procurement tailwinds for remote endarterectomy training infrastructure. EU MDR technical documentation mandates favor early clinical evidence investors across notified body jurisdictions. Baden-Württemberg's precision engineering corridor supplies critical Nitinol processing capabilities for superelastic alloy components.
Japan
PMDA post-market surveillance expansion mandates longitudinal outcome tracking for peripheral vascular devices, concentrating demand among compliant portfolios. Aging surgical populations expand addressable patient pools for high-risk intervention candidates. Tokyo-Osaka medical device corridors sustain dedicated clinical affairs teams managing adverse event reporting workflows.
United Kingdom
NHS integrated care systems standardize vendor contracts across catheterization laboratory networks, favoring platform suppliers with training infrastructure. MHRA convergence with EU MDR technical standards streamlines dual-territory approval pathways for prepared manufacturers. London-Southeast academic medical centers anchor adoption of intravascular ultrasound-guided navigation systems.
China
NMPA clinical trial requirements for Class III vascular devices extend registration timelines but reward persistent entrants with protected market windows. Provincial healthcare procurement centralization in Jiangsu and Guangdong consolidates demand around domestic-foreign joint venture platforms. Yangtze River Delta manufacturing clusters scale catheter production for cost-competitive export positioning.
Remote Endarterectomy Devices Market Competitive Landscape
Capability concentration sits with specialized vascular technology developers; scale advantage sits with diversified medical device conglomerates. The competitive terrain organizes around three archetypes: integrated catheter platform suppliers, mechanical guide specialists, and imaging-navigation convergent players. M&A activity targets complementary catheter portfolios while strategic partnerships lock in hospital training commitments. Geographic expansion through direct-to-hospital service contracts bypasses traditional distributor networks.
Among diversified medical technology conglomerates, Medtronic plc and Boston Scientific Corporation occupy positions anchoring integrated platform supply across United States hospital networks. LeMaitre Vascular exemplifies the specialized mechanical guide archetype where focused R&D investment outcompetes broader portfolio rivals in niche segments. Terumo Corporation represents the Asia-Pacific headquartered tier leveraging PMDA compliance infrastructure for sustained Japanese market insulation.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Scanlan International |
| LeMaitre Vascular |
| Cardiovascular Systems, Inc. (CSI) |
| Terumo Corporation |
| Getinge AB |
| Abbott Laboratories |
| Philips Image-Guided Therapy |
| Others |
Value Network & Pricing Analysis
Nitinol superelastic alloy processors in Baden-Württemberg, Germany, concentrate critical raw material supply for catheter-based systems, anchoring margin pools in downstream device assembly and recurring instrument sales rather than commodity metal supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between hospital networks and integrated platform suppliers, locking in predictable disposable instrument revenue streams across multi-year agreements. Price differentiation hinges on FDA 510(k) clearance tier and bundled after-sales service depth, with academic medical centers showing lowest sensitivity due to reimbursement pass-through mechanics while ambulatory surgical centers face acute cost compression. Pricing pressure stems from drug-coated balloon substitution in moderate lesion segments, forcing mechanical atherectomy vendors toward value-based contracting.
Supply Chain Analysis
Export control regimes limiting advanced catheter navigation technology flows shape strategic sourcing decisions for precision vascular instruments. Component manufacturing clusters in Germany, Japan, and the United States feed finished device assembly, with superelastic Nitinol alloys, RF generator modules, and intravascular ultrasound transducers anchoring bill-of-materials costs. Single-source vulnerability concentrates in specialty metal processing for torque-transmitting shafts. Distribution runs through manufacturer-employed clinical specialists bypassing traditional distributor networks in United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote endarterectomy markets are crossing a platform-economics threshold where catheter-navigation software interoperability determines hospital vendor consolidation patterns.
For Market Incumbents: Pre-empt drug-coated balloon encroachment by embedding AI-guided lesion characterization into platform ecosystems, locking physician workflow dependency. Deepen backward integration into Nitinol processing through captive supply agreements with Baden-Württemberg metalwork specialists, insulating margin pressure from raw material allocation risk. Accelerate EU MDR technical documentation investments to compress dual-territory approval timelines before predicate device pathways narrow further. For New Entrants and Emerging Players: Establish a beachhead in mechanical guide segments where LeMaitre Vascular's focused dominance reveals executable white-space beneath integrated platform radar. Target Japan's PMDA-compliant clinical infrastructure gap—foreign firms with dedicated Tokyo-Osaka regulatory affairs teams capture sustained competitive insulation. Deploy direct-to-hospital service contracts as primary go-to-market mechanism, capturing margin compression from distributor intermediaries while building account-level training lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward imaging-navigation convergent players with FDA-cleared AI catheter guidance modules and established hospital pilot programs. Long-term viability across the analysis window favors firms controlling proprietary intravascular ultrasound integration rather than discrete mechanical tool manufacturers facing software-defined obsolescence. Watch Medicare reimbursement decisions for peripheral artery interventions as primary inflection signal—hospital capital allocation shifts toward remote endarterectomy programs versus competing revascularization modalities would accelerate platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines capture predicate device pathways before regulatory narrowing. |
| CE Marking Pathway | EU MDR technical documentation investments unlock dual-territory commercialization across notified body jurisdictions. |
| Hospital System Partnership | Integrated delivery network contracts concentrate procurement around single-vendor catheter platforms. |
| Software Companion Development | AI-guided navigation modules differentiate hardware platforms and compress operator training requirements. |
| Reimbursement Strategy | G-BA innovation funding alignment in Germany directs capital toward outpatient training infrastructure. |
Research Methodology
Operator-level perspectives from interventional cardiologists, vascular surgeons, hospital purchasing committee chairs, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and Japanese PMDA approval records. Bottom-up installed base modeling and top-down procedure volume estimates triangulated market sizing across technology and application segments.
Scenario-bracketing around regulatory approval timelines and reimbursement decision outcomes structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, energy modality, end-user facility type, and anatomical application territory. CAGRs derived from procedure volume elasticity to aging demographic expansion and technology substitution dynamics. Forecast inputs incorporated PMDA post-market surveillance burden trajectories and G-BA pilot program expansion patterns.
Sensitivities concentrate around FDA predicate device pathway availability, EU MDR notified body capacity constraints, and Medicare reimbursement tier adjustments for peripheral artery interventions. Forecasts reflect assumptions regarding operator training pipeline recovery and nitinol raw material supply stability. Material shifts in drug-coated balloon efficacy data or Japan's PMDA clinical evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market