
 Peripheral Vascular Interventions Market | 2026-2036
Peripheral Vascular Interventions Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Vascular Interventions Market Intelligence
A shift toward outpatient settings, particularly Ambulatory Surgical Centers, is reorganizing purchasing patterns away from traditional large hospital systems. Medtronic leverages its extensive portfolio to serve both hospital and outpatient channels effectively. Boston Scientific Corporation competes through its focus on minimally invasive device innovation for complex lesions. Cook Medical sustains its market position with a specialized range of guidewires and catheters essential for interventional procedures.
Peripheral vascular interventions encompass catheter-based procedures designed to treat occlusive disease in arteries and veins outside the heart and brain. These interventions often use devices made from materials like nitinol or cobalt-chromium and are performed under fluoroscopic guidance. Stents, especially drug-eluting versions, and balloon catheters represent the largest product segments. Within therapy areas, treatments for Peripheral Artery Disease (PAD) constitute the primary application volume, driven by an aging demographic and associated comorbidities.
Device approval pathways set by the US FDA, Europe's EMA under the Medical Device Regulation (MDR), and Japan's PMDA dictate market entry timelines and costs. These regulatory bodies enforce stringent requirements for clinical evidence, particularly for novel technologies like bioresorbable scaffolds. Successfully navigating reimbursement policies for new procedures and devices across different national healthcare systems remains a critical variable for manufacturers seeking market access.
Market Dynamics
The fundamental market dynamic is the procedural shift from hospital inpatient settings to outpatient Ambulatory Surgical Centers. This migration alters purchasing decisions, device requirements, and the competitive landscape for manufacturers serving interventional cardiology and radiology departments.
Growth Catalysts
- Bioresorbable Scaffolds:The development of advanced bioresorbable scaffolds, which dissolve over time, offers a clinical alternative to permanent metallic implants, driving adoption in specific patient populations concerned with long-term device presence.
- Demographic Pressures:An aging population in countries like Germany and Japan leads to a higher prevalence of Peripheral Artery Disease (PAD) and associated comorbidities, expanding the addressable patient volume for interventions.
- Reimbursement Policy:Favorable changes in reimbursement codes for procedures performed in Ambulatory Surgical Centers in the United States encourage the transfer of cases from more expensive hospital operating rooms.
Market Restraints
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance, increasing the time and cost for device manufacturers to gain and maintain CE marking.
- Material Costs:Price volatility and supply concentration of raw materials like nitinol and cobalt-chromium, which are essential for manufacturing stents and guidewires, create cost pressures for device producers.
- Technical Limitations:Certain drug-eluting technologies face challenges related to long-term vessel patency and the risk of late-stent thrombosis, which can limit their application in more complex or lengthy arterial lesions.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets such as Brazil and India present significant growth avenues as healthcare infrastructure improves and access to advanced treatments for vascular disease expands.
- Below-the-Knee (BTK) Devices:There is a distinct clinical need for specialized devices, including smaller-diameter stents and drug-coated balloons, designed specifically for treating complex lesions in arteries below the knee.
- AI-Enhanced Imaging:Integrating artificial intelligence algorithms with fluoroscopic guidance systems can optimize device placement, reduce radiation exposure for patients and clinicians, and improve procedural outcomes.
Industry Challenges
- Specialist Skill Gaps:A shortage of interventional radiologists and vascular surgeons with advanced training on novel devices and complex endovascular techniques limits the broader adoption of new procedures.
- Reimbursement Fragmentation:Manufacturers must navigate inconsistent and often delayed reimbursement decisions across different national and regional healthcare payers, complicating market access strategies, particularly within Europe.
- System Interoperability:Ensuring seamless integration of new catheter-based intervention systems with hospitals' existing picture archiving and communication systems (PACS) and electronic health records remains a persistent operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Vascular Interventions Market |
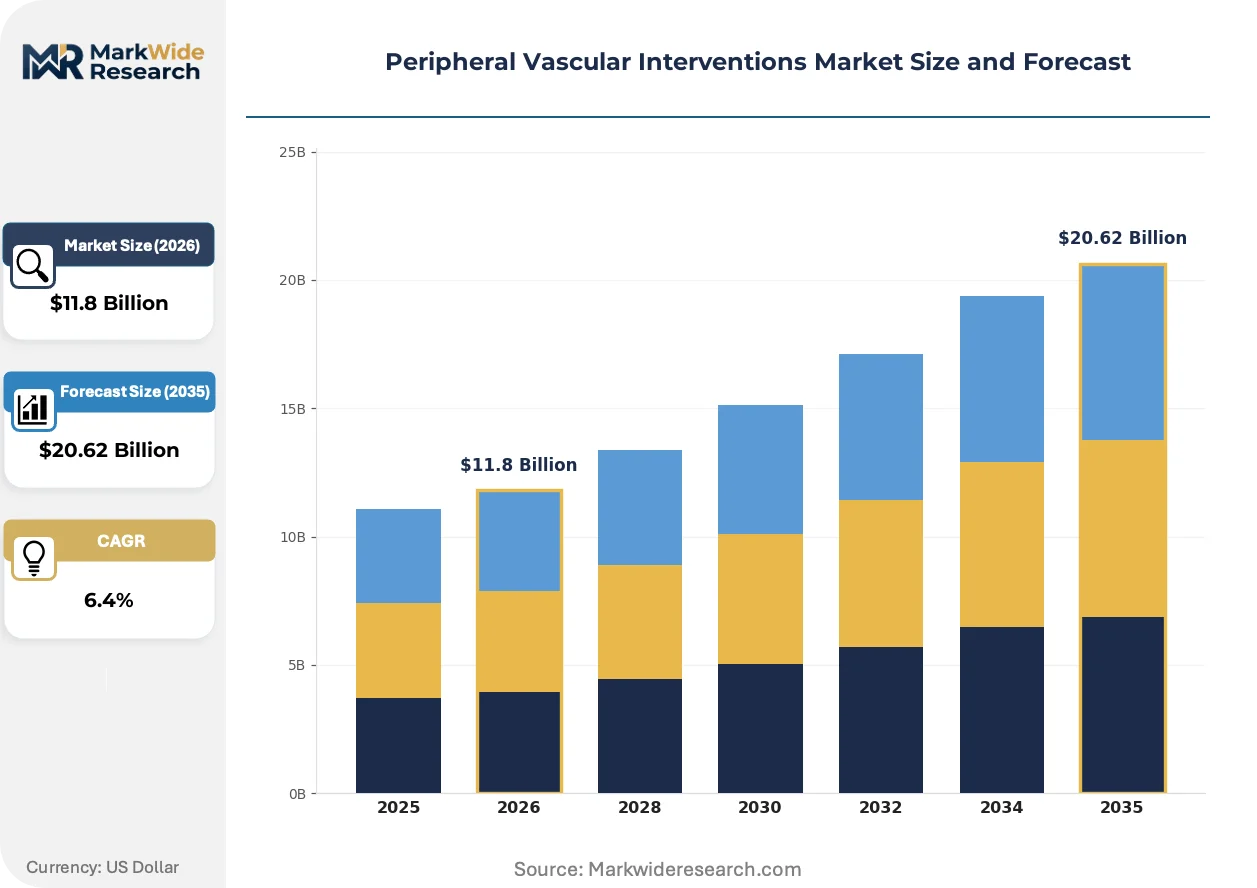
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stents, Atherectomy Devices, Embolic Protection Devices, Guidewires Therapy Area: Carotid Artery Disease, Peripheral Artery Disease, Chronic Total Occlusion, Deep Vein Thrombosis, Aneurysms End User: Cardiology Centers, Vascular Surgery Clinics, Specialty Hospitals, Diagnostic Imaging Facilities, Ambulatory Surgical Centers Deployment Type: Hospital-Based, Clinic-Based, Mobile Units, Telehealth-Enabled Services, Outpatient Facilities |
| Companies Covered | B. Braun Melsungen AG, W. L. Gore & Associates, Boston Scientific Corporation, Stryker, Cook Medical, Medtronic, Terumo Corporation, Philips, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Vascular Interventions Market Strategic Shifts & Innovations
Device innovation is focused on treating more complex lesions in smaller vessels with greater precision and durability. This technological push corresponds with a procedural migration to lower-cost outpatient settings, altering the entire service delivery model for vascular care.
Bioresorbable scaffolds provide temporary vessel support before gradually dissolving, eliminating a permanent implant. These devices are being adopted for patients with less complex, focal lesions where long-term caging of the vessel is undesirable. This technology is supplanting permanent metallic stents in select clinical scenarios, particularly within younger patient demographics treated in specialized centers.
Europe's Medical Device Regulation (MDR) elevates the standards for clinical evidence required for market approval and continued access. The regulation forces manufacturers to conduct more rigorous post-market clinical follow-up studies to prove long-term safety and performance. Novel technologies like bioresorbable scaffolds are most affected, facing extended timelines to gather sufficient data for certification.
Physician-preference purchasing in Ambulatory Surgical Centers is disrupting traditional hospital procurement models. This shift favors suppliers who engage directly with clinicians on device efficacy and training, rather than competing solely on price through large Group Purchasing Organization contracts. The trend is most advanced in the United States, where the outpatient procedural volume is expanding rapidly.
Peripheral Vascular Interventions Market Segmentation
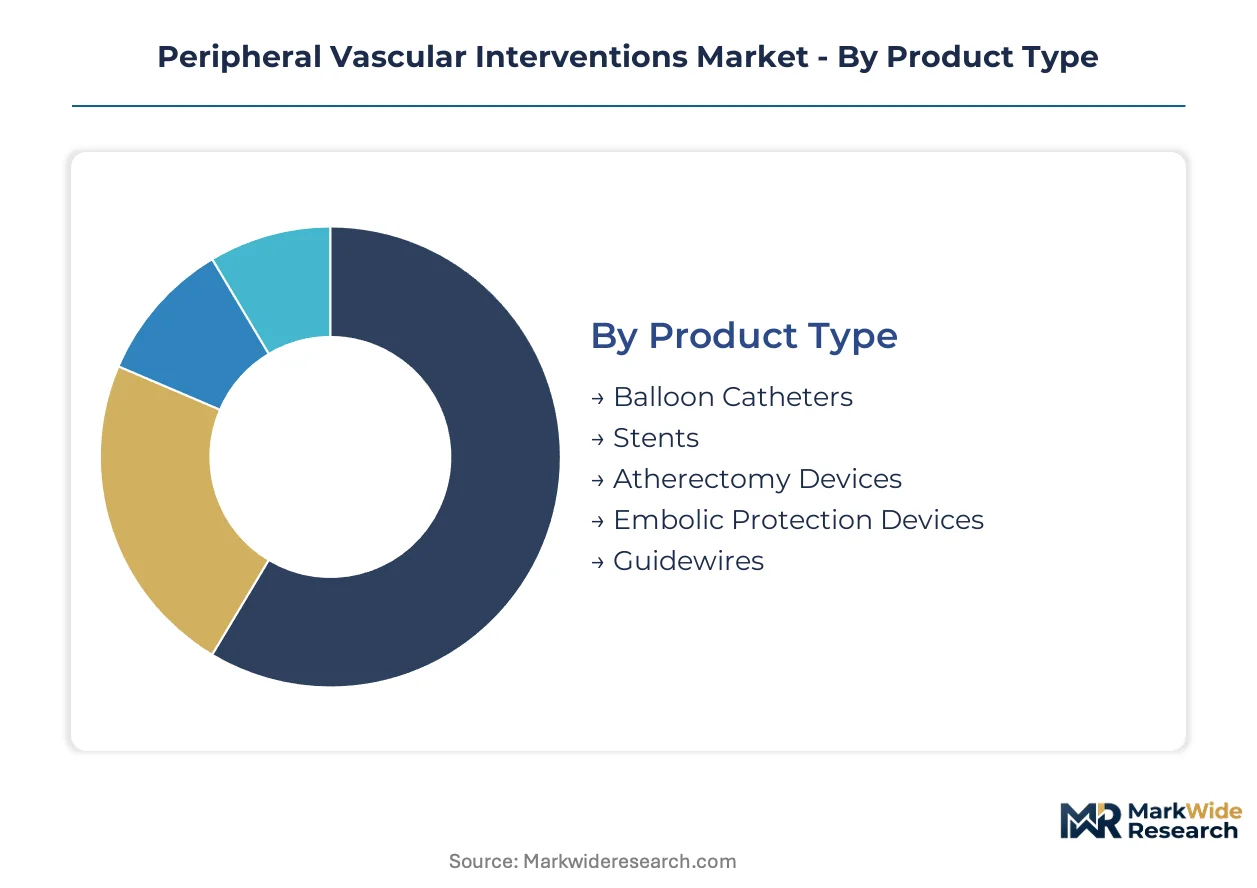
The Peripheral Vascular Interventions Market is delineated by distinct segments that reflect evolving clinical practices, technological advancements, and shifts in healthcare delivery models. Understanding these segment dynamics is crucial for manufacturers to align product development and market access strategies effectively.
Product Type:
Substitution pressure from bioresorbable scaffolds challenges traditional metallic implants across the product type segments, driving innovation towards temporary vessel support solutions.
- Stents:These permanent or bioresorbable tubular devices are deployed to maintain vessel patency following angioplasty, often made from nitinol or cobalt-chromium. Demand concentrates in treatments for complex Peripheral Artery Disease lesions, driven by an aging population requiring durable solutions.
- Balloon Catheters:These devices feature an inflatable balloon at their tip, used to dilate stenotic peripheral arteries and veins, often coated with anti-restenotic drugs. Their application is expanding in Ambulatory Surgical Centers, encouraged by favorable reimbursement policies for outpatient procedures.
- Atherectomy Devices:Specialized catheters employ rotational, orbital, or directional mechanisms to remove atherosclerotic plaque from arterial walls.
- Embolic Protection Devices:Filters or occlusion balloons are temporarily deployed distal to a lesion to capture or deflect embolic debris during intervention, preventing downstream complications.
- Guidewires:Thin, flexible wires navigate through the vascular system, providing a rail for the advancement of other interventional devices.
Stents anchor the volume base while Atherectomy Devices gain share at the steepest rate.
Therapy Area:
Application focus defines distinct patient populations and procedural approaches within therapy areas, requiring specialized device designs for optimal outcomes.
- Peripheral Artery Disease:This condition involves narrowed arteries that reduce blood flow to the limbs, primarily affecting the legs and feet, necessitating a broad range of revascularization devices. An aging demographic in countries like Germany and Japan fuels the primary application volume for these interventions.
- Chronic Total Occlusion:Complete blockages in arteries that have persisted for a significant duration require highly specialized guidewires and re-entry devices to navigate and recanalize the occluded segment. Clinical needs for these complex procedures are pronounced in patients with advanced vascular disease.
- Carotid Artery Disease:Stenosis in the carotid arteries, which supply blood to the brain, carries a risk of stroke, often treated with carotid stenting or endarterectomy.
- Deep Vein Thrombosis:Blood clots forming in deep veins, typically in the legs, are managed with catheter-directed thrombolysis or mechanical thrombectomy.
- Aneurysms:Weaknesses in arterial walls that bulge outwards are treated with endovascular aneurysm repair (EVAR) using stent grafts.
Peripheral Artery Disease represents the largest application volume, with Chronic Total Occlusion expanding most quickly.
End User:
Customer type segmentation reflects the evolving landscape of care delivery for vascular interventions, with a notable shift toward less intensive settings.
- Cardiology Centers:These specialized units within hospitals or standalone clinics perform a high volume of cardiac and peripheral vascular interventions, leveraging advanced imaging and catheterization labs. They remain critical hubs for complex cases and training.
- Ambulatory Surgical Centers:Outpatient facilities performing same-day surgical procedures, including many peripheral vascular interventions, benefit from lower operating costs and patient convenience. The United States sees significant procedural migration to these centers due to favorable reimbursement.
- Vascular Surgery Clinics:Outpatient clinics managed by vascular surgeons provide consultations, diagnostics, and often perform minor interventional procedures.
- Specialty Hospitals:Hospitals with a dedicated focus on specific medical areas, such as cardiovascular diseases, offer comprehensive care for complex peripheral vascular conditions.
- Diagnostic Imaging Facilities:These centers primarily focus on imaging services, including angiography, which is crucial for diagnosis and procedural planning in peripheral vascular interventions.
Cardiology Centers maintain high procedural volumes, while Ambulatory Surgical Centers are rapidly increasing their case load.
Deployment Type:
Maturity levels vary significantly across deployment types, influencing operational models and patient access for peripheral vascular interventions.
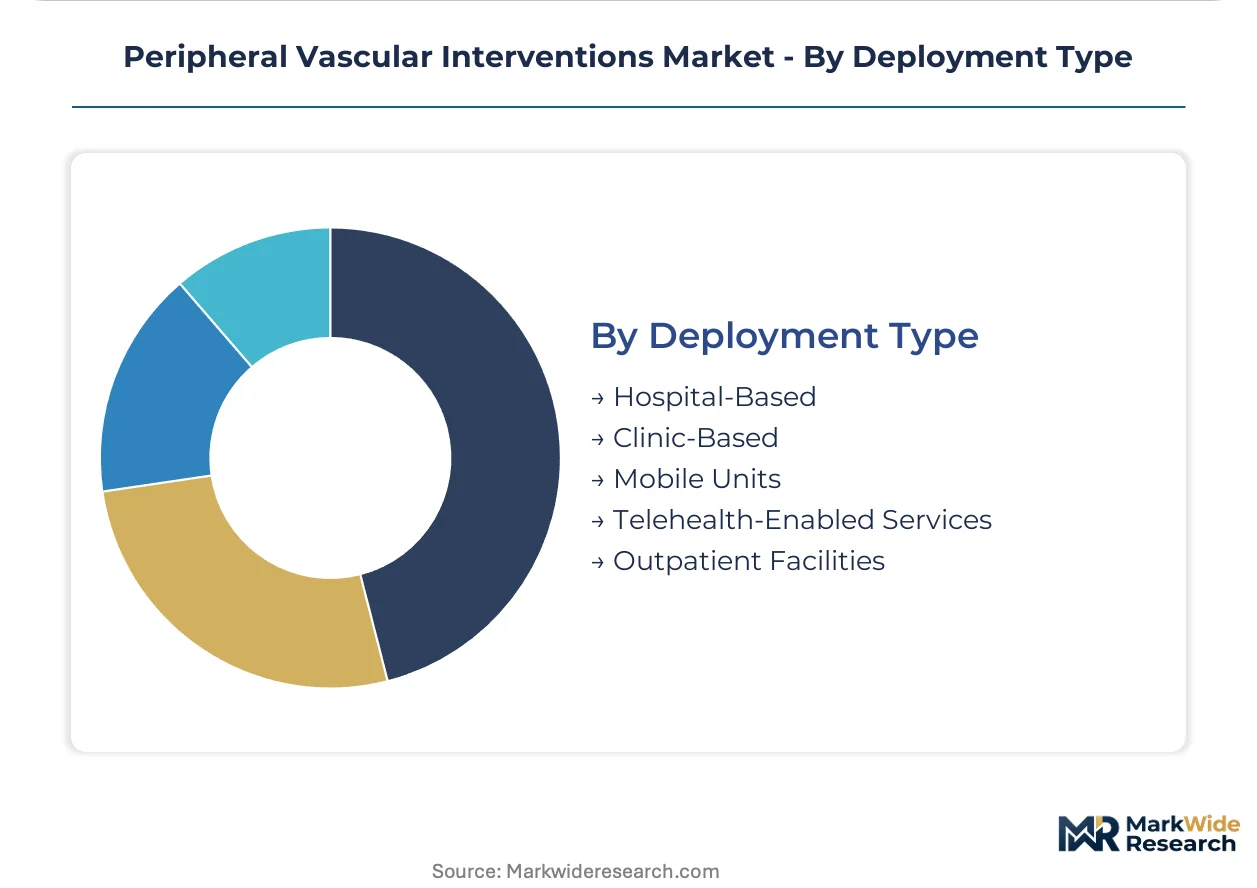
- Hospital-Based:Procedures performed within traditional hospital settings, including inpatient and outpatient departments, offer comprehensive support for complex cases and potential complications. This remains the foundational deployment type for high-acuity interventions.
- Outpatient Facilities:This category encompasses Ambulatory Surgical Centers and other standalone clinics where procedures are performed without an overnight stay. The procedural shift to these settings is a fundamental market dynamic, driven by cost efficiency and patient preference.
- Clinic-Based:Procedures conducted in physician offices or smaller clinics, typically for less complex cases or follow-up care, emphasize convenience and accessibility.
- Mobile Units:Specialized vehicles equipped for diagnostic or interventional procedures, often serving remote or underserved populations, offer flexible access to care.
- Telehealth-Enabled Services:Remote consultation, monitoring, and pre/post-procedure guidance utilizing digital communication technologies enhance patient engagement and care coordination.
Hospital-Based interventions remain the core, as Outpatient Facilities see significant expansion driven by policy shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced healthcare infrastructure underwrites the global role of key geographies in the peripheral vascular interventions market. Countries with established medical device industries and high vascular disease prevalence drive significant demand. Regulatory frameworks and reimbursement policies within these regions critically influence market access and adoption of novel technologies.
United States
High prevalence of Peripheral Artery Disease and favorable reimbursement policies for Ambulatory Surgical Centers drive significant demand for interventions. The US FDA's rigorous device approval pathways influence market entry timelines for new products. Boston's MedTech cluster continues to innovate in minimally invasive devices, attracting substantial investment and research talent.
Germany
An aging population and a high prevalence of associated comorbidities expand the addressable patient volume for peripheral vascular interventions. The European Medical Device Regulation (MDR), implemented by the EMA, sets stringent requirements for clinical evidence. Munich's medical technology hub focuses on developing advanced imaging and interventional tools, supporting local and regional clinical practices.
Japan
An aging demographic creates a substantial patient pool requiring advanced treatments for vascular conditions. Japan's PMDA dictates market entry and post-market surveillance for medical devices, ensuring product quality. Tokyo's research and development centers actively pursue innovations in bioresorbable scaffolds and drug-eluting technologies, positioning the city as a key innovation hub.
United Kingdom
A strong clinical research base and a national healthcare system focused on patient outcomes support the adoption of advanced peripheral vascular intervention techniques. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees device approvals and post-market vigilance. London's healthcare innovation ecosystem fosters collaborations between academic institutions and medical device companies.
France
A focus on patient-centric care and early adoption of innovative devices, such as bioresorbable scaffolds, characterize the French market. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) ensures compliance with European Union medical device regulations. Lyon's growing biotech and medical device industry contributes to the development of specialized guidewires and catheters.
Peripheral Vascular Interventions Market Key Industry Players
Listed leaders compete with private specialists across the peripheral vascular interventions market, reflecting a dynamic industry structure. The market exhibits a tiered consolidation, with large diversified medical technology companies alongside specialized niche players. Key strategic archetypes include broad portfolio providers, minimally invasive innovators, and specialized component manufacturers. Competitive moves often involve strategic partnerships to enhance product portfolios and targeted geographic expansion into underpenetrated markets.
Among the broad portfolio providers, Medtronic leverages its extensive product range to serve both hospital and outpatient channels effectively. Boston Scientific Corporation exemplifies innovation in minimally invasive devices for complex lesions, maintaining a strong market presence. Cook Medical sustains its market position as a specialized component manufacturer, providing essential guidewires and catheters for a wide array of interventional procedures.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| W. L. Gore & Associates |
| Boston Scientific Corporation |
| Stryker |
| Cook Medical |
| Medtronic |
| Terumo Corporation |
| Philips |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
The European Medical Device Regulation (MDR) dictates stringent market entry for devices, directly influencing supply qualification and pricing power for novel technologies. This regulatory framework ensures product safety and performance, but also adds significant cost to development and compliance.
Pricing Analysis
Volume-based contracts structure pricing for peripheral vascular interventions, particularly for high-volume hospital systems. Price differentiation stems from device complexity and the depth of clinical evidence supporting long-term outcomes. Pricing pressure stems from the shift to outpatient settings, where cost efficiency is paramount. Ambulatory Surgical Centers exhibit higher price sensitivity compared to large hospital procurement departments.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume, standard devices, while strategic stockpiles support specialized bioresorbable scaffolds and complex guidewires. Supply concentrates in advanced manufacturing hubs across the United States, Germany, and Japan. Raw material dependencies include nitinol, cobalt-chromium, and specialized polymer coatings. Commodity price volatility presents a structural risk, and distribution primarily occurs through direct sales forces engaging end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peripheral vascular interventions market undergoes high-growth disruption, driven by the procedural migration to Ambulatory Surgical Centers. This shift alters the entire service delivery model for vascular care.
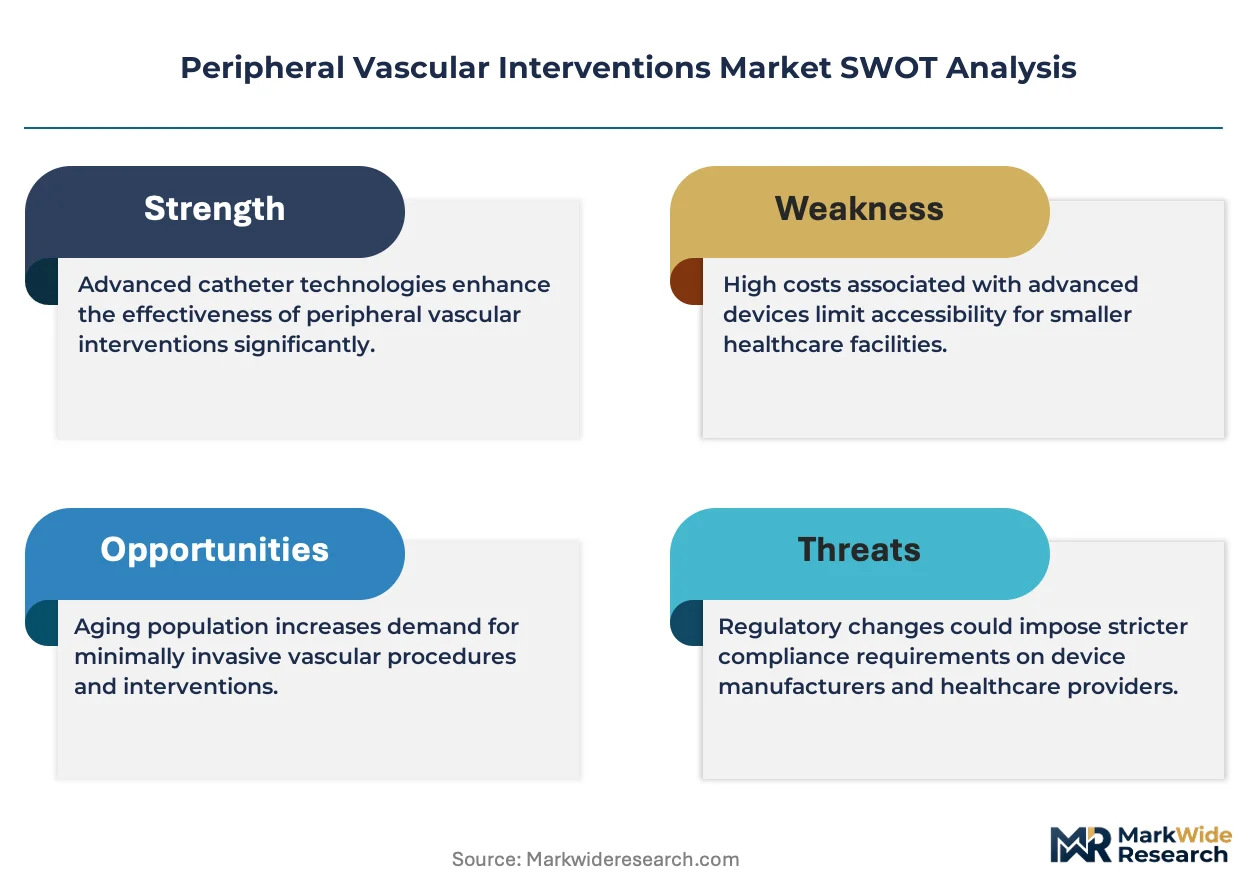
For Market Incumbents: Shield market share by deepening partnerships with Ambulatory Surgical Centers through integrated device portfolios and training programs. Acquire niche technology firms specializing in advanced bioresorbable scaffolds to counter the threat from novel device innovation. Invest in R&D for AI-enhanced imaging to maintain a competitive edge. Strengthen clinical evidence for existing product lines to navigate evolving regulatory scrutiny.
For New Entrants and Emerging Players: Expedited certification pathways for breakthrough devices offer new entrants a strategic advantage in the peripheral vascular interventions market. Target underpenetrated segments like Below-the-Knee (BTK) devices and emerging geographic markets such as Brazil and India. Focus on direct physician engagement and specialized training programs for novel technologies. This approach allows smaller innovators to gain traction against established players.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across outpatient intervention facilities, favoring asset-light business models. Seek acquisition targets with strong intellectual property in bioresorbable scaffolds or AI-integrated navigation systems. Long-term viability remains strong due to an aging demographic and continuous technological advancements. Monitor shifts in national reimbursement policies for outpatient procedures as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firms | Acquiring innovators in bioresorbable scaffolds diversifies product portfolios and mitigates competitive threats. |
| Expansion into Ambulatory Surgical Centers | Deepening engagement with ASCs captures procedural volume from the inpatient setting. |
| Investment in AI-Enhanced Imaging | Integrating AI improves procedural precision and reduces radiation exposure for clinicians. |
| Development of Below-the-Knee Devices | Addressing unmet clinical needs in smaller vessels expands the addressable patient population. |
| Strategic Partnerships in Emerging Markets | Collaborating with local distributors in Brazil and India facilitates market access and growth. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings and quantitative models within this analysis. Primary insights derive from interventional cardiologists, vascular surgeons, hospital procurement managers, and Ambulatory Surgical Center administrators. Secondary sources include US FDA filings, EMA submissions, clinical trial registries, and Group Purchasing Organization contract data. This approach ensures robust bottom-up and top-down triangulation.
Sensitivity analysis frames the forecast framework, evaluating market dynamics across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, deployment type, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends, projected disease prevalence, and anticipated technological adoption. Key industry-specific forecast inputs encompass demographic shifts and device approval timelines.
Underlying assumptions cover current regulatory frameworks and established technological adoption curves, with deviation risk concentrated in unforeseen policy changes. Geopolitical instability affecting raw material supply also presents a significant risk. Revision becomes warranted when key clinical trial outcomes or major reimbursement decisions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market