
 Stent Grafts Market | 2026-2036
Stent Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Stent Grafts Market Analysis
Aftermarket service revenue is fragmenting between device manufacturers and third-party reprocessors. Medtronic leverages its integrated vascular platform to capture recurring clinical support contracts. Cook Medical sustains dominance in custom-designed thoracic graft configurations for complex anatomies. W. L. Gore & Associates differentiates through proprietary expanded polytetrafluoroethylene materials that anchor premium positioning in abdominal aortic applications.
Stent grafts are implantable tubular prostheses combining metallic scaffold structures with fabric coverings, typically manufactured from nitinol or stainless steel frames paired with polyester or ePTFE graft material, designed to exclude aneurysmal segments from arterial pressure while restoring physiologic blood flow. Abdominal aortic grafts occupy the largest volume position due to standardized infrarenal landing zone protocols and broad surgeon familiarity. Thoracic aortic grafts represent the fastest-expanding segment as branched and fenestrated designs enable endovascular repair of arch and descending pathologies previously managed only through open surgery. Polymer-based materials lead current revenue while composite configurations gain traction for their balance of conformability and radial force durability.
FDA premarket approval requirements and the EU Medical Device Regulation impose substantial clinical evidence burdens that filter market entrants and extend product development timelines. Japan's PMDA maintains distinct technical documentation standards that shape localization strategies for multinational manufacturers. Stakeholders must monitor evolving real-world evidence requirements and health technology assessment methodologies as payers tighten reimbursement criteria for elective endovascular procedures.
Market Dynamics
Endovascular repair protocols are displacing open surgical approaches for aortic pathologies, compressing hospital length-of-stay metrics and redirecting capital expenditure toward catheterization laboratory infrastructure rather than traditional operating theater capacity.
Growth Catalysts
- Fenestrated Graft Architecture:Branched and fenestrated stent designs are enabling endovascular repair of juxtarenal and suprarenal aneurysms previously excluded from minimally invasive treatment protocols.
- Japan's PMDA Accelerated Pathways:Streamlined approval mechanisms for breakthrough medical devices are reducing time-to-market for novel thoracic graft configurations in the world's fastest-aging major economy.
- Outpatient Procedure Migration:Ambulatory surgical centers in the United States are expanding endovascular capacity, capturing elective infrarenal repairs from inpatient hospital settings.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy supply concentration in Chinese smelting operations creates input cost instability for frame manufacturing.
- EU MDR Clinical Evidence Burden:Expanded post-market surveillance requirements and notified body capacity constraints are extending recertification timelines for legacy abdominal graft products.
- Open Surgery Residual Preference:Vascular surgeons in Germany and Japan retain institutional training pathways that sustain hybrid and open repair volumes for complex anatomies.
Strategic Opportunities
- India's Underpenetrated Elective Repair Market:Abdominal aortic aneurysm screening programs remain nascent, creating first-mover positioning for localized graft distribution partnerships.
- Computed Tomography Angiography Integration:Preoperative planning software convergence with three-dimensional printing is enabling patient-specific graft sizing workflows.
- Brazil's ANVISA Harmonization:Regulatory alignment with FDA premarket approval standards is reducing duplicate clinical trial requirements for multinational manufacturers.
Industry Challenges
- Complex Anatomy Planning Expertise:Fenestrated and branched graft deployment requires specialized computational fluid dynamics skills that outpace current fellowship training output.
- Real-World Evidence Infrastructure:Post-market registry participation demands data architecture investments that strain mid-tier manufacturer operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stent Grafts Market |
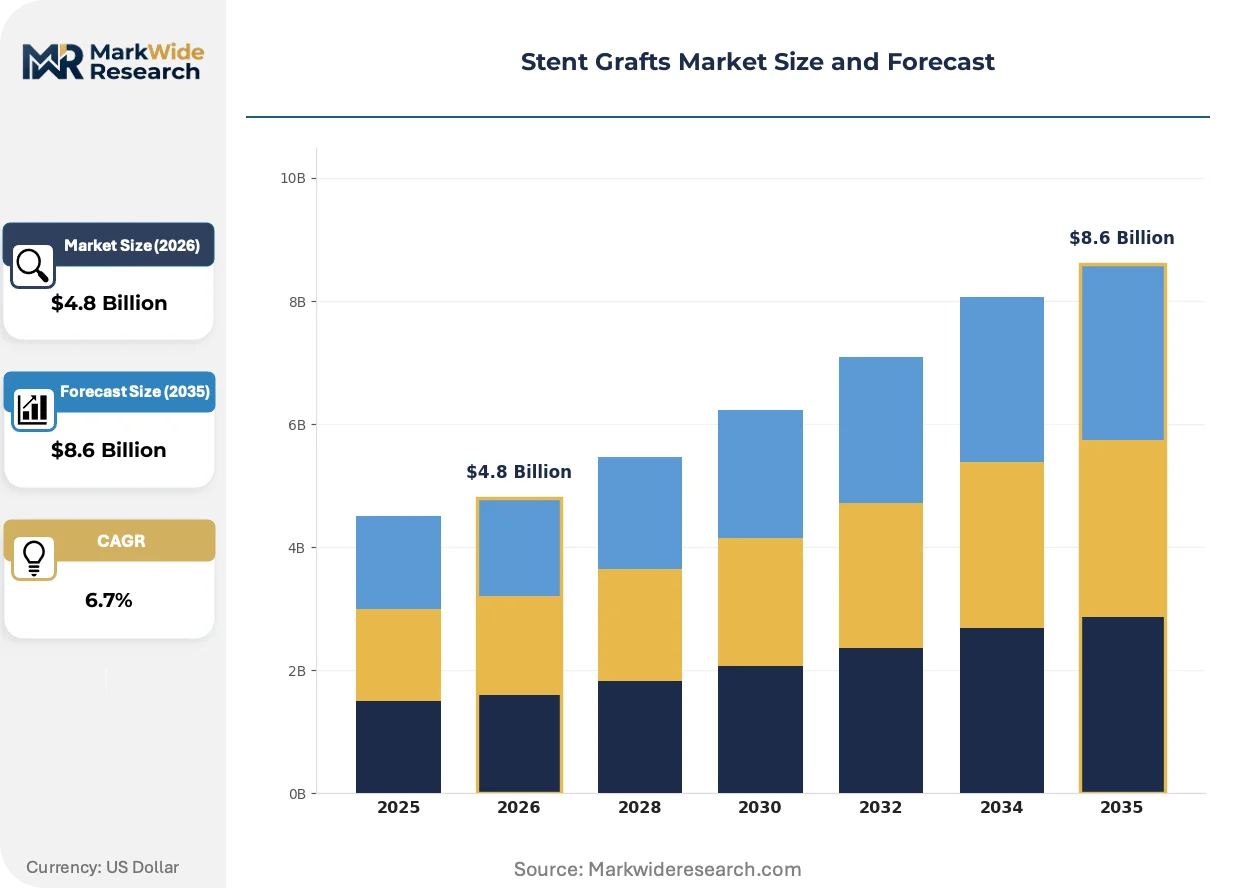
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ascending Aortic Grafts, Peripheral Aortic Grafts, Thoracic Aortic Grafts, Abdominal Aortic Grafts Material: Polymer, Metal, Composite, Biodegradable Delivery Mode: Endovascular, Open Surgery, Minimally Invasive, Robotic Assistance End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Medtronic, Cook Medical, W. L. Gore & Associates, Terumo Corporation, BD, Getinge AB, B. Braun Melsungen AG, Endologix, Jotec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stent Grafts Market Emerging Trajectories
Computational modeling and intraoperative imaging convergence are compressing the planning-to-procedure timeline for complex aortic repairs, while regulatory frameworks on three continents simultaneously tighten evidence standards.
Three-dimensional printing is digitizing patient-specific graft manufacturing workflows. Vascular centers in Germany and the United States are adopting computed tomography-derived anatomical models for preoperative device selection. This capability is digitizing the traditional sizing process, reducing operative time and contrast exposure during fenestrated deployments.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic long-term follow-up data collection. Manufacturers must now maintain active implant registries with fifteen-year mortality and reintervention tracking. Thoracic graft portfolios face the steepest compliance burden given the younger patient demographics and extended life expectancy of successful repairs.
Hospital procurement departments are consolidating vendor relationships through integrated delivery network contracting. United States health systems are bundling stent graft supply with clinical support services and physician training commitments. This concentration is visible most acutely in the southeastern states where Catholic health system mergers have reduced qualified suppliers to two or three per network.
Stent Grafts Market Segmentation
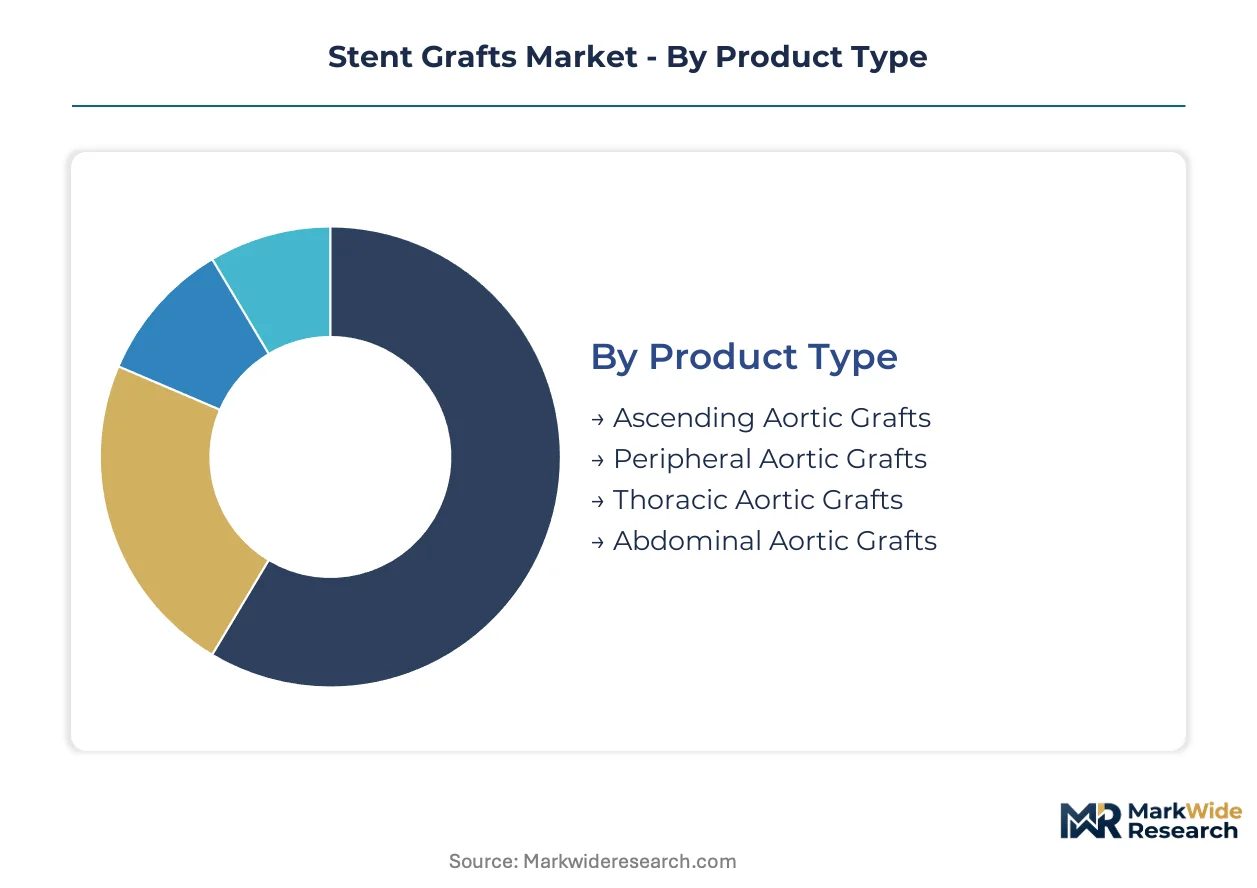
Stent graft segmentation reveals how anatomical complexity, material science, and care setting economics partition commercial opportunity. Each dimension carries distinct regulatory pathways and reimbursement logic that shape manufacturer portfolio priorities.
Product Type:
Mature repair protocols dominate abdominal applications while thoracic designs represent the frontier of endovascular capability expansion.
- Abdominal Aortic Grafts:Nitinol or stainless steel frames paired with polyester or ePTFE fabric target the infrarenal landing zone below the renal arteries. Hospital systems in the United States and Germany perform the highest elective volumes where established reimbursement codes support standardized workflows.
- Thoracic Aortic Grafts:Branched and fenestrated configurations enable endovascular repair of arch and descending pathologies. Japan's PMDA accelerated pathways are reducing approval timelines for these complex designs as the country's aging population drives demand for minimally invasive alternatives to open surgery.
- Ascending Aortic Grafts:Specialized configurations address the aortic root and ascending segments near the heart.
- Peripheral Aortic Grafts:Smaller-diameter designs target iliac and femoral aneurysmal disease.
Abdominal aortic grafts handle the majority of throughput; thoracic aortic grafts are climbing the fastest on share.
Material:
Cost tier stratification separates established synthetic platforms from emerging bioresorbable alternatives.
- Polymer:Polyester and expanded polytetrafluoroethylene fabrics dominate current revenue through proven durability and broad surgeon familiarity. ePTFE commands premium positioning in abdominal applications where tissue ingrowth characteristics anchor long-term seal performance.
- Composite:Hybrid configurations balance nitinol radial force with polymer conformability. These designs are gaining traction in thoracic deployments where anatomical tortuosity demands both structural support and flexibility.
- Metal:Bare metal or fully metallic constructs occupy niche indications.
- Biodegradable:Experimental magnesium and polymer alloys target temporary scaffolding applications.
Polymer platforms absorb the bulk of current implant volume; composite configurations are expanding most quickly as complex anatomy cases multiply.
Delivery Mode:
Volume concentration favors catheter-based deployment while robotic systems represent capital-intensive differentiation.
- Endovascular:Catheter-delivered deployment through femoral access has displaced open surgery for most infrarenal repairs. Ambulatory surgical centers in the United States are expanding dedicated endovascular capacity to capture elective cases from inpatient settings.
- Minimally Invasive:Hybrid approaches combining small incisions with endovascular elements address anatomies unsuitable for pure percutaneous repair.
- Open Surgery:Traditional graft replacement through thoracotomy or laparotomy persists for complex arch reconstructions.
- Robotic Assistance:Da Vinci and comparable platforms enable precision suturing in hybrid procedures.
Endovascular delivery captures the dominant procedure share; minimally invasive techniques are gaining ground fastest as imaging and planning software improves.
End User:
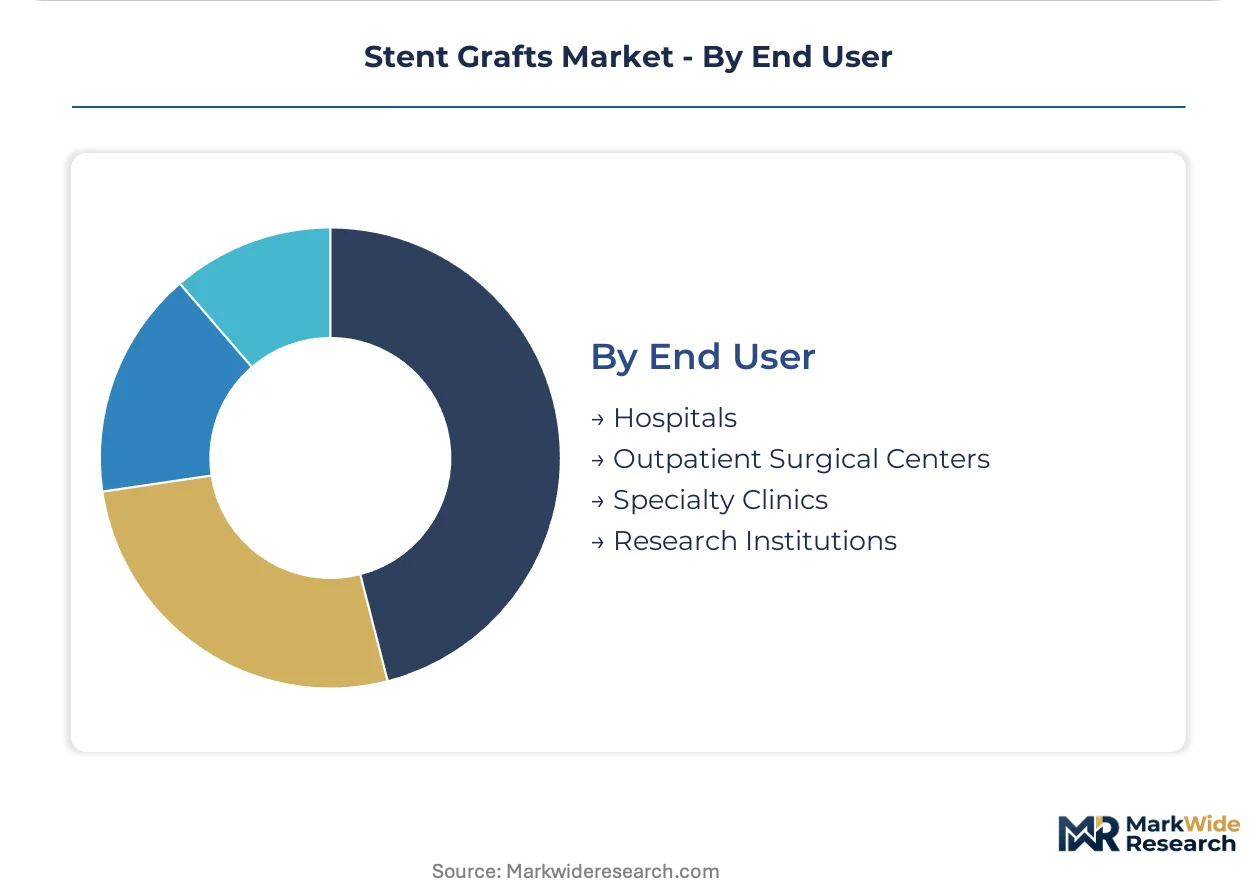
Customer type segmentation tracks the migration of elective repair from tertiary hospitals toward distributed surgical infrastructure.
- Hospitals:Academic medical centers and community hospitals maintain the deepest case volumes for complex thoracic repairs requiring intensive care unit backup. Catholic health system mergers in the southeastern United States have consolidated purchasing power around two or three qualified suppliers per network.
- Outpatient Surgical Centers:Freestanding facilities are capturing stable infrarenal abdominal repairs where same-day discharge protocols reduce total episode cost. United States reimbursement policy shifts favor site-of-service migration for qualifying patients.
- Specialty Clinics:Vascular-focused practices concentrate preoperative planning and follow-up surveillance.
- Research Institutions:Academic centers drive fenestrated graft trials and computational modeling validation.
Hospitals retain the majority of complex case throughput; outpatient surgical centers are expanding fastest as ambulatory reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for complex thoracic grafts, while procurement departments in India and Brazil prioritize cost containment over premium positioning.
United States
Hospital systems in the southeastern states consolidate purchasing through Catholic health network mergers, reducing qualified suppliers per network. FDA premarket approval pathways reshape clearance timelines for fenestrated designs. The Texas Medical Center in Houston anchors complex aortic repair volumes with dedicated endovascular surgery programs.
Germany
Vascular surgeons retain institutional training pathways sustaining hybrid and open repair volumes for complex anatomies. EU Medical Device Regulation imposes expanded post-market surveillance with fifteen-year tracking requirements. The Baden-Württemberg cluster around Stuttgart concentrates custom thoracic graft manufacturing for challenging landing zones.
Japan
The world's fastest-aging major economy drives demand for minimally invasive alternatives to open surgery. PMDA accelerated pathways reduce time-to-market for novel thoracic graft configurations. Tokyo's academic medical centers lead fenestrated graft trials and computational modeling validation.
India
Abdominal aortic aneurysm screening programs remain nascent, creating first-mover positioning for localized distribution partnerships. CDSCO regulatory harmonization efforts streamline import pathways for multinational manufacturers. Maharashtra's private hospital chains in Mumbai and Pune expand elective endovascular capacity.
Brazil
ANVISA alignment with FDA premarket approval standards reduces duplicate clinical trial requirements for multinational entrants. Public hospital procurement favors cost-optimized abdominal graft configurations. São Paulo's vascular surgery centers concentrate the country's complex thoracic repair expertise.
Stent Grafts Market Vendor Landscape
Capability concentration sits with integrated vascular platforms; scale advantage sits with diversified medical device conglomerates. The vendor base organizes around three strategic archetypes: integrated platform operators capturing recurring clinical support contracts, custom-configuration specialists serving complex anatomies, and materials-science differentiators commanding premium positioning through proprietary polymers. Dominant competitive moves include vertical integration into nitinol frame manufacturing and strategic partnerships with computed-tomography planning software vendors.
Among integrated platform operators, Medtronic exemplifies the capability-heavy archetype through its vascular ecosystem. Cook Medical represents the custom-configuration specialist tier with bespoke thoracic designs. W. L. Gore & Associates anchors the materials-science differentiation vector through proprietary expanded polytetrafluoroethylene positioning.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| W. L. Gore & Associates |
| Terumo Corporation |
| BD |
| Getinge AB |
| B. Braun Melsungen AG |
| Endologix |
| Jotec GmbH |
| Others |
Supply Flow & Price Mechanics
Chinese nitinol smelting operations concentrate frame-grade nickel-titanium alloy supply, anchoring margin capture with device manufacturers who have secured long-term offtake agreements while tier-two competitors absorb spot-market volatility. This upstream concentration cascades downstream into differentiated pricing power across abdominal versus thoracic graft portfolios.
Pricing Analysis
Aftermarket service contracts and clinical support subscriptions now drive lifetime value beyond initial device placement. Three-tier pricing structure across premium fenestrated configurations, standard infrarenal platforms, and economy bare-metal alternatives separates Medtronic's integrated vascular ecosystem from Cook Medical's custom thoracic specialization and W. L. Gore's ePTFE material premium. Price differentiation hinges on FDA PMA pathway completion and EU MDR certification tier, with margins tightening for legacy abdominal grafts facing recertification burdens while branched thoracic designs command pricing power. Hospital procurement committees in the United States demonstrate lowest price sensitivity for complex arch repairs, whereas Brazilian public hospital tenders prioritize cost-optimized abdominal configurations.
Supply Chain Analysis
Contract manufacturing for nitinol laser-cut frames concentrates with Nitinol Devices & Components and SAES Getters in the United States, with secondary capacity at Fort Wayne Metals, while ePTFE graft fabric production rests on W. L. Gore's proprietary Delaware operations and limited alternative suppliers in Germany and Japan. Raw material dependencies span nickel-titanium alloy feedstock, medical-grade polyester yarn, and platinum-iridium radiopaque markers. Single-source vulnerability in ePTFE membrane supply creates concentrated risk for thoracic graft manufacturers. Distribution runs through direct hospital contracting in North America and Western Europe, with localized distributor partnerships dominating India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stent graft markets are approaching a platform-economics inflection where computational planning software interoperability determines ecosystem lock-in, with Medtronic's acquisition trajectory and Cook Medical's imaging partnerships signaling the shift toward integrated surgical workflow capture.
For Market Incumbents: Harden proprietary ePTFE supply positions through backward integration into medical-grade polymer resin production, while simultaneously embedding computational fluid dynamics planning tools into hospital cath lab infrastructure to raise switching costs. Defend against emerging robotics-assisted deployment platforms by accelerating fenestrated graft FDA submissions and securing exclusive GPO contracts with Catholic health system networks in the southeastern United States. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated abdominal aortic aneurysm screening infrastructure through CDSCO-registered distribution partnerships with Maharashtra private hospital chains, leveraging cost-optimized nitinol frame sourcing from Chinese contract manufacturers. Target ambulatory surgical center expansion in the United States with simplified infrarenal graft configurations designed for same-day discharge protocols, bypassing entrenched hospital procurement committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed custom thoracic graft specialists possessing FDA breakthrough device designation but limited commercial infrastructure, representing platform tuck-in opportunities for diversified medtech conglomerates. Five-to-ten year viability hinges on EU MDR recertification completion and real-world evidence registry participation. Watch for PMDA accelerated approval grants to Japanese thoracic graft developers as inflection signals for Asia-Pacific competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | PMDA harmonization accelerates Japanese market entry for fenestrated configurations. |
| Hospital System Partnership | Catholic health network consolidation in the southeastern United States reduces qualified suppliers per IDN. |
| Computational Planning Integration | CT-derived 3D modeling partnerships compress planning-to-procedure timelines for complex anatomies. |
| EU MDR Recertification | Fifteen-year post-market surveillance mandates reshape legacy abdominal graft portfolio economics. |
| Reimbursement Strategy | CMS site-of-service payment differentials favor ASC migration for qualifying infrarenal repairs. |
Methodological Framework
A standing panel of vascular surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from FDA PMA filings, PMDA approval summaries, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare claims data. Bottom-up implant volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Scenario bracketing around regulatory timeline delays, nitinol price volatility bands, and reimbursement policy shifts anchored the analytical framework. Segmentation modeling incorporated product type complexity tiers, material science platforms, delivery mode capital intensity, and end-user site-of-service economics. CAGRs derived from logistic diffusion curves fitted to historical procedure volumes, adjusted for demographic aging trajectories and endovascular protocol adoption S-curves in Germany, Japan, and the United States.
Sensitivities concentrate around EU MDR notified body capacity constraints extending recertification timelines, PMDA technical documentation revisions, and nitinol supply disruptions from Chinese environmental compliance actions. Quarterly review of FDA PMA submission grants, GPO contract award announcements, and cath lab capital expenditure disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Hypertension Management Devices Market