
 Global Vascular Graft Market | 2026-2036
Global Vascular Graft Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Graft Market Foresight
Hospital procurement of synthetic grafts for hemodialysis access is broadening as chronic kidney disease prevalence climbs. W. L. Gore & Associates leverages its ePTFE technology leadership to dominate high-performance vascular conduit supply. Medtronic anchors its position through extensive R&D intensity across biological and composite graft platforms. Getinge competes on manufacturing scale, sustaining global distribution reach for Dacron-based aortic replacements.
A vascular graft is a tubular prosthetic implant designed to bypass, replace, or reinforce damaged blood vessels, typically manufactured from expanded polytetrafluoroethylene (ePTFE), polyethylene terephthalate (Dacron), or biodegradable polymers with pore sizes calibrated between 10–60 microns to enable tissue ingrowth and endothelialization. Synthetic grafts command the largest revenue share due to established clinical validation and standardized production economics, while biological grafts occupy premium niches requiring minimal thrombogenicity. Electrospun nanofiber technology leads fastest-growing segments as manufacturers refine sub-micron fiber architectures to mimic native vessel compliance and reduce intimal hyperplasia.
FDA premarket notification pathways and EMA Medical Device Regulation (MDR) conformity assessments govern biocompatibility, mechanical fatigue, and sterilization validation for vascular graft commercialization. ISO 7198 standards for cardiovascular implants define critical performance benchmarks including burst strength, suture retention, and kink resistance that shape product development priorities. Japan's PMDA adds layer-specific testing requirements for novel biodegradable polymer grafts entering clinical evaluation. Stakeholders must monitor evolving MDR technical documentation demands and shifting hemodialysis access reimbursement thresholds to calibrate portfolio investments between established synthetic lines and emerging resorbable platforms.
Market Dynamics
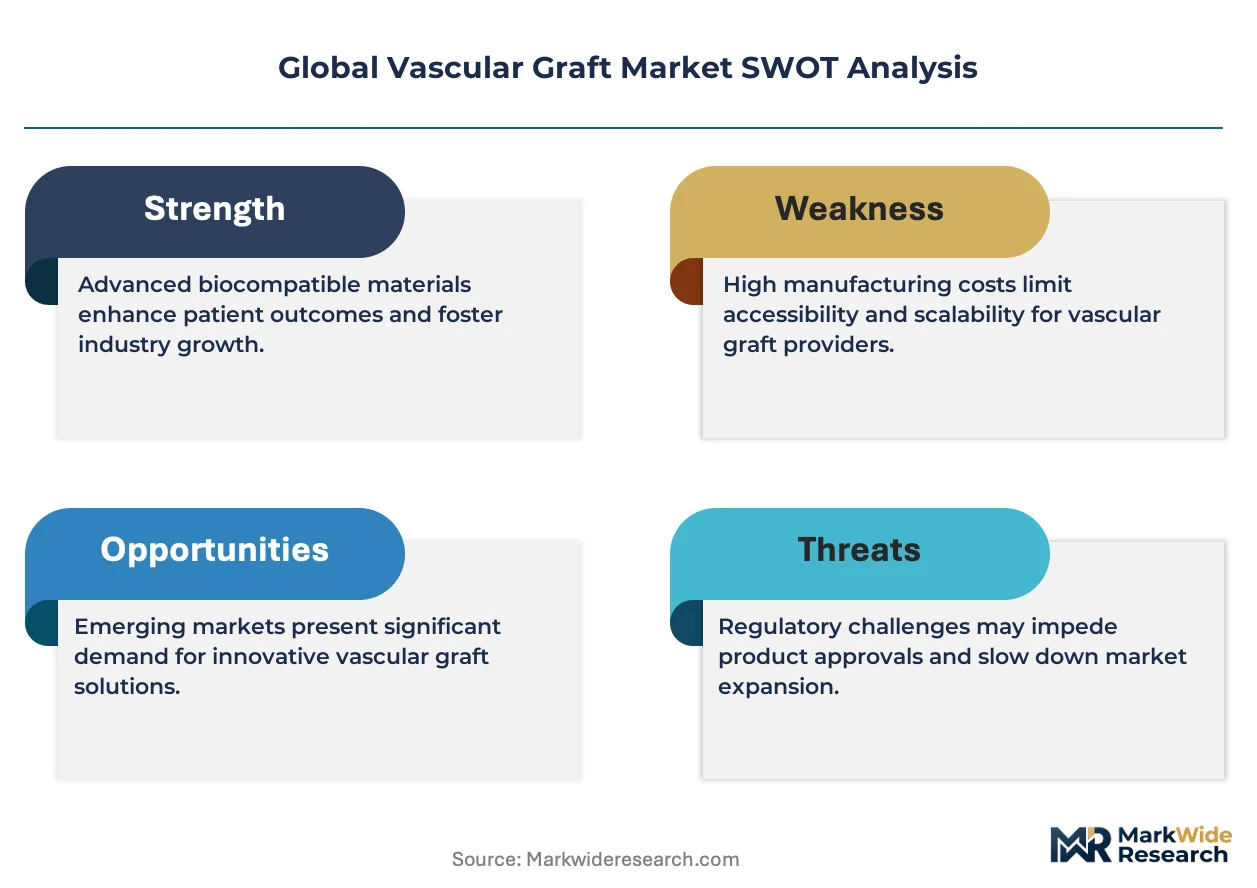
Electrospun nanofiber architectures are compressing the performance gap between synthetic grafts and autologous vessels, forcing manufacturers to reconfigure R&D spending toward compliance-first design rather than incremental material improvements.
Growth Catalysts
- Chronic kidney disease prevalence:Hospital procurement of synthetic grafts for hemodialysis access is broadening as dialysis-dependent populations expand in the United States, Germany, and Japan.
- FDA premarket notification pathways:Tightened biocompatibility testing protocols for ePTFE substrates are accelerating validation standards that filter out marginal competitors.
- Electrospinning technology:Sub-micron fiber manufacturing is enabling tissue-mimicking compliance profiles that reduce intimal hyperplasia in peripheral bypass applications.
Market Restraints
- Biodegradable polymer supply concentration:Novel resorbable substrate production clusters in specialized European chemical corridors, creating single-source vulnerability for graft manufacturers.
- EMA MDR technical documentation demands:Layer-specific testing requirements for novel materials are extending conformity assessment timelines and freezing pipeline commitments.
- Biological graft cost structures:Allograft and xenograft sourcing depends on tissue bank availability and serological screening protocols that inflate per-unit economics.
Strategic Opportunities
- Japan's PMDA biodegradable polymer pathway:Layer-specific testing requirements for resorbable grafts create first-mover advantage for manufacturers with pre-validated polymer platforms.
- Outpatient surgical center expansion:Ambulatory vascular reconstruction in the United States is creating demand for off-the-shelf synthetic conduits with simplified implantation protocols.
- ISO 7198 standard harmonization:Burst strength and suture retention benchmarks are converging across FDA, EMA, and PMDA frameworks, enabling single-validation global launches.
Industry Challenges
- Electrospinning process engineering talent:Sub-micron fiber architecture optimization requires rare combinations of polymer chemistry and biomedical engineering expertise that outpaces graduate pipeline output.
- Sterilization validation timelines:Gamma and ethylene oxide protocol confirmation for novel biodegradable materials extends certification cycles beyond typical investor return horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Graft Market |
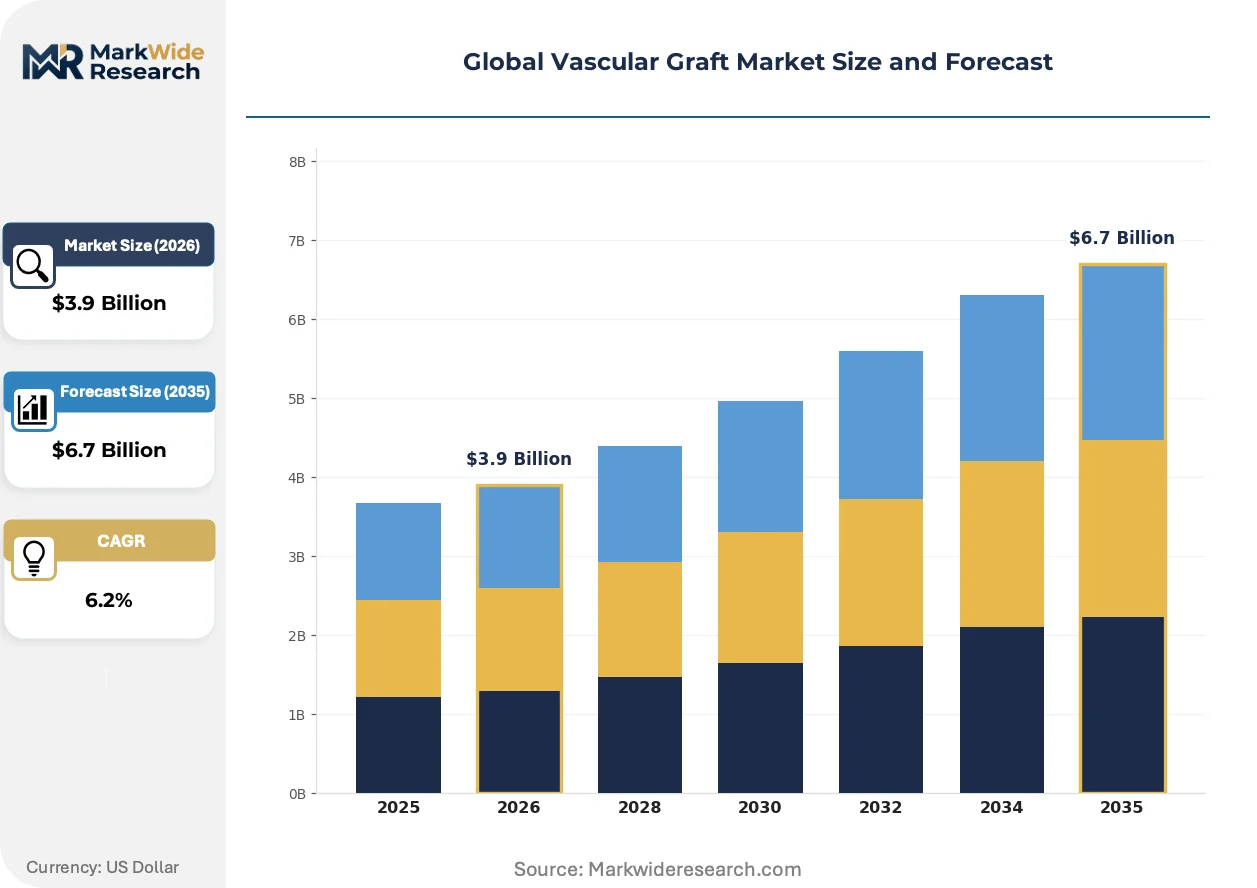
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $6.7 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Grafts, Synthetic Grafts, Biological Grafts, Composite Grafts Application: Peripheral Arterial Disease, Coronary Artery Bypass, Hemodialysis Access, Aortic Aneurysm Repair, Venous Reconstruction End User: Hospitals, Specialized Clinics, Ambulatory Surgical Centers, Vascular Surgery Centers Technology: ePTFE, Dacron, Polyurethane, Biodegradable Polymers, Electrospun Nanofibers |
| Companies Covered | W. L. Gore & Associates, Medtronic, Getinge, LeMaitre Vascular, Terumo Corporation, BD, Abbott, Cook Medical, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Graft Market Shifts & Advancements
Manufacturing technology and regulatory convergence are compressing the validation-to-commercialization cycle for next-generation vascular conduits, while procurement centralization in hospital systems is reshaping how graft suppliers compete on service rather than product alone.
Electrospun nanofiber grafts are decentralizing the production of high-compliance vascular conduits that previously required biological sourcing. Academic medical centers in Germany and Japan are piloting in-house electrospinning capabilities for patient-specific graft geometries. This technology is decentralizing supply chains away from centralized polymer extrusion facilities toward distributed manufacturing nodes with shorter fulfillment cycles.
EMA Medical Device Regulation conformity assessments are tightening biocompatibility documentation requirements for ePTFE and biodegradable polymer substrates. Manufacturers must now submit comprehensive mechanical fatigue data and sterilization validation protocols that exceed prior MEDDEV guidance. Small and mid-sized graft developers in Switzerland and the Netherlands are consolidating regulatory affairs functions to absorb these compliance costs.
Hospital procurement departments are consolidating hemodialysis access graft purchasing through multi-year framework agreements that bundle synthetic conduit supply with implantation training and complication management services. United States hospital systems are favoring suppliers with integrated clinical support teams over catalog-only distributors. This bundling is most visible in Midwestern and Southeastern health networks where dialysis center density supports volume-based contracting.
Global Vascular Graft Market Segmentation
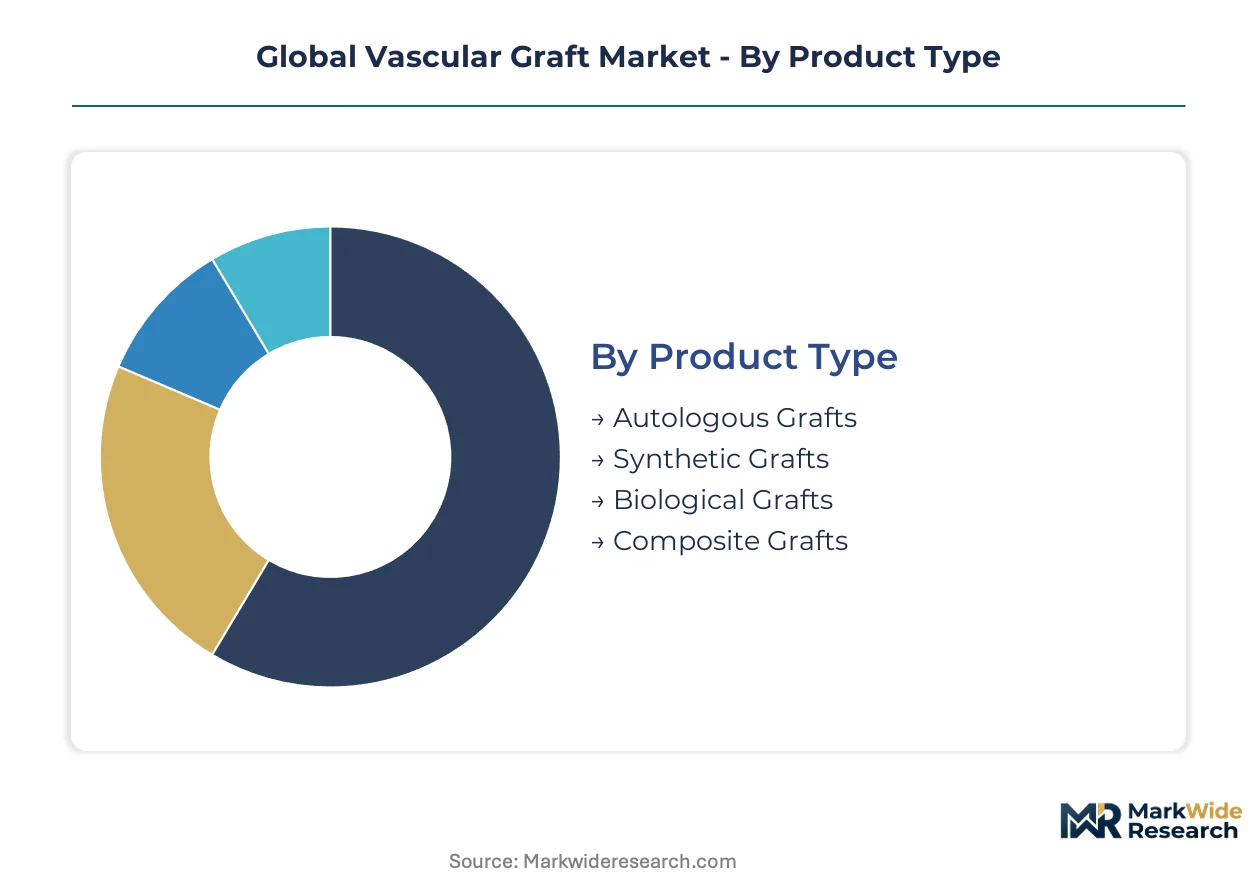
Vascular graft segmentation reveals competing imperatives between established synthetic platforms and emerging resorbable technologies. Procurement patterns diverge sharply across end-use settings, with hospital systems prioritizing standardized inventory while specialized centers pursue patient-specific solutions.
Product Type:
Synthetic grafts dominate hospital procurement volumes, while biological variants command premium pricing in complex reconstructions.
- Synthetic Grafts:Manufactured from ePTFE or Dacron with calibrated 10–60 micron porosity to enable controlled tissue ingrowth. Demand concentrates in United States hospital systems managing high hemodialysis access volumes, where standardized sizing and immediate availability override biological compatibility concerns. Procurement departments favor synthetic lines for their predictable cost structures and established reimbursement pathways.
- Biological Grafts:Derived from autologous vein, allograft, or xenograft tissue with minimal thrombogenicity profiles. Demand clusters in German academic medical centers performing complex aortic reconstructions, where superior compliance and reduced infection risk justify premium economics. Tissue bank availability and serological screening protocols constrain supply scalability.
- Autologous Grafts:Patient-harvested saphenous vein or radial artery segments with optimal biocompatibility.
- Composite Grafts:Hybrid constructions combining synthetic structural cores with biological surface modifications.
Today's leader: Synthetic Grafts. Tomorrow's challenger: Biological Grafts.
Application:
Procedure volume distribution tracks demographic disease burden and reimbursement stability across developed healthcare systems.
- Hemodialysis Access:Arteriovenous graft placement for dialysis-dependent chronic kidney disease patients. Demand concentrates in Japanese tertiary centers, where aging demographics and universal coverage support elective access creation. Hospital procurement frameworks increasingly bundle graft supply with complication management services.
- Peripheral Arterial Disease:Femoropopliteal and infrapopliteal bypass procedures addressing limb ischemia. Demand clusters in United States vascular surgery centers, where diabetes prevalence and endovascular treatment failures drive surgical revascularization volumes. Off-the-shelf synthetic conduits with simplified implantation protocols capture ambulatory procedure growth.
- Coronary Artery Bypass:Saphenous vein or synthetic conduit replacement for occluded coronary vessels.
- Aortic Aneurysm Repair:Open surgical or hybrid endovascular approaches requiring large-diameter conduits.
- Venous Reconstruction:Deep vein bypass or valve replacement procedures for chronic venous insufficiency.
Hemodialysis Access generates current procurement volumes; Peripheral Arterial Disease applications are expanding most quickly as endovascular limitations become apparent.
End User:
Site-of-care migration from inpatient to ambulatory settings is reshaping graft specification requirements and supplier service models.
- Hospitals:Integrated health systems with centralized procurement and inventory management functions.
- Specialized Clinics:Disease-focused facilities concentrating dialysis access or vascular surgery volumes.
- Ambulatory Surgical Centers:United States outpatient facilities performing same-day vascular procedures. Demand concentrates in Southeastern and Midwestern networks where dialysis center density supports volume-based contracting. Simplified implantation protocols and reduced complication profiles drive graft selection criteria.
- Vascular Surgery Centers:Physician-owned facilities with specialized equipment and staffing configurations.
Hospital systems anchor current purchasing power; Ambulatory Surgical Centers represent the steepest expansion trajectory as procedure migration accelerates.
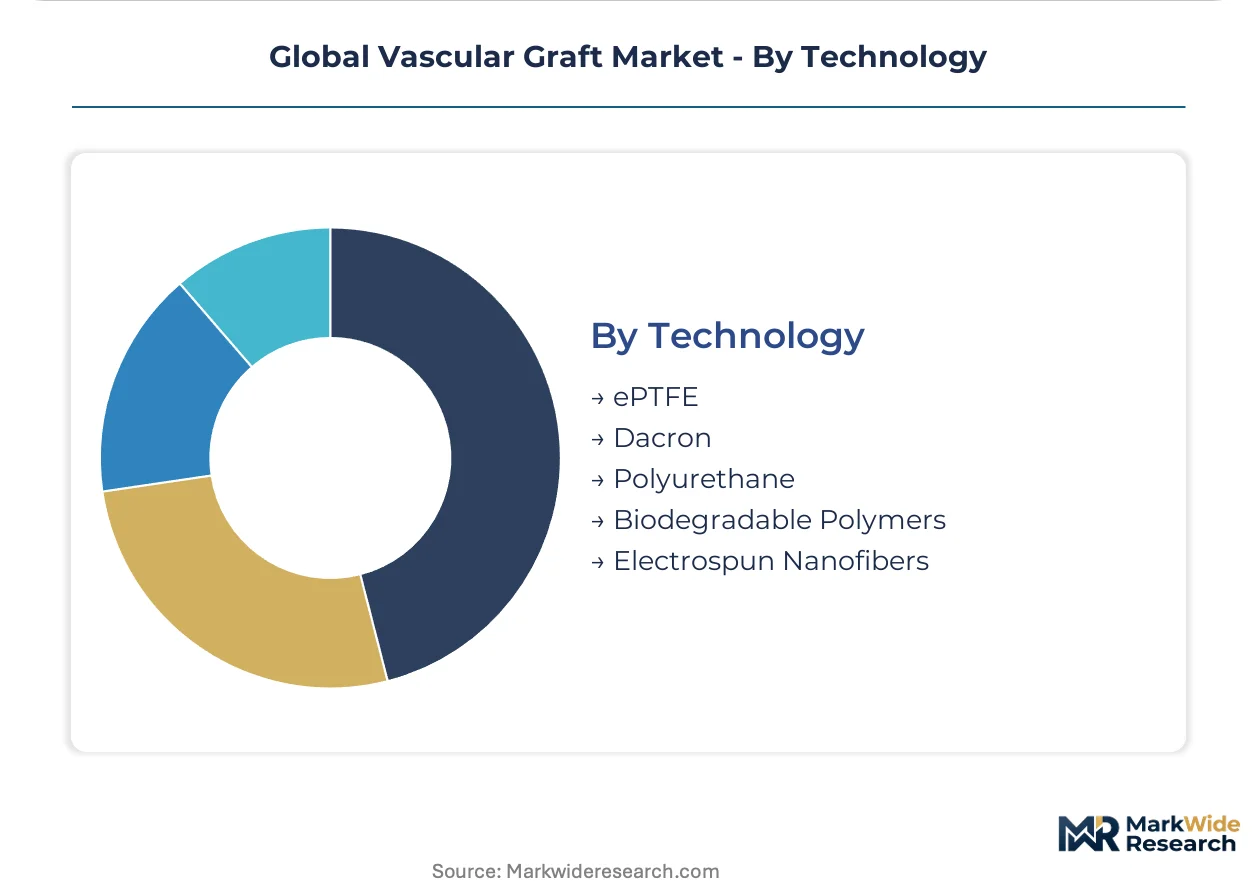
Technology:
Material science differentiation determines performance profiles across compliance, thrombogenicity, and tissue integration dimensions.
- ePTFE:Expanded polytetrafluoroethylene with node-and-fibril microstructure providing chemical inertness and mechanical durability. Demand concentrates in hemodialysis access applications where FDA-validated biocompatibility protocols support standardized clinical adoption. W. L. Gore & Associates technology leadership shapes competitive benchmarks.
- Electrospun Nanofibers:Sub-micron fiber architectures mimicking native vessel compliance and reducing intimal hyperplasia. Demand clusters in German and Japanese academic centers piloting patient-specific graft geometries through distributed manufacturing capabilities. Layer-specific PMDA testing requirements create first-mover advantages for pre-validated platforms.
- Dacron:Woven or knitted polyethylene terephthalate with established performance in large-diameter aortic applications.
- Polyurethane:Segmented elastomeric polymers offering compliance matching in small-diameter configurations.
- Biodegradable Polymers:Resorbable substrates enabling gradual tissue replacement and reduced long-term foreign body response.
ePTFE maintains incumbent position; Electrospun Nanofibers are gaining share fastest as manufacturing scalability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EMA MDR compliance costs in Europe push electrospinning capacity toward jurisdictions with streamlined biocompatibility validation pathways. Production migration follows reimbursement stability and specialized polymer supply clustering rather than labor cost differentials alone.
United States
FDA premarket notification pathways for ePTFE substrates anchor procurement decisions in hospital systems managing high hemodialysis access volumes. The agency's tightened biocompatibility testing protocols filter marginal competitors and reinforce incumbent positions. Minneapolis and Boston medical device corridors concentrate R&D functions for biological and composite graft platforms.
Germany
EMA MDR conformity assessments extend technical documentation timelines for novel biodegradable polymers entering European markets. Academic medical centers in Munich and Heidelberg pilot distributed electrospinning manufacturing for patient-specific graft geometries. Layer-specific testing requirements create consolidation pressure among Swiss and Dutch regulatory affairs functions.
Japan
PMDA layer-specific testing pathways for resorbable grafts attract manufacturers with pre-validated polymer platforms seeking first-mover positioning. Universal coverage and aging demographics support elective access creation volumes in Tokyo and Osaka tertiary centers. Biodegradable polymer supply concentration in specialized European corridors creates import dependency for domestic graft fabricators.
Switzerland
Swissmedic device classification frameworks align with EMA MDR benchmarks while offering specialized pathways for nanofiber-based cardiovascular implants. Basel and Zurich clusters concentrate regulatory expertise serving mid-sized developers absorbing compliance cost inflation. Manufacturing scale advantages in Dacron-based aortic replacements sustain export competitiveness despite domestic market size constraints.
Netherlands
Rotterdam and Eindhoven medical technology corridors host contract sterilization validation services critical for novel biodegradable material certification cycles. Eindhoven's polymer chemistry graduate pipeline feeds electrospinning process engineering demand outpacing regional supply. Hospital procurement centralization through multi-year framework agreements favors suppliers with integrated clinical support teams over catalog-only distributors.
Global Vascular Graft Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with synthetic graft procurement consolidating around technology leaders while biological platforms sustain fragmented premium niches. Market structure tilts toward consolidated supply in standardized ePTFE and Dacron lines, with electrospun nanofiber segments showing emergent specialization. Three archetypes dominate: integrated technology owners controlling substrate intellectual property, manufacturing-scale operators competing on fulfillment reliability, and distributed manufacturing enablers serving patient-specific geometries. Competitive moves concentrate on regulatory pre-validation investments and clinical support service bundling rather than price-based positioning.
Among integrated technology owners, W. L. Gore & Associates occupies a position exemplifying ePTFE substrate leadership, while Medtronic anchors diversified portfolio exposure across biological and synthetic platforms. Getinge represents manufacturing-scale archetypes competing on global distribution reach for established Dacron-based applications. These three entities illustrate how competitive positioning stratifies between substrate control, platform breadth, and fulfillment infrastructure rather than converging on single-dimension dominance.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Medtronic |
| Getinge |
| LeMaitre Vascular |
| Terumo Corporation |
| BD |
| Abbott |
| Cook Medical |
| B. Braun |
| Others |
Supply & Pricing Matrix
EMA MDR biocompatibility documentation requirements for ePTFE and biodegradable polymer substrates gate qualified supply access and premium-tier pricing power for vascular graft manufacturers. Hospital procurement departments in the United States, Germany, and Japan increasingly bundle graft supply with clinical support services, compressing margins for catalog-only distributors while rewarding integrated providers with pricing leverage.
Pricing Analysis
Distributor margins in the United States hospital procurement channel compress pricing power for synthetic graft manufacturers competing on standardized ePTFE lines. Three-tier pricing structure across premium biological, standard synthetic, and economy bare-metal configurations reflects ISO 7198 certification grade and after-sales service bundling. Cost compression in economy synthetic tiers intensifies because of multi-year framework agreement consolidation by Midwestern and Southeastern health networks. Dialysis-dependent patient populations in Japanese tertiary centers demonstrate least price sensitivity, while ambulatory surgical centers in the United States exhibit highest sensitivity to per-unit graft economics.
Supply Chain Analysis
ISO 7198 certification and FDA premarket notification pathways for novel biodegradable polymers concentrate qualified supply among incumbent substrate specialists in the United States, Germany, and Switzerland. Raw material dependencies center on ePTFE resin feedstocks, specialized Dacron yarn production, and resorbable polymer precursors clustered in European chemical corridors. Single-source vulnerability for biodegradable polymer substrates creates supply chain risk as layer-specific PMDA testing requirements extend validation timelines. Distribution runs through hospital procurement departments and group purchasing organizations consolidating hemodialysis access graft purchasing across integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular graft market reads as a late-cycle quality story where hospital procurement consolidation favors suppliers with pre-validated polymer platforms and integrated clinical support teams. Demand is shifting toward electrospun nanofiber grafts with tissue-mimicking compliance profiles that command premium positioning in German and Japanese academic centers.
For Market Incumbents: To counter electrospinning technology disruption from distributed manufacturing pilots in Munich and Heidelberg, W. L. Gore & Associates and Medtronic should deepen backward integration into sub-micron fiber architecture production and accelerate PMDA pre-validation investments for resorbable platforms. Certification investment in ISO 7198 harmonization across FDA, EMA, and PMDA frameworks enables single-validation global launches that freeze out marginal competitors. For New Entrants and Emerging Players: Japan's PMDA layer-specific testing pathway for biodegradable polymer grafts opens a window for specialized nanofiber developers with pre-validated platforms to capture first-mover positioning in Tokyo and Osaka tertiary centers. Target ambulatory surgical center expansion in Southeastern United States networks where simplified implantation protocols and reduced complication profiles drive graft selection criteria. Go-to-market through hospital system partnership models bundling supply with implantation training and complication management services. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized electrospinning specialists because EMA MDR compliance costs are forcing consolidation among Swiss and Dutch regulatory affairs functions while patient-specific manufacturing demand fragments production scale requirements. Long-term viability hinges on acquiring platforms with validated sub-micron fiber architectures and established PMDA submission pathways. Watch for sterilization validation timeline compression as the inflection signal indicating manufacturing scalability breakthrough for biodegradable polymer substrates.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Pre-Validation Investment | Layer-specific testing requirements in Japan create first-mover advantage for resorbable graft platforms with validated polymer chemistry. |
| Hospital System Partnership | Midwestern and Southeastern United States networks favor suppliers bundling graft supply with implantation training and complication management. |
| Electrospinning Capacity Expansion | Distributed manufacturing nodes in Germany and Japan shorten fulfillment cycles for patient-specific graft geometries. |
| ISO 7198 Harmonization Program | Converging burst strength and suture retention benchmarks across FDA, EMA, and PMDA frameworks enable single-validation global launches. |
| Biodegradable Polymer Supply Agreement | Long-term offtake contracts with specialized European chemical corridors reduce single-source vulnerability for resorbable substrate production. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down electrospinning capacity tracking forms the analytical core of this vascular graft market assessment. Primary interviews with vascular surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation databases, PMDA submission records, and hospital procurement contract registries. Triangulation between demand-side procedure volume analysis and supply-side manufacturing footprint mapping ensures segmentation integrity across synthetic, biological, and composite graft categories.
Historical trendline analysis of hemodialysis access procedure volumes, chronic kidney disease prevalence trajectories, and endovascular treatment failure rates anchors the forecast framework. Segmentation modeling spans product type, application, end user, and technology dimensions with particular attention to electrospun nanofiber adoption curves and biodegradable polymer regulatory pathway progression. CAGRs derive from fitted growth curves calibrated against reimbursement stability indicators and procurement centralization trends across the projection horizon. Industry-specific inputs include dialysis center density metrics, ambulatory surgical center expansion rates, and layer-specific testing timeline assumptions for novel resorbable substrates.
Revisions become necessary when EMA MDR technical documentation demands intensify beyond current MEDDEV guidance, PMDA layer-specific testing protocols shift for biodegradable polymers, or hospital procurement framework agreement structures alter service bundling requirements. Forecasts reflect assumptions about regulatory timeline stability, sterilization validation cycle duration, and electrospinning process engineering talent pipeline adequacy. A model refresh is warranted upon material change in hemodialysis access reimbursement thresholds or electrospun nanofiber manufacturing scalability breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Vena Cava Clips and Filters Market