
 PDA Closure Devices Market | 2026-2036
PDA Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
PDA Closure Devices Market Analytics
Aftermarket service revenue is narrowing as manufacturers bundle follow-up imaging and device surveillance into initial procurement contracts. Abbott Laboratories leverages its electrophysiology infrastructure to control cath-lab workflow integration. Boston Scientific Corporation anchors North American hospital purchasing through dedicated pediatric interventional specialists. Medtronic plc competes in emerging markets with scaled manufacturing of nickel-titanium occluder alloys.
PDA closure devices are implantable cardiovascular instruments, typically constructed from nitinol wire mesh with polyester fabric patches, designed to mechanically occlude the patent ductus arteriosus through transcatheter or surgical delivery. These devices restore normal cardiac blood flow patterns in neonatal and pediatric patients, eliminating left-to-right shunting that strains pulmonary circulation. Septal occluders dominate procedural volumes in catheterization labs, while coil occluders retain share in low-weight infant cases where device profile constraints govern selection. Transcatheter technology leads growth trajectories as imaging guidance systems advance fluoroscopic precision during deployment.
FDA PMA requirements govern commercial entry for novel occluder designs in the United States, while the EU MDR transition demands renewed clinical evidence for CE-marked legacy devices. Health Canada and TGA align with ISO 10993 biocompatibility standards for permanent implant materials. Stakeholders must monitor reimbursement coding shifts for pediatric catheterization procedures and anticipate how real-world evidence mandates will reshape post-market surveillance obligations.
Market Dynamics
Transcatheter occluder deployment protocols are consolidating cath-lab workflows around fluoroscopy-integrated delivery systems, compressing procedural training cycles and reshaping capital equipment procurement priorities across pediatric cardiology networks.
Growth Catalysts
- EU MDR transition timelines:Renewed clinical evidence requirements for legacy CE-marked devices are accelerating hospital upgrades to next-generation occluder platforms with enhanced biocompatibility documentation.
- Nitinol wire mesh manufacturing:Advances in shape-memory alloy processing are enabling lower-profile device designs suitable for premature infant populations previously excluded from transcatheter intervention.
- University hospital pediatric cardiology programs:Academic medical centers in Germany, the United States, and China are standardizing fellowship training around catheter-based closure techniques, expanding the qualified operator pool.
Market Restraints
- Nickel-titanium alloy supply concentration:Specialized nitinol feedstock production clusters in a limited set of metallurgical facilities create input cost volatility and single-source vulnerability for occluder manufacturers.
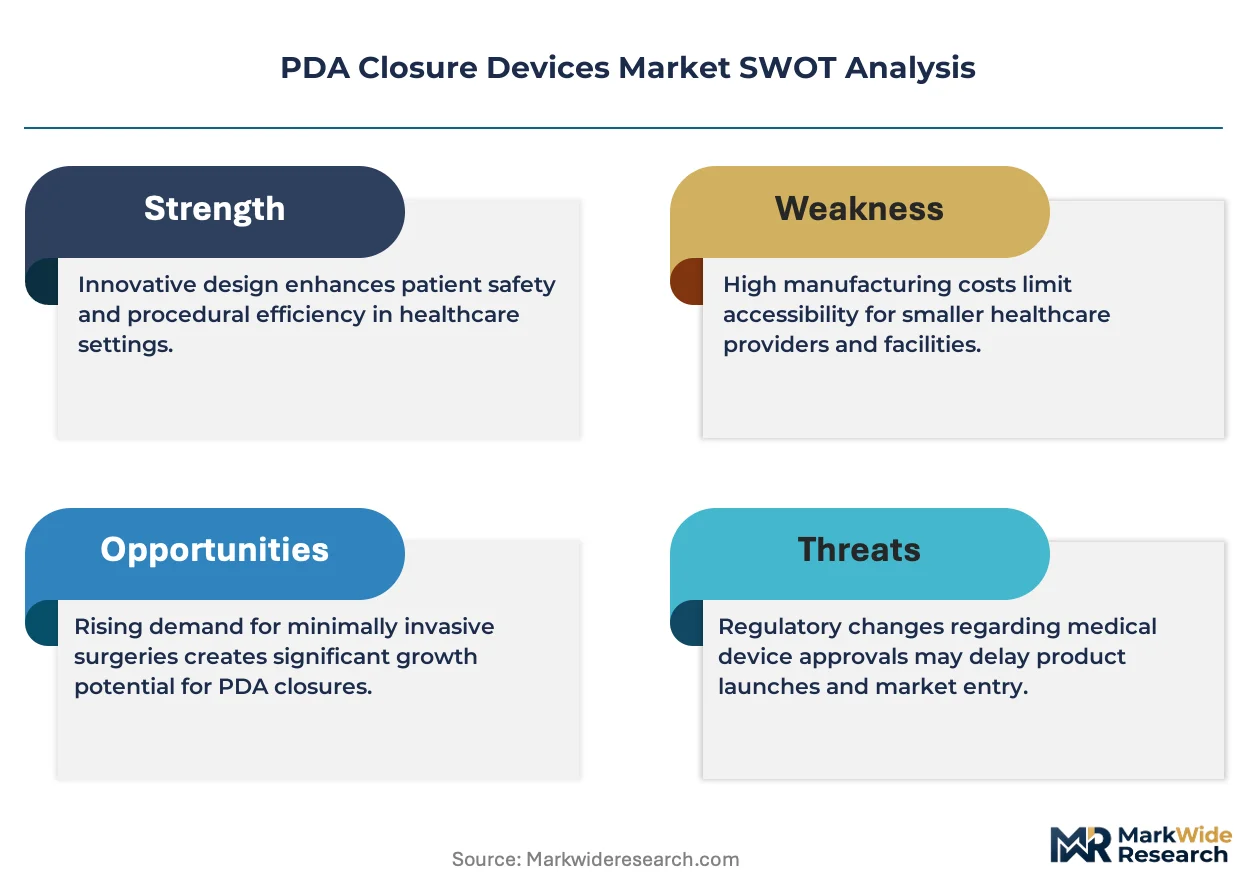
- FDA PMA pathway duration:Premarket approval requirements for novel occluder designs impose extended clinical trial obligations and regulatory friction that delay commercial entry for innovative device geometries.
- Surgical ligation persistence:Open surgical closure remains the fallback standard in low-birth-weight neonates where transcatheter device profiles exceed anatomical constraints, limiting addressable procedural expansion.
Strategic Opportunities
- Real-world evidence mandates:Post-market surveillance obligations under FDA and Health Canada frameworks create demand for integrated device tracking platforms that manufacturers can monetize as subscription services.
- Hybrid OR-cath lab convergence:Surgical backup capabilities in interventional suites enable same-setting conversion protocols, opening procedural categories previously reserved for standalone surgical centers.
- India and Southeast Asia pediatric cardiac networks:Underpenetrated interventional cardiology infrastructure in these regions presents white-space expansion for scaled manufacturing of cost-optimized coil occluder systems.
Industry Challenges
- Pediatric interventional cardiologist training pipelines:The specialized skill set combining neonatal hemodynamic management with fluoroscopic navigation faces constrained fellowship placement capacity, creating qualified operator scarcity.
- ISO 10993 biocompatibility certification timelines:Permanent implant material testing protocols for novel polymer coatings or modified nitinol compositions extend product development cycles and compress competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PDA Closure Devices Market |
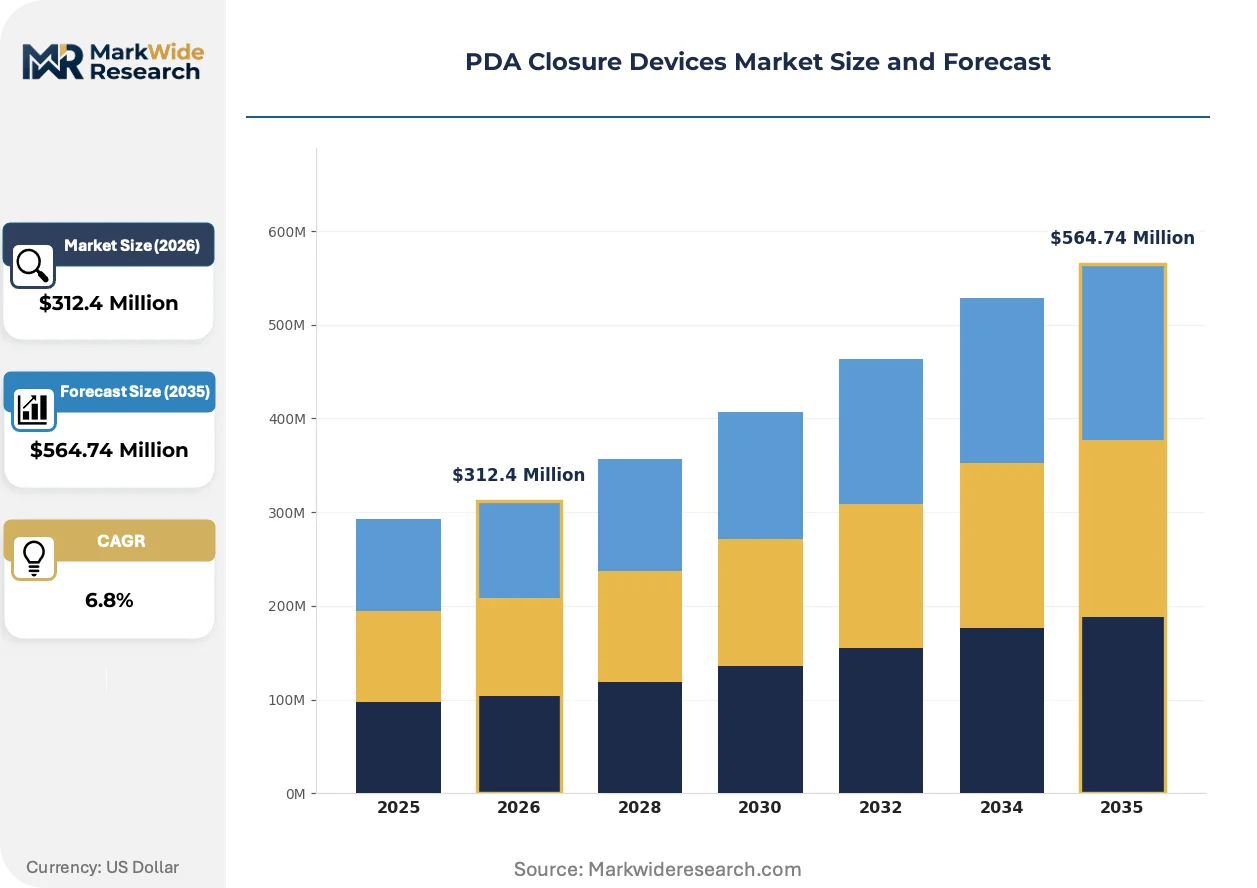
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Septal Occluders, Coil Occluders, Plug Occluders, Others Application: Pediatrics, Adults, Clinical Trials, Surgical Procedures End User: Hospitals, Cardiology Clinics, Research Institutes, Outpatient Centers Technology: Transcatheter, Open-Heart Surgery, Imaging Guidance, Others |
| Companies Covered | W. L. Gore & Associates, Inc., LifeTech Scientific Corporation, Abbott Laboratories, Lepu Medical, MicroPort Scientific Corporation, Boston Scientific Corporation, Occlutech International AB, Cardia, Inc., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PDA Closure Devices Market Evolving Landscape
Device miniaturization and imaging integration are converging to enable intervention in patient populations previously excluded from transcatheter approaches, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for permanent implants.
Self-expanding nitinol occluders with integrated echocardiographic markers are rendering obsolete conventional fluoroscopy-dependent deployment protocols that required extensive radiation exposure and prolonged procedure times. Pediatric catheterization labs at academic medical centers are adopting these platforms within eighteen-month equipment refresh cycles. The structural consequence is compression of the learning curve for new operators and reduced dependence on surgical backup.
EU MDR Article 52 clinical evaluation requirements are forcing systematic re-evaluation of legacy occluder designs that received CE marking under the prior Medical Device Directive. Manufacturers must generate new post-market clinical follow-up data or withdraw products from European distribution. High-volume septal occluder portfolios face the most acute compliance pressure, with several firms prioritizing MDR technical documentation over new product development.
Hospital purchasing committees are unbundling device procurement from historical vendor-tied imaging service contracts, creating direct price competition between Abbott Laboratories, Boston Scientific Corporation, and Medtronic plc at the point of cath-lab specification. Independent distributors in Germany and China are capturing margin previously retained by manufacturer direct sales forces. This disintermediation is most visible in mid-tier community hospitals without dedicated pediatric interventional specialists, where procurement autonomy has shifted from physician preference to supply chain centralized purchasing.
PDA Closure Devices Market Segmentation
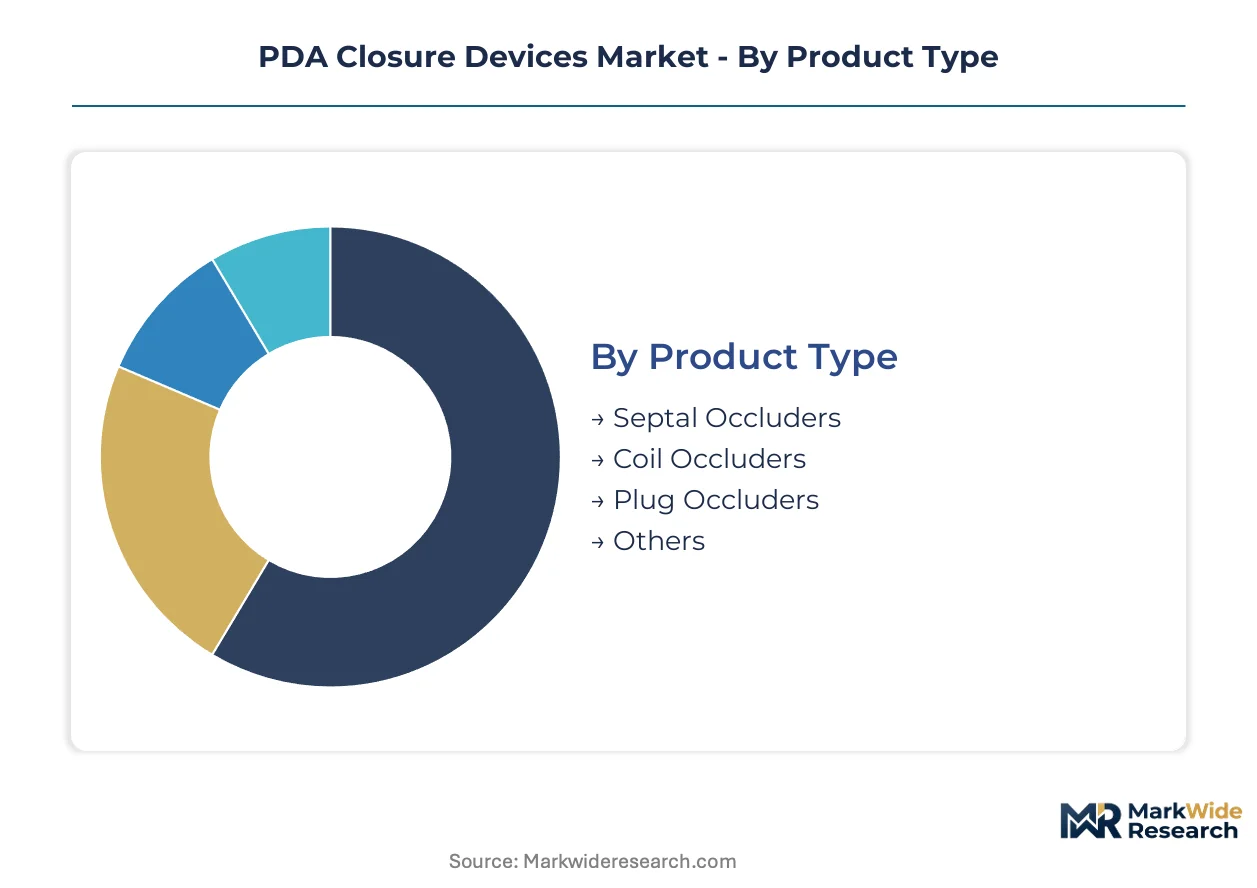
Device segmentation in the PDA closure market maps directly to patient physiology, procedural setting, and regulatory pathway complexity. Each dimension carries distinct reimbursement codes, operator training requirements, and supply chain configurations that shape procurement decisions.
Product Type:
Mature nitinol platforms dominate procedural economics, while emerging geometries target previously excluded patient populations.
- Septal Occluders:Self-expanding nitinol wire mesh discs with polyester fabric patches occlude ductal tissue through radial force apposition. University hospital catheterization labs in Germany and the United States concentrate demand for these platforms as fellowship training standardizes around fluoroscopy-integrated deployment protocols.
- Coil Occluders:Helical stainless steel or platinum-tungsten configurations with synthetic fiber thrombogenicity enhancement occupy the low-birth-weight neonate segment where device profile constraints exclude disc-based alternatives. China's pediatric cardiac networks drive volume for scaled manufacturing of cost-optimized coil systems.
- Plug Occluders:Cylindrical nitinol constructs with retention skirts address irregular ductal morphologies.
- Others:Experimental biodegradable polymer scaffolds and hybrid surgical-transcatheter instruments.
Septal occluders handle the majority of throughput; coil occluders are expanding most quickly in premature infant indications.
Application:
Patient age stratification determines device sizing protocols, anesthesia requirements, and post-procedural monitoring intensity.
- Pediatrics:Neonatal and infant populations require sub-6mm device profiles compatible with 4-French vascular access. Pediatric interventional cardiologist scarcity constrains procedural expansion despite favorable hemodynamic outcomes.
- Adults:Persistent ductal shunts in adult congenital heart disease patients demand larger device footprints and extended antiplatelet regimens. German and United States academic centers capture this volume through specialized adult congenital programs.
- Clinical Trials:Investigational device exemption protocols for novel occluder geometries.
- Surgical Procedures:Open ligation fallback for anatomically complex cases.
Pediatrics commands the installed base; adults are climbing the fastest on procedural share as diagnostic sophistication improves.
End User:
Facility type dictates capital equipment requirements, case volume thresholds, and vendor contracting leverage.
- Hospitals:Tertiary pediatric cardiac centers with hybrid OR-cath lab convergence capabilities perform complex closures with surgical backup. FDA PMA pathway experience and MDR technical documentation proficiency concentrate at these institutions.
- Cardiology Clinics:Ambulatory settings with echocardiography-integrated fluoroscopy systems handle stable adolescent and adult cases. India's emerging pediatric cardiac networks favor this model for cost containment.
- Research Institutes:Academic medical centers generating real-world evidence for post-market surveillance mandates.
- Outpatient Centers:Standalone facilities with limited surgical backup capacity.
Hospitals absorb the dominant share of high-acuity procedures; cardiology clinics are gaining share fastest in stable patient segments.
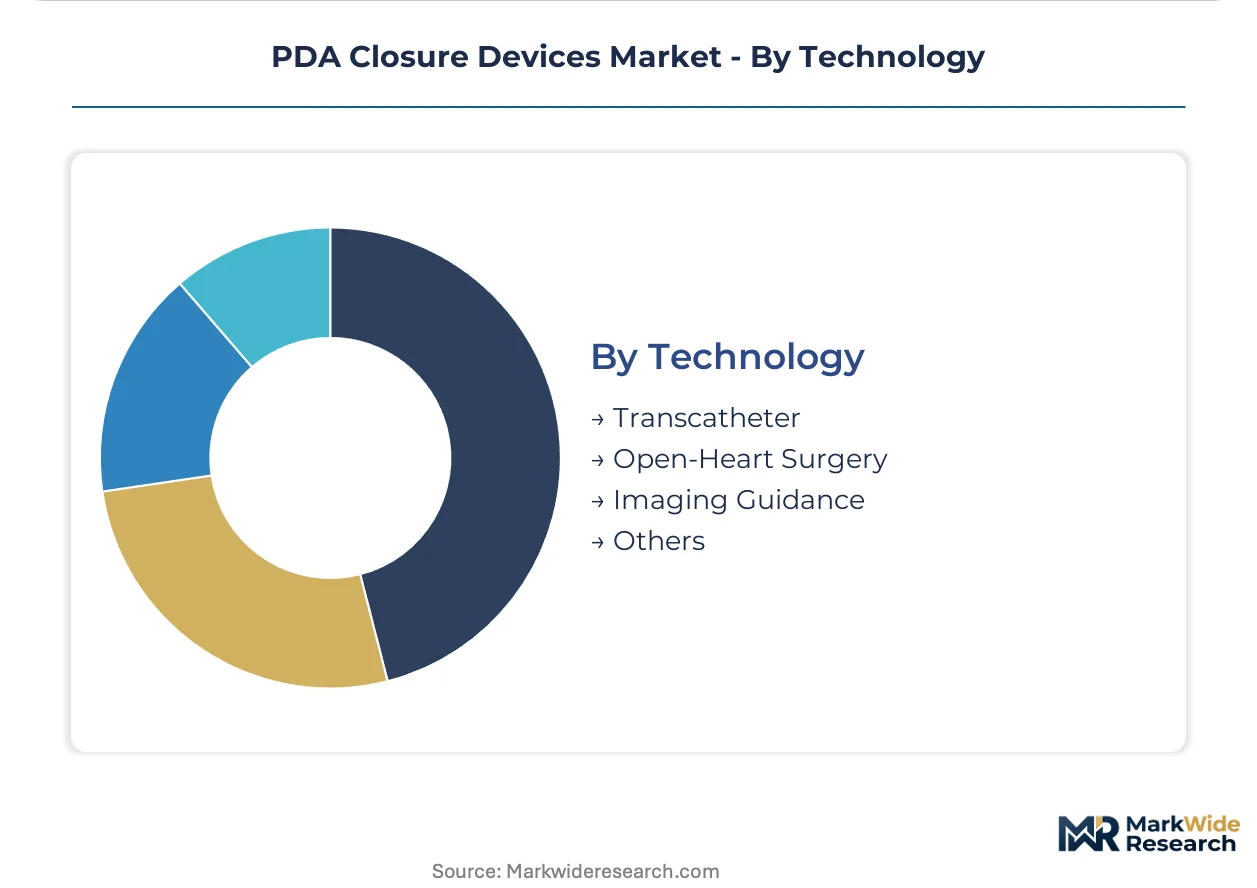
Technology:
Delivery modality selection hinges on anatomical suitability, operator training, and institutional surgical backup availability.
- Transcatheter:Percutaneous femoral venous access with fluoroscopic and echocardiographic guidance enables same-day discharge for appropriate candidates. University hospital standardization of fellowship curricula accelerates qualified operator supply.
- Open-Heart Surgery:Median sternotomy or lateral thoracotomy ligation persists for premature infants below 2kg and anatomically atypical ductal morphologies. German surgical centers maintain proficiency as fallback referral destinations.
- Imaging Guidance:Integrated three-dimensional rotational angiography and intracardiac echocardiography reduce radiation exposure and contrast load.
- Others:Hybrid approaches combining surgical access with device deployment.
Transcatheter technology anchors procedural volume; imaging guidance integration is advancing fastest on adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany favors septal occluders with MDR-compliant documentation, whereas China's pediatric networks prioritize cost-optimized coil systems for premature infants. The United States concentrates transcatheter volume in academic medical centers with hybrid OR capabilities.
United States
University hospital pediatric cardiology programs in Boston and Philadelphia drive transcatheter occluder adoption through standardized fellowship curricula. FDA PMA pathways impose extended clinical trial obligations for novel device geometries. The Texas Medical Center in Houston anchors high-volume procedural networks with integrated cath-lab and surgical backup infrastructure.
Germany
Academic medical centers in Munich and Heidelberg standardize training around fluoroscopy-integrated deployment protocols for septal occluders. EU MDR Article 52 clinical evaluation requirements force systematic re-evaluation of legacy CE-marked devices. The Berlin-Brandenburg cluster concentrates MDR technical documentation expertise and post-market surveillance capabilities.
China
Pediatric cardiac networks in Shanghai and Beijing drive volume for scaled manufacturing of low-profile coil occluders suitable for premature infants. NMPA registration pathways align with ISO 10993 biocompatibility standards for permanent implant materials. The Yangtze River Delta region hosts concentrated nitinol wire mesh processing facilities serving domestic and export markets.
India
Emerging pediatric interventional cardiology infrastructure in Delhi and Mumbai favors ambulatory cardiology clinic models for cost containment. CDSCO medical device regulations govern commercial entry for imported and domestically manufactured occluders. The Karnataka cluster in Bangalore develops echocardiography-integrated fluoroscopy systems for resource-constrained settings.
Japan
Adult congenital heart disease programs in Tokyo and Osaka generate demand for larger-device-footprint occluders with extended antiplatelet protocols. PMDA premarket approval requirements emphasize clinical evidence from domestic patient populations. The Kansai region maintains surgical ligation proficiency as fallback referral destinations for anatomically complex cases.
PDA Closure Devices Market Competitive Landscape
Capability concentration sits with specialized nitinol processing specialists; scale advantage sits with diversified cardiovascular device conglomerates. The vendor base separates into three tiers: integrated multinationals with electrophysiology infrastructure, mid-scale regional manufacturers with metallurgical expertise, and emerging Asian fabricators with cost-optimized coil production. Dominant competitive moves include M&A to secure nitinol feedstock supply and strategic partnerships to integrate real-world evidence tracking platforms.
Among diversified cardiovascular device conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify the integrated multinational archetype with cath-lab workflow control capabilities. Medtronic plc anchors the scale-driven tier with nickel-titanium alloy manufacturing breadth. Chinese specialists Lepu Medical and MicroPort Scientific Corporation occupy positions within the cost-optimized manufacturing tier serving Asia-Pacific pediatric networks.
| Leading Market Players |
|---|
| W. L. Gore & Associates, Inc. |
| LifeTech Scientific Corporation |
| Abbott Laboratories |
| Lepu Medical |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Occlutech International AB |
| Cardia, Inc. |
| Medtronic plc |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's concentrated nitinol wire mesh processing capacity grants Chinese fabricators substantial leverage over global coil occluder pricing, while German and United States manufacturers defend septal occluder premiums through MDR-compliant documentation and integrated cath-lab service bundling.
Pricing Analysis
Long-term offtake agreements between university hospital purchasing consortia and diversified cardiovascular device conglomerates dominate the United States and Germany, compressing spot-market exposure for premium septal occluder platforms. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified nitinol discs from legacy CE-marked inventory and cost-optimized coil systems manufactured for India's emerging pediatric networks. Cost compression in the economy tier is intensifying because Chinese fabricators are scaling output of platinum-tungsten coil configurations for Southeast Asian procurement committees. Community hospitals without dedicated pediatric interventional specialists exhibit the highest price sensitivity, whereas academic medical centers with hybrid OR-cath lab convergence prioritize device-integrated imaging workflows over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for nitinol feedstock procurement, compelling manufacturers to qualify secondary metallurgical sources in Germany and Japan. Specialized nitinol alloy production clusters in the Yangtze River Delta, Bavaria, and Osaka Prefecture supply shape-memory wire to occluder fabricators across three continents. Device assembly draws from polyester fabric patch suppliers in South Korea, platinum-tungsten coil vendors in Switzerland, and echocardiographic marker integrators in Massachusetts. Single-source vulnerability in sub-6mm device profile manufacturing for premature infant indications constrains supply flexibility. Distribution runs through manufacturer direct sales forces for tertiary pediatric cardiac centers, while independent distributors capture margin in mid-tier German community hospitals and China's provincial hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as cath-lab workflow integration and real-world evidence tracking platforms reshape competitive boundaries around interoperability rather than standalone device performance.
For Market Incumbents: Pre-empt emerging Asian fabricators by securing captive supply of medical-grade nitinol feedstock through backward integration into Yangtze River Delta metallurgical facilities or long-term offtake agreements with German alloy specialists. Accelerate software companion development for device tracking platforms that satisfy FDA and Health Canada post-market surveillance mandates, converting regulatory compliance burden into recurring subscription revenue before mid-scale competitors achieve technical documentation parity.
For New Entrants and Emerging Players: Build out echocardiography-integrated fluoroscopy system partnerships with India's Karnataka cluster to serve Delhi and Mumbai ambulatory cardiology clinics with cost-containment procurement priorities. Target the low-birth-weight neonate segment where device profile constraints exclude established septal occluder platforms and coil occluder demand concentrates in China's pediatric cardiac networks. Pursue CDSCO registration pathways for domestically manufactured coil systems that undercut imported nitinol disc pricing by eliminating currency exposure and tariff layers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming cardiovascular device divisions lacking electrophysiology infrastructure integration. The five-to-ten-year viability window favors manufacturers with demonstrated MDR technical documentation proficiency and established real-world evidence collection capabilities. Acquisition candidates displaying ISO 10993 biocompatibility certification breadth and pediatric interventional cardiologist training program sponsorships warrant priority evaluation. Monitor NMPA registration velocity for domestic Chinese fabricators as the inflection indicator for when cost-optimized manufacturing achieves quality parity with Western nitinol processing standards.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EU MDR Article 52 compliance preserves European market access for legacy septal occluder portfolios. |
| Real-World Evidence Platform Development | Integrated device tracking satisfies FDA post-market surveillance mandates and generates recurring subscription revenue. |
| Nitinol Feedstock Supply Security | Backward integration into Yangtze River Delta or Bavarian metallurgical facilities mitigates single-source vulnerability. |
| Hybrid OR-Cath Lab Partnership | Surgical backup capabilities in interventional suites enable same-setting conversion protocols previously reserved for standalone surgical centers. |
| Pediatric Interventional Fellowship Sponsorship | Standardized training curricula at Munich and Boston academic centers expand qualified operator supply and embed device preference. |
Research Methodology
A standing panel of pediatric interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles, with secondary validation drawing from FDA PMA filings, NMPA registration databases, EU MDR technical documentation repositories, and hospital procurement contract disclosures. Bottom-up triangulation of device shipment volumes by product type and application combined with top-down reconciliation against tertiary pediatric cardiac center procedural throughput estimates established market sizing boundaries.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning device geometry, patient age stratification, facility type, and delivery modality. CAGRs derived from fitted growth curves applied to procedural volume trajectories modeled under varying assumptions for pediatric interventional cardiologist fellowship placement capacity and EU MDR compliance timelines. Industry-specific forecast inputs incorporated nitinol alloy price volatility indices and reimbursement coding shifts for pediatric catheterization procedures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported fabricators or unexpected FDA PMA pathway accelerations for novel occluder geometries would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UAE Respiratory Devices Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Coil Assisted Flow Diverters Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market