
 Interventional ENT Devices Market | 2026-2036
Interventional ENT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional ENT Devices Market Analytics
The interventional ENT devices category is pivoting between premium robotic-assisted platforms and commoditized balloon dilation kits. Medtronic leverages integrated navigation and powered instrumentation to sustain premium positioning across sinus surgery suites. Stryker anchors its presence through dedicated ENT visualization stacks that compete on optical clarity and workflow integration. Olympus Corporation dominates flexible endoscope supply for otology applications, extending its installed base through reprocessing economics.
Interventional ENT devices encompass minimally invasive instruments, implants, and energy systems designed to access, visualize, and treat pathologies of the ear, nose, and throat through natural orifices or small incisions, typically employing biocompatible polymers, nitinol actuation, or solid-state laser diodes operating at specific wavelengths for tissue ablation or dilation. These devices serve otolaryngologists and neurotologists in restoring airway patency, conductive hearing, or vocal function while reducing procedural morbidity relative to open surgical approaches. Balloon sinus dilation occupies the largest revenue pool among product types due to broad ambulatory eligibility and favorable reimbursement, while robotic surgery represents the fastest-expanding technology segment as systems gain 510(k) clearances for transoral and transnasal indications. Endoscopic platforms maintain mature, high-margin aftermarket streams through instrument turnover and service contracts.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development cycles and market access timelines for interventional ENT devices, with notified bodies scrutinizing biocompatibility and electromagnetic compatibility under tightened post-market surveillance obligations. ISO 13485 quality management systems and IEC 60601 electrical safety standards form baseline compliance infrastructure for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving FDA guidance on software-enabled devices and EU AI Act applicability to surgical planning algorithms embedded in navigation platforms.
Market Dynamics
Balloon sinus dilation is converging with ambulatory surgical center workflows, compressing hospital outpatient volumes while FDA 510(k) pathways accelerate commoditization of once-premium instruments.
Growth Catalysts
- Ambulatory Migration:ASCs in the United States now perform the majority of balloon sinus dilation procedures, driven by site-of-service payment differentials and same-day discharge protocols.
- EU MDR Streamlining:Consolidated technical documentation requirements for Class IIa ENT devices are reducing notified body review timelines for manufacturers with established quality management systems.
- Nitinol Actuation:Superelastic nickel-titanium alloys enable single-use dilators with predictable radial force profiles, replacing reusable mechanical instruments in Japan and Germany.
Market Restraints
- Reimbursement Compression:CMS facility fee reductions for sinus dilation in hospital outpatient settings are squeezing margins on capital equipment placements.
- Optics Supply Concentration:CCD and CMOS sensor fabrication for ENT endoscopes concentrates in Taiwanese and South Korean foundries, creating vulnerability to geopolitical disruption.
- Technical Ceiling:Current flexible endoscope articulation mechanics limit access to anterior ethmoid air cells, constraining indication expansion beyond sphenoid and maxillary targets.
Strategic Opportunities
- India ASC Buildout:Private hospital chains in Mumbai and Delhi are deploying dedicated ENT day-surgery units, creating first-mover advantage for balloon dilation kit suppliers.
- AI Navigation Convergence:Preoperative CT segmentation algorithms are integrating with electromagnetic tracking to reduce fluoroscopy exposure in complex revision cases.
- Direct-to-Physician Distribution:Manufacturers are bypassing distributor networks for high-velocity consumables, capturing margin through e-procurement platforms serving US otolaryngology practices.
Industry Challenges
- Reprocessing Validation:Automated endoscope reprocessors require cycle validation for each flexible scope model, extending service engineer deployment timelines.
- Electromagnetic Compatibility Testing:Navigation platforms must demonstrate coexistence with MRI suites and cardiac pacemakers, lengthening IEC 60601-1-2 certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional ENT Devices Market |
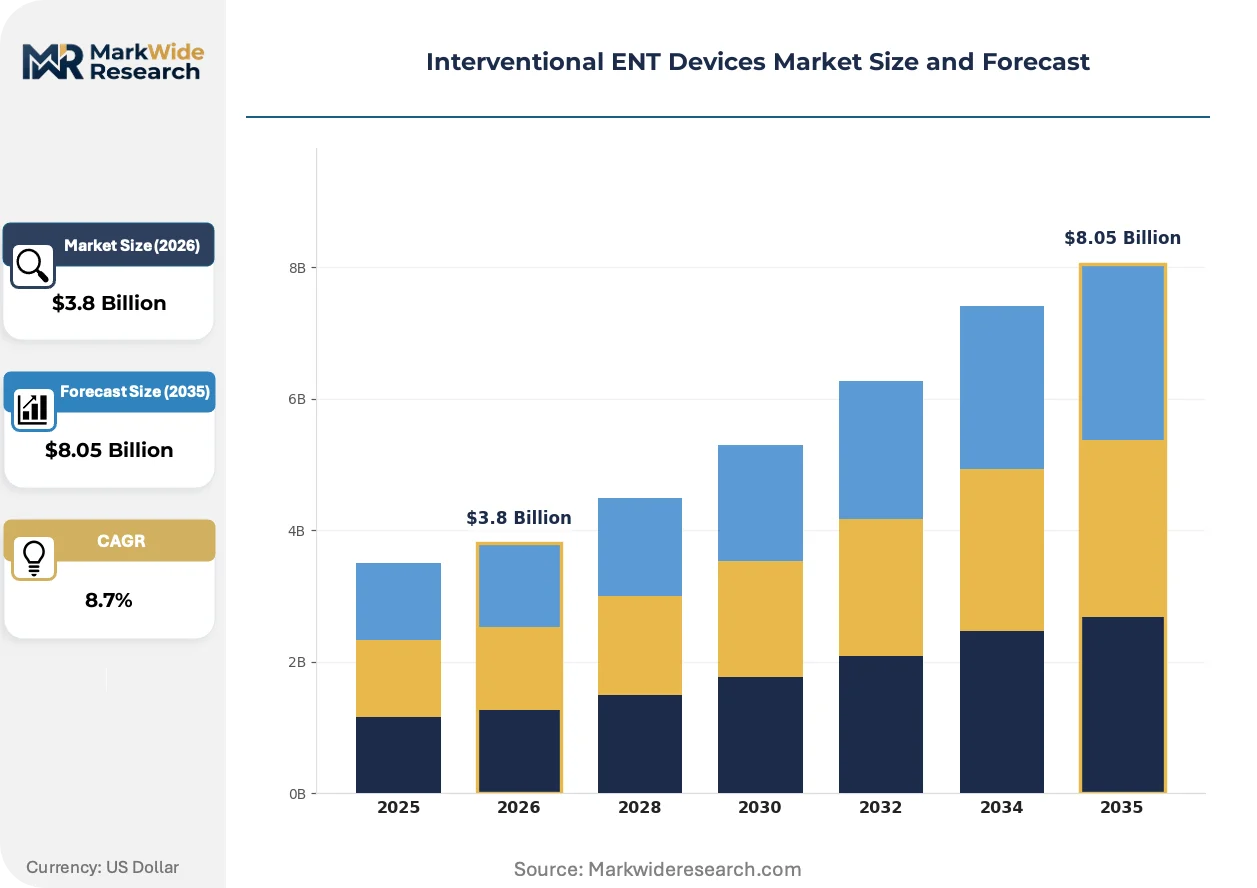
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Sinus Dilation, Ear Tubes, Nasal Splints, Laser Systems Application: Sinus Surgery, Cochlear Implants, Snoring Treatment, Otitis Media End User: Hospitals, Outpatient Clinics, Surgical Centers, Diagnostic Laboratories Technology: Minimally Invasive, Endoscopic, Robotic Surgery, Telemedicine |
| Companies Covered | Medtronic, Stryker, Olympus Corporation, Johnson & Johnson Services, Inc., Smith & Nephew, Karl Storz, Richard Wolf GmbH, Acclarent, Inc., PENTAX Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional ENT Devices Market Evolving Landscape
Digital surgical planning is displacing conventional anatomical landmark recognition, while single-use instrument economics restructure capital-versus-consumable trade-offs across procurement functions.
Optical coherence tomography is converging with conventional endoscopic visualization to enable subsurface tissue characterization during laryngeal lesion assessment. Otolaryngology departments at academic medical centers in the United States are piloting integrated OCT-video stacks for intraoperative margin determination. This convergence is compressing the diagnostic pathway by reducing dependency on frozen section pathology.
EU MDR post-market surveillance obligations now mandate systematic literature reviews and PMCF studies for legacy ENT implants, forcing manufacturers to rebuild clinical evidence portfolios. Notified bodies in Germany and the Netherlands are applying heightened scrutiny to biocompatibility testing protocols for permanent implants. Class IIa device holders are responding by consolidating product families to streamline technical documentation.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, demanding itemized pricing for preventive maintenance and software updates. This behavioral shift is most pronounced in German Krankenhaus procurement and US IDN supply chain functions. Manufacturers are countering with subscription-based instrument replacement programs that obscure total cost of ownership.
Interventional ENT Devices Market Segmentation
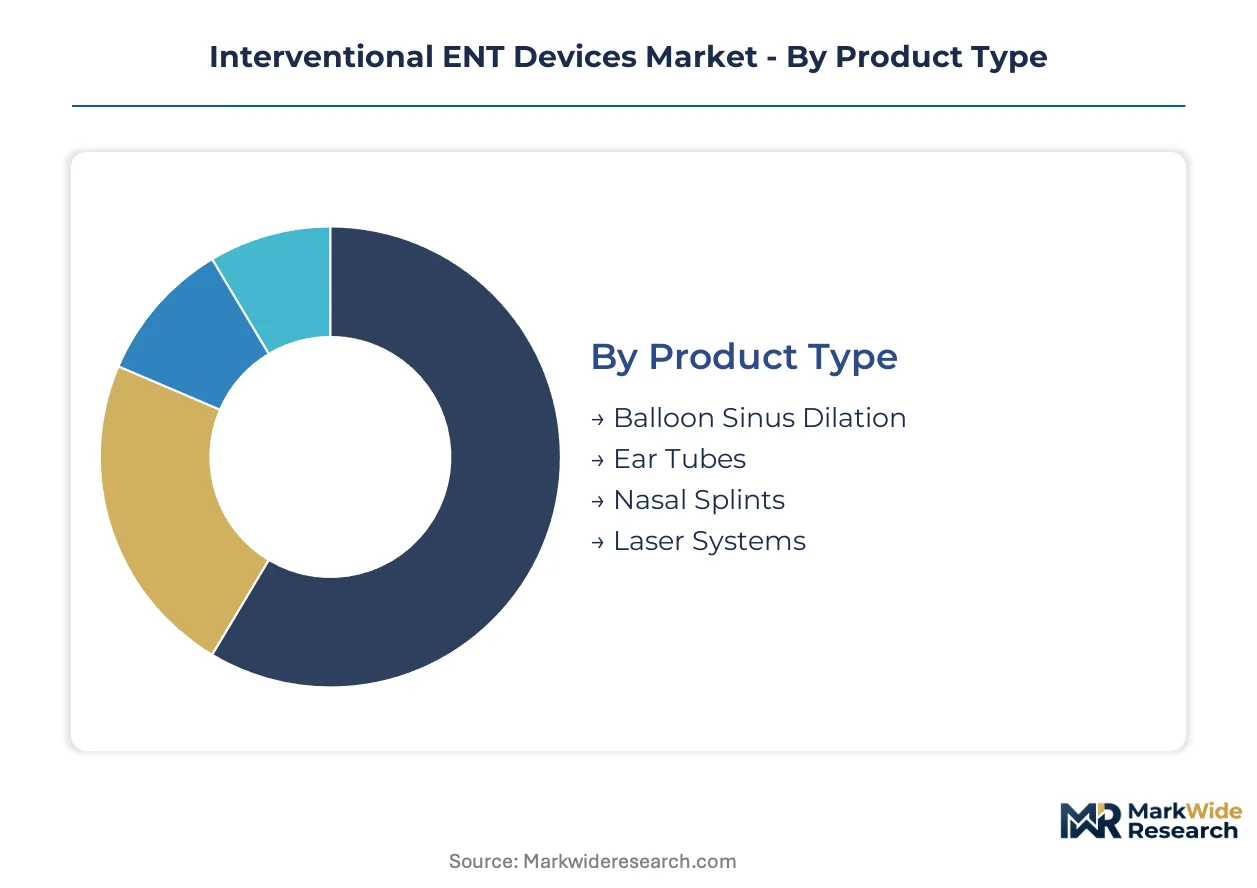
Interventional ENT devices fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and technology adoption curves. Product type classifications govern capital intensity and consumable turnover rates. Application segmentation aligns with anatomical complexity and payer category. End-user categories reflect site-of-service economics reshaping volume distribution. Technology tiers separate established workflows from emerging platforms requiring infrastructure investment.
Product Type:
Procurement committees distinguish between capital equipment with depreciation schedules and high-velocity consumables with predictable reorder cadence.
- Balloon Sinus Dilation:Single-use catheters employing superelastic nitinol deliver controlled radial force for maxillary and sphenoid ostial dilation. Demand concentrates in United States ambulatory surgical centers where site-of-service payment differentials compress procedure costs below hospital outpatient thresholds. Reimbursement stability under CPT codes 31295-31297 sustains manufacturer margin structures.
- Ear Tubes:Fluoroplastic or silicone tympanostomy tubes ventilate middle ear effusion in pediatric otitis media cases. German and Japanese otolaryngology clinics drive specification refinement toward bioinert materials with reduced extrusion rates. Volume correlates with pediatric population density and seasonal infection patterns.
- Nasal Splints:Thermoplastic or silicone stents maintain septal positioning post-septoplasty.
- Laser Systems:Solid-state diode and KTP platforms enable precise soft tissue ablation in laryngeal and nasal applications.
Volume sits with balloon sinus dilation; growth tilts toward laser systems as office-based laryngeal procedures expand.
Application:
Anatomical target determines regulatory pathway complexity, with sinus procedures navigating clearer 510(k) predicates than novel cochlear indications.
- Sinus Surgery:Functional endoscopic sinus surgery and balloon dilation address chronic rhinosinusitis refractory to medical management. United States hospital systems and German academic centers anchor procedure volume, driven by aging demographics and CT-based diagnostic penetration. Revision case complexity sustains demand for navigation-integrated platforms.
- Cochlear Implants:Multichannel electrode arrays restore auditory sensation in severe-to-profound sensorineural hearing loss. Japanese and Australian implantation rates exceed global medians due to universal screening programs and favorable reimbursement. Neural interface reliability constraints limit expansion beyond specialized neurotology centers.
- Snoring Treatment:Palatal stiffening and base-of-tongue reduction address obstructive sleep apnea spectrum disorders.
- Otitis Media:Tympanostomy tube placement and chronic ear disease management target pediatric populations.
Revenue concentrates in sinus surgery; cochlear implants climb the fastest as bilateral indication expansion and MRI-compatible electrode designs penetrate mature markets.
End User:
Facility type dictates capital equipment purchasing authority, with integrated delivery networks centralizing high-value acquisitions independent of individual physician preference.
- Hospitals:Academic medical centers and community hospital systems maintain comprehensive ENT service lines including skull base and complex revision capabilities. United States IDNs leverage volume commitments for capital equipment discounts. Operating room block scheduling constraints limit same-day discharge penetration.
- Outpatient Clinics:Physician-owned practices and hospital-affiliated ambulatory sites perform office-based procedures including laryngeal laser and limited endoscopy. German and Japanese clinic networks emphasize diagnostic-to-therapeutic workflow compression. Equipment footprint limitations favor portable platforms.
- Surgical Centers:Dedicated ambulatory surgery facilities optimize throughput for balloon sinus dilation and routine otologic procedures.
- Diagnostic Laboratories:Pathology and audiology service providers support preoperative assessment and implant programming.
Procedure volume gravitates toward surgical centers; diagnostic laboratories gain share fastest as preoperative CT and audiological testing decouple from therapeutic sites.
Technology:
Technology selection reflects infrastructure maturity, with robotic platforms requiring dedicated capital allocation against established endoscopic workflows.
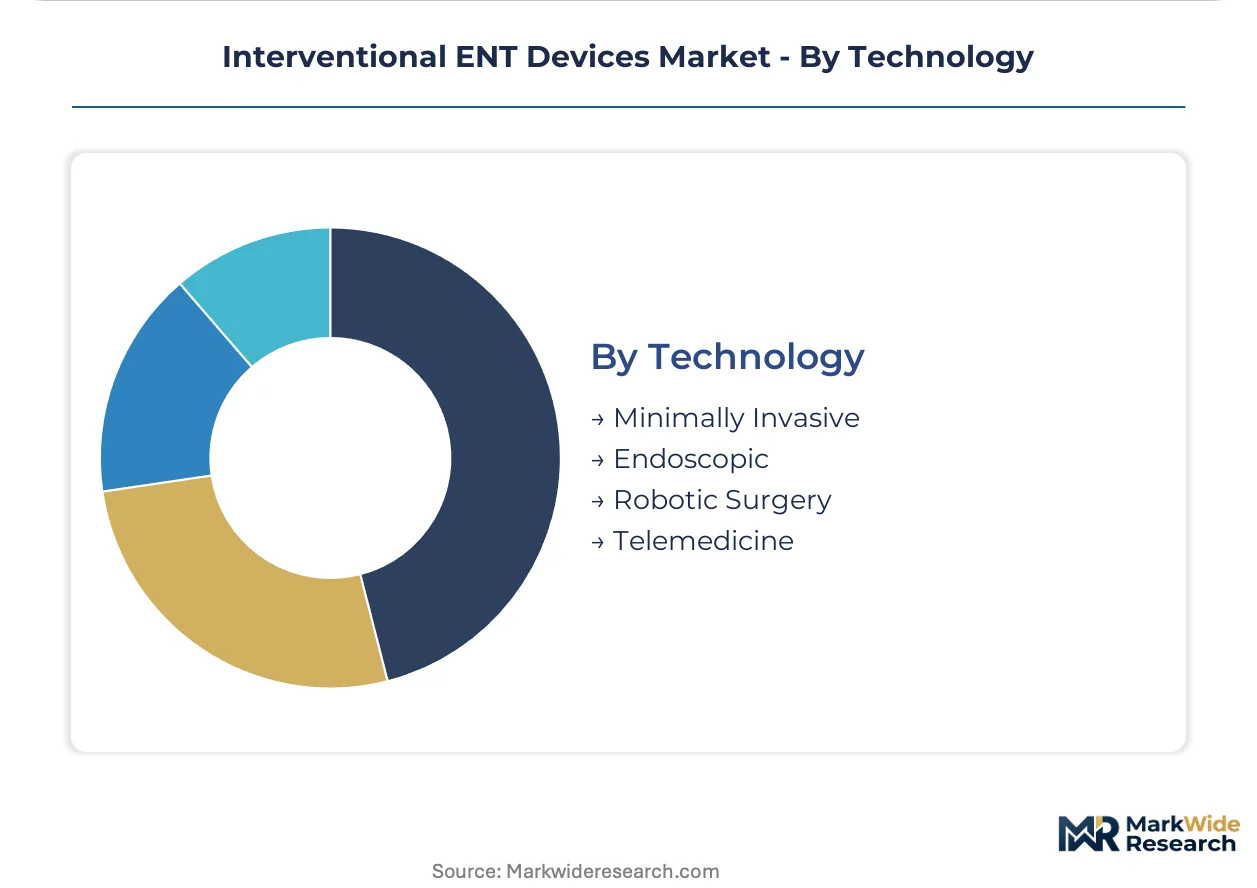
- Minimally Invasive:Balloon dilation, microdebrider-based tissue removal, and transoral approaches reduce procedural morbidity versus open techniques. United States and German adoption curves favor same-day discharge protocols. Reimbursement parity with conventional approaches accelerates substitution.
- Endoscopic:Rigid and flexible fiberoptic visualization enables anatomically precise intervention through natural orifices. Olympus and Karl Storz installed bases in Japan and Germany create switching costs for competitive platform entry. 4K and 3D visualization upgrades sustain aftermarket revenue streams.
- Robotic Surgery:Transoral and transnasal robotic platforms enable single-surgeon procedures in confined anatomical spaces.
- Telemedicine:Remote consultation and postoperative surveillance extend geographic reach of specialized otolaryngology expertise.
Installed base concentrates with endoscopic technology; robotic surgery exhibits steepest expansion trajectory as FDA 510(k) clearances accumulate for head and neck indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American interventional ENT device development, with the metropolitan corridor hosting concentrated surgical navigation and powered instrumentation engineering.
United States
ASC site-of-service differentials and aging demographic profiles drive balloon sinus dilation volume. FDA 510(k) premarket notification pathways compress product development cycles for Class II devices. Texas Medical Center in Houston hosts dedicated ENT innovation clusters where academic medical centers pilot navigation-integrated platforms.
Germany
Universal healthcare reimbursement and Krankenhaus procurement centralization sustain demand for premium visualization stacks. EU MDR notified body assessments under TÜV SÜD and DEKRA shape market access timelines. Baden-Württemberg's precision manufacturing corridor around Stuttgart supplies optical components for rigid endoscope production.
Japan
Universal newborn hearing screening and aging-related conductive loss sustain cochlear implant and otologic instrument demand. PMDA premarket certification and JIS quality standards govern product registration. Tokyo-Osaka metropolitan clusters concentrate neurotology referral centers and specialized training programs.
India
Private hospital chain expansion in Mumbai and Delhi deploys dedicated ENT day-surgery units for balloon dilation adoption. CDSCO medical device rules and import license requirements structure competitive entry. Bangalore's medtech corridor attracts contract manufacturing for single-use sinus instruments serving domestic and export markets.
Australia
Bilateral cochlear implant reimbursement expansion and Indigenous ear health programs drive procedural volume. TGA conformity assessment pathways align with EU MDR technical documentation standards. Melbourne's biomedical precinct clusters cochlear research with surgical training institutions.
Interventional ENT Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across navigation integration and optical performance tiers, with integrated platform vendors commanding service-contract pricing power against single-use kit suppliers. The vendor base stratifies between diversified medtech conglomerates with installed base leverage and specialized ENT-focused manufacturers competing on procedure-specific workflow optimization. Three archetypes dominate: full-stack platform vendors bundling capital and consumables, pure-play balloon dilation specialists, and optical component OEMs supplying visualization subsystems. Consolidation pressure favors M&A-driven portfolio expansion into robotic-assisted platforms, while geographic licensing agreements accelerate emerging market penetration without direct regulatory infrastructure investment.
Among diversified medtech conglomerates, Medtronic, Stryker, and Johnson & Johnson Services, Inc. exemplify the integrated platform archetype, each anchoring distinct competitive positions through navigation, visualization, or surgical stapling ecosystems that lock in recurring consumable revenue. These entities occupy positions where capital equipment placements precondition long-term instrument and service contract relationships, representing the structural dynamic that compresses standalone device manufacturer margins.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Olympus Corporation |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew |
| Karl Storz |
| Richard Wolf GmbH |
| Acclarent, Inc. |
| PENTAX Medical |
| Others |
Value Network & Pricing Analysis
Ambulatory surgical center procurement committees in the United States anchor pricing power for balloon sinus dilation kits, compressing margins through volume commitments and unbundled service contracts. This buyer concentration forces manufacturers toward subscription-based instrument replacement programs that obscure total cost of ownership while locking in recurring revenue streams.
Pricing Analysis
Outcome-based pricing anchors balloon sinus dilation contracts, with reimbursement stability under CPT codes 31295-31297 sustaining manufacturer margin structures. Three-tier pricing structure across premium navigation-integrated, standard visualization, and economy single-use tiers separates Medtronic and Stryker capital platforms from commoditized balloon kits. Cost compression in the economy tier is intensifying because German Krankenhaus procurement centralization demands itemized preventive maintenance pricing. Price sensitivity concentrates among outpatient clinics seeking portable platforms, while academic medical centers prioritize optical clarity and workflow integration over unit cost.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Stuttgart, and Tokyo orchestrate hub-and-spoke patterns for ENT visualization stacks and powered instrumentation. Component fabrication draws from Taiwanese and South Korean foundries for CCD and CMOS sensors, Japanese precision manufacturers for nitinol actuation wire, and German optical specialists for rigid endoscope lenses. Single-source vulnerability concentrates in sensor supply chains exposed to geopolitical disruption. Distribution runs through dedicated medtech logistics providers serving hospital systems and ambulatory surgery centers with temperature-controlled sterile instrument handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration momentum is accelerating as manufacturers pursue captive supply of nitinol actuation components and optical sensor subassemblies to defend margin structures against procurement centralization.
For Market Incumbents: Acquire electromagnetic tracking and navigation software assets to fortify platform stickiness against pure-play balloon dilation specialists. Consolidate technical documentation portfolios under EU MDR streamlined pathways to reduce notified body review timelines. Backward integration into nitinol wire drawing secures predictable radial force profiles for single-use dilators while insulating against commodity price volatility. For New Entrants and Emerging Players: Physician-owned ambulatory practices in India represent the most penetrable buyer archetype, with Mumbai and Delhi day-surgery units deploying dedicated ENT infrastructure. Direct-to-physician e-procurement platforms bypass distributor markups for high-velocity consumables. Target CDSCO import license navigation as a regulatory differentiation moat against established multinational supply chains. For Investors and Strategic Acquirers: The window for entry favors robotic-assisted platform specialists with FDA 510(k) clearances for transoral indications. Long-term viability hinges on software-enabled device guidance convergence with surgical planning algorithms. Watch FDA premarket notification pathway acceleration for head and neck robotic indications as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation consolidation accelerates notified body assessments under TÜV SÜD and DEKRA. |
| Hospital System Partnership | United States IDN volume commitments secure capital equipment discounts and lock in consumable reorder cadence. |
| Software Companion Development | Preoperative CT segmentation algorithms integrate with electromagnetic tracking to reduce fluoroscopy exposure. |
| Reimbursement Strategy | CPT code stability for balloon sinus dilation sustains ASC site-of-service payment differentials against hospital outpatient compression. |
| Backward Integration | In-house nitinol wire production insulates radial force consistency from commodity supply volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this interventional ENT devices analysis. Primary interviews with otolaryngologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EU MDR notified body assessments, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across product type, application, end user, and technology segmentation dimensions.
Granularity-level modeling addressed balloon sinus dilation catheters, cochlear implant electrode arrays, and robotic surgery platforms at the SKU level across ambulatory surgical center, hospital outpatient, and office-based site-of-service categories. CAGRs derived from procedure volume trends, reimbursement trajectory assumptions, and technology substitution elasticity coefficients. Forecast inputs incorporated nitinol alloy pricing indices, optical sensor foundry capacity utilization, and EU MDR transition timeline uncertainty.
Revisions become necessary when FDA software-enabled device guidance shifts, EU AI Act applicability to surgical navigation clarifies, or geopolitical disruption affects Taiwanese sensor foundry output. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Audiology Devices Market
ENT
Nasal Sampling Lines Market
ENT
Ear Health Market
ENT
Global Audiological Devices Market
ENT
Global ENT Workstations Market
ENT
Custom Hearing Aids Market
ENT
ENT Examination Chair Market
ENT
Europe Hearing Aids Market
ENT
Electrolarynx Market
ENT
Global Sinusitis Treatment Market
ENT
Global Pediatric Hearing Aids Market
ENT
Nasal Polyps Treatment Market
ENT
ENT Laser Devices Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
ENT Devices Market
ENT
Over-The-Counter (OTC) Hearing Aids Market