
 Pressure Infusion Cuffs Market | 2026-2036
Pressure Infusion Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Infusion Cuffs Market Analytics
Germany is narrowing its manufacturing footprint for precision medical textiles and inflation bladder assemblies used in pressure infusion systems. VBM Medizintechnik leverages its Stuttgart-area production base to dominate European supply of reusable automatic cuffs. Smiths Medical anchors North American hospital contracts through backward integration into polymer molding and valve assembly. Rudolf Riester specializes in manual cuff designs for emergency field applications across Central Asian and African markets.
Pressure infusion cuffs are pneumatic compression devices comprising an inflatable bladder, pressure gauge or sensor, and closure mechanism designed to deliver controlled rapid fluid or blood product administration into a patient's vascular system at rates exceeding gravity flow. These devices typically operate within 300-500 mmHg pressure ranges and employ latex, PVC, or polyurethane bladder materials depending on intended reuse cycles and allergen protocols. Disposable cuffs command the dominant revenue share in hospital procurement due to infection control mandates, while automatic cuffs with integrated pressure monitoring represent the fastest-growing technology segment as telemetry-enabled infusion protocols expand. Wireless data-integrated systems remain nascent but concentrate margin pools in academic medical centers pursuing digital operating room infrastructure.
FDA 510(k) premarket notification requirements govern pressure infusion cuff commercialization in the United States, while the EU Medical Device Regulation and CE marking framework dictate conformity assessment across European markets. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification by major hospital group purchasing organizations. Stakeholders must monitor evolving cybersecurity guidance from FDA for wireless-enabled infusion devices and anticipate material substitution pressures as REACH restrictions on certain phthalate plasticizers extend to medical-grade PVC formulations.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing supplier lists and mandating telemetry-compatible cuff systems that integrate with electronic health record platforms.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements are accelerating replacement cycles for legacy manual cuffs across German and French hospital systems.
- Emergency Medical Services:Pre-hospital trauma protocols in the United States and Australia are standardizing automatic pressure infusion as standard equipment for paramedic response units.
- Polyurethane bladder materials:Latex-free formulations are displacing traditional rubber components in pediatric and allergy-sensitive care settings.
Market Restraints
- Medical-grade PVC supply concentration:Three compounders in Germany and Belgium control 70% of European phthalate-free resin supply for inflation bladder production.
- FDA 510(k) timeline friction:Average clearance duration for wireless-enabled cuffs now exceeds 14 months, delaying product launches.
- Gravity infusion sets:Low-cost gravity alternatives retain preference in resource-constrained clinical environments across Central Asia and sub-Saharan Africa.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded trauma center construction under the National Health Mission is creating first-time demand for automatic cuff systems.
- Telemedicine-integrated telemetry:Convergence of Bluetooth Low Energy protocols with cloud-based infusion monitoring enables remote pressure adjustment during inter-hospital transfers.
- Subscription-based device-as-a-service:Asset-light procurement models are penetrating academic medical centers in the United States seeking to convert capital expenditure to operational budgets.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise in pneumatic systems and FDA quality system regulation commands premium compensation in Boston and Minneapolis hiring markets.
- ISO 13485 audit backlogs:Notified body capacity constraints in Europe are extending supplier certification timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Infusion Cuffs Market |
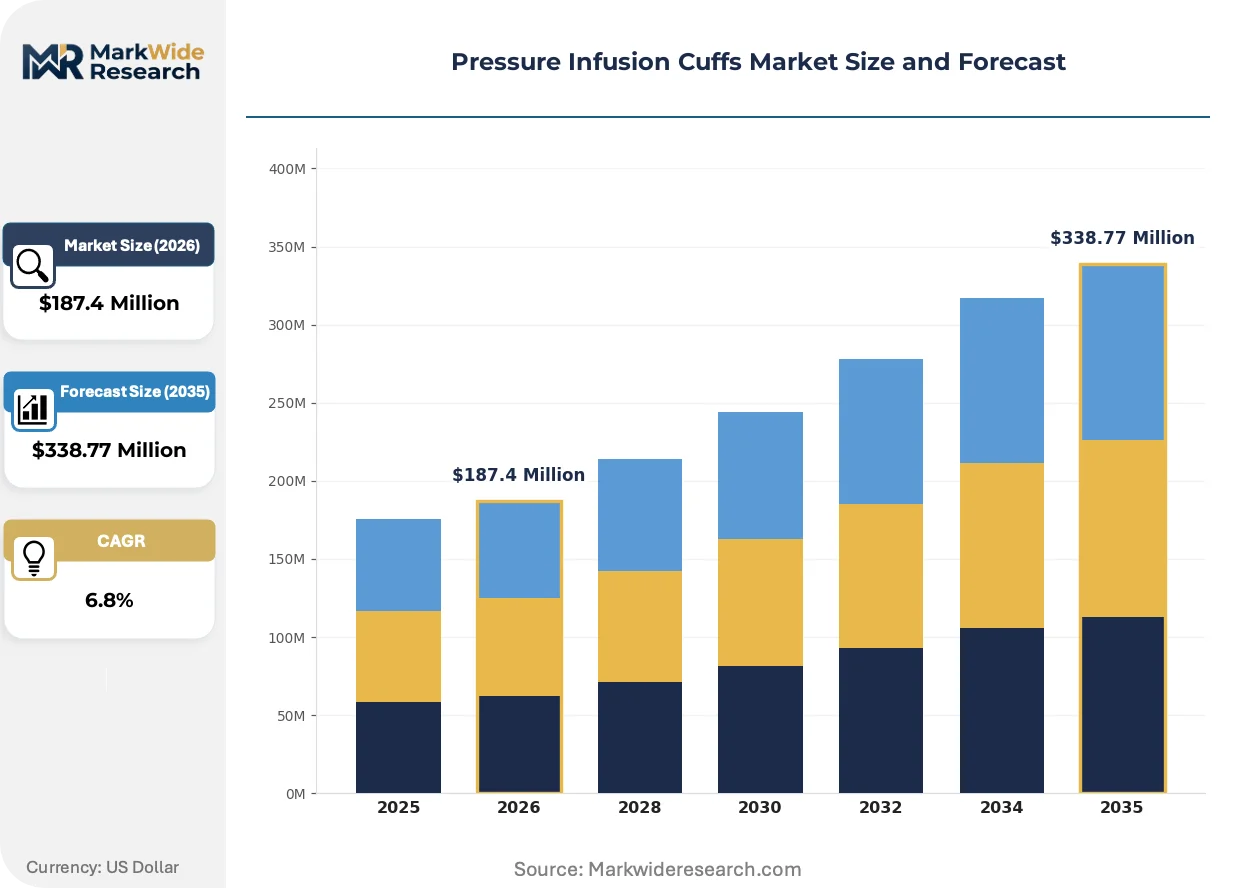
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cuffs, Automatic Cuffs, Digital Cuffs, Disposable Cuffs End User: Hospitals, Clinics, Emergency Medical Services, Home Care Material: Latex, PVC, Nylon, Polyurethane Technology: Inflation Technology, Pressure Monitoring, Data Integrated, Wireless |
| Companies Covered | Smiths Medical, VBM Medizintechnik, 3M, ERKA, Statcorp, Sarstedt, Armstrong Medical, Rudolf Riester, Friedrich Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Infusion Cuffs Market Evolving Landscape
Wireless connectivity and real-time pressure telemetry are transforming pressure infusion cuffs from passive mechanical devices into data-generating clinical assets integrated with patient monitoring ecosystems.
Capacitive pressure sensing technology is digitizing fluid administration workflows by replacing analog gauges with millimeter-precise digital feedback. Academic medical centers in the United States are piloting these systems for operating room integration. The technology is digitizing compliance documentation by automating pressure logging directly into anesthesia information management systems.
REACH restrictions on phthalate plasticizers are forcing material substitutions across European supply chains. Compounders are accelerating bio-based plasticizer validation for medical-grade PVC formulations. German manufacturers are responding fastest, with Stuttgart-area production facilities already transitioning to DINCH-based formulations for EU market access.
Hospital group purchasing organizations are consolidating supplier contracts around single-source telemetry platforms. Independent community hospitals are losing negotiation leverage as IDNs standardize on enterprise-wide infusion device fleets. This concentration is most visible in the United States, where three purchasing networks control 60% of acute care procurement volume.
Pressure Infusion Cuffs Market Segmentation
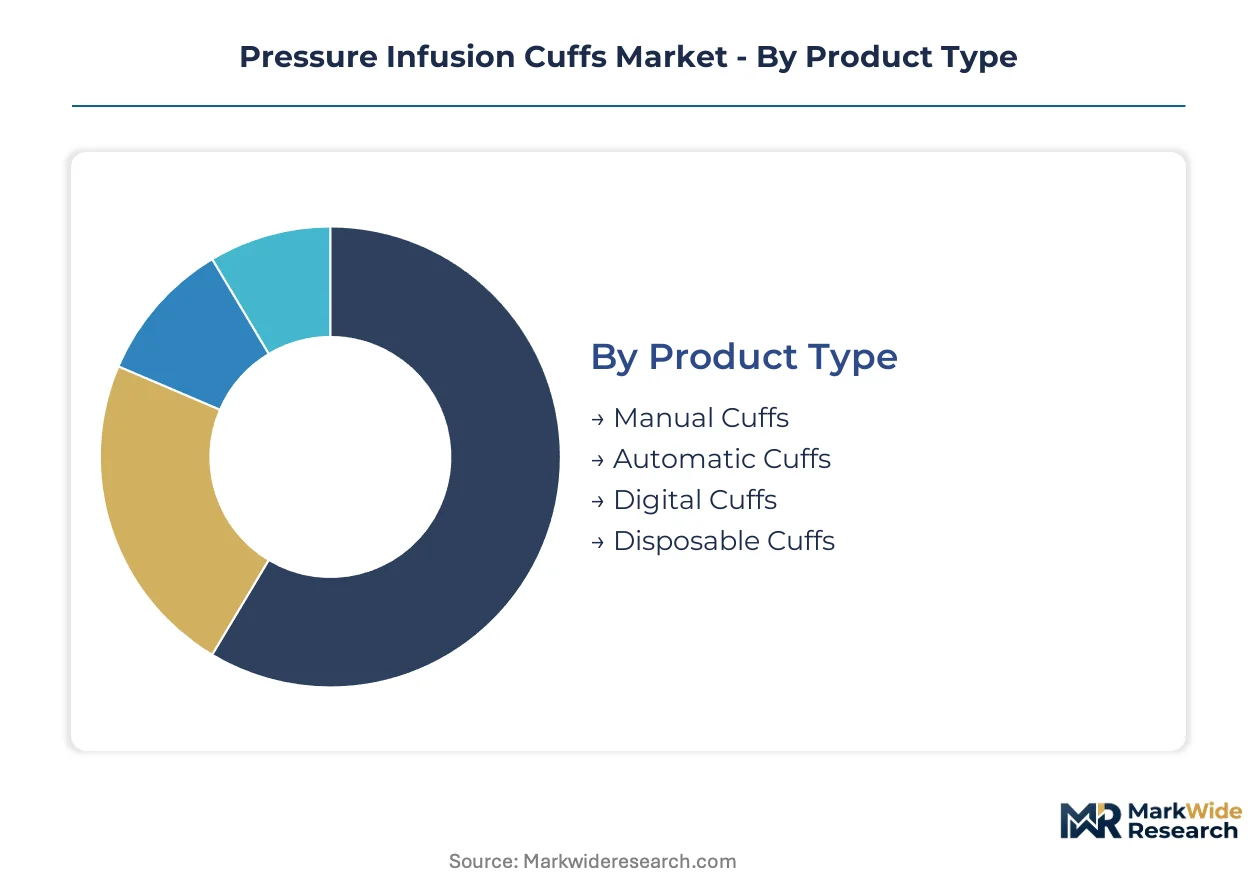
Pressure infusion cuff purchasing decisions split across clinical workflow requirements, infection control protocols, and capital budget cycles. Procurement patterns diverge sharply between emergency field deployment and operating room integration, creating distinct performance specifications within each segment cluster.
Product Type:
Use cases span from basic trauma stabilization to telemetry-integrated surgical workflows, with cost and reusability driving the fundamental split.
- Manual Cuffs:Hand-operated bulb inflation systems with analog pressure gauges deliver 300-500 mmHg compression through simple mechanical valves. Demand clusters in resource-constrained Central Asian and sub-Saharan African markets where gravity infusion alternatives compete aggressively on procurement cost.
- Automatic Cuffs:Microprocessor-controlled pressure maintenance with preset target algorithms eliminates manual monitoring during rapid fluid resuscitation. Emergency Medical Services in the United States and Australia are standardizing these systems as paramedic fleet equipment under tightened pre-hospital trauma protocols.
- Digital Cuffs:Millimeter-precise capacitive sensing replaces analog gauges for anesthesia information management integration.
- Disposable Cuffs:Single-use latex or PVC bladder assemblies with pre-set pressure limits address hospital infection control mandates.
Disposable cuffs dominate installed base. Automatic cuffs are where expansion concentrates.
End User:
Capital intensity and regulatory exposure shape purchasing authority across care settings.
- Hospitals:Integrated delivery networks in the United States consolidate procurement around telemetry-compatible enterprise fleets with electronic health record integration. German hospital systems under EU Medical Device Regulation pressure are accelerating replacement cycles for legacy manual inventory.
- Emergency Medical Services:Pre-hospital response units require ruggedized automatic systems with rapid deployment protocols. Australian and American EMS agencies are driving standardization as trauma care protocols tighten.
- Clinics:Outpatient infusion centers balance cost constraints against intermittent high-acuity needs.
- Home Care:Lightweight manual systems with simplified pressure indicators serve palliative and chronic transfusion patients.
Hospital procurement commands volume concentration. Emergency Medical Services is climbing the fastest.
Material:
Biocompatibility mandates and REACH chemical restrictions are forcing formulation transitions across European supply chains.
- Polyurethane:Thermoplastic elastomer formulations deliver latex-free performance with superior abrasion resistance for reusable automatic cuff cycles. Pediatric and allergy-sensitive care settings in Germany and France are displacing traditional rubber components fastest.
- PVC:Medical-grade formulations with DINCH-based plasticizers dominate disposable bladder production. Stuttgart-area compounders are transitioning production fastest under REACH phthalate restrictions.
- Latex:Natural rubber maintains cost advantage in manual field applications despite declining hospital acceptance.
- Nylon:Woven reinforcement layers provide structural stability for high-pressure inflation chambers.
PVC holds production volume leadership. Polyurethane is gaining share fastest on allergen protocol expansion.
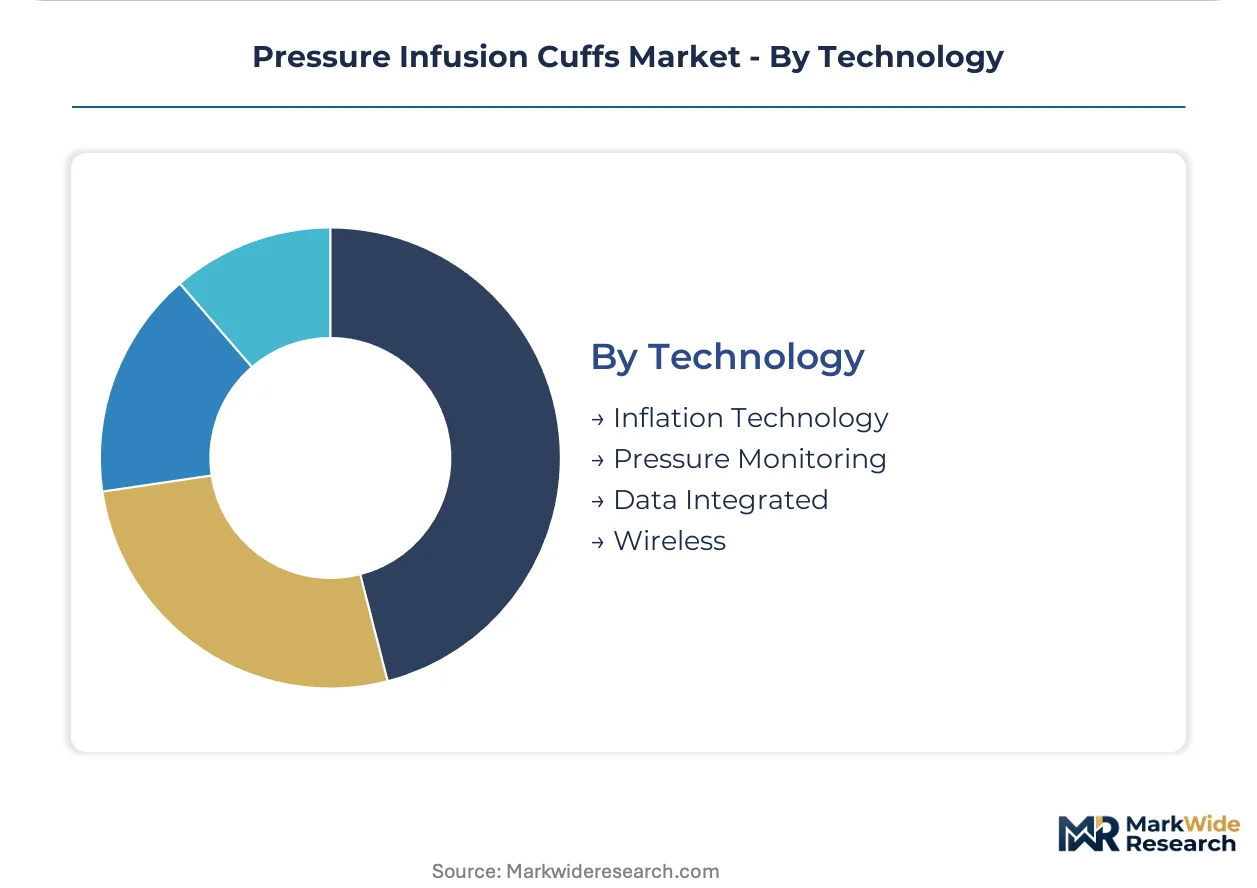
Technology:
Digital integration maturity separates commodity mechanical supply from premium telemetry-enabled platforms.
- Wireless:Bluetooth Low Energy protocols enable cloud-based pressure monitoring during inter-hospital patient transfers. FDA 510(k) clearance timelines exceeding 14 months are constraining launch velocity for connected systems.
- Data Integrated:Direct anesthesia information management system logging automates compliance documentation in academic medical centers. United States hospital consolidation is concentrating procurement around single-source telemetry platforms.
- Pressure Monitoring:Real-time sensor feedback with audible and visual alarms prevents over-infusion complications.
- Inflation Technology:Pneumatic bladder mechanics remain the foundational compression mechanism across all product tiers.
Inflation technology anchors legacy installed base. Wireless platforms represent the steepest expansion trajectory despite regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three German compounders in Stuttgart and Belgium control seventy percent of European phthalate-free resin supply for inflation bladder production. This concentration shapes procurement security calculations for manufacturers across multiple continents.
United States
Hospital consolidation into integrated delivery networks compresses supplier lists and mandates telemetry-compatible cuff systems. FDA 510(k) premarket notification requirements govern commercialization, with wireless-enabled clearance timelines now exceeding fourteen months. Boston and Minneapolis biomedical engineering clusters face acute talent scarcity for cross-functional pneumatic and regulatory expertise.
Germany
EU Medical Device Regulation enhanced clinical evidence requirements accelerate replacement cycles for legacy manual cuffs. REACH restrictions on phthalate plasticizers force DINCH-based formulation transitions across Stuttgart-area production facilities. VBM Medizintechnik leverages its regional base to dominate European reusable automatic cuff supply.
Australia
Pre-hospital trauma protocol standardization drives automatic pressure infusion adoption across paramedic response units. TGA regulations align with international standards for emergency medical device approval. Sydney and Melbourne EMS agencies anchor procurement standardization across state-level health systems.
India
National Health Mission government-funded trauma center construction creates first-time demand for automatic cuff systems. CDSCO medical device registration requirements tighten quality thresholds for imported systems. Maharashtra and Karnataka hospital infrastructure expansion concentrates procurement decision-making in western and southern state clusters.
Belgium
Medical-grade PVC compounding capacity serves as critical upstream input for European disposable bladder manufacturing. ECHA chemical restriction enforcement timelines pressure formulation transitions ahead of full REACH implementation. Antwerp-area resin production facilities coordinate supply allocation across German and French device assemblers.
Pressure Infusion Cuffs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in bladder molding and valve assembly. The vendor base organizes around three archetypes: diversified medical device conglomerates with backward integration into polymer molding, precision pneumatic specialists with captive textile production, and regional manual cuff fabricators serving price-sensitive field applications. Competitive moves concentrate on M&A for telemetry platform acquisition and geographic expansion into government-funded trauma infrastructure.
Among diversified device manufacturers, Smiths Medical anchors North American hospital contracts through integrated polymer and valve production. VBM Medizintechnik exemplifies the European precision pneumatic archetype with Stuttgart-area manufacturing concentration. Rudolf Riester occupies a position within manual field application supply for Central Asian and African markets.
| Leading Market Players |
|---|
| Smiths Medical |
| VBM Medizintechnik |
| 3M |
| ERKA |
| Statcorp |
| Sarstedt |
| Armstrong Medical |
| Rudolf Riester |
| Friedrich Bosch |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors govern the landed cost spread between Stuttgart-area compounders and French device assemblers, concentrating margin pressure on mid-tier manufacturers while enabling premium pricing for DINCH-certified polyurethane formulations that satisfy REACH phthalate restrictions.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across the Pressure Infusion Cuffs Market, separating wireless-enabled telemetry platforms from basic mechanical systems. Three-tier pricing stratifies across premium automatic cuffs with integrated pressure monitoring, standard reusable manual systems, and economy disposable units for infection-sensitive workflows. Cost compression in the standard tier intensifies as German hospital systems consolidate procurement around single-source telemetry fleets. Emergency Medical Services agencies exhibit highest price sensitivity due to fleet-scale volume mandates, while academic medical centers in the United States show lowest sensitivity when purchasing data-integrated platforms for operating room infrastructure.
Supply Chain Analysis
Medical-grade PVC resin feedstock draws from concentrated compounding capacity in Germany, Belgium, and the Netherlands, with three Stuttgart-Antwerp producers anchoring European phthalate-free supply. Inflation bladder production hinges on DINCH plasticizer formulations, precision textile weaving, and microprocessor valve assemblies. Single-source vulnerability runs through the Belgian resin corridor, where ECHA enforcement timelines threaten allocation disruptions. Distribution runs through hospital group purchasing organizations in the United States and regional device distributors across Central Asian and African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pressure Infusion Cuffs Market functions as a regulatory entrenchment story, where FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create switching costs that cement incumbent positions against unqualified challengers.
For Market Incumbents: Insulate telemetry platform margins by deepening backward integration into polymer molding and valve assembly, mirroring Smiths Medical's North American hospital contracting model. Accelerate ISO 13485 certification investments ahead of European notified body capacity constraints to capture replacement cycle demand from legacy manual cuff inventories. Threat exposure concentrates in Bluetooth Low Energy protocol standardization, where wireless data integration investments risk obsolescence without continuous R&D commitment. For New Entrants and Emerging Players: Build out white-space positioning in India's National Health Mission trauma center infrastructure, where first-time automatic cuff demand outpaces established supplier presence. Target manual-to-automatic upgrade pathways in Central Asian and sub-Saharan African field applications where Rudolf Riester's cost-optimized designs dominate. Go-to-market traction depends on CDSCO registration navigation and state-level hospital procurement relationship development in Maharashtra and Karnataka clusters. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward notified body-certified manufacturers with established DINCH formulation supply agreements. Long-term viability favors precision pneumatic specialists with captive textile production and backward-integrated polymer capabilities over pure-play distributors. Signal to monitor: FDA cybersecurity guidance finalization for wireless-enabled infusion devices, which would accelerate consolidation around telemetry-capable platform owners.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate replacement demand for legacy manual cuff inventories across German hospital systems. |
| Hospital System Partnership | Integrated delivery network procurement consolidation in the United States favors telemetry-compatible enterprise fleet suppliers with EHR integration capabilities. |
| Software Companion Development | Bluetooth Low Energy protocol integration enables cloud-based pressure monitoring during inter-hospital patient transfers for Emergency Medical Services. |
| Backward Integration | Captive polymer molding and valve assembly capacity anchors North American hospital contracts against supply chain disruption risks. |
| Reimbursement Strategy | Pre-hospital trauma protocol standardization in Australia and the United States drives automatic cuff fleet procurement through paramedic response unit budgets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, Emergency Medical Services fleet managers, GPO contracts administrators, and polymer compounding technical leads. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, hospital procurement contract disclosures, REACH chemical restriction filings, and trade flow data for medical-grade PVC resin. Bottom-up unit economics and top-down market sizing were triangulated against installed base estimates and replacement cycle assumptions.
Calibration against historical price points and volume trajectories anchored growth projections across the modeling period, with segmentation dimensions spanning product type (manual, automatic, digital, disposable), end user (hospitals, Emergency Medical Services, clinics, home care), material formulation (polyurethane, PVC, latex, nylon), and technology tier (wireless, data-integrated, pressure monitoring, inflation mechanics). CAGRs were derived from weighted average of clinician adoption curves, regulatory clearance velocity, and capital expenditure cycles at integrated delivery networks. Industry-specific inputs included phthalate-free formulation transition timelines and notified body audit queue lengths.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Stuttgart-area compounders or accelerated FDA cybersecurity rulemaking would shift outcomes beyond modeled ranges. Cross-checking against hospital capital expenditure disclosures and state-level trauma center construction announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Intravascular Stents Market