
 Vascular Access Systems Market | 2026-2036
Vascular Access Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Access Systems Market Analytics
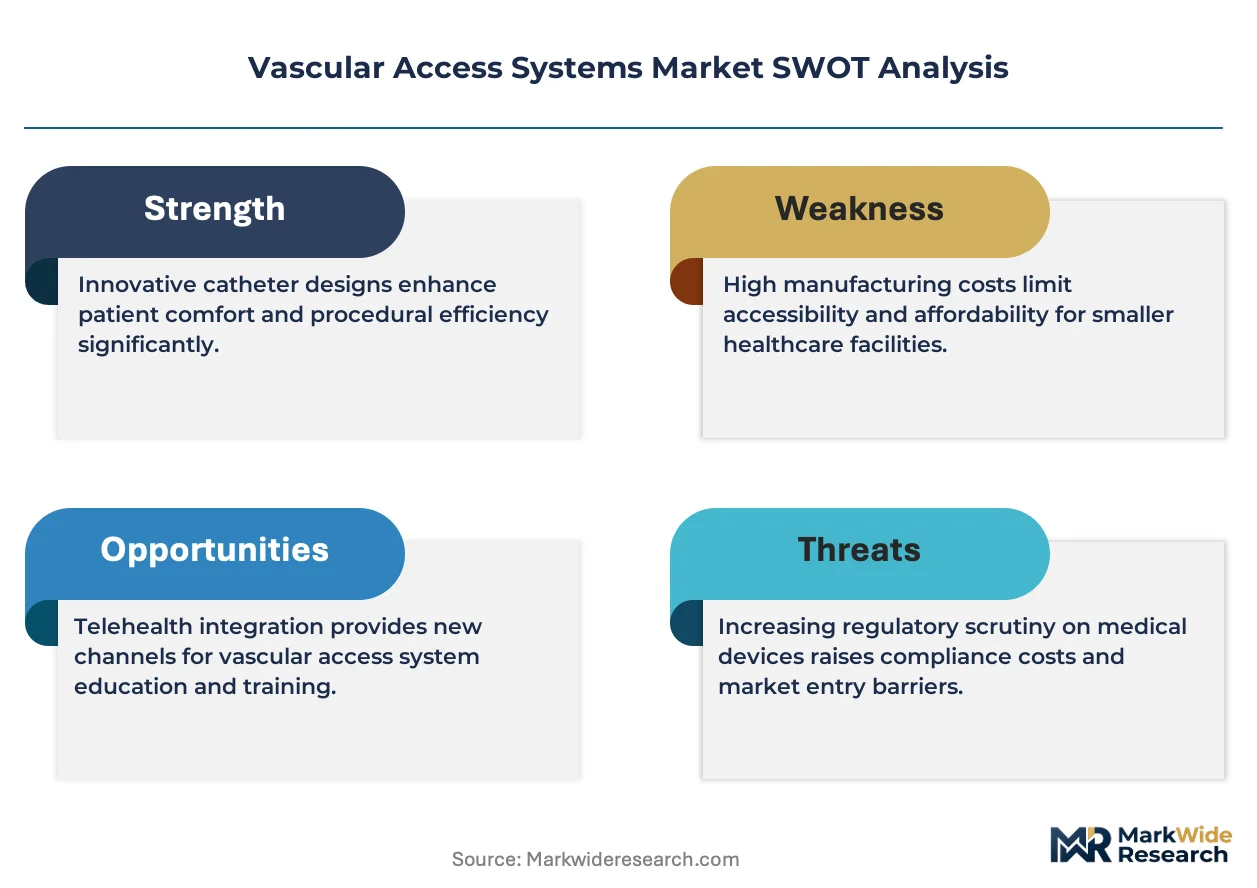
Asset-light leasing models for ultrasound-guided insertion equipment is narrowing the competitive field to firms with strong balance sheets. Becton, Dickinson and Company leverages its captive polymer compounding capacity to control input costs on polyurethane catheters. Teleflex Incorporated anchors its position through dedicated vascular access sales forces embedded in major IDN procurement committees. ICU Medical, Inc. specializes in closed-system transfer devices that reduce bloodstream infection liability for hospital purchasers.
Vascular access systems comprise indwelling catheters, implantable ports, and associated insertion accessories engineered to deliver pharmaceuticals, withdraw blood, or conduct hemodynamic monitoring through central or peripheral venous pathways. These devices typically feature radiopaque polyurethane or silicone construction with durometer ratings between 55A and 85A to balance kink resistance with vessel compliance. Centrally inserted catheters dominate value pools due to extended dwell times and higher ASPs in ICU settings. Ultrasound-guided technology is expanding fastest as electromagnetic navigation adds cost without proven superiority in routine placements. Home healthcare represents an emerging margin segment where patient self-administration training creates recurring revenue streams.
FDA 510(k) clearance pathways and the EU MDR clinical evaluation requirements are elevating documentation burdens for novel catheter coatings. The EPA and ECHA jointly scrutinize phthalate plasticizers in PVC-based devices, accelerating material transitions toward TPU alternatives. Stakeholders must monitor reimbursement shifts for peripherally inserted central catheter placements in ambulatory settings.
Market Dynamics
Asset-light leasing models for ultrasound-guided insertion equipment are concentrating purchasing power among integrated delivery networks with balance-sheet capacity to absorb utilization risk, compressing vendor margins and narrowing the competitive field to firms with strong financial positions.
Growth Catalysts
- EU MDR clinical evaluation requirements:The EU MDR elevates documentation burdens for novel catheter coatings, creating competitive moats for manufacturers with established quality management systems and accelerating consolidation among smaller suppliers.
- Oncology clinic expansion in the United States:Implantable ports for long-term chemotherapy delivery are seeing concentrated demand from expanding oncology networks seeking durable vascular access solutions with extended dwell times.
- Ultrasound-guided catheter systems:German university hospitals are consolidating purchasing for these systems, driving standardization of insertion protocols and reducing variability in placement outcomes across tertiary care centers.
Market Restraints
- Phthalate plasticizer scrutiny:The EPA and ECHA jointly scrutinize phthalate plasticizers in PVC-based devices, forcing accelerated material transitions toward TPU alternatives with higher input costs and reformulation timelines.
- Polymer compounding concentration:Captive polymer compounding capacity resides with a limited number of vertically integrated manufacturers, creating supply concentration risk for polyurethane catheter producers dependent on external material sourcing.
- Electromagnetic navigation limitations:Electromagnetic navigation adds cost without proven superiority in routine placements, constraining adoption to complex anatomical cases and limiting addressable market expansion.
Strategic Opportunities
- Home healthcare self-administration:Patient self-administration training creates recurring revenue streams in home healthcare, an emerging margin segment where vascular access device manufacturers can capture value beyond initial device sales.
- FDA 510(k) pathway optimization:Streamlined FDA 510(k) clearance pathways for incremental device modifications enable faster time-to-market for catheter coating innovations, rewarding firms with robust regulatory affairs capabilities.
- Closed-system transfer device integration:Closed-system transfer devices that reduce bloodstream infection liability address hospital purchaser risk management priorities, creating differentiation in competitive bidding environments.
Industry Challenges
- Durometer specification expertise:Balancing kink resistance with vessel compliance requires specialized polymer engineering talent scarce in the medical device workforce, constraining product development velocity.
- Reimbursement code alignment:Shifting reimbursement frameworks for peripherally inserted central catheter placements in ambulatory settings create revenue recognition uncertainty and demand forecasting complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Access Systems Market |
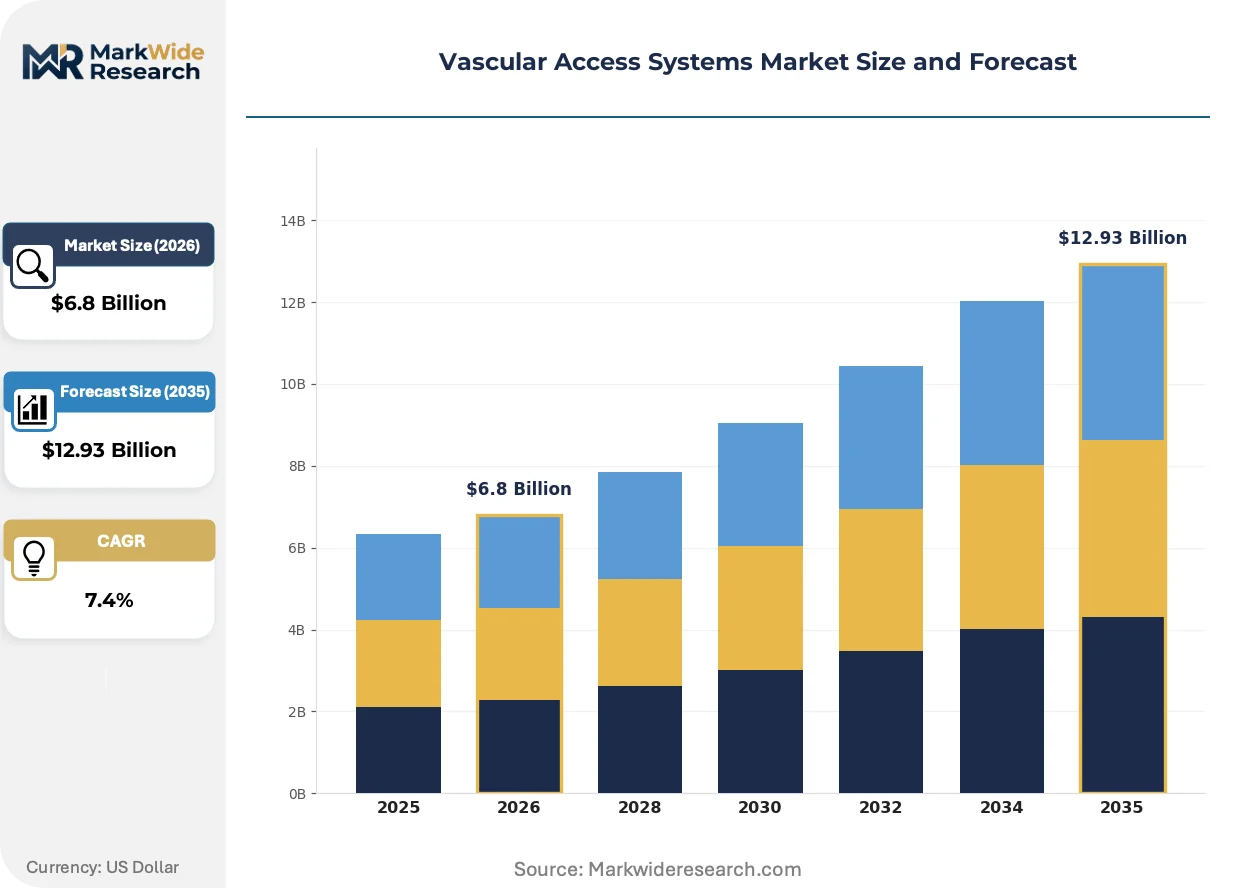
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrally Inserted Catheters, Peripherally Inserted Catheters, Dialysis Catheters, Implantable Ports End User: Hospitals, Ambulatory Surgery Centers, Clinics, Home Healthcare Material: Polyurethane, Silicone, PVC, Acrylonitrile Butadiene Styrene Technology: Conventional, Ultrasound-guided, Electromagnetic, Optical |
| Companies Covered | Becton, Dickinson and Company, Teleflex Incorporated, ICU Medical, Inc., B. Braun SE, Medtronic, AngioDynamics, Inc., Terumo Corporation, Cook Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Access Systems Market Evolving Landscape
Radiopaque polyurethane formulations with tunable durometer ratings are displacing legacy silicone constructions as the dominant catheter material platform, while regulatory scrutiny of plasticizers and infection control protocols reshape product development priorities across the value chain.
Antimicrobial catheter coatings incorporating chlorhexidine or silver nanoparticles are migrating from premium ICU segments toward standard-of-care positioning in general ward placements. Academic medical centers in the United States are piloting these coatings for routine central line insertions, compressing the price premium between antimicrobial and uncoated devices and forcing coating suppliers to demonstrate measurable infection reduction in real-world evidence studies rather than controlled trials.
The EU MDR's tightened clinical evaluation requirements for Class II devices are elevating biocompatibility documentation burdens for polyurethane and silicone formulations. Manufacturers must now submit comprehensive biological safety data for each material variant, extending certification timelines and favoring incumbent firms with established technical files over emerging competitors seeking initial market entry.
Integrated delivery networks are consolidating vascular access device procurement through dedicated sales force relationships embedded in major IDN procurement committees. This concentration is most visible in Germany, where university hospital purchasing alliances are standardizing on ultrasound-guided insertion systems and bundling catheter, port, and accessory contracts to extract volume discounts and lock in multi-year supply agreements.
Vascular Access Systems Market Segmentation
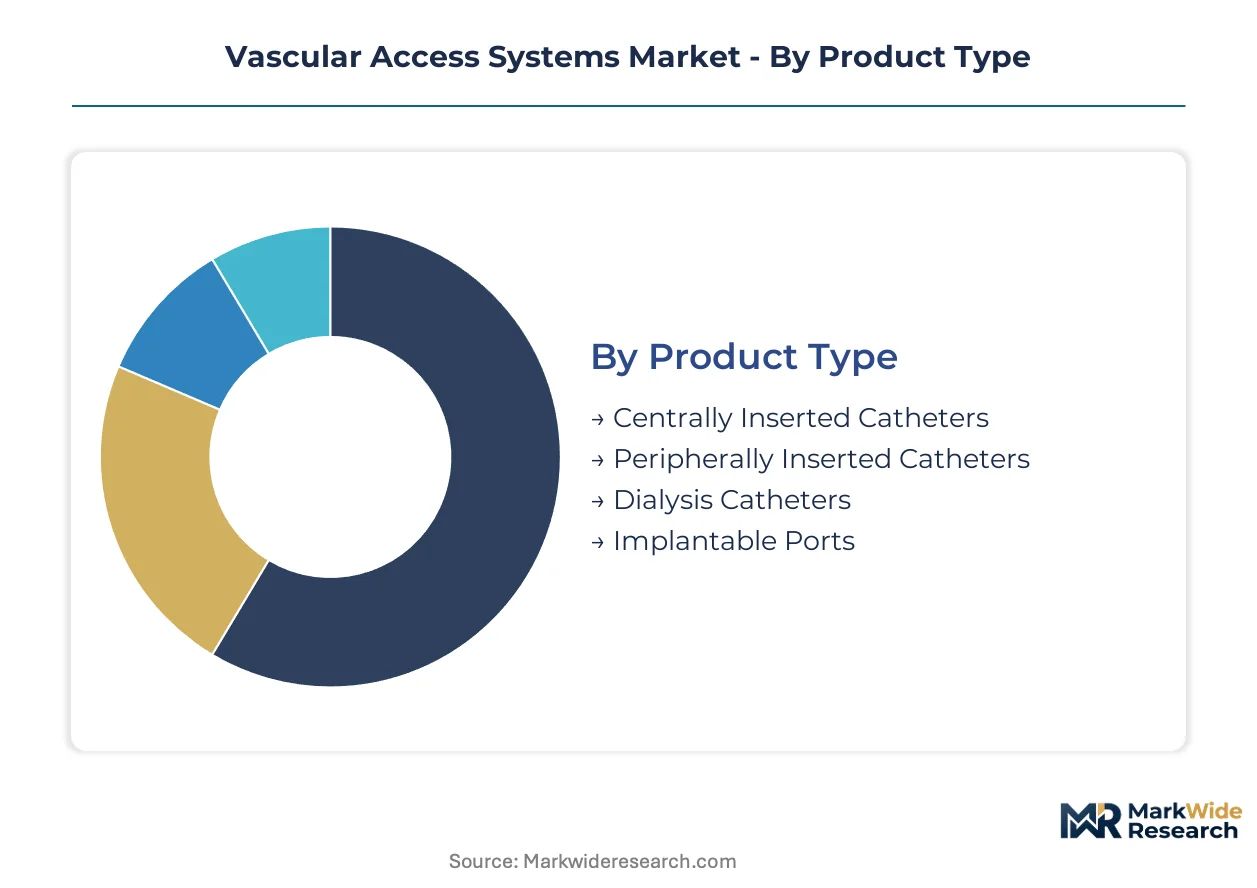
Vascular access systems serve divergent clinical workflows spanning acute ICU interventions to chronic home-based therapy. Segmentation reveals how material selection, insertion technology, and care setting interact to determine pricing power and procurement concentration across the value chain.
Product Type:
Product categories align with dwell time requirements and procedural complexity across the therapeutic use-case spectrum.
- Centrally Inserted Catheters:These devices feature radiopaque polyurethane construction with durometer ratings between 65A and 85A for kink resistance in high-flow ICU applications. Demand concentrates in United States academic medical centers where extended dwell times justify premium ASPs for triple-lumen configurations.
- Peripherally Inserted Catheters:Shorter-term venous access for intermediate-duration therapy employs softer 55A-70A durometer formulations prioritizing vessel compliance over structural rigidity. German university hospitals are consolidating purchasing for ultrasound-guided placement bundles, standardizing these devices across general ward protocols.
- Dialysis Catheters:High-flow dual-lumen designs accommodate hemodialysis exchange volumes with specialized tip geometries reducing recirculation rates.
- Implantable Ports:Subcutaneous reservoir systems with titanium or plastic housings enable long-term chemotherapy delivery through central venous access.
The dominant share belongs to Centrally Inserted Catheters, while Peripherally Inserted Catheters is closing the gap fastest.
End User:
Customer concentration tracks reimbursement frameworks and capital equipment requirements across care delivery models.
- Hospitals:Integrated delivery networks with captive polymer compounding partnerships capture volume discounts on catheter bundles. United States IDN procurement committees are embedding dedicated vascular access specialists to standardize insertion protocols and reduce bloodstream infection liability.
- Home Healthcare:Patient self-administration training creates recurring revenue streams where manufacturers capture value beyond initial device sales through education and remote monitoring services.
- Ambulatory Surgery Centers:Same-day discharge protocols favor single-lumen devices with simplified insertion requirements and lower per-procedure material costs.
- Clinics:Oncology and infusion centers prioritize implantable ports for long-term therapy regimens with minimal maintenance intervals.
Hospitals command the largest volume position, though Home Healthcare is expanding most quickly as reimbursement shifts toward site-neutral payment models.
Material:
Material selection reflects the tension between regulatory scrutiny of legacy plasticizers and performance requirements for specific clinical applications.
- Polyurethane:Thermoplastic formulations with tunable durometer ratings between 55A and 85A balance kink resistance with vessel compliance. FDA and ECHA joint scrutiny of phthalate alternatives is accelerating transitions toward aliphatic TPU grades with established biocompatibility documentation under EU MDR clinical evaluation requirements.
- Silicone:Platinum-cured elastomers maintain dominance in implantable ports where long-term biostability and low thrombogenicity justify higher material costs despite inferior tensile strength versus polyurethane alternatives.
- PVC:Legacy formulations face accelerated phase-out as EPA and ECHA regulations restrict phthalate plasticizer content in devices with patient contact duration exceeding 24 hours.
- Acrylonitrile Butadiene Styrene:Rigid polymer housings for port chambers and catheter hubs provide structural integrity without direct blood contact requirements.
Polyurethane holds the leading position by value, while silicone maintains defensive share in long-dwell implantable applications.
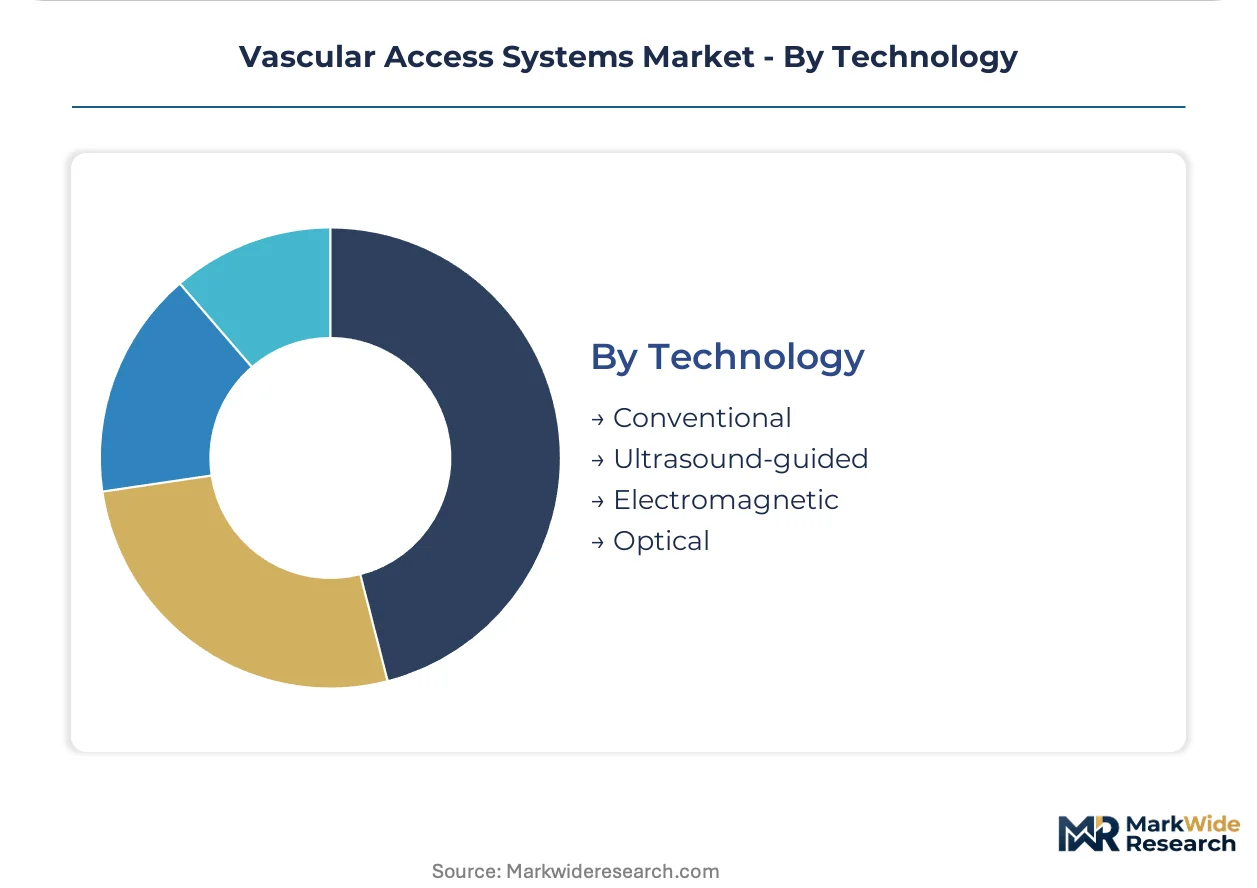
Technology:
Insertion guidance technology segments by capital intensity and evidence base for routine versus complex anatomical placements.
- Ultrasound-guided:Real-time vessel visualization reduces placement attempts and mechanical complication rates. German university hospital purchasing alliances are standardizing on these systems and bundling catheter contracts to extract multi-year supply agreements.
- Conventional:Landmark-based anatomical positioning remains standard for experienced operators in resource-constrained settings without capital equipment requirements.
- Electromagnetic:Navigation systems add cost without proven superiority in routine placements, constraining adoption to complex anatomical cases with variant vessel architecture.
- Optical:Near-infrared vein visualization assists peripheral cannulation in patients with difficult venous access, primarily deployed in pediatric and bariatric populations.
Conventional methods retain the highest procedure volume, yet Ultrasound-guided technology is gaining share fastest as training protocols standardize across tertiary care networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements and EU MDR clinical evaluation standards are tightening material biocompatibility documentation across major markets. Germany, the United States, Japan, China, and the United Kingdom concentrate purchasing power for advanced catheter systems.
United States
Oncology clinic networks are expanding implantable port adoption for long-term chemotherapy delivery. FDA 510(k) clearance pathways for Class II devices now demand comprehensive biological safety data for each polyurethane and silicone formulation variant. Academic medical centers in Boston and the Research Triangle are piloting antimicrobial coatings for routine central line insertions.
Germany
University hospitals are consolidating purchasing for ultrasound-guided catheter systems through dedicated procurement alliances. ECHA scrutiny of phthalate alternatives under REACH regulations accelerates transitions toward aliphatic TPU grades with established biocompatibility dossiers. The Rhine-Ruhr metropolitan region anchors catheter manufacturing clusters serving tertiary care standardization initiatives.
Japan
PMDA quality management system requirements favor manufacturers with established technical files for silicone implantable ports. METI incentives for domestic medical device production strengthen supply chain resilience for platinum-cured elastomer formulations. Osaka-based polymer engineering specialists concentrate durometer specification expertise for long-dwell applications.
China
NMPA biocompatibility standards for imported Class II devices are elevating documentation burdens for foreign catheter manufacturers seeking market entry. MIIT industrial upgrading programs support domestic TPU compounding capacity for radiopaque polyurethane catheter production. Yangtze River Delta medical device clusters are absorbing technology transfer partnerships with European coating specialists.
United Kingdom
NHS procurement frameworks are embedding vascular access specialists within integrated care systems to standardize insertion protocols and reduce bloodstream infection liability. MHRA post-Brexit regulatory alignment with EU MDR clinical evaluation requirements maintains equivalent biocompatibility documentation standards. London and Southeast hospital networks are consolidating purchasing for closed-system transfer devices addressing risk management priorities.
Vascular Access Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates around vertically integrated polymer compounders, dedicated vascular access sales organizations, and infection control technology specialists. Three archetypes dominate: balance-sheet-heavy lessors of ultrasound equipment, captive polymer producers controlling input costs, and closed-system engineers reducing hospital liability exposure. Competitive moves center on multi-year supply agreement lock-ins with integrated delivery networks and regulatory dossier accumulation under tightened FDA and ECHA standards.
Among United States-based diversified medical technology corporations, Becton, Dickinson and Company and Teleflex Incorporated exemplify channel-controlling archetypes through embedded sales force relationships with major IDN procurement committees. ICU Medical, Inc. occupies a specialist position within the infection control tier, representing the closed-system engineering approach to bloodstream infection liability reduction. Japanese and German competitors including Terumo Corporation and B. Braun SE anchor regional manufacturing positions serving domestic hospital consolidation trends.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical, Inc. |
| B. Braun SE |
| Medtronic |
| AngioDynamics, Inc. |
| Terumo Corporation |
| Cook Medical |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Undercapacity in aliphatic TPU compounding across the Rhine-Ruhr corridor is driving polyurethane catheter manufacturers toward captive polymer sourcing or premium spot-market purchases, compressing margins for non-integrated producers while concentrating pricing power with vertically integrated incumbents.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked versus uncertified) creates the primary spread across catheter pricing tiers, with antimicrobial-coated devices commanding premium positioning against standard polyurethane formulations. Three-tier pricing structure across premium, standard, and economy levels reflects durometer specification precision and biocompatibility documentation depth. Cost compression in standard-grade peripherally inserted catheters is intensifying because German university hospital purchasing alliances extract volume discounts through multi-year supply agreements. Ambulatory surgery centers exhibit the highest price sensitivity due to same-day discharge protocols and simplified insertion requirements, while United States academic medical centers prioritize infection reduction metrics over per-unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for radiopaque additive sourcing, forcing catheter manufacturers to qualify alternative suppliers or absorb margin impact. Manufacturing concentrates in Germany, the United States, and Japan, with each hub serving distinct regulatory filing requirements and hospital procurement frameworks. Raw material dependencies center on aliphatic thermoplastic polyurethane pellets, platinum-cured silicone elastomers, and barium sulfate radiopaque fillers. Single-source vulnerability in specialized durometer compounding creates bottlenecks for novel catheter formulations seeking rapid scale-up. Distribution runs through integrated delivery network procurement committees and group purchasing organizations, with direct-to-hospital contracting expanding for ultrasound-guided insertion system bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular access systems market functions as a service-attach opportunity where patient self-administration training and remote monitoring subscriptions expand recurring revenue faster than hardware sales alone.
For Market Incumbents: Build regulatory dossier moats by accumulating EU MDR technical files and FDA 510(k) clearances across polyurethane formulation variants before smaller competitors exhaust compliance resources. Consolidate polymer compounding partnerships in the Rhine-Ruhr region to secure aliphatic TPU supply amid ECHA phthalate restrictions. Channel control through embedded sales forces in major IDN procurement committees remains the critical lever against emerging coating specialists.
For New Entrants and Emerging Players: Pursue home healthcare self-administration segments where patient training services create recurring revenue streams beyond commoditized catheter hardware. Target oncology infusion centers in the United States seeking implantable port alternatives with extended dwell times and reduced maintenance intervals. Differentiate through closed-system transfer device integration that addresses hospital bloodstream infection liability priorities in competitive bidding environments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultrasound-guided insertion equipment leasing as asset-light models concentrate purchasing power among balance-sheet-heavy integrated delivery networks. Long-term viability over the next decade hinges on regulatory dossier depth rather than manufacturing scale alone. Acquisition candidates with established EU MDR technical files and FDA quality system certifications offer defensive positioning. Monitor German university hospital purchasing alliance contract announcements as inflection indicators for vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Accumulation | Accelerates market access for polyurethane catheter variants under tightened clinical evaluation requirements. |
| Hospital System Partnership | Locks in multi-year supply agreements with German university hospital purchasing alliances standardizing ultrasound-guided protocols. |
| Software Companion Development | Enables remote monitoring services for home healthcare patients self-administering vascular access devices. |
| Reimbursement Strategy | Aligns catheter coating innovations with CMS and private payer frameworks for ambulatory placement codes. |
| CE Marking Pathway | Facilitates market entry across European territories under harmonized biocompatibility documentation standards. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and vascular access specialists anchored the qualitative base for this study. Primary interviews with clinicians and procurement directors across United States academic medical centers and German university hospitals combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS reimbursement data. Bottom-up unit economics modeling and top-down market sizing triangulation ensured cross-verification of segment-level demand estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic and conservative cases reflecting regulatory approval velocity and hospital capital expenditure cycles. Segmentation dimensions modeled include product type (centrally inserted versus peripherally inserted catheters, implantable ports, dialysis catheters), material formulation (polyurethane durometer grades, silicone elastomers), end-user setting (hospitals, home healthcare, ambulatory surgery centers, clinics), and insertion technology (ultrasound-guided, conventional, electromagnetic, optical). CAGRs derived from historical procedure volume trends and ASP trajectory analysis incorporated infection control protocol adoption curves and antimicrobial coating penetration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by balance-sheet-heavy lessors or vertically integrated polymer compounders would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Cardiac Surgery Devices Market