
 Atrial Fibrillation (AF) Ablation Market | 2026-2036
Atrial Fibrillation (AF) Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Atrial Fibrillation (AF) Ablation Market Analytics
The AF ablation device landscape is pivoting between premium integrated mapping-ablation platforms and commodity single-use catheters. Abbott Laboratories leverages its electrophysiology portfolio to sustain integrated system sales across North American hospital networks. Medtronic plc anchors its position through cryoablation technology leadership and extensive clinical validation programs.
Atrial fibrillation ablation encompasses catheter-based and surgical procedures that destroy cardiac tissue triggering arrhythmias, typically using radiofrequency energy at 450-500 kHz or cryothermal energy at minus 40 to minus 70 degrees Celsius to electrically isolate pulmonary vein ostia. The primary purpose is restoring sinus rhythm and reducing stroke risk in patients refractory to antiarrhythmic drug therapy. Catheters and mapping systems capture the dominant margin pools, while cryoablation devices represent the fastest-expanding technology segment due to shorter physician learning curves. RF ablation maintains mature procedural volume leadership, though pulsed field ablation is displacing conventional thermal modalities in premium accounts.
The FDA governs device approval pathways through premarket notification and premarket approval processes, while the EU MDR imposes strengthened clinical evidence requirements for electrophysiology devices entering European markets. Japan's PMDA maintains distinct technical standards for radiofrequency generators that shape product localization strategies for entrants. Stakeholders must monitor reimbursement decisions by the CMS National Coverage Determination process and parallel health technology assessments in Germany and Japan, as these will determine whether pulsed field ablation platforms achieve standard-of-care status or remain restricted to select centers.
Market Dynamics
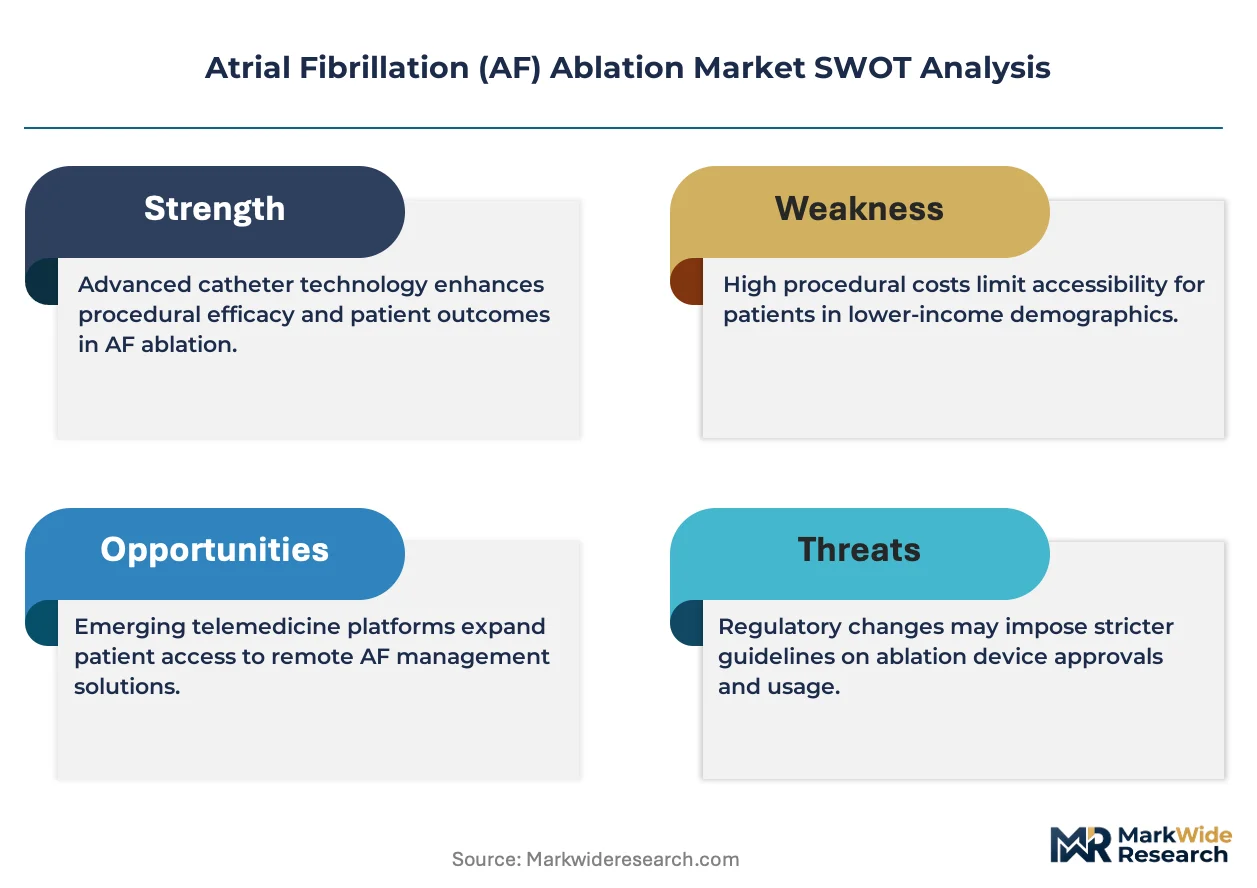
Pulsed field ablation technology is compressing the competitive window for thermal modalities across tertiary cardiac centers, forcing incumbent catheter manufacturers to accelerate platform refresh cycles while hospital procurement teams renegotiate capital equipment terms.
Growth Catalysts
- CMS National Coverage Determination expansion:Reimbursement pathway clarity for novel energy modalities accelerates hospital capital planning cycles and reduces adoption friction among electrophysiology departments.
- Japan's tertiary cardiac center clustering:Concentrated procedural volume in designated high-volume centers creates economies of scale that justify premium mapping-ablation platform investments.
- Cryoablation learning curve compression:Shorter physician training requirements compared to radiofrequency techniques expand the addressable operator pool and procedural throughput.
Market Restraints
- Single-use catheter input cost volatility:Specialized polymer and electrode material supply chains face pricing pressure from medical-grade commodity markets.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance obligations extend time-to-revenue for new electrophysiology device entrants.
- Radiofrequency generator technical standard fragmentation:Japan's PMDA maintains distinct electrical safety specifications that force product localization and duplicate certification costs.
Strategic Opportunities
- Germany's health technology assessment pathway:Early engagement with IQWiG evaluation processes positions pulsed field platforms for favorable reimbursement classification ahead of market entry.
- Integrated mapping-ablation system convergence:Combination of high-density electroanatomical mapping with single-shot ablation catheters reduces procedure time and capital footprint.
- Outpatient electrophysiology lab expansion:Ambulatory surgical center certification for select ablation procedures opens lower-acuity patient segments.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship program capacity limits operator supply expansion despite procedural demand growth.
- Legacy RF platform integration complexity:Hospital IT and inventory systems require reconfiguration to accommodate mixed thermal and non-thermal catheter workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrial Fibrillation (AF) Ablation Market |
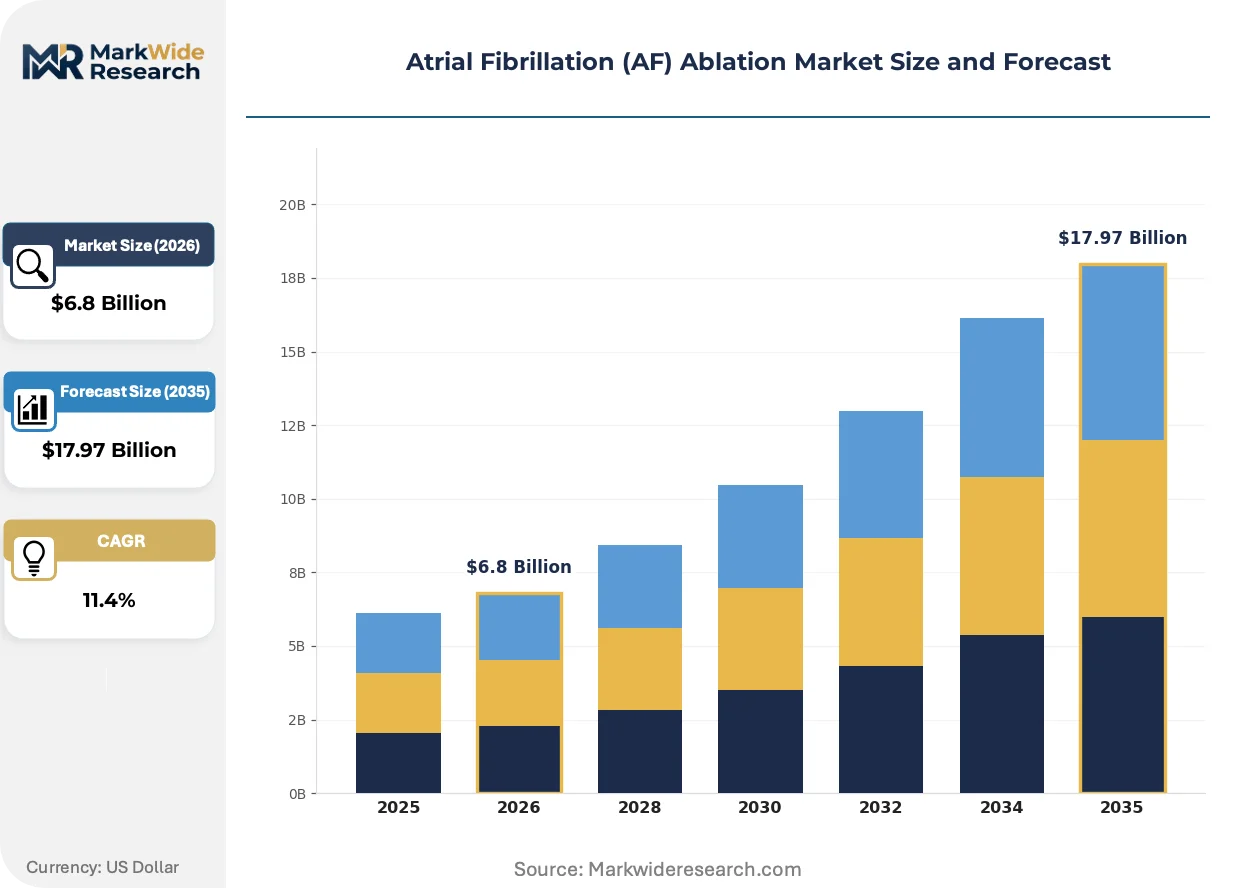
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, RF Energy Devices, Cryoablation Devices, Mapping Systems End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Institutions Technology: RF Ablation, Cryoablation, Laser Ablation, Hybrid Techniques Application: Persistent AF, Paroxysmal AF, Long-standing AF, Atrial Flutter |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, Medtronic plc, AtriCure Inc., Biotronik SE & Co. KG, MicroPort Scientific Corporation, CardioFocus Inc., Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrial Fibrillation (AF) Ablation Market Evolving Landscape
Ablation technology is bifurcating between single-shot pulmonary vein isolation systems and precision focal tools, with energy modality selection increasingly determined by hospital procedural volume tiers rather than physician preference alone.
Pulsed field ablation is consolidating competitive positioning among high-volume electrophysiology programs by delivering durable lesion sets without thermal collateral damage. Tertiary cardiac centers in the United States and Germany are prioritizing platform conversions during planned capital replacement cycles. This technology is consolidating vendor relationships as hospitals standardize on integrated systems to reduce catheter inventory complexity and training overhead.
The EU MDR imposes strengthened clinical evidence requirements for electrophysiology devices entering European markets. Manufacturers must now submit prospective registry data and extended follow-up outcomes for novel ablation technologies. Germany's notified body landscape has consolidated, extending review timelines and favoring established players with dedicated regulatory affairs infrastructure.
Hospital procurement teams are unbundling after-sales service contracts from capital equipment purchases and negotiating direct technical support agreements. Electrophysiology lab directors increasingly specify performance-based service level agreements tied to system uptime metrics. This shift is most visible in United States hospital networks where centralized supply chain functions have gained negotiating authority over departmental capital requests.
Atrial Fibrillation (AF) Ablation Market Segmentation
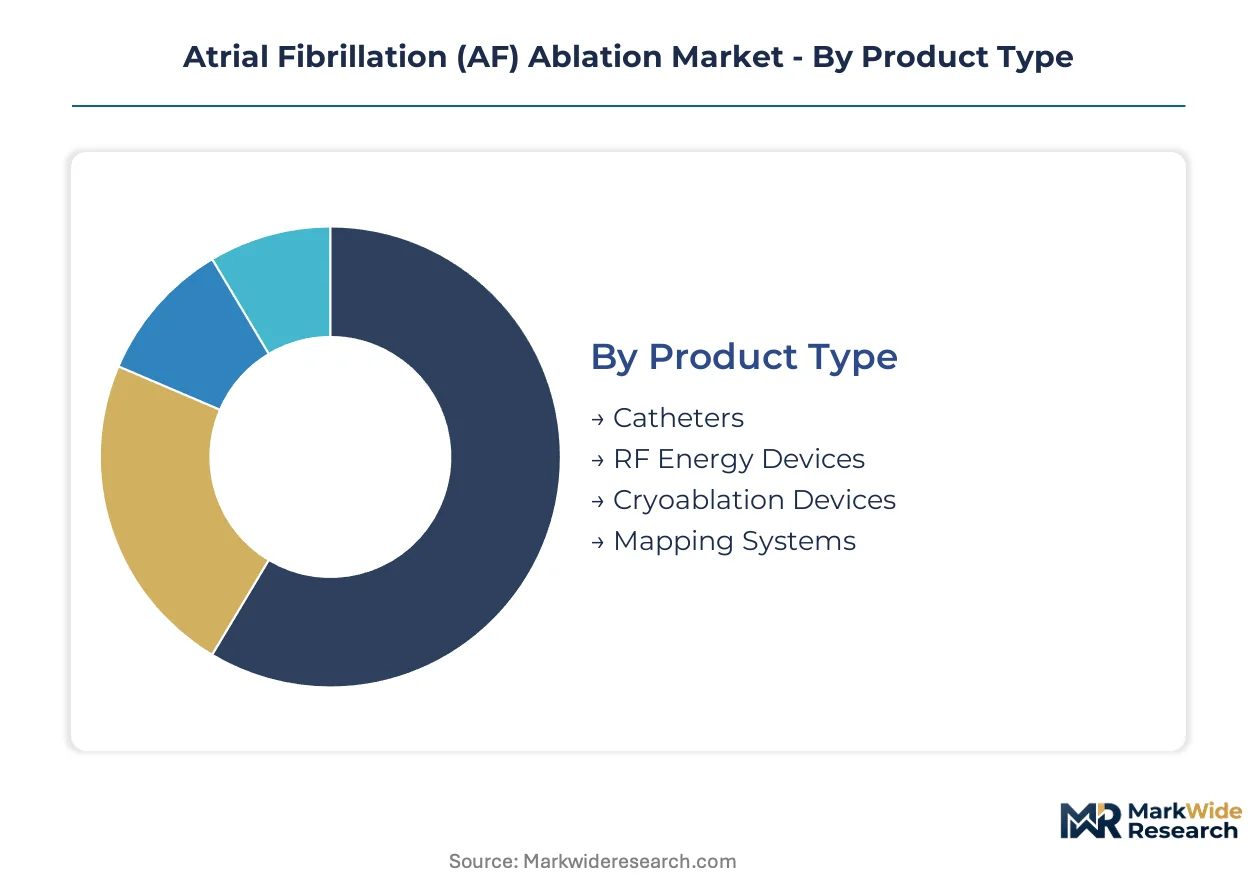
AF ablation market segmentation reveals how regulatory pathways, capital intensity, and procedural complexity fragment commercial opportunity across distinct product categories and care settings. Understanding these divisions clarifies where FDA premarket approval burdens concentrate versus where CE marking under EU MDR shapes competitive entry.
Product Type:
Catheter-based platforms face divergent certification timelines, with single-use disposable catheters clearing through FDA 510(k) pathways while integrated mapping-ablation systems require PMA submissions and extended clinical follow-up.
- Catheters:Single-use devices incorporating electrode arrays and steering mechanisms deliver radiofrequency or pulsed field energy to cardiac tissue. Demand clusters in tertiary cardiac centers across the United States, Germany, and Japan where procedural volumes justify high catheter throughput. FDA 510(k) clearance pathways enable faster commercialization than capital equipment categories.
- RF Energy Devices:Radiofrequency generators operating at 450-500 kHz supply controlled thermal energy through interface cables and dispersive pads. Procurement concentrates in hospital electrophysiology departments upgrading legacy systems, with Japan's PMDA imposing distinct electrical safety specifications that force product localization.
- Cryoablation Devices:Nitrous oxide or argon-based systems deliver minus 40 to minus 70 degrees Celsius cryothermal energy through balloon catheters.
- Mapping Systems:Electroanatomical navigation platforms integrating magnetic or impedance-based localization with 3D cardiac reconstruction.
Catheters sit at the top of the volume ranking, with cryoablation devices climbing the fastest.
End User:
Capital equipment purchasing authority and reimbursement coding sophistication determine which care settings access premium ablation platforms versus commodity catheter supplies.
- Hospitals:Tertiary cardiac centers with dedicated electrophysiology labs perform the majority of complex AF ablations, leveraging integrated mapping-ablation platforms and maintaining 24-hour procedural capacity. CMS National Coverage Determination pathways and parallel German G-DRG reimbursement codes shape capital investment cycles.
- Cardiology Clinics:Outpatient facilities with diagnostic electrophysiology capabilities but limited ablation infrastructure concentrate on patient screening and post-procedural monitoring.
- Ambulatory Surgical Centers:Lower-acuity settings expanding into electrophysiology through streamlined certification pathways.
- Research Institutions:Academic medical centers conducting clinical trials and physician training programs.
Hospitals command the dominant revenue share, though ambulatory surgical centers are expanding their procedural footprint most aggressively.
Technology:
Energy modality selection increasingly follows hospital procedural volume tiers rather than physician preference, with high-volume centers standardizing on next-generation platforms.
- RF Ablation:Mature thermal technology using resistive heating at electrode-tissue interfaces maintains procedural volume leadership across established electrophysiology programs. The installed base of RF generators and physician familiarity sustain its position in mid-tier hospitals.
- Cryoablation:Balloon-based cryothermal pulmonary vein isolation delivers single-shot lesion sets with shorter physician learning curves than point-by-point RF techniques. Tertiary centers in the United States and Germany are prioritizing platform conversions during capital replacement cycles.
- Laser Ablation:Optical energy delivery through balloon-diffuser systems offers precise lesion control.
- Hybrid Techniques:Combined surgical-catheter approaches for persistent AF cases.
RF ablation retains the largest procedural base, while cryoablation platforms are gaining installed base most rapidly.
Application:
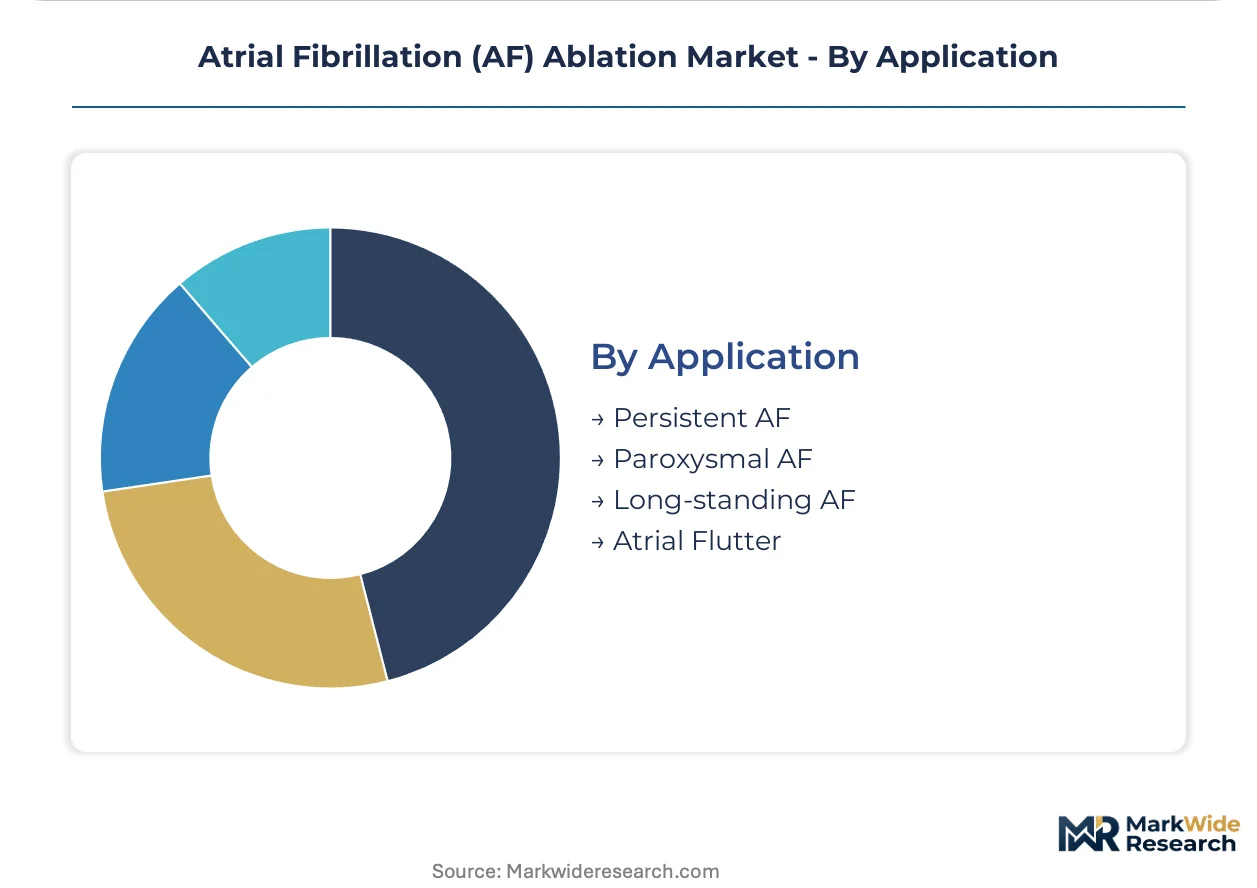
AF subtype classification drives technology selection and reimbursement complexity, with persistent cases requiring more advanced energy modalities than paroxysmal presentations.
- Persistent AF:Continuous arrhythmia lasting beyond seven days demands durable pulmonary vein isolation plus additional substrate modification. Cases concentrate in high-volume tertiary centers equipped with advanced mapping systems and hybrid surgical capability.
- Paroxysmal AF:Self-terminating episodes within seven days represent the most common ablation indication. Catheter-based pulmonary vein isolation in electrophysiology labs constitutes standard care.
- Long-standing AF:Continuous arrhythmia exceeding twelve months requires extensive ablation strategies.
- Atrial Flutter:Macro-reentrant tachycardia with distinct cavotricuspid isthmus ablation protocols.
Paroxysmal AF generates the highest procedure count, with persistent AF applications showing the steepest expansion trajectory as pulsed field ablation enables safer substrate modification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiologist density and tertiary cardiac center certification standards concentrate procedural capacity in select markets. Japan's PMDA electrical safety specifications and Germany's IQWiG assessment pathways create distinct localization requirements. The United States, Germany, Japan, and Switzerland host the dominant high-volume ablation programs.
United States
Tertiary cardiac centers in Cleveland, Houston, and Boston maintain the highest AF ablation volumes per operator. CMS National Coverage Determination pathways for novel energy modalities accelerate hospital capital planning cycles. The Texas Medical Center and Mayo Clinic Rochester anchor integrated mapping-ablation platform adoption, with procurement teams renegotiating service contracts separately from equipment purchases.
Germany
Designated high-volume electrophysiology centers in Munich, Heidelberg, and Hamburg concentrate over half of national AF ablation procedures. IQWiG health technology assessments determine G-DRG reimbursement classification for pulsed field ablation platforms. Baden-Württemberg and Bavaria lead capital equipment replacement cycles, with university hospitals prioritizing single-shot cryoablation conversions.
Japan
PMDA distinct technical standards for radiofrequency generators force dedicated product localization for market entry. Tokyo, Osaka, and Nagoya clusters concentrate electrophysiologist training programs and procedural volume. The Japan Arrhythmia Society certification requirements shape operator supply constraints, with Kanto and Kansai regions hosting designated advanced ablation centers.
Switzerland
Swissmedic maintains streamlined device approval pathways that attract early-stage pulsed field ablation clinical trials. Zurich and Geneva university hospitals serve as referral hubs for complex persistent AF cases across Alpine corridor markets. The country's concentrated private hospital networks enable rapid platform standardization decisions across Basel, Bern, and Lausanne electrophysiology departments.
Atrial Fibrillation (AF) Ablation Market Competitive Landscape
Capital-heavy integrated system manufacturers compete with asset-light catheter specialists across distinct margin tiers. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with electrophysiology divisions, pure-play cardiac ablation device firms, and emerging pulsed field technology entrants. Consolidation pressures intensify as hospitals standardize on single-vendor platforms to reduce training overhead and inventory complexity. Geographic expansion into Japan's PMDA-regulated market and strategic partnerships for cryoablation distribution rights represent dominant competitive moves.
Among diversified medtech conglomerates, Abbott Laboratories and Medtronic plc exemplify integrated portfolio strategies spanning mapping systems, ablation catheters, and generator hardware. Boston Scientific Corporation occupies a position within the specialized cardiac rhythm management tier, anchoring competitive positioning through electrophysiology-focused R&D concentration. These three firms represent the dominant capital equipment and disposable catheter supply positions across United States hospital networks and German tertiary cardiac centers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Medtronic plc |
| AtriCure Inc. |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| CardioFocus Inc. |
| Acutus Medical |
| Others |
Value Network & Pricing Analysis
Integrated mapping-ablation platform premiums versus commodity catheter pricing creates a bifurcated procurement landscape where United States hospital networks exploit capital replacement cycles to unbundle service contracts, while German tertiary centers leverage IQWiG assessment timing to compress capital equipment margins and Japanese PMDA localization requirements inflate landed costs for RF generator imports.
Pricing Analysis
Bundled service contracts are unbundling from capital equipment purchases as United States hospital procurement teams negotiate direct technical support agreements with performance-based SLAs tied to system uptime metrics. Price differentiation rests on after-sales service bundling and FDA PMA certification tier, with integrated platforms commanding premiums over 510(k)-cleared catheters. Pricing pressure stems from pulsed field ablation platform conversions forcing incumbent thermal modality discounting. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiac centers with dedicated electrophysiology labs show least.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan operate hub-and-spoke patterns feeding tertiary cardiac clusters. Manufacturing concentrates in the United States, Ireland, and Costa Rica for catheter assemblies. Specialized polymer electrodes and nitrous oxide cryogen tanks constitute critical input dependencies. Single-source vulnerability around medical-grade polymer supply chains poses structural risk. Distribution runs through GPO contracts and direct hospital agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AF ablation market reads as a late-cycle quality story where pulsed field ablation safety profiles are shifting hospital procurement toward premium integrated platforms over commodity thermal modalities.
For Market Incumbents: Lock in electrophysiology lab standardization decisions during planned capital replacement cycles by offering performance-based service level agreements that reduce hospital inventory complexity. Defend against pulsed field entrants by accelerating cryoablation platform refresh cycles and securing exclusive GPO contracts. Vertical integration into catheter electrode manufacturing mitigates polymer supply volatility. For New Entrants and Emerging Players: Pulsed field ablation technology-first wedges open procurement at ambulatory surgical centers seeking outpatient electrophysiology certification with lower capital footprint requirements. Target mid-tier United States hospital networks lacking integrated mapping-ablation platforms. White-space exists in hybrid surgical-catheter persistent AF protocols. Go-to-market through direct technical support partnerships bypasses incumbent GPO lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital standardization on single-vendor platforms reduces viable independent catheter suppliers. Five-to-ten year viability favors diversified medtech conglomerates with dedicated regulatory affairs infrastructure for EU MDR compliance. Target acquisition archetype: pure-play pulsed field technology firms with PMA-submitted platforms. Signal to watch: CMS National Coverage Determination expansion for novel energy modalities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submissions for pulsed field platforms secure premium reimbursement classification ahead of thermal modality commoditization. |
| CE Marking Under EU MDR | Strengthened clinical evidence requirements favor established players with dedicated European regulatory infrastructure. |
| Hospital System Partnership | Exclusive supply agreements with Texas Medical Center or Mayo Clinic Rochester anchor platform standardization decisions. |
| Software Companion Development | Electroanatomical mapping algorithm integration reduces procedure time and locks in catheter-consumable pull-through. |
| Reimbursement Strategy | Early IQWiG engagement positions pulsed field platforms for favorable G-DRG classification in German tertiary centers. |
Research Methodology
Direct dialogue with electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) and PMA filings, CMS National Coverage Determination records, IQWiG assessment documents, and Japan PMDA technical standards. Bottom-up catheter volume estimates triangulated against top-down capital equipment replacement cycle analysis.
Segmentation outputs across product type, end user, technology, and application dimensions fed into procedural volume modeling throughout the forecast period. CAGRs derived from electrophysiologist supply expansion constraints and pulsed field ablation adoption curve assumptions. Industry-specific inputs incorporated Japan Arrhythmia Society certification pipeline capacity and German high-volume center clustering patterns.
The model holds under stable reimbursement pathways and pulsed field safety profile validation; deviation in CMS coverage determination timing or EU MDR review timeline extension would shift capital equipment replacement assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
India Coronary Stent Market