
 Brake Shoe Market | 2026-2036
Brake Shoe Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Shoe Market Intelligence
The basis of competition in the brake shoe market is shifting, creating a divergence between high-performance ceramic shoes for OEMs and cost-effective organic formulations for the aftermarket. Premium suppliers like Brembo S.p.A. focus on material science innovation for performance vehicles and specialized applications. In contrast, major players such as Bosch leverage extensive distribution networks to serve both OEM and broad aftermarket segments with a tiered product portfolio. Federal-Mogul Motorparts competes by offering a wide range of replacement parts across multiple quality and price points.
A brake shoe is a crescent-shaped component featuring a friction material lining that is either bonded or riveted to a solid steel backing. It operates within a drum brake system, where hydraulic pressure forces the shoe outward against the inner surface of a rotating drum to generate friction and decelerate the vehicle. Non-asbestos organic formulations are prevalent in the passenger car segment due to their favorable cost and low-noise characteristics. Conversely, semi-metallic product types are standard for heavy-duty trucks and buses, where superior heat dissipation and durability are required.
Market access and material composition are directly shaped by safety and environmental regulations. The European Union's REACH framework restricts the use of certain chemicals in friction materials, while the EPA in the United States enforces strict limits on asbestos. In China, all brake components must adhere to mandatory GB standards for performance and safety. Consequently, manufacturers must continually adapt material formulations and production processes to navigate these divergent regional compliance requirements and performance benchmarks.
Market Dynamics
The brake shoe market's evolution is governed by a global regulatory push toward non-asbestos friction materials. This transition, driven by health and environmental mandates from bodies like the EPA in the United States, forces continuous material reformulation and creates divergent compliance pathways across regions.
Growth Catalysts
- Vehicle Fleet Expansion:A growing vehicle parc, particularly for light commercial vehicles in developing economies across Southeast Asia, directly fuels demand for replacement brake shoes in the high-volume aftermarket sector.
- Material Innovation:The industry-wide shift away from asbestos creates demand for alternative non-asbestos organic (NAO) and ceramic friction materials that offer improved performance, lower noise, and enhanced safety.
- Regulatory Mandates:Stricter safety and environmental standards, such as China's GB standards, compel vehicle manufacturers and repair shops to use certified, higher-quality brake components, phasing out substandard products.
Market Restraints
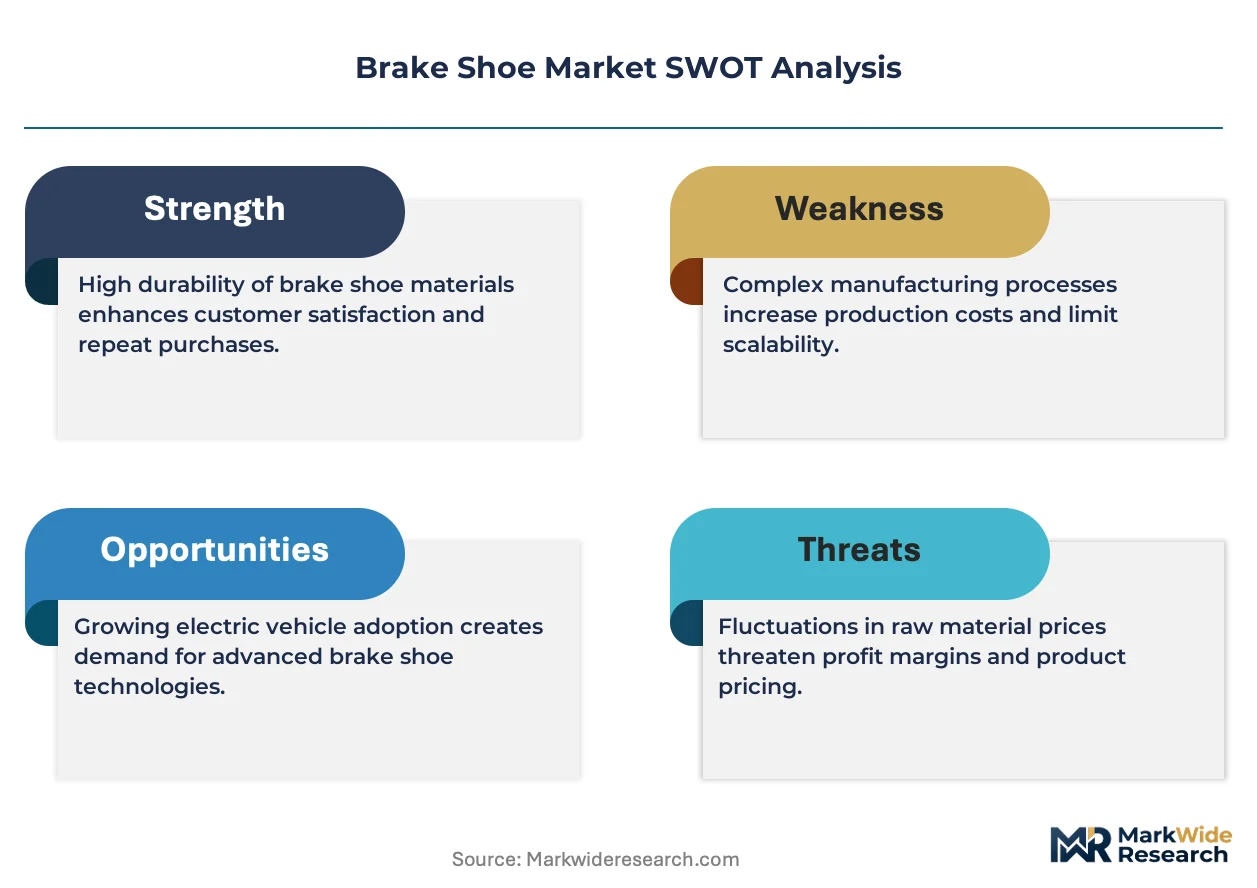
- Raw Material Volatility:The cost of key inputs for non-asbestos formulations, such as copper, aramid fibers, and specialized resins, is subject to price fluctuations that can compress manufacturer margins.
- Substitution by Disc Brakes:The increasing standardization of disc brake systems on all four wheels of new passenger cars and light trucks progressively shrinks the addressable OEM market for drum brake systems and their constituent shoes.
- Performance Trade-Offs:Friction material engineering involves inherent compromises; for example, semi-metallic shoes offer high-temperature durability for trucks but can produce more noise and dust than organic formulations preferred in passenger cars.
Strategic Opportunities
- Eco-Friendly Formulations:Developing and marketing low-copper or copper-free brake shoes offers a competitive advantage by preemptively meeting future environmental regulations, such as those emerging in specific US states.
- Electric Vehicle Applications:A specialized opportunity exists in creating brake shoes for electric vehicles that are optimized for low-dust emission and quiet operation, complementing the characteristics of regenerative braking systems.
- Untapped Aftermarket Geographies:The large and aging vehicle fleets in markets across Latin America and Africa, which heavily rely on drum brake technology, represent significant untapped potential for aftermarket suppliers.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face significant complexity and cost in ensuring products simultaneously comply with disparate regulations like the EU's REACH framework, US EPA guidelines, and country-specific certification marks.
- Aftermarket Counterfeiting:The prevalence of low-cost, uncertified, and counterfeit brake shoes, particularly in emerging markets, poses a major threat to brand reputation, public safety, and the profitability of legitimate suppliers.
- Capital-Intensive Retooling:Transitioning production lines from traditional asbestos-based processes to modern, environmentally compliant bonding and riveting techniques for non-asbestos materials requires substantial capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Shoe Market |
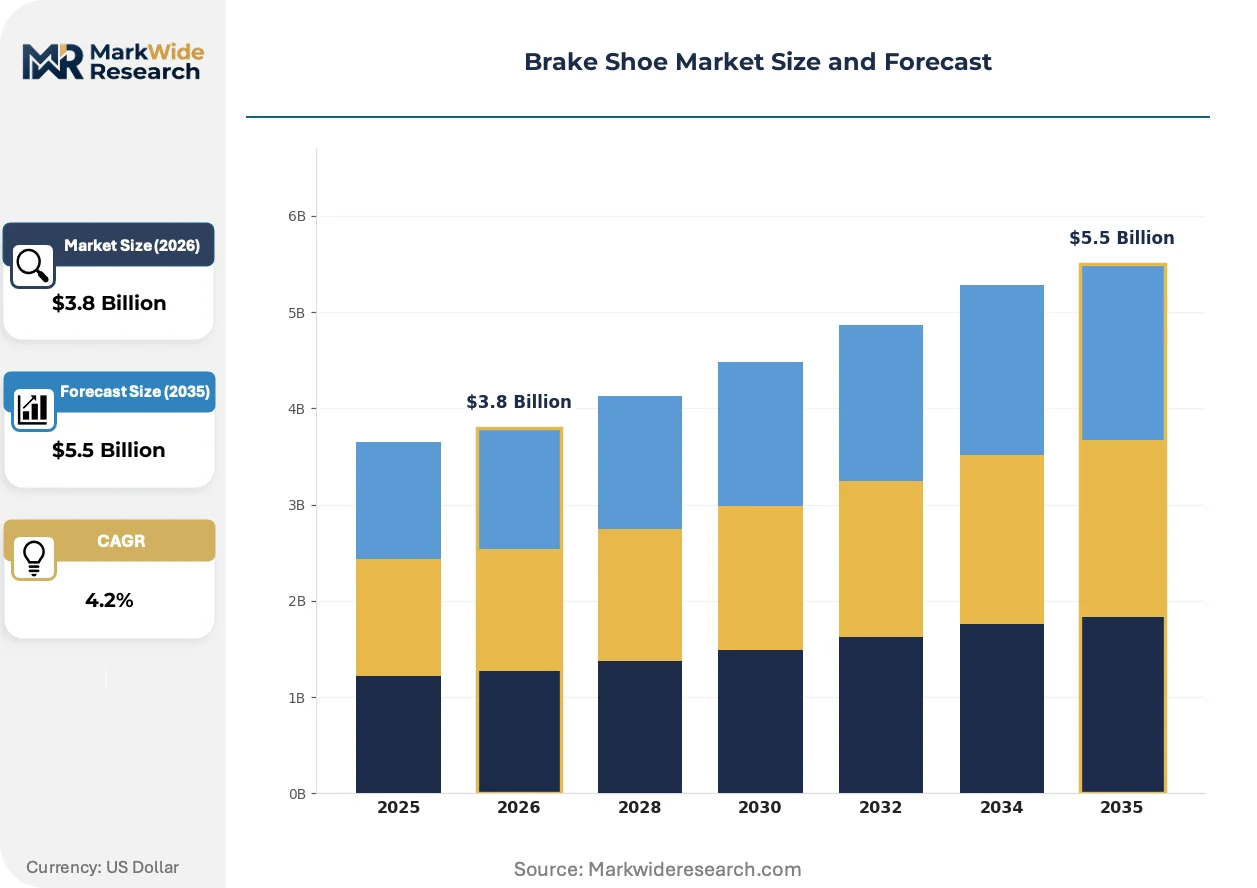
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Asbestos, Semi-Metallic, Organic, Ceramic, Sintered Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, Two Wheelers, Buses Application: Drum Brakes, Disc Brakes, Industrial Machinery, Agricultural Equipment, Construction Equipment Distribution Channel: OEM, Aftermarket, Online Retail, Authorized Dealers, Independent Garages |
| Companies Covered | Brembo S.p.A., Bosch, Akebono Brake Industry, ZF Friedrichshafen AG, Continental AG, Aisin Corporation, Mando Corporation, Federal-Mogul Motorparts, Nisshinbo Brake, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Shoe Market Strategic Shifts & Innovations
Material science innovation is the central theme, driven by the twin pressures of stringent environmental regulations and rising consumer expectations for performance and comfort. This compels a move away from one-size-fits-all solutions toward highly specialized friction material formulations.
Advanced friction material compounding allows for the precise tuning of brake shoe characteristics for specific vehicle weights, duty cycles, and performance envelopes. This approach is gaining traction rapidly within the OEM supply chain and for premium aftermarket lines. It is automating the development process, enabling engineers to systematically design materials that optimize the trade-offs between stopping power, noise, wear, and dust generation for a given application.
The European Union's REACH framework continues to be a powerful agent of change in material composition. This regulation restricts or bans certain chemicals used as binders, fillers, and friction modifiers in brake linings, forcing ongoing reformulation efforts across the supply chain. The heavy-duty truck and bus segment is particularly impacted, as it relies on specific compounds for extreme heat and wear resistance that are now under scrutiny.
A notable shift is occurring in aftermarket distribution, with independent repair shops and smaller distributors increasingly turning to e-commerce platforms for parts sourcing. This model challenges the dominance of traditional, multi-tiered wholesale distribution networks by offering greater price transparency and faster delivery times. This trend is most pronounced in the mature North American and European aftermarkets, where logistics and digital infrastructure enable efficient direct-to-installer fulfillment.
Brake Shoe Market Segmentation
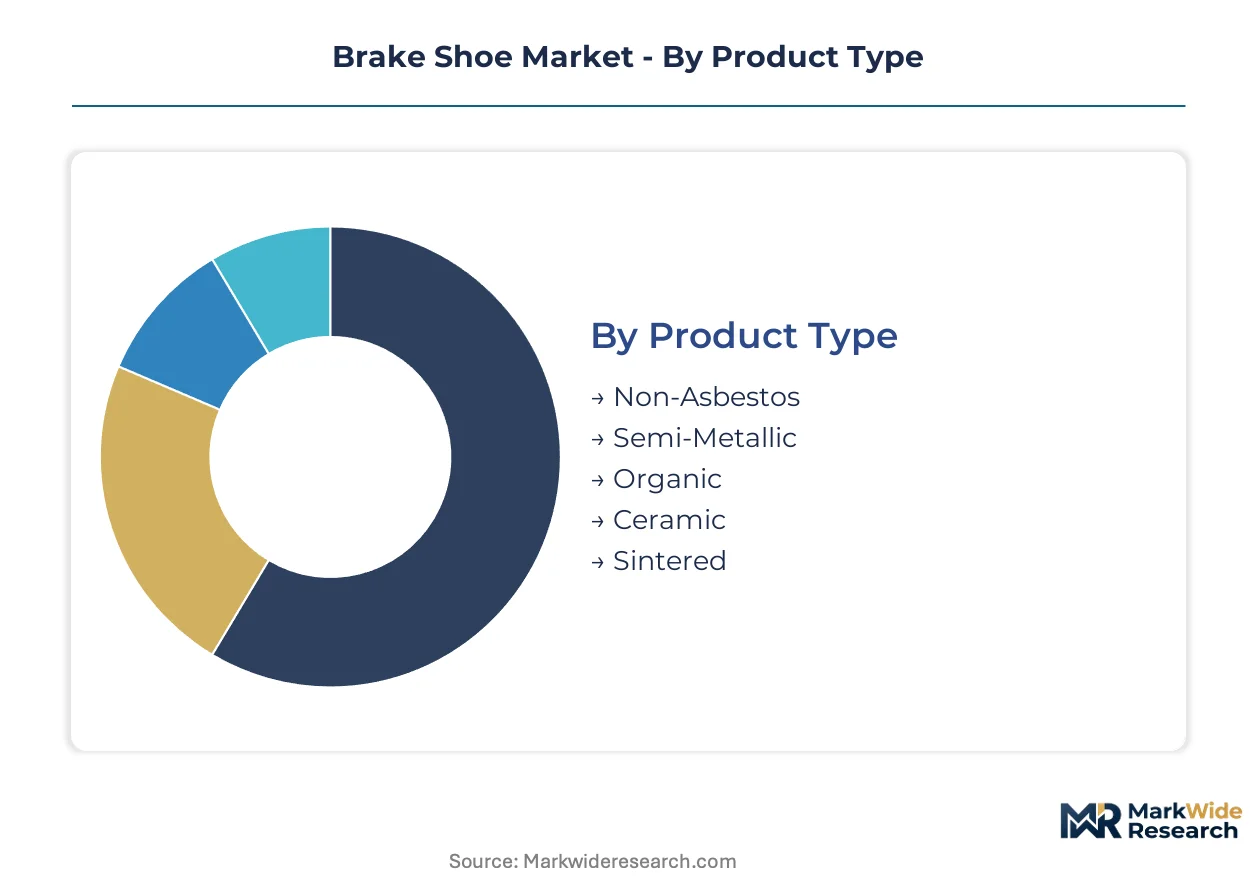
The brake shoe market segmentation provides a granular understanding of product differentiation, application nuances, and distribution pathways. Analyzing these segments reveals specific demand patterns and regulatory influences shaping product development and market access across diverse vehicle types and end-use sectors.
Product Type:
The certification burden significantly impacts product type selection, with various formulations requiring specific approvals for performance and environmental compliance, such as EPA guidelines in the United States or the EU's REACH framework.
- Non-Asbestos:These formulations, including Non-Asbestos Organic (NAO) and ceramic materials, represent the industry standard, driven by global health and environmental regulations. Demand concentrates in the passenger car and light commercial vehicle aftermarket, due to their balanced performance and regulatory compliance in regions like the European Union.
- Semi-Metallic:Comprising metallic fibers for enhanced friction and heat dissipation, semi-metallic shoes are critical for heavy-duty applications. This product type sees high demand in the heavy-duty truck and bus segments across North America and China, where superior stopping power and durability are paramount.
- Organic:Organic brake shoes offer cost-effectiveness and low noise characteristics, primarily serving the budget-conscious passenger car aftermarket.
- Ceramic:Ceramic formulations provide premium performance with minimal dust and quiet operation, typically specified for high-end passenger vehicles and specialized applications.
- Sintered:Sintered brake shoes are engineered for extreme conditions, offering robust performance in industrial machinery and off-road equipment.
Non-Asbestos sits at the top of the volume ranking, with Ceramic climbing the fastest.
Vehicle Type:
Demand for brake shoes varies considerably across vehicle types, reflecting differences in vehicle parc size, duty cycles, and regulatory requirements specific to each segment.
- Passenger Cars:This segment represents the largest volume consumer of brake shoes, driven by the vast global passenger vehicle fleet and routine replacement cycles. Non-asbestos organic formulations are prevalent, particularly in developing economies across Southeast Asia, due to their cost-effectiveness and low noise.
- Light Commercial Vehicles:Light commercial vehicles, including vans and pickups, demand durable and reliable brake shoes to handle frequent stops and varying loads. The aftermarket for these vehicles in countries like Indonesia and Vietnam shows significant growth, fueled by expanding logistics and service sectors.
- Heavy Duty Trucks:These vehicles require semi-metallic brake shoes for their superior heat resistance and longevity under extreme braking conditions.
- Two Wheelers:Two-wheelers utilize compact brake shoe designs, with demand concentrated in emerging markets where motorcycles are a primary mode of transport.
- Buses:Buses operate with high-wear braking systems, necessitating robust brake shoes that can withstand continuous heavy use in urban environments.
Passenger Cars dominate the market in terms of unit volume, while Light Commercial Vehicles exhibit strong expansion in developing regions.
Application:
The application segment delineates brake shoe usage based on the specific braking system or equipment, influencing material composition and performance specifications.
- Drum Brakes:Drum brakes remain a foundational application for brake shoes, especially on the rear axles of many passenger cars and light commercial vehicles. This application continues to drive significant aftermarket demand, particularly in regions with older vehicle fleets like Latin America and Africa.
- Disc Brakes:While disc brakes primarily use pads, some hybrid systems and specialized applications still incorporate drum brake mechanisms for parking brakes or specific vehicle designs. The progressive adoption of disc brakes on all four wheels for new vehicles gradually reduces the addressable OEM market for drum brake shoes.
- Industrial Machinery:Heavy industrial machinery, including cranes and forklifts, relies on robust brake shoes for precise control and safety in demanding operational environments.
- Agricultural Equipment:Tractors and other farm machinery utilize specialized brake shoes designed for durability and performance in varied terrain and weather conditions.
- Construction Equipment:Earthmovers and other construction vehicles require high-performance brake shoes capable of withstanding extreme loads and frequent braking cycles on job sites.
Drum Brakes maintain a substantial market share, whereas Industrial Machinery applications demonstrate consistent, specialized demand.
Distribution Channel:
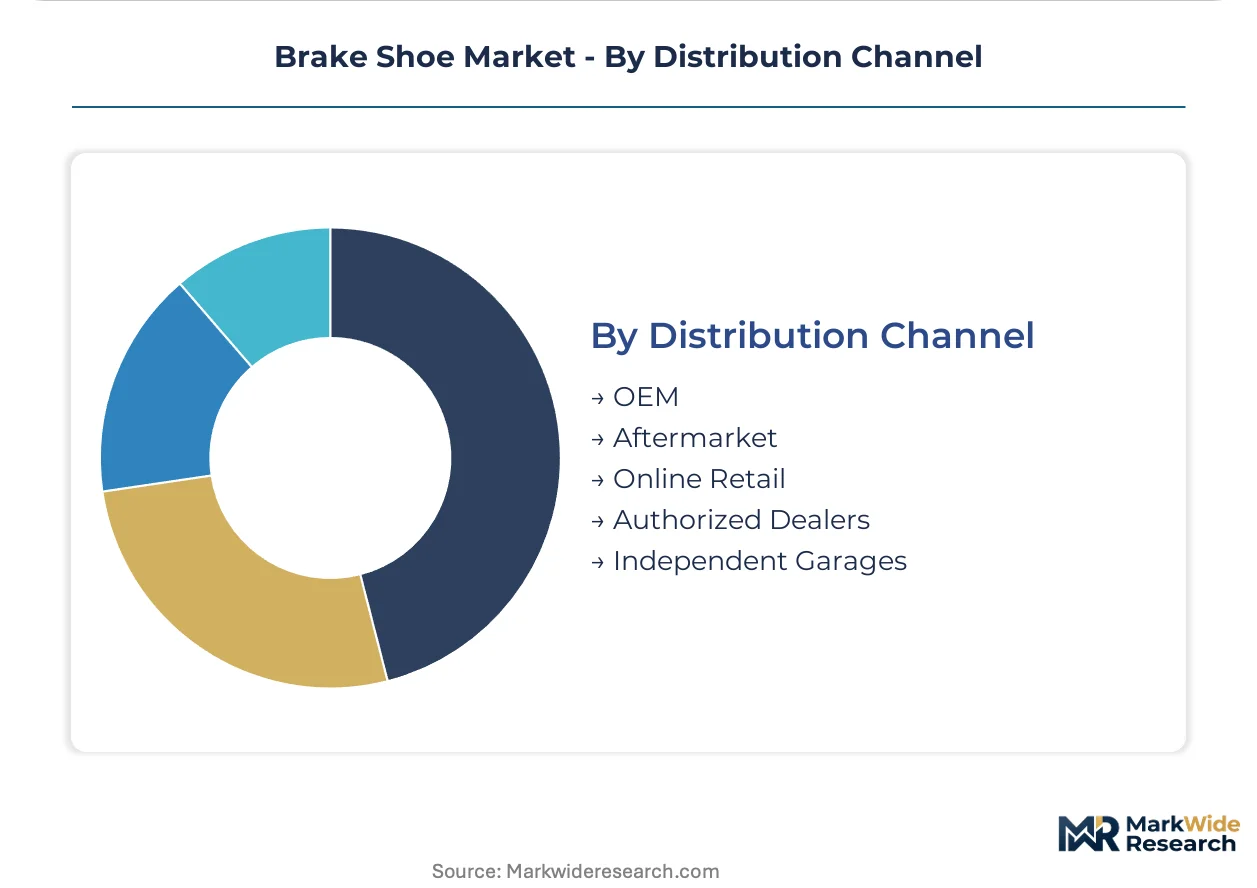
The distribution channel segment reflects how brake shoes reach end-users, highlighting the varying market access strategies and supply chain dynamics.
- OEM:The Original Equipment Manufacturer channel supplies brake shoes directly to vehicle assembly lines for new vehicle production. This channel demands stringent quality control and adherence to manufacturer specifications, often involving long-term supply agreements.
- Aftermarket:The aftermarket channel provides replacement brake shoes for vehicles already in operation, primarily serving repair shops and individual consumers. This segment exhibits high volume and price sensitivity, with extensive product portfolios from various suppliers.
- Online Retail:E-commerce platforms facilitate direct sales of brake shoes to consumers and independent repair shops, offering convenience and price transparency. This channel is gaining traction in mature markets like North America and Europe, challenging traditional distribution models.
- Authorized Dealers:Authorized dealers, affiliated with specific vehicle brands, offer genuine OEM replacement brake shoes, often emphasizing quality and warranty support.
- Independent Garages:Independent garages source brake shoes from a variety of suppliers, prioritizing cost-effectiveness and availability to serve a broad customer base.
The Aftermarket channel represents the largest revenue contributor, with Online Retail gaining market share rapidly in developed regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled engineering workforce anchors manufacturing innovation across key global regions, driving advancements in brake shoe technology. Regulatory frameworks and a growing vehicle parc influence regional market dynamics, with significant aftermarket demand concentrated in specific developing economies.
United States
Demand for brake shoes in the United States stems from a vast operational vehicle fleet and stringent safety requirements. The EPA guidelines for non-asbestos friction materials significantly influence product development and market entry. Detroit's automotive manufacturing cluster drives both OEM supply and a substantial aftermarket for replacement components.
China
China's enormous vehicle production volume and expanding aftermarket drive substantial demand for brake shoes. All brake components must adhere to mandatory GB standards for performance and safety, impacting material composition. Manufacturing centers within the Yangtze River Delta produce high volumes for both domestic consumption and export.
Germany
Germany's premium automotive sector and focus on advanced material science create demand for high-performance brake shoes. The European Union's REACH framework restricts certain chemicals, compelling continuous material reformulation. Stuttgart's automotive research and development centers lead innovation in friction material technology.
Indonesia
Indonesia's expanding light commercial vehicle fleet fuels a growing demand for durable and cost-effective aftermarket brake shoes. Local vehicle safety standards influence product specifications and market preferences. Jakarta's dynamic logistics and transportation sector drives significant consumption of replacement parts.
Brazil
Brazil's large and aging vehicle fleets, particularly those relying on drum brake technology, support a robust aftermarket for brake shoes. CONTRAN regulations govern vehicle component certification, ensuring product quality and safety. São Paulo's established automotive industry supports both local production and extensive distribution networks.
Brake Shoe Market Key Industry Players
Top-tier vendors anchor the premium segment with material science innovation, while a diverse array of suppliers addresses the broad aftermarket with cost-effective solutions. The market exhibits a tiered structure, with specialized performance providers, comprehensive portfolio leaders, and value-oriented manufacturers. Strategic archetypes include high-performance innovators, extensive distribution network operators, and wide-range replacement part suppliers. Competitive moves center on material science innovation and the expansion of distribution networks.
On the premium-tier vector, Brembo S.p.A. exemplifies a focus on material science innovation for performance vehicles and specialized applications. Bosch represents players leveraging extensive distribution networks to serve both OEM and broad aftermarket segments with a tiered product portfolio. Federal-Mogul Motorparts occupies a position offering a wide range of replacement parts across multiple quality and price points.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Bosch |
| Akebono Brake Industry |
| ZF Friedrichshafen AG |
| Continental AG |
| Aisin Corporation |
| Mando Corporation |
| Federal-Mogul Motorparts |
| Nisshinbo Brake |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material processing anchors supply positions for premium brake shoe manufacturers, enabling greater control over material quality and cost, which directly influences their pricing power in specialized segments.
Pricing Analysis
Bundled after-sales service and product warranties differentiate pricing for OEM-supplied brake shoes, contrasting with the unbundled, transactional model prevalent in the aftermarket. Pricing stratifies across premium, standard, and economy tiers, driven by material composition and brand reputation. Geographic delivery costs and certification levels, such as GB standards in China, also influence price points. Pricing pressure stems from the proliferation of low-cost alternatives, particularly in the budget-conscious passenger car aftermarket. Heavy-duty truck operators, prioritizing durability, exhibit lower price sensitivity compared to individual consumers seeking replacement parts for older vehicles.
Supply Chain Analysis
Raw material input dependency for non-asbestos formulations rests on specialized chemical producers in China for aramid fibers and copper suppliers in Chile. Geographic supply concentration for finished brake shoes centers in manufacturing hubs across China and India, which serve global aftermarket demand. Commodity price volatility for key inputs like copper and specialized resins presents a structural risk to manufacturer margins. Distribution runs through extensive multi-tiered networks for OEMs, while the aftermarket increasingly leverages online retail platforms for direct-to-installer fulfillment in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, as demand shifts toward premium, low-dust, and quiet-operation specifications for passenger cars and electric vehicles.
For Market Incumbents:Acquire specialized material science firms to deepen expertise in eco-friendly and high-performance friction formulations. Consolidate manufacturing footprints in regions with favorable regulatory environments, such as those adhering to EU REACH framework. This defends against margin pressure from raw material volatility and strengthens compliance capabilities. Invest in advanced testing and certification for new non-asbestos organic materials to maintain a competitive edge against emerging entrants.
For New Entrants and Emerging Players:The EPA guidelines in the United States open a window for manufacturers specializing in low-copper or copper-free brake shoes. Target the light commercial vehicle aftermarket in Southeast Asia, where expanding fleets create significant replacement demand. Focus on developing cost-effective non-asbestos organic formulations certified to regional standards. A direct-to-installer e-commerce model, emphasizing transparent pricing and rapid delivery, offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory fragmentation and raw material volatility compress margins for smaller players. The long-term viability favors entities with diversified product portfolios and strong material science capabilities. Acquire mid-sized manufacturers possessing established distribution networks in underpenetrated aftermarket geographies like Latin America. A signal to watch is the accelerating adoption rate of copper-free formulations in major automotive markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Material Science Startups | Integrates specialized expertise in eco-friendly and high-performance friction material development. |
| Expand Aftermarket Distribution in Southeast Asia | Captures significant replacement demand from expanding light commercial vehicle fleets in developing economies. |
| Invest in Copper-Free Formulation R&D | Preemptively meets future environmental regulations and creates a competitive advantage in key markets. |
| Standardize Global Certification Processes | Reduces complexity and cost associated with navigating divergent regional compliance requirements for brake components. |
| Develop EV-Specific Brake Shoe Lines | Addresses the specialized performance and low-dust needs of electric vehicles, complementing regenerative braking systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of market dynamics. Primary research involved discussions with OEM procurement managers, aftermarket distributors, friction material engineers, and vehicle fleet operators across key regions. This was triangulated with secondary data from automotive industry associations, regulatory body publications like the EPA, and trade statistics.
Comparable historical periods anchored the forecast framework, establishing baseline trends for material adoption and regional demand. The analytical framework modeled market segmentation across product types, vehicle types, applications, and distribution channels. Compound annual growth rates were derived from a multi-factor analysis considering vehicle parc expansion, regulatory impacts, and technological shifts. Forecast inputs included projected raw material costs and vehicle production volumes.
Revisions become necessary when significant policy changes, such as new environmental mandates, or unforeseen macroeconomic shifts materialize. Forecasts reflect assumptions regarding technological advancements and stable supply chain conditions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Engine Bearings Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Engine Oil Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Variable Valve Timing (VVT) Market