
 Automotive Exhaust Heat Recovery System Market | 2026-2036
Automotive Exhaust Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Heat Recovery System Market Outlook
Automotive thermal engineering talent is rotating from conventional powertrain cooling toward exhaust energy harvesting disciplines, tightening the labor pool for advanced heat exchanger design. BorgWarner leverages its turbocharger integration expertise to bundle exhaust recovery modules with existing forced-induction architectures. Dana Incorporated anchors its position through captive supply of thermal management hardware for commercial vehicle OEMs. Faurecia specializes in lightweight exhaust component packaging that accommodates thermoelectric generator substrates within tight underfloor envelopes.
An automotive exhaust heat recovery system captures thermal energy from engine exhaust streams and converts it into usable mechanical or electrical power through heat exchangers, turbo-compounding, or thermoelectric modules operating at exhaust temperatures typically exceeding 600°C. These systems primarily serve to improve overall vehicle thermal efficiency and reduce fuel consumption in internal combustion engine platforms. Heat exchangers dominate current product volumes due to their mature manufacturing base and compatibility with existing exhaust architectures, while thermoelectric generators represent the fastest-growing technology segment as semiconductor material costs decline and conversion efficiencies improve. Mechanical recovery approaches retain margin strength in heavy-duty truck applications where Rankine-cycle expanders deliver demonstrable fuel savings at sustained highway loads.
The EPA regulates exhaust thermal efficiency credits under greenhouse gas emission standards for medium- and heavy-duty engines, directly incentivizing OEM adoption of heat recovery hardware. NHTSA fuel economy rules for passenger vehicles create parallel compliance pressure that channels R&D investment toward electrical recovery pathways. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in secondary thermal loops, altering system design specifications for European vehicle assemblers. Stakeholders must monitor how battery-electric vehicle penetration rates reshape the addressable fleet for exhaust-based energy recovery and whether hybrid architectures sustain sufficient production volumes to justify continued thermoelectric material development.
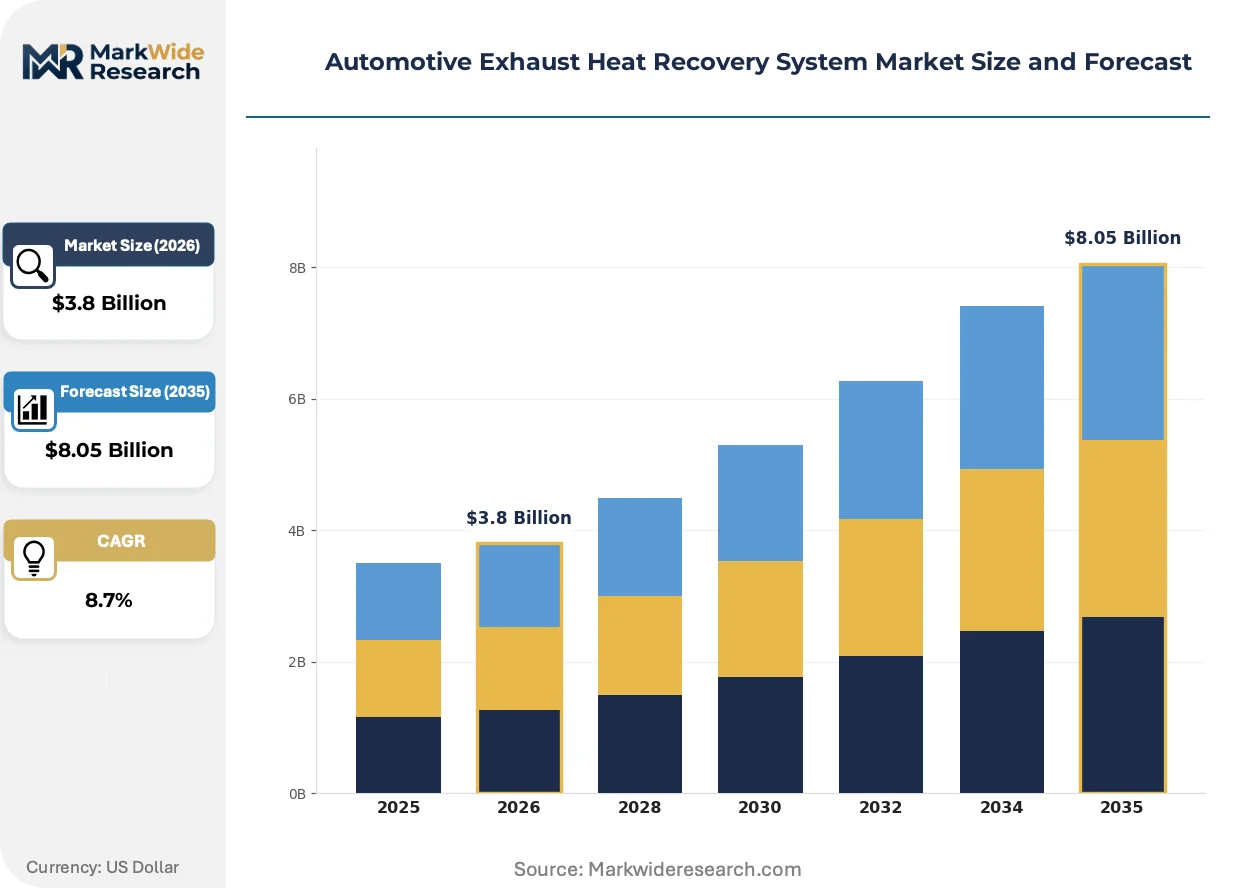
Market Dynamics
The automotive exhaust heat recovery system market pivots on EPA greenhouse gas Phase 2 standards, which mandate thermal efficiency credits for commercial vehicle fleets and force OEMs to integrate energy harvesting hardware into existing powertrain architectures.
Growth Catalysts
- Thermoelectric generator substrates:Semiconductor material costs are declining while conversion efficiencies improve, enabling broader deployment in hybrid powertrain architectures across Japan and Germany.
- EPA greenhouse gas Phase 2:Medium- and heavy-duty engine standards in the United States directly incentivize heat recovery hardware adoption through quantified thermal efficiency credits.
- Commercial vehicle fleet expansion:North American logistics operators face compliance pressure that channels capital toward Rankine-cycle expanders and heat exchanger retrofits.
Market Restraints
- Silicon-germanium thermoelectric material costs:Rare earth element price volatility constrains module production scaling and limits supplier margin flexibility.
- Battery-electric vehicle substitution:Zero-emission powertrains eliminate exhaust streams entirely, eroding the addressable fleet for thermal recovery systems in passenger segments.
- EU F-Gas Regulation:Refrigerant constraints in secondary thermal loops force redesign cycles that extend development timelines for European vehicle assemblers.
Strategic Opportunities
- Hybrid powertrain sustained production:Japan's domestic assemblers maintain heat exchanger integration programs that justify continued thermoelectric material R&D investment.
- Turbocharger bundling:Forced-induction architecture convergence creates channel synergies for exhaust recovery module packaging with existing underfloor components.
- Heavy-duty highway applications:Sustained load profiles in long-haul trucking enable demonstrable fuel savings from mechanical recovery approaches.
Industry Challenges
- Advanced heat exchanger design talent:Automotive thermal engineering labor pools are tightening as specialists rotate from conventional powertrain cooling toward exhaust energy harvesting disciplines.
- Legacy exhaust architecture integration:Retrofitting recovery hardware into existing vehicle platforms requires reconfiguration of tight underfloor packaging envelopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Heat Recovery System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Turbochargers, Thermoelectric Generators, Phase Change Materials Technology: Mechanical Recovery, Electrical Recovery, Hybrid Systems, Advanced Materials Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Bosch Thermotechnology, Siemens, Dana Incorporated, Futaba Industrial, T.RAD, Faurecia, BOSAL, SANGO, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Heat Recovery System Market Strategic Shifts
Exhaust heat recovery technology is fragmenting across competing conversion pathways, with material science advances and regulatory credit structures determining which approaches capture investment priority.
Thermoelectric generator technology is decomposing the traditional dominance of mechanical recovery systems in light-duty applications. Hybrid vehicle assemblers in Japan and Germany are accelerating semiconductor-based module deployment. This shift is compressing the market share of Rankine-cycle hardware in passenger segments where electrical integration offers simpler packaging.
EPA greenhouse gas Phase 2 standards are restructuring commercial vehicle procurement criteria in the United States. Fleet operators now specify thermal efficiency hardware to secure compliance credits. Heavy-duty truck manufacturers respond by embedding heat exchangers as standard equipment in highway tractor configurations.
Aftermarket retrofit channels are fragmenting OEM-dominated supply relationships for exhaust recovery hardware. Independent service networks in North America now offer heat exchanger upgrades for existing commercial fleets. This pattern is most visible among logistics operators seeking Phase 2 compliance without full vehicle replacement cycles.
Automotive Exhaust Heat Recovery System Market Segmentation
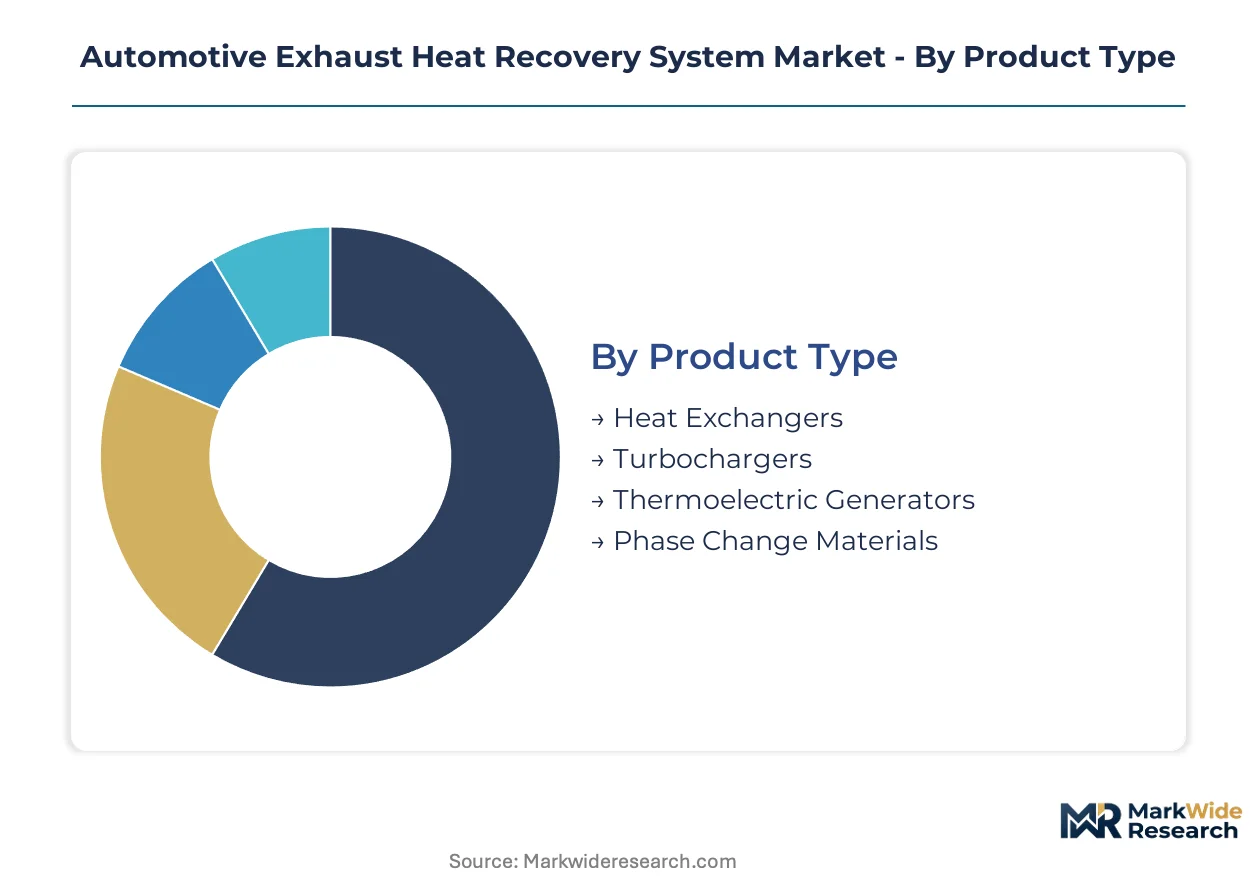
Exhaust heat recovery suppliers configure product portfolios around conversion physics and thermal loop architecture. Segment boundaries reflect divergent R&D investment patterns across electrical, mechanical, and hybrid recovery pathways.
Product Type:
Margin pools concentrate in thermoelectric substrates where semiconductor material science commands pricing power, while heat exchanger volumes sustain cash flow through manufacturing scale.
- Thermoelectric Generators:Solid-state modules convert exhaust temperature differentials directly into electrical output using silicon-germanium or bismuth telluride substrates. Japanese hybrid assemblers in Toyota City and Nagoya integrate these into underfloor packages to harvest electrical energy for auxiliary loads.
- Heat Exchangers:Shell-and-tube or plate-fin configurations transfer thermal energy from exhaust streams to working fluids in secondary loops. North American commercial fleets specify these for EPA Phase 2 compliance, bundling them with existing aftertreatment hardware.
- Turbochargers:Forced-induction turbines capture exhaust kinetic energy to boost intake air density and improve combustion efficiency.
- Phase Change Materials:Latent heat storage media absorb thermal spikes during transient engine operation and release energy during cold-start conditions.
The dominant share belongs to Heat Exchangers, while Thermoelectric Generators are expanding most quickly as conversion efficiencies improve.
Technology:
Application requirements split the addressable market between highway-duty mechanical systems and urban electrical recovery where packaging constraints dominate.
- Electrical Recovery:Thermoelectric and thermophotovoltaic approaches generate DC power for battery charging or auxiliary electrification. German automotive suppliers around Stuttgart prioritize this pathway for CO2 reduction targets in light-duty platforms.
- Mechanical Recovery:Rankine-cycle expanders or turbo-compounding systems convert thermal energy into crankshaft torque. Long-haul trucking routes through the US Interstate system deliver sustained loads where mechanical recovery demonstrates measurable fuel savings.
- Hybrid Systems:Combined electrical-mechanical architectures optimize across variable duty cycles using intelligent thermal management controllers.
- Advanced Materials:Nanostructured thermoelectrics and ceramic matrix composites push operating temperatures beyond conventional metal limits.
Mechanical Recovery retains the revenue base in heavy-duty segments, though Electrical Recovery is climbing the fastest as hybrid architectures proliferate.
Application:
Vehicle mass and duty cycle duration determine system sizing and recovery pathway selection across passenger and commercial platforms.
- Commercial Vehicles:Medium-duty delivery trucks and urban freight carriers balance payload sensitivity with regulatory compliance pressure. Fleet operators in California and Texas specify integrated heat recovery to secure EPA greenhouse gas credits without range compromise.
- Heavy-Duty Trucks:Class 8 highway tractors sustain exhaust temperatures above 600°C for extended periods, enabling Rankine-cycle economics. US Interstate corridor operators achieve payback periods under three years through fuel savings.
- Passenger Vehicles:Compact underfloor envelopes constrain heat exchanger packaging in sedans and light SUVs.
- Motorcycles:Two-wheel platforms present extreme space limitations that favor thermoelectric modules over fluid-based recovery loops.
Heavy-Duty Trucks command the highest per-unit system values, while Commercial Vehicles are gaining share fastest as urban logistics electrifies partially.
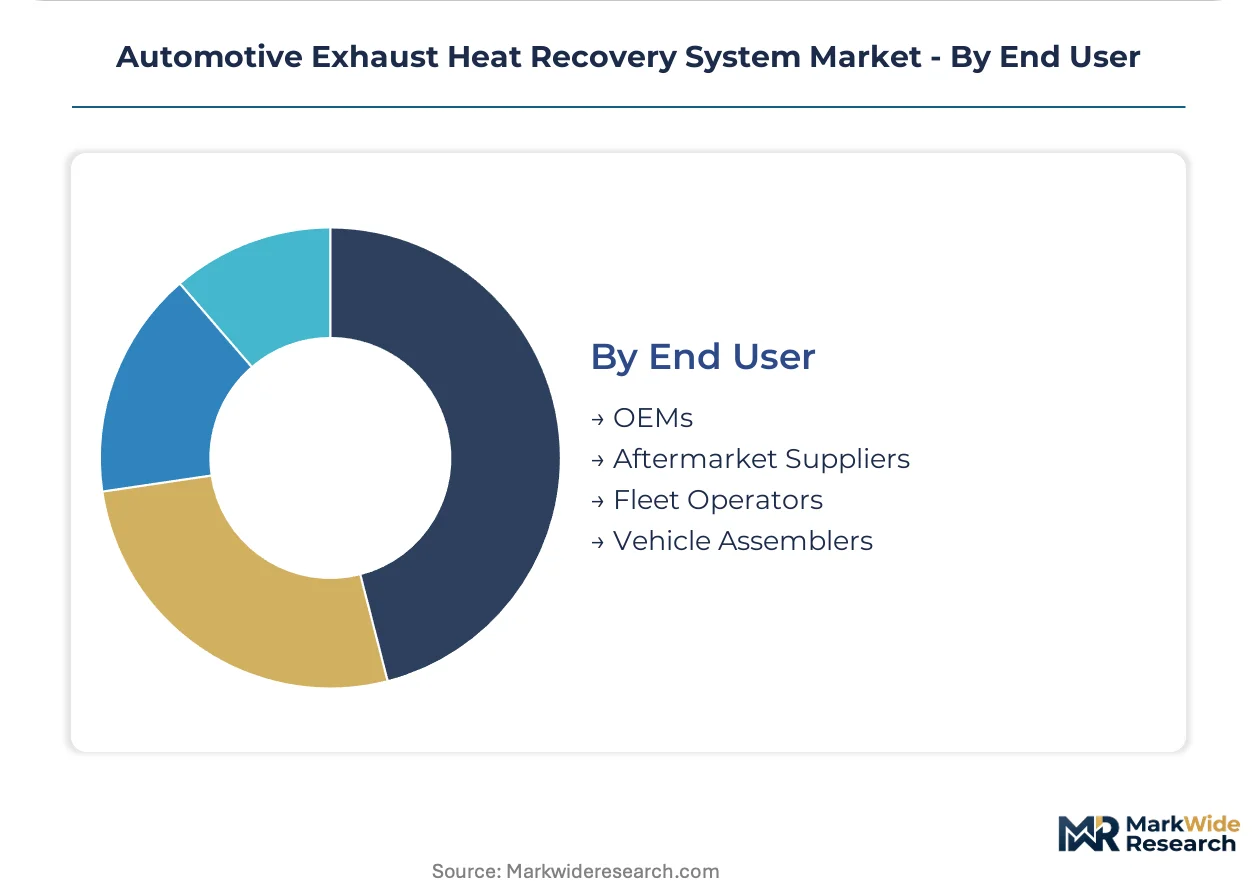
End User:
Procurement authority flows through distinct channels with divergent technical specifications and lifecycle cost horizons.
- OEMs:Original equipment manufacturers integrate heat recovery hardware at the powertrain design stage, specifying thermal efficiency targets that cascade to Tier 1 suppliers. Detroit-based truck manufacturers embed heat exchangers as standard equipment in highway tractor configurations.
- Fleet Operators:Logistics companies with centralized procurement authority retrofit existing vehicles to secure regulatory compliance without full replacement cycles. Independent service networks across the US Midwest now offer heat exchanger upgrades for Phase 2 credit eligibility.
- Aftermarket Suppliers:Independent distributors serve fragmented vehicle populations outside warranty coverage.
- Vehicle Assemblers:Contract manufacturers integrate subsystems according to OEM thermal architecture specifications.
OEMs control the specification pipeline, though Fleet Operators are closing the gap fastest as aftermarket retrofit channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geographic consumption patterns diverge sharply between heavy-duty highway corridors favoring mechanical recovery and urban hybrid fleets prioritizing electrical pathways. Japan and Germany concentrate thermoelectric development for passenger architectures, while the United States dominates commercial vehicle adoption driven by fleet compliance mandates.
United States
Class 8 highway tractor operators along Interstate corridors sustain exhaust temperatures above 600°C for extended durations, enabling Rankine-cycle economics with sub-three-year payback periods. EPA greenhouse gas Phase 2 standards mandate thermal efficiency credits that channel fleet capital toward heat exchanger retrofits. Detroit-based truck manufacturers embed recovery hardware as standard equipment in highway configurations.
Germany
Automotive suppliers around Stuttgart prioritize thermoelectric generator substrates to meet CO2 reduction targets in light-duty platforms. The EU Green Deal constrains refrigerant choices in secondary thermal loops, forcing redesign cycles that extend development timelines. Baden-Württemberg's supplier cluster accelerates semiconductor-based module deployment for hybrid architectures.
Japan
Domestic vehicle assemblers in Toyota City and Nagoya integrate heat exchanger systems into hybrid powertrain architectures as standard practice. METI industrial policy supports thermoelectric material R&D through targeted funding programs. The Chubu region's manufacturing concentration sustains captive supply relationships for thermal management hardware.
China
Domestic OEMs face dual carbon goals that intensify thermal efficiency requirements across commercial and passenger segments. MIIT fuel consumption standards create compliance pressure analogous to EPA regulations. Yangtze River Delta automotive clusters experiment with nanostructured thermoelectric materials for next-generation modules.
South Korea
Hyundai-Kia supplier networks in the Seoul Capital Area develop integrated exhaust recovery systems for hybrid SUV platforms. The country's national environmental regulator enforces greenhouse gas fleet averages that incentivize thermal efficiency hardware. Busan-Ulsan manufacturing corridors concentrate heat exchanger production for export markets.
Automotive Exhaust Heat Recovery System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that fragments across conversion technology and vehicle application boundaries. The upper tier commands specification authority through captive relationships with major OEM thermal architecture programs. Specialists concentrate in thermoelectric substrates, lightweight exhaust packaging, or commercial vehicle retrofit channels. Dominant competitive moves include turbocharger bundling strategies and backward integration into semiconductor material supply.
Among diversified automotive suppliers, Dana Incorporated and BorgWarner occupy positions that exemplify the integrated leader archetype through their existing thermal management and forced-induction footprints. Faurecia represents the packaging specialist tier with its focus on lightweight exhaust component integration. These three companies anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Siemens |
| Dana Incorporated |
| Futaba Industrial |
| T.RAD |
| Faurecia |
| BOSAL |
| SANGO |
| BorgWarner |
| Others |
Value Chain & Pricing Dynamics
Ninety-day silicon-germanium substrate lead times concentrate pricing power among Japanese and German material suppliers, while EPA Phase 2 compliance deadlines force North American fleet buyers into premium contract structures that absorb cost volatility.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier 1 thermal management suppliers and commercial vehicle OEMs seeking EPA credit certainty, though spot purchases persist for aftermarket retrofit channels. Price differentiation rests on semiconductor material grade and ISO 26262 automotive safety certification tier. Cost compression in thermoelectric substrates is intensifying because rare earth element volatility constrains supplier margin flexibility. Fleet operators exhibit highest price sensitivity due to three-year payback thresholds, while luxury hybrid assemblers absorb premiums for packaged integration.
Supply Chain Analysis
Container availability constraints on the transpacific trade lane extend inbound logistics costs for North American heat exchanger assemblers sourcing brazed aluminum cores from East Asian foundries. Manufacturing concentrates in Germany, Japan, and China, with the Yangtze River Delta anchoring shell-and-tube production for export markets. The supply chain draws from silicon-germanium substrates, ceramic matrix composites, and precision-brazed aluminum cores. Single-source vulnerability in rare earth element refining creates structural risk. Distribution runs through captive OEM supply agreements and independent aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
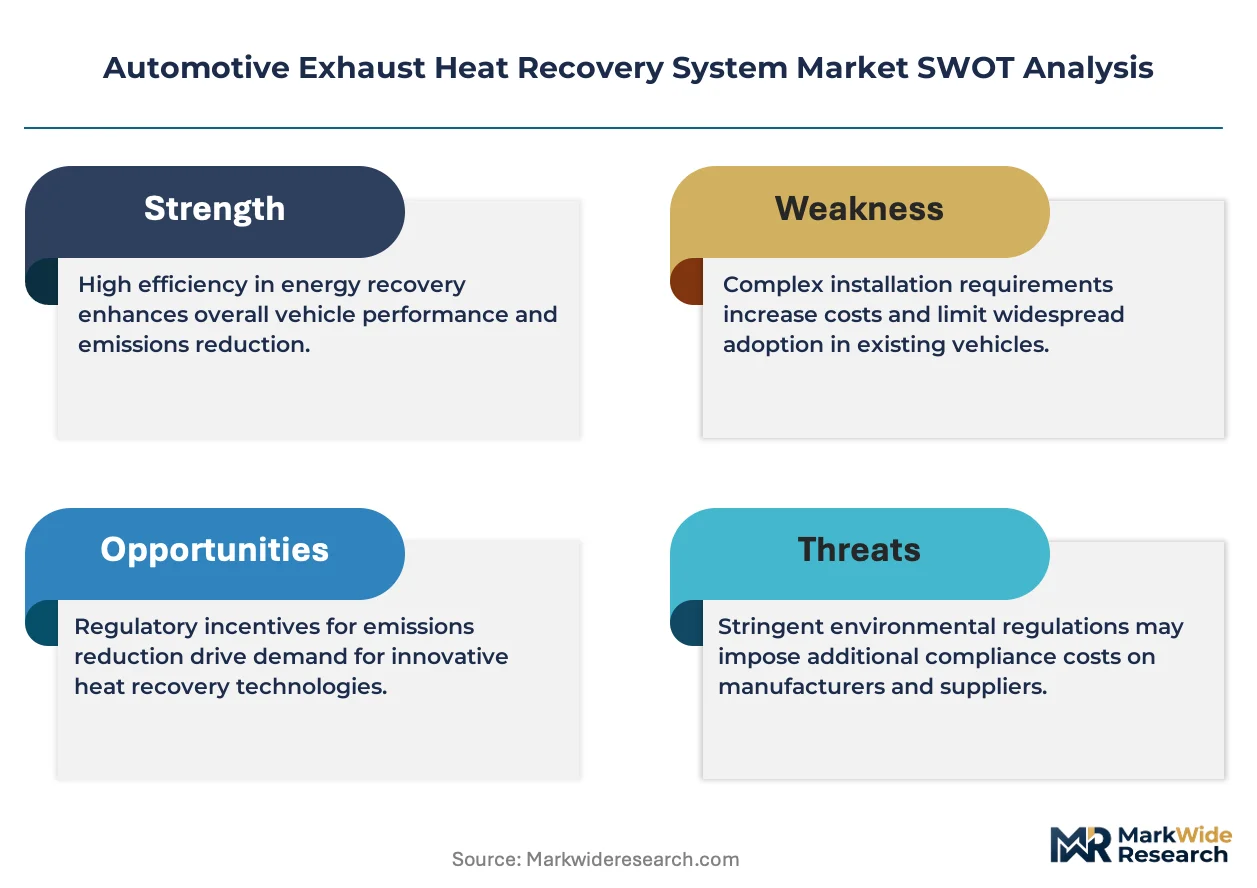
Talent scarcity in advanced heat exchanger design and thermoelectric material science constrains supplier capacity expansion, creating asymmetric returns for firms that secure specialized engineering teams before competitors.
For Market Incumbents: Shield specification authority by deepening captive relationships with Detroit-based truck manufacturers and embedding recovery hardware as standard equipment before emerging packaging specialists capture retrofit channels. Prioritize backward integration into silicon-germanium substrate supply to offset rare earth price volatility and constrain competitor access to critical semiconductor materials. For New Entrants and Emerging Players: EPA Phase 2 certification fast-tracks for aftermarket heat exchanger retrofits open white-space among Midwest logistics operators seeking compliance without full vehicle replacement. Target independent fleet service networks in Texas and California as the most penetrable channel. Pursue project-based engineering partnerships with regional commercial vehicle dealers lacking in-house thermal expertise. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-dependency play because EPA greenhouse gas standards and EU Green Deal thermal efficiency mandates sustain addressable demand even as battery-electric penetration advances. Acquisition candidates should display captive OEM relationships and in-house thermoelectric R&D programs. Watch hybrid powertrain production volumes at Japanese assemblers as the critical inflection signal for thermoelectric material demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoelectric Material R&D Partnership | Japanese METI-funded programs accelerate silicon-germanium conversion efficiency gains for hybrid architectures. |
| Aftermarket Retrofit Channel Expansion | Independent service networks in California and Texas secure EPA Phase 2 compliance credits for existing fleet vehicles. |
| Turbocharger Integration Bundling | BorgWarner leverages forced-induction expertise to package exhaust recovery modules within underfloor envelopes. |
| Backward Integration into Substrate Supply | Dana Incorporated anchors margin control through captive semiconductor material sourcing for thermoelectric generators. |
| Lightweight Packaging Specialist Acquisition | Faurecia's exhaust component expertise addresses space constraints in hybrid powertrain thermal management systems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and commercial fleet maintenance managers. Secondary validation drew from EPA regulatory filings, NHTSA fuel economy rulemakings, vehicle production databases, and customs trade records for thermal management component flows. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including conversion technology type, vehicle propulsion architecture, OEM tier classification, and regional regulatory cluster. CAGRs were derived from installed base growth rates and content-per-vehicle assumptions. Forecast inputs incorporated EPA Phase 2 compliance credit values and hybrid powertrain production schedules at Japanese assemblers.
Decision-makers should treat outputs as directional under sustained internal combustion engine production and hybrid architecture viability assumptions; material deviation in battery-electric substitution rates would warrant model refresh. Forecasts reflect these base conditions without guarantee of regulatory continuity or technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Car Rack Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Air Filter Cartridges Market