
 Automotive and Transportation Connector Market | 2026-2036
Automotive and Transportation Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive and Transportation Connector Market Analysis
Aftermarket service revenue is narrowing as OEMs and Tier-1 suppliers push for captive connector replacement programs. TE Connectivity leverages its vertical integration across sensor-to-connector systems to sustain margin capture in autonomous vehicle architectures. Sumitomo Electric anchors Japanese supply chains through high-voltage cable-connector integration for hybrid platforms.
Automotive and transportation connectors are electromechanical interfaces engineered to transmit power, signal, or data across vehicle subsystems, typically rated for temperatures spanning minus 40 to 150 degrees Celsius and sealed against ingress per IP67 or IP6K9K standards depending on underhood or chassis placement. Sealed connectors command durable margin pools given their penetration in powertrain and battery management zones where moisture and vibration resistance is non-negotiable. Board-to-board connectors within autonomous systems represent the fastest-expanding category as sensor fusion modules multiply printed circuit board interconnections per vehicle.
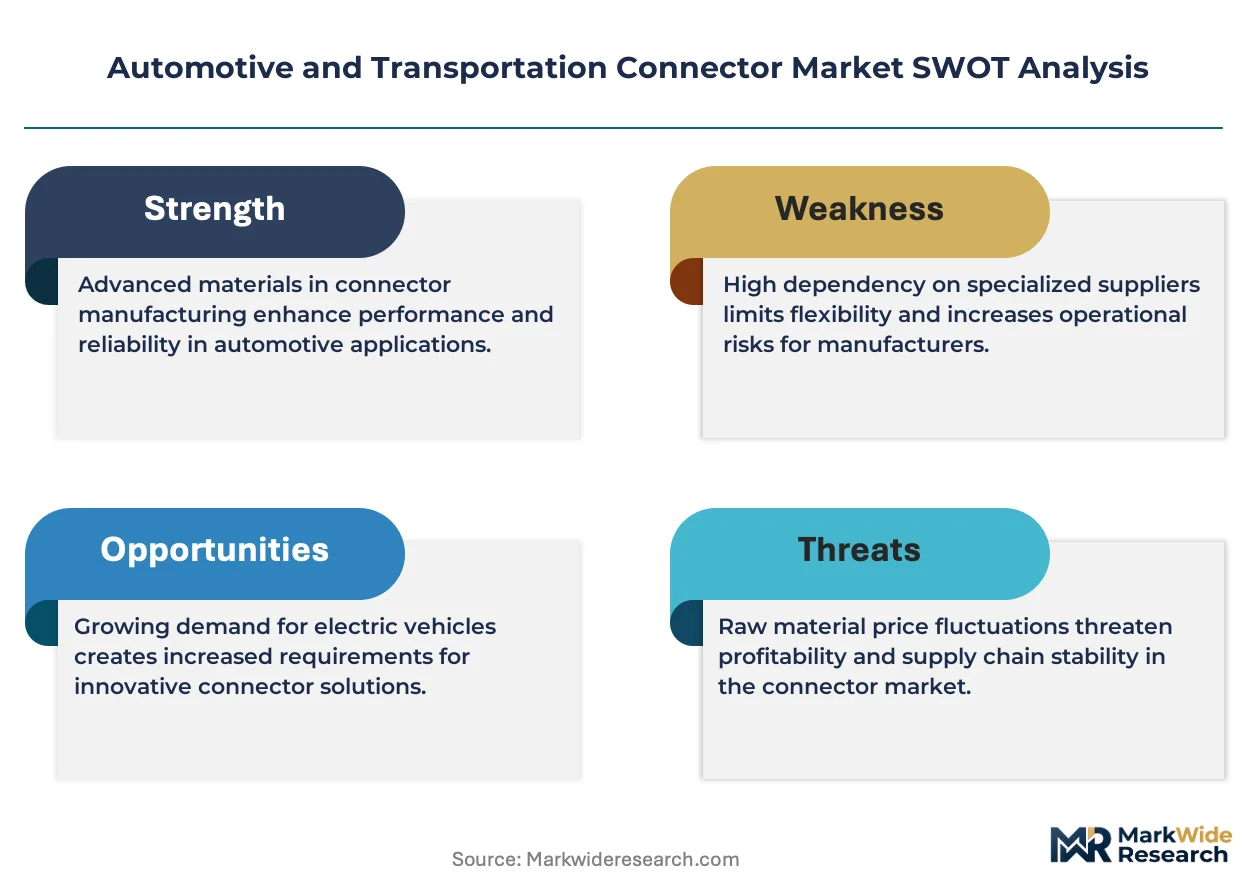
US NHTSA safety mandates and EPA emissions thresholds compel connector redesigns for weight reduction and signal integrity in electrified platforms. EU REACH restrictions on halogenated flame retardants and CE marking requirements for electromagnetic compatibility filter material choices and testing protocols for European-bound suppliers. Stakeholders must monitor how battery-electric platform architectures consolidate connector counts while simultaneously escalating performance requirements per connection point.
Market Dynamics
Powertrain electrification is fragmenting connector architectures as high-voltage battery systems demand specialized interconnection solutions incompatible with legacy 12V harness designs. Tier-1 suppliers face simultaneous pressure to reduce connector counts per vehicle while escalating thermal and electrical performance at each remaining node.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating sealed connector redesigns for thermal management systems in battery-electric platforms.
- Autonomous sensor fusion:LiDAR and camera arrays are multiplying board-to-board connector density within perception modules across premium vehicle segments.
- China:Domestic EV production scaling under MIIT dual carbon mandates is concentrating demand for localized high-voltage connector supply chains.
Market Restraints
- Copper price volatility:Raw material cost swings in conductor metals compress margin predictability for high-current connector variants.
- Japanese supply concentration:Specialized high-voltage cable-connector integration capabilities remain concentrated among a limited supplier base.
- REACH halogen restrictions:ECHA limitations on brominated flame retardants force costly material requalification for European-bound sealed connectors.
Strategic Opportunities
- India:PLI scheme incentives for domestic EV manufacturing are opening connector localization opportunities as OEMs establish regional assembly.
- Vehicle-to-grid integration:Bidirectional charging architectures create demand for high-cycle-life connectors rated for frequent disconnect events.
- Wireless power transfer:Inductive charging pad connectors represent emerging specification territory with limited incumbent lock-in.
Industry Challenges
- High-voltage safety certification:IEC 60664 and ISO 6469 compliance timelines extend product development cycles for 800V architecture connectors.
- Legacy harness integration:Electrified platforms must maintain backward compatibility with 12V auxiliary systems, multiplying interface complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive and Transportation Connector Market |
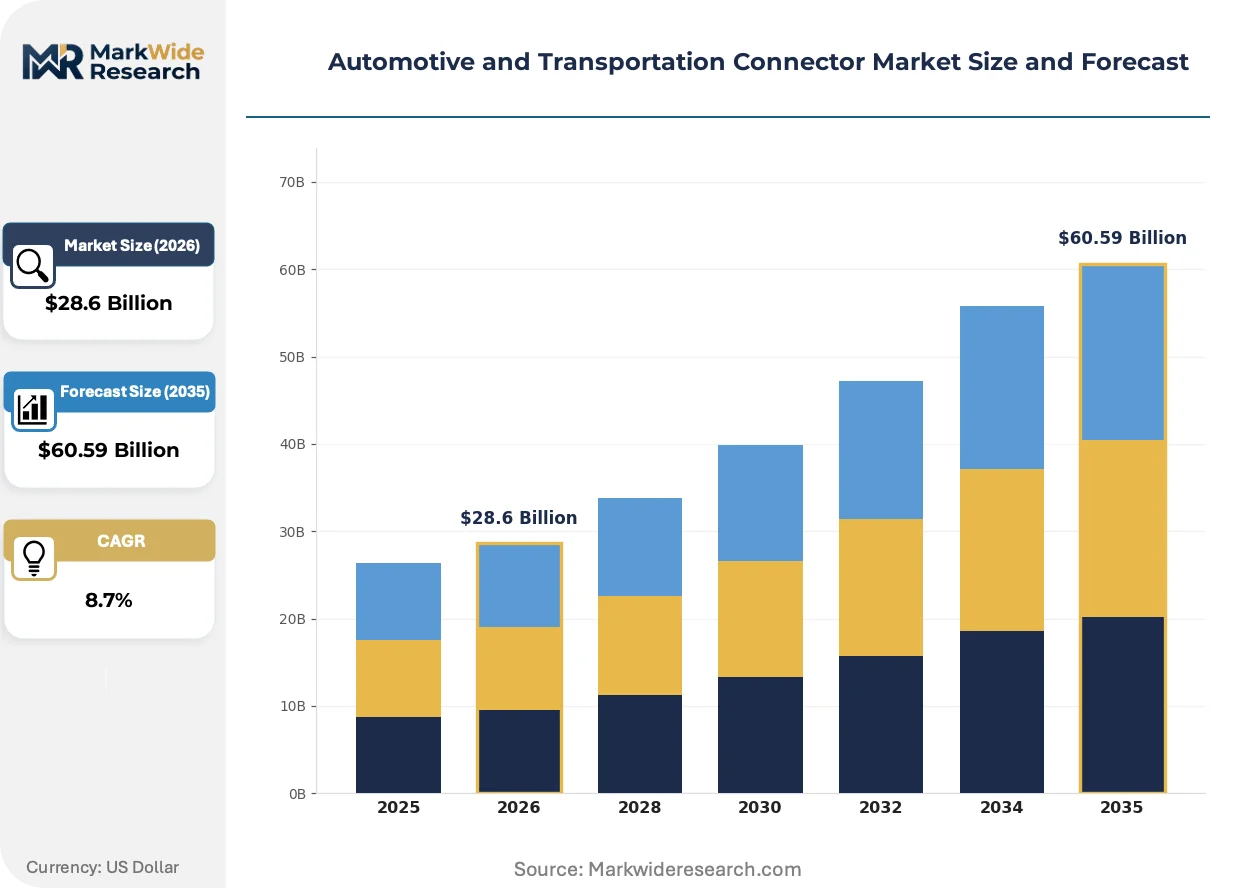
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Connectors, Sealed Connectors, Circular Connectors, Board-To-Board Connectors Technology: Optical, Electrical, Hybrid, Wireless Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Molex, Sumitomo Electric, TE Connectivity, Rosenberger, JAE, Amphenol, Yazaki, Luxshare, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive and Transportation Connector Market Emerging Trajectories
Connector technology is bifurcating between ultra-miniaturized signal interfaces for autonomous systems and ruggedized high-power solutions for electrified powertrains. This dual-track evolution is compressing development cycles while expanding performance specification ranges.
Contactless inductive coupling is digitizing power transmission across rotating assemblies in electric axle systems. Tier-1 drivetrain suppliers are adopting slip-ring replacements for wheel hub motors and steering columns. This architecture is digitizing maintenance intervals and eliminating wear-prone mechanical interfaces previously requiring sealed bearing assemblies.
EU REACH restrictions on halogenated compounds are forcing polymer reformulation across sealed connector housing supply chains. ECHA substance-of-very-high-concern listings now cover common flame-retardant chemistries used in underhood applications. European-bound suppliers are responding with phosphorus-nitrogen alternative compounds requiring extended thermal aging validation.
Fleet operators are consolidating connector procurement around lifecycle cost metrics rather than unit pricing. Commercial vehicle buyers now specify mean-time-between-failure thresholds in service contracts. This recalibration is most visible in North American heavy-duty trucking, where uptime guarantees drive preference for sealed connector families with field-replaceable terminal designs.
Automotive and Transportation Connector Market Segmentation
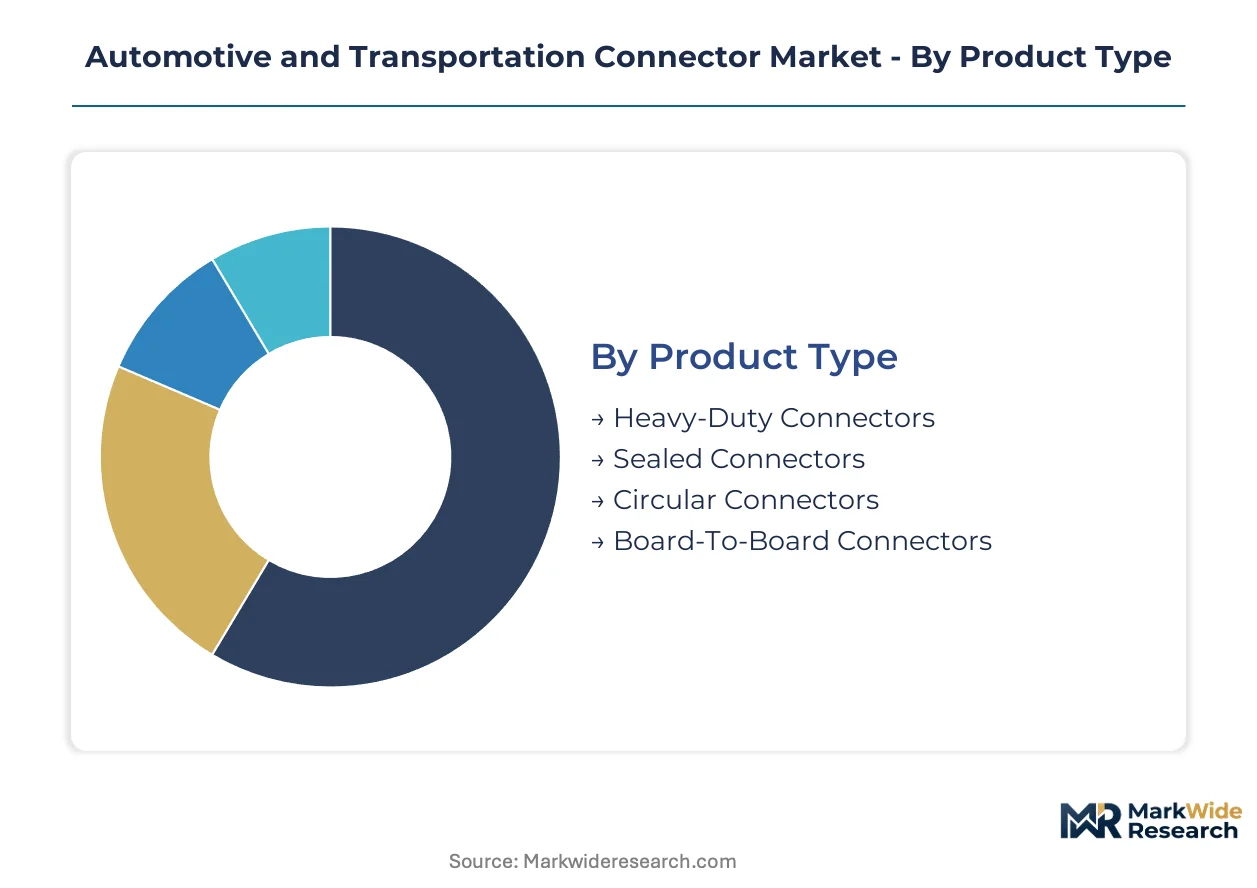
Connector architectures fragment across vehicle electrification tiers, with high-voltage platforms demanding specialized interconnection solutions incompatible with legacy harness designs. Segmentation clarity enables suppliers to align thermal specifications, sealing ratings, and cycle-life requirements against distinct procurement patterns across OEM captive programs and aftermarket channels.
Product Type:
Application severity spans sealed underhood environments through miniature signal interfaces in perception modules.
- Sealed Connectors:IP6K9K-rated housings with silicone wire seals and thermoplastic backshells withstand battery tray condensation and powertrain fluid exposure. China and Germany concentrate demand as domestic EV production scales localized high-voltage architectures under MIIT dual carbon mandates and EU F-Gas Regulation thermal management requirements.
- Board-To-Board Connectors:Ultra-miniaturized mezzanine and edge-card interfaces stack sensor fusion PCBs within LiDAR and camera modules. Autonomous system developers specify these for signal integrity in premium passenger vehicles where perception node density is climbing fastest.
- Heavy-Duty Connectors:Multi-pin power interfaces rated for 300+ amp continuous duty in commercial vehicle traction inverters.
- Circular Connectors:Bayonet-lock or threaded coupling systems dominate military-aerospace crossover applications in heavy trucking.
Established volume favors sealed connectors; emerging adoption favors board-to-board connectors.
Technology:
Transmission physics determines material intensity, with copper conductor dependency creating divergent margin exposure.
- Electrical:Copper-alloy terminals with tin or silver plating carry 12V auxiliary through 800V battery circuits across all vehicle classes. Raw material cost swings in conductor metals compress margin predictability for high-current variants serving commercial vehicle electrification.
- Hybrid:Combined power-and-signal interfaces integrate coaxial or twisted-pair elements within single housing footprints. Electric vehicle powertrain controllers specify these for reduced harness mass in 400V and 800V architectures.
- Optical:Fiber-based links eliminate electromagnetic interference in high-bandwidth infotainment and V2X communication backbones.
- Wireless:Inductive coupling for rotating assemblies eliminates mechanical wear in electric axle and steering column applications.
Electrical technology captures the dominant revenue share; hybrid configurations are expanding most quickly in battery-electric platforms.
Application:
Vehicle architecture complexity scales from standardized 12V body electronics through multi-voltage electrified platforms.
- Electric Vehicles:High-voltage interlock loop connectors, battery disconnect units, and thermal management system interfaces require arc-resistant housings and touch-safe terminal geometries. China concentrates demand as OEMs localize supply chains under production mandates from MIIT.
- Autonomous Systems:Redundant power and data distribution networks multiply connector counts per vehicle as sensor arrays proliferate. US NHTSA safety thresholds and EPA emissions compliance compel lightweight, high-density interconnects in development fleets.
- Passenger Vehicles:Internal combustion and mild-hybrid platforms sustain legacy connector specifications across high-volume nameplates.
- Commercial Vehicles:Fleet uptime requirements specify field-serviceable sealed families with replaceable terminals in North American heavy-duty trucking.
Passenger vehicle volumes dominate current procurement; electric vehicles are gaining share fastest through the forecast window.
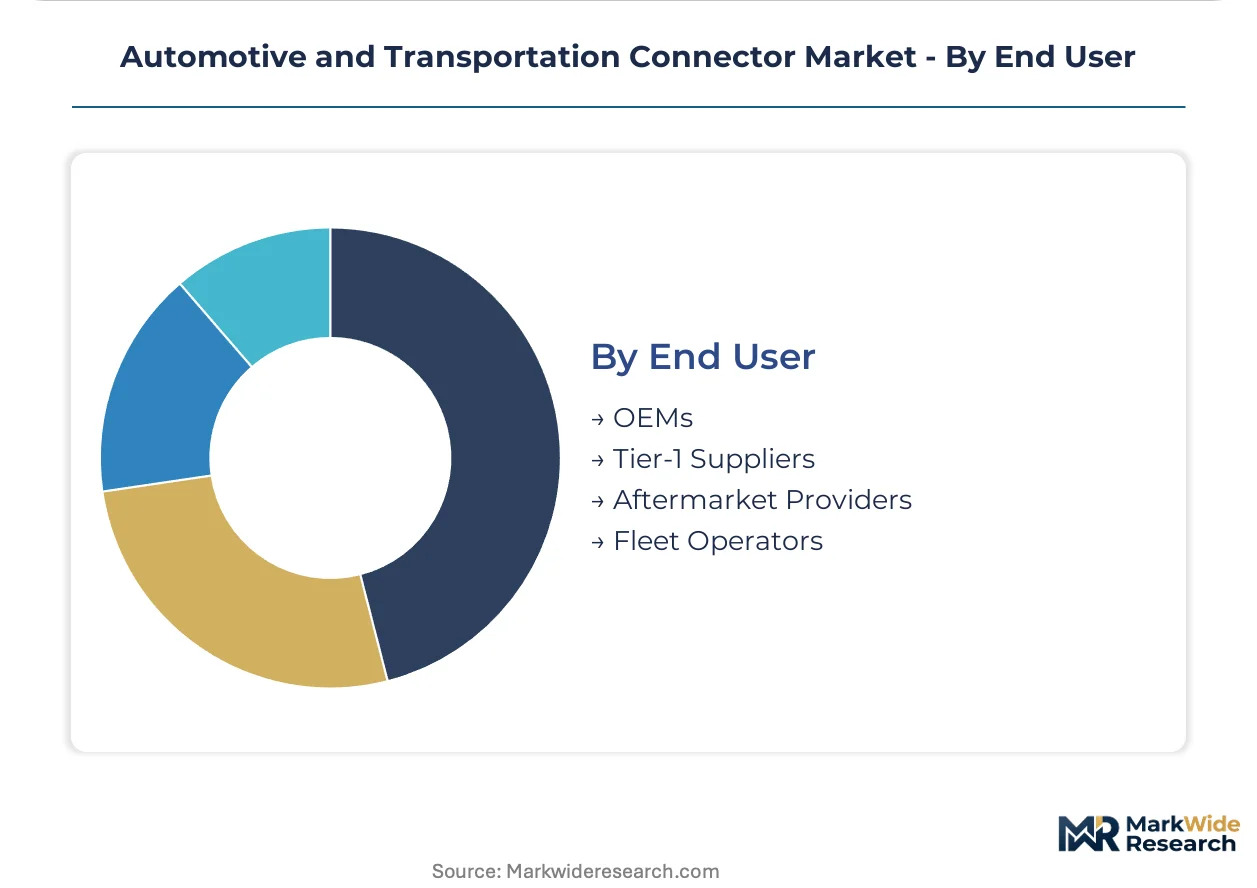
End User:
Procurement authority fragments between vehicle assemblers, system integrators, and post-warranty service channels.
- OEMs:Direct specification of connector families for captive harness production and platform standardization across nameplates. German and US automakers consolidate global connector sourcing through approved vendor lists with multi-year volume commitments.
- Tier-1 Suppliers:System-level integration of cable-connector assemblies for powertrain, chassis, and body electronics modules. Japanese suppliers anchor high-voltage cable-connector integration capabilities for hybrid platform supply.
- Aftermarket Providers:Independent distributors and service chains face narrowing revenue pools as OEMs expand captive replacement programs.
- Fleet Operators:Commercial buyers in North America now specify mean-time-between-failure thresholds in service contracts, recalibrating procurement around lifecycle cost metrics.
Tier-1 suppliers capture the central procurement role; fleet operators are restructuring specification authority through performance-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector procurement patterns diverge sharply by geography. China and Germany prioritize high-voltage architectures for battery-electric platforms. The United States emphasizes autonomous sensor fusion networks. Japan concentrates on hybrid powertrain integration. India represents emerging localization demand under manufacturing incentives.
China
Domestic EV production scaling under MIIT dual carbon mandates concentrates demand for localized high-voltage connector supply chains. GB standards and SAMR certification requirements filter material specifications for sealed battery management interfaces. Shanghai and Guangdong province anchor captive production as OEMs localize tier-1 sourcing away from import dependency.
Germany
EU F-Gas Regulation and REACH compliance reshape material specifications for sealed and circular connector variants serving thermal management systems. KBA type-approval processes extend development timelines for 800V architecture components. Baden-Württemberg and Bavaria house concentrated R&D activity as automakers consolidate approved vendor lists.
United States
NHTSA safety mandates and EPA emissions thresholds compel connector redesigns for weight reduction and signal integrity in electrified platforms. IRA domestic content provisions incentivize North American manufacturing localization. Michigan and California development clusters drive specification authority for autonomous perception module interconnections.
Japan
Hybrid platform persistence sustains specialized high-voltage cable-connector integration capabilities concentrated among limited supplier bases. METI technology roadmaps prioritize next-generation thermal management connector specifications. Aichi and Kanagawa prefectures anchor production networks serving Toyota and Honda captive programs.
India
PLI scheme incentives for domestic EV manufacturing open connector localization opportunities as OEMs establish regional assembly. BIS certification requirements and DGFT import substitution policies filter procurement toward qualified domestic suppliers. Maharashtra and Tamil Nadu industrial corridors concentrate emerging tier-1 facility investments.
Automotive and Transportation Connector Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. High-voltage safety certification and material science expertise cluster among Japanese and German specialists with decades of automotive qualification heritage. Volume manufacturing scale concentrates among diversified electronics conglomerates with cross-industry connector portfolios. Three archetypes dominate: integrated cable-connector system suppliers, pure-play connector specialists, and diversified industrial electronics houses. Consolidation through approved vendor list capture and backward integration into terminal stamping represent the dominant competitive vectors.
Among diversified industrial electronics houses, TE Connectivity, Molex, and Amphenol occupy positions spanning sensor-to-connector system integration. TE Connectivity exemplifies the vertically integrated archetype through captive sensor and terminal production. Molex represents scale-driven manufacturing breadth across multiple voltage tiers and vehicle classes. Amphenol anchors military-aerospace crossover capabilities migrating into heavy commercial vehicle applications. Each sits within distinct procurement channels—TE Connectivity through OEM direct specification, Molex through tier-1 harness supplier integration, Amphenol through fleet operator performance-based contracting.
| Leading Market Players |
|---|
| Molex |
| Sumitomo Electric |
| TE Connectivity |
| Rosenberger |
| JAE |
| Amphenol |
| Yazaki |
| Luxshare |
| Aptiv |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor anchors cost dynamics for copper-alloy terminal shipments, with freight rate volatility feeding directly into tiered pricing spreads between captive OEM programs and aftermarket channels. Supply concentration in East Asian stamping operations amplifies procurement leverage for volume buyers while fragmenting price-setting authority across German and Japanese specialist houses.
Pricing Analysis
Long-term offtake contracts dominate high-voltage connector procurement, locking in copper price baselines for Tier-1 harness suppliers serving German and Chinese OEM platforms. Price differentiation hinges on IP6K9K certification grade and volume scale, with fleet operators commanding steepest discounts through multi-year uptime guarantees. Cost compression in sealed connector families is intensifying as REACH-compliant polymer reformulation adds material qualification overhead. Aftermarket distributors exhibit highest price sensitivity due to narrowing replacement revenue pools under captive OEM service programs.
Supply Chain Analysis
Extended payment terms from German automakers are squeezing working capital for terminal stamping houses concentrated in China, Japan, and Mexico. Copper conductor supply draws from Chilean mining operations and Chinese smelter capacity, while silicone seal compounds rest on German and US specialty chemical production. Single-source vulnerability concentrates in high-voltage cable-connector integration capabilities anchored among Japanese suppliers. Distribution runs through Tier-1 harness assemblers holding approved vendor list status with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connector market fragmentation is accelerating as powertrain electrification splits procurement between legacy 12V architectures and 800V battery platforms, creating distinct specification territories for specialist suppliers.
For Market Incumbents: Insulate high-voltage safety certification moats by accelerating IEC 60664 validation pipelines before 800V architectures proliferate across Chinese and German OEM lineups. Deepen backward integration into copper-alloy terminal stamping to offset raw material cost volatility compressing margins in heavy-duty connector variants. Channel control through captive aftermarket replacement programs represents the priority defensive lever against independent distributor encroachment. For New Entrants and Emerging Players: Pursue vehicle-to-grid bidirectional charging connector specifications where cycle-life requirements and limited incumbent qualification heritage create accessible entry points. India's PLI-scheme corridor offers the most penetrable geography as domestic EV assembly localization outpaces qualified supplier base expansion. A go-to-market angle anchored in field-replaceable terminal designs aligns with North American fleet operator lifecycle cost contracting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial electronics conglomerates with underutilized automotive connector divisions lacking platform engineering relationships. Long-term viability centers on suppliers holding simultaneous REACH, GB standard, and MIIT certification breadth across the analysis window. The signal to watch is 800V architecture penetration rates in Chinese domestic EV production as inflection indicator for high-voltage connector demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Safety Certification Investment | IEC 60664 and ISO 6469 compliance gates access to 800V battery platform specifications at German and Chinese OEMs. |
| Copper Terminal Backward Integration | In-house stamping capacity insulates margin from London Metal Exchange volatility in high-current connector variants. |
| REACH-Compliant Polymer Reformulation | Phosphorus-nitrogen flame retardant qualification unlocks European sealed connector procurement under ECHA restrictions. |
| Vehicle-to-Grid Connector Development | Bidirectional charging specifications address emerging fleet operator demand for high-cycle-life interconnects in commercial electrification. |
| India PLI Corridor Manufacturing Footprint | BIS certification and DGFT compliance position suppliers for domestic content requirements in Maharashtra and Tamil Nadu assembly clusters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing OEM platform engineers, Tier-1 harness procurement directors, aftermarket distributor operations heads, and fleet maintenance contract managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of diversified electronics houses, and customs records of copper-alloy terminal trade flows. Bottom-up connector shipment tallies by vehicle platform were triangulated against top-down OEM procurement budget disclosures.
Calibration against historical volume trajectories informed projection modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value expansion. Industry-specific forecast inputs included MIIT dual carbon mandate implementation timelines, EU F-Gas Regulation phasedown schedules, and NHTSA autonomous vehicle safety threshold progression.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, maritime freight rates, or automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions around electrification penetration and regulatory compliance timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Truck Axle Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Wheel Seals Market
Vehicle Components
HCV Axles Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Gas Station Equipment Market