
 Variable Valve Timing (VVT) Market | 2026-2036
Variable Valve Timing (VVT) Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Valve Timing (VVT) Market Analytics
ISO 26262 functional safety qualification is unwinding the competitive landscape for VVT system suppliers. Robert Bosch GmbH leverages its integrated semiconductor and actuator manufacturing to control certification timelines internally. Schaeffler AG anchors its position through captive production of precision camshaft phasing components. Eaton Corporation Plc competes on hydraulic valve train heritage while navigating the electromechanical transition.
Variable valve timing denotes precision mechanisms that modulate intake and exhaust valve lift, duration, and timing relative to crankshaft position, typically operating within oil pressure ranges of 0.5 to 5.5 bar and response thresholds below 100 milliseconds to optimize cylinder charge dynamics. The technology serves the primary commercial purpose of reducing pumping losses and enabling Atkinson-cycle operation without sacrificing low-end torque. Electromechanical product types now lead development roadmaps as OEMs pursue decoupled valve control for hybrid powertrains, while VTEC and VVTi technologies retain volume dominance in established gasoline engine architectures. Camless technology occupies the fastest-growth trajectory despite current cost barriers, with margin pools concentrating in OEM-facing electromechanical system integration rather than discrete component supply.
EPA Corporate Average Fuel Economy standards in the United States, EU CO2 fleet emission targets under the European Green Deal framework, and China's Stage VI fuel consumption regulations enforced by MIIT collectively mandate engine efficiency improvements that directly expand VVT penetration. Japan's METI administers comparable top-runner efficiency standards that sustain domestic supplier R&D commitments. Stakeholders must monitor the pace at which battery electric vehicle adoption displaces internal combustion investment cycles, as this transition determines the effective window for advanced valve train technology returns.
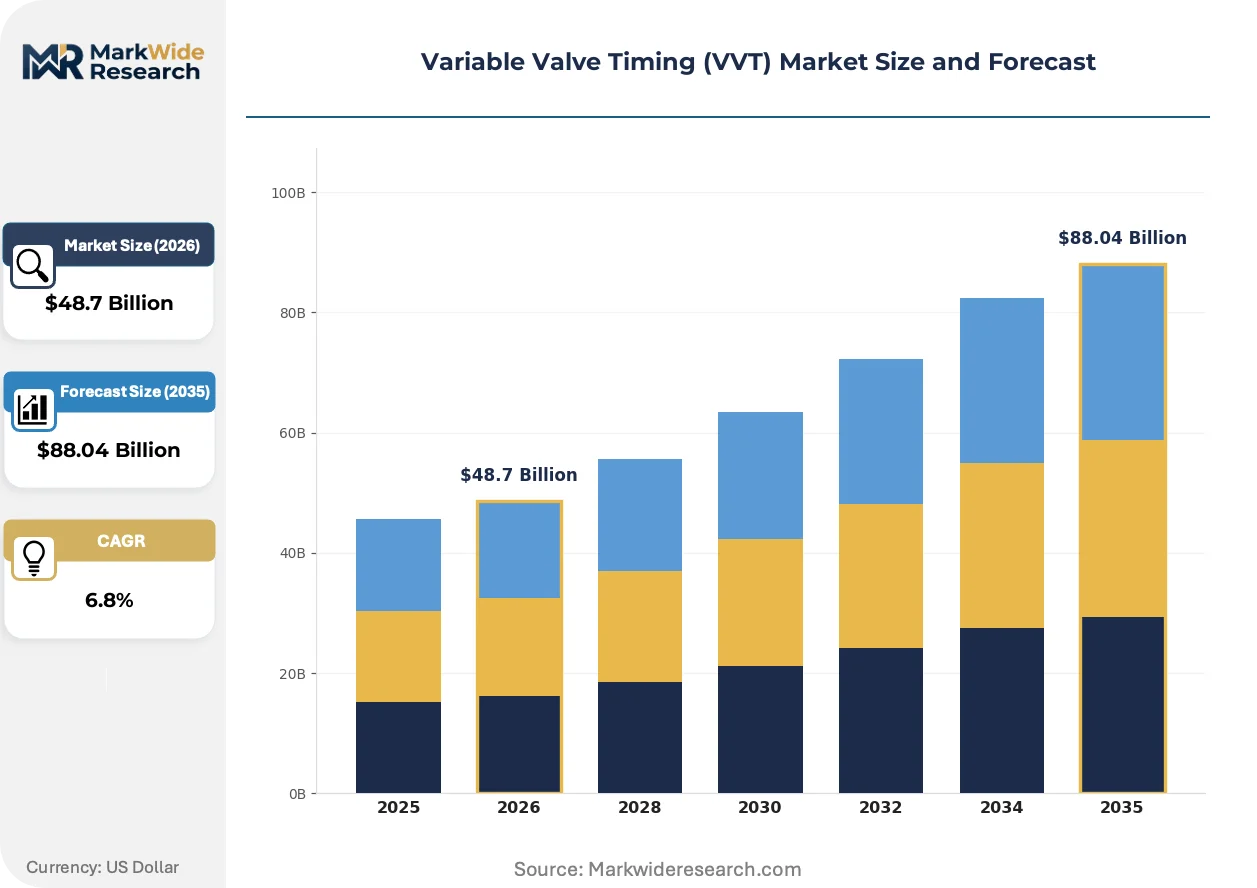
Market Dynamics
Electromechanical actuation architectures are bifurcating the supplier base as hydraulic heritage competes against de-novo electromechanical entrants, compressing margins for component-only vendors while rewarding system integrators with captive semiconductor and software capabilities.
Growth Catalysts
- China's Stage VI fuel consumption regulations:MIIT enforcement mandates engine efficiency improvements that expand VVT penetration across domestic OEM powertrain lineups.
- Hybrid powertrain architectures:Electromechanical valve control enables cylinder deactivation and Atkinson-cycle operation without sacrificing low-end torque response.
- Japan's METI top-runner standards:Sustained domestic supplier R&D commitments maintain precision camshaft phasing technology leadership.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings constrain electromechanical actuator motor economics.
- Supplier concentration in precision camshaft machining:Germany and Japan dominate high-volume phasing component production.
- Battery electric vehicle substitution trajectory:OEM powertrain investment cycles face compression as BEV adoption accelerates.
Strategic Opportunities
- India's underpenetrated passenger vehicle segment:BIS efficiency norms and PLI scheme incentives create first-mover positioning for electromechanical system suppliers.
- Camless valve train convergence:Electromechanical actuation merges with advanced combustion control software to enable fully flexible valve events.
- Aftermarket remanufacturing channels:Independent service networks in North America seek certified VVT actuator replacement programs.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Functional safety qualification stretches 18-24 months for new electromechanical architectures.
- Legacy engine controller integration:Electromechanical actuators require software stack rearchitecture incompatible with decade-old ECU hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Valve Timing (VVT) Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Mechanical Technology: VTEC, VVTi, Twin VVT-i, Camless technology End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Fuel Type: Gasoline, Diesel, Hybrid, Ethanol |
| Companies Covered | Robert Bosch GmbH, Eaton Corporation Plc, Schaeffler AG, DENSO Corporation, BorgWarner Inc., Aisin Corporation, Mitsubishi Electric Corporation, Continental AG, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Valve Timing (VVT) Market Evolving Landscape
Valve train technology is fragmenting across three simultaneous vectors: actuation physics, control software, and thermal management integration. This divergence rewards suppliers with cross-domain engineering depth while isolating single-technology vendors.
Electromechanical cam phasers are bifurcating the product landscape. These devices replace hydraulic oil pressure with brushless DC motors to achieve sub-100-millisecond response independent of engine temperature. Premium hybrid OEMs in Germany and Japan are adopting them for cold-start emissions compliance. The technology is bifurcating margin pools toward integrated mechatronics suppliers and away from discrete hydraulic component manufacturers.
EPA Corporate Average Fuel Economy standards are tightening fleet efficiency mandates through model year 2032. The regulation forces powertrain engineers to extract residual gains from remaining internal combustion production. Full-size truck and SUV segments in the United States face the steepest compliance cliffs, accelerating adoption of cylinder deactivation enabled by advanced VVT systems.
Powertrain procurement is consolidating supplier relationships around system-level accountability. OEM technical teams now specify valve timing as a combustion outcome rather than component performance metric. Tier-1 integrators in South Korea and China are absorbing previously discrete camshaft, actuator, and controller sourcing decisions. This behavior concentrates volume with suppliers offering calibrated subsystem deliveries rather than catalog components.
Variable Valve Timing (VVT) Market Segmentation
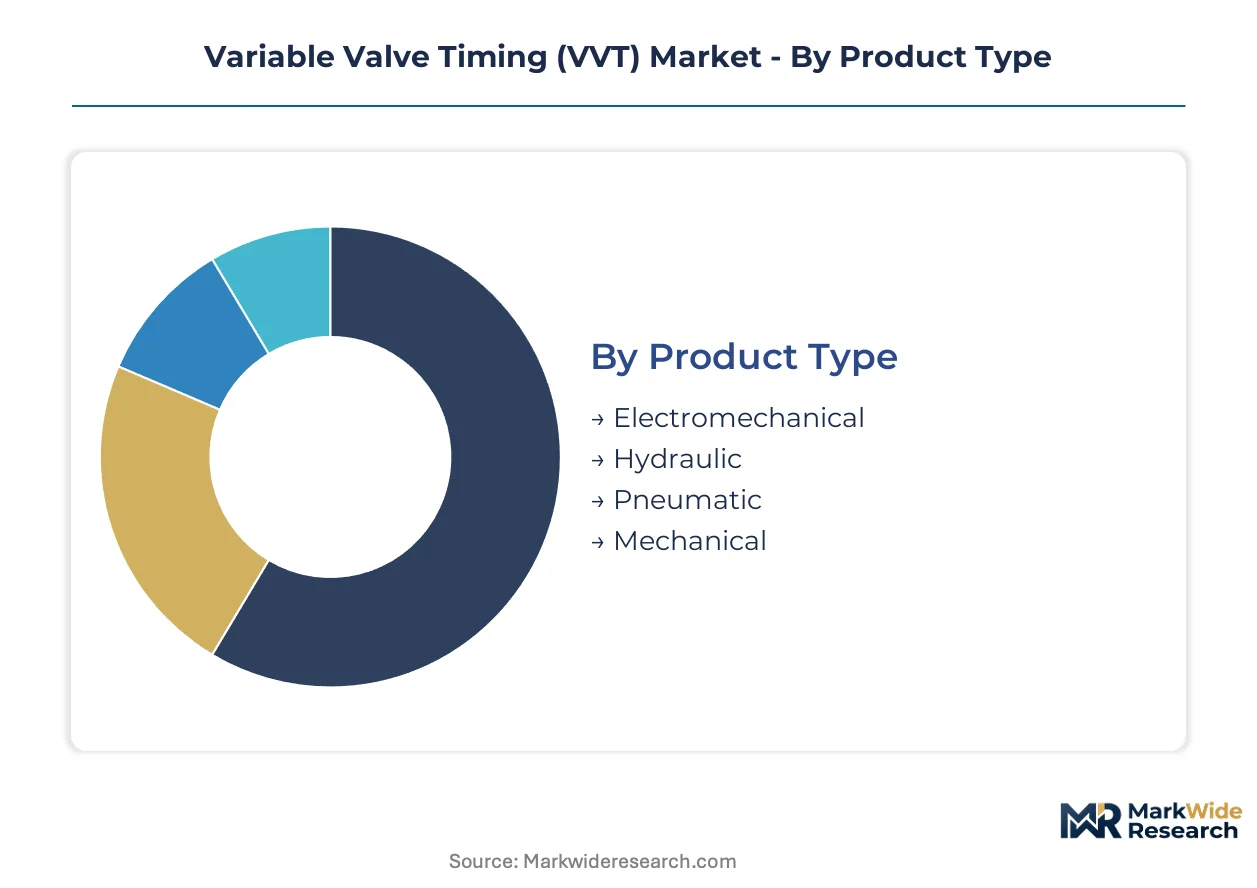
Segmentation in the VVT market reveals how actuation physics, combustion architecture, and supply chain position determine margin capture. Each dimension exposes different competitive vulnerabilities and investment priorities for stakeholders navigating the electromechanical transition.
Product Type:
Domestic production concentrates electromechanical systems in Germany and Japan, while hydraulic architectures sustain export volumes from China and South Korea to emerging markets.
- Electromechanical:Brushless DC motors replace oil pressure to achieve sub-100-millisecond response independent of engine temperature. Premium hybrid OEMs in Germany adopt these for cold-start emissions compliance; MIIT Stage VI enforcement accelerates Chinese domestic sourcing.
- Hydraulic:Conventional oil-pressure systems operating at 0.5 to 5.5 bar dominate established gasoline engine architectures. South Korean OEMs maintain volume production for export to Southeast Asian markets where cost sensitivity persists.
- Pneumatic:Compressed air actuation serves niche industrial and heavy-duty applications with extreme thermal cycling requirements. Limited adoption constrains supplier R&D commitment outside specialty vehicle segments.
- Mechanical:Fixed-profile camshaft designs with minimal timing adjustment retain presence in emerging market entry vehicles. Indian OEMs specify these for cost-optimized powertrains under BIS efficiency norms.
Hydraulic systems hold the largest share; momentum sits with electromechanical architectures.
Technology:
Patent concentration and licensing structures fragment competitive access across technology tiers, with Japanese OEMs controlling foundational VVTi intellectual property.
- VTEC:Honda's variable valve timing and lift electronic control system enables discrete cam profile switching for high-RPM performance. Japanese OEMs license variants to Chinese joint ventures seeking sport-positioned gasoline engines.
- VVTi:Toyota's continuously variable intake cam phasing retains volume leadership through manufacturing scale. Thai and Indonesian assembly plants source these systems for ASEAN export production.
- Twin VVT-i:Dual independent phasing of intake and exhaust camshafts enables Atkinson-cycle operation without sacrificing low-end torque. South Korean hybrid powertrains specify these for EPA compliance in US-bound exports.
- Camless technology:Fully electromechanical valve actuation eliminates camshaft entirely, enabling cylinder-specific event programming. German premium OEMs pilot these for 48V mild-hybrid integration despite current cost barriers.
VVTi commands installed base dominance; camless technology climbs the fastest.
End User:
Procurement accountability is shifting from component catalog purchasing to subsystem calibration contracts, compressing margins for catalog vendors.
- OEMs:Volkswagen, Toyota, and Hyundai specify valve timing as combustion outcomes rather than component performance metrics. Internal powertrain divisions increasingly insource electromechanical actuator controller software.
- Aftermarket Providers:Independent service networks in North America seek certified VVT actuator replacement programs for high-mileage Japanese and German vehicles. Remanufacturing economics favor hydraulic system rebuilds over electromechanical module replacement.
- Tier-1 Suppliers:Bosch, Schaeffler, and Denso absorb previously discrete camshaft, actuator, and controller sourcing decisions. System-level accountability requirements concentrate volume with integrators offering calibrated subsystem deliveries.
- Vehicle Assemblers:Contract manufacturers in Eastern Europe and Mexico procure pre-calibrated valve train modules from Tier-1 partners. Limited technical specification authority constrains direct component supplier relationships.
Tier-1 suppliers capture value chain position; aftermarket channels expand most quickly.
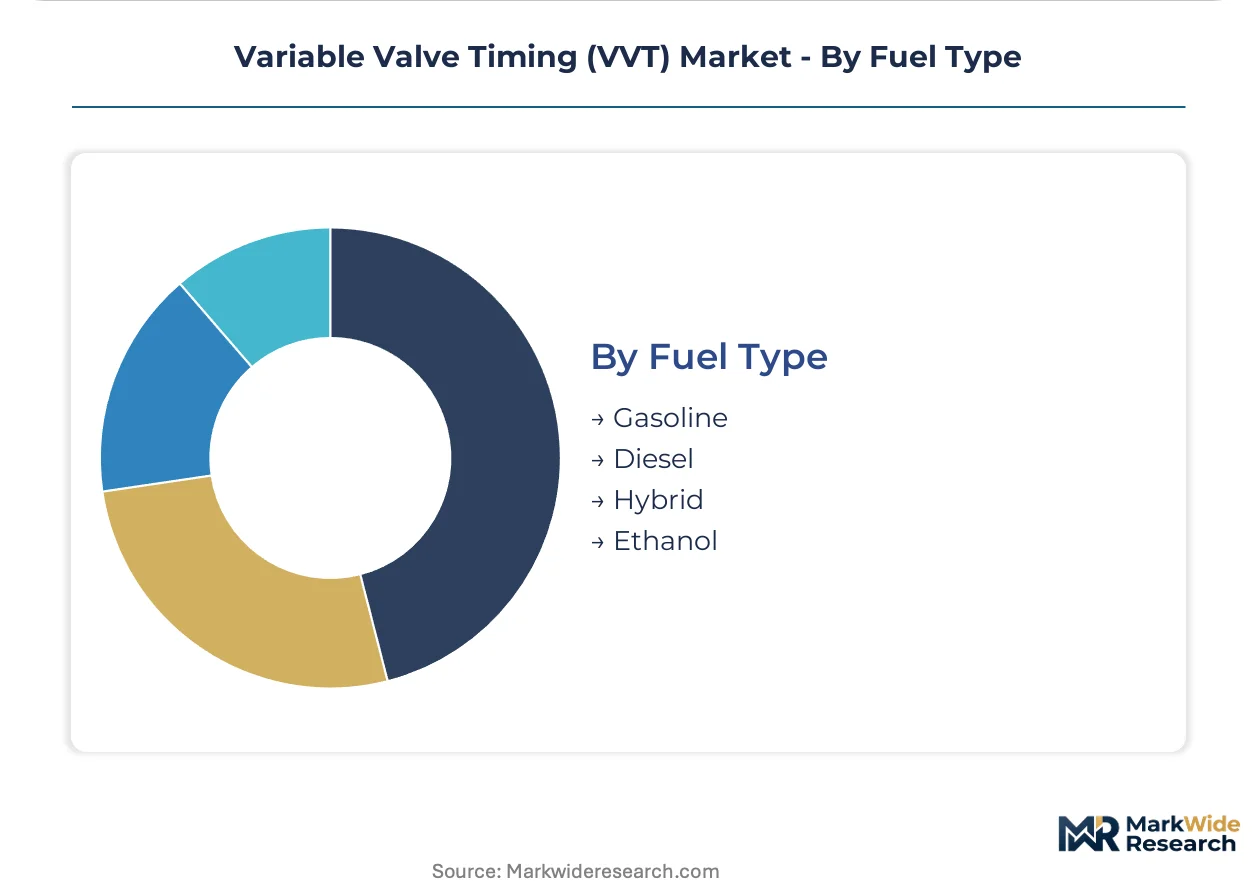
Fuel Type:
Regulatory stringency varies by combustion chemistry, with gasoline facing the steepest efficiency mandates and diesel confronting emission aftertreatment cost pressure.
- Gasoline:Direct injection turbocharged architectures require precise valve timing to mitigate knock and enable Miller-cycle operation. Chinese OEMs expand VVT penetration across domestic powertrain lineups to satisfy MIIT consumption regulations.
- Diesel:Compression ignition engines use VVT primarily for exhaust gas recirculation control and emission aftertreatment thermal management. European commercial vehicle manufacturers face EU Green Deal CO2 targets compressing investment timelines.
- Hybrid:Electromechanical valve control enables seamless transitions between Atkinson-cycle efficiency and Otto-cycle torque for dual-mode operation. Japanese OEMs anchor R&D commitment through METI top-runner standard compliance.
- Ethanol:Flexible-fuel architectures in Brazil require valve timing adjustment for varying octane and latent heat of vaporization. ANVISA fuel quality regulations interact with engine management calibration requirements.
Gasoline retains volume dominance; hybrid applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT Stage VI fuel consumption regulations in China are compressing VVT adoption timelines across Asia-Pacific OEM lineups. EPA Corporate Average Fuel Economy standards through model year 2032 sustain North American demand for cylinder deactivation technologies. EU CO2 fleet targets under the European Green Deal framework force powertrain efficiency investments despite BEV transition pressures.
China
Domestic OEMs expand electromechanical VVT sourcing to satisfy MIIT enforcement of Stage VI consumption rules. The MIIT mandates engine efficiency improvements that accelerate cam phaser penetration across gasoline direct-injection turbocharged architectures. Shanghai and Beijing house concentrated Tier-1 system integration facilities serving BYD and Geely powertrain divisions.
United States
Full-size truck and SUV segments face steep EPA compliance cliffs through 2032. EPA regulations force residual efficiency gains from remaining internal combustion production cycles. Detroit's automotive corridor anchors hydraulic VVT manufacturing for legacy powertrains while Michigan-based engineering centers pilot electromechanical transitions.
Germany
Premium hybrid OEMs adopt electromechanical cam phasers for cold-start emissions compliance. The KBA administers EU Green Deal CO2 fleet targets that sustain valve train R&D commitments. Stuttgart and Munich host integrated mechatronics development for 48V mild-hybrid VVT integration.
Japan
METI top-runner efficiency standards sustain domestic supplier precision camshaft phasing leadership. METI enforcement maintains R&D investment in Twin VVT-i architectures for hybrid powertrains. Toyota City and Nagoya industrial clusters anchor volume manufacturing for ASEAN export production.
South Korea
Hyundai and Kia specify electromechanical valve control for US-bound hybrid exports. The MFDS-aligned efficiency framework supports powertrain technology advancement. Ulsan and Hwaseong house concentrated cam phaser assembly serving domestic OEM technical specifications.
Variable Valve Timing (VVT) Market Competitive Landscape
Player mix skews toward diversified automotive Tier-1 suppliers with captive mechatronics capabilities. Market structure concentrates volume among integrators offering calibrated subsystem deliveries rather than catalog component vendors. Strategic archetypes include hydraulic heritage manufacturers navigating electromechanical transitions, semiconductor-capable system integrators controlling certification timelines, and precision machining specialists with captive camshaft production. Dominant competitive moves encompass backward integration into actuator controller software and strategic partnerships for ISO 26262 ASIL-D qualification acceleration.
Within the semiconductor-integrated tier, Robert Bosch GmbH and Mitsubishi Electric Corporation exemplify archetypes leveraging in-house chip manufacturing to compress functional safety certification cycles. Schaeffler AG occupies a position representing precision machining heritage with captive camshaft phasing component production. These three entities anchor the competitive landscape through differentiated control over critical supply chain nodes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Eaton Corporation Plc |
| Schaeffler AG |
| DENSO Corporation |
| BorgWarner Inc. |
| Aisin Corporation |
| Mitsubishi Electric Corporation |
| Continental AG |
| Delphi Technologies |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for precision camshaft phasing components concentrate margin capture with German and Japanese suppliers, translating supply scarcity into pricing leverage for ISO 26262 ASIL-D certified electromechanical systems while hydraulic heritage manufacturers absorb cost compression.
Pricing Analysis
Certification level creates the primary spread between premium electromechanical and standard hydraulic tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D qualification investment, volume scale, and captive semiconductor capability. Pricing pressure stems from rare earth magnet cost volatility constraining brushless DC motor economics. Aftermarket channels exhibit highest price sensitivity; OEM subsystem contracts demonstrate lowest.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for rare earth magnet shipments from Chinese processing facilities. Manufacturing concentrates in Germany, Japan, and China for precision camshaft machining and electromechanical actuator assembly. Supply rests on neodymium-dysprosium magnet supply, silicon carbide semiconductors, and precision steel alloys. Single-source vulnerability concentrates in Japanese precision grinding equipment. Distribution runs through Tier-1 calibrated subsystem contracts rather than catalog component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 26262 functional safety engineering talent concentrates competitive advantage with suppliers controlling captive semiconductor fabrication and software stack development. Electromechanical integration capability gaps separate margin leaders from component vendors facing displacement.
For Market Incumbents: Compound defensive positioning through backward integration into actuator controller software and acceleration of ASIL-D certification pipelines. Hydraulic heritage manufacturers face electromechanical transition timelines compressing returns. Priority lever centers on captive semiconductor sourcing to control rare earth magnet cost exposure. For New Entrants and Emerging Players: Differentiate on camless valve train convergence with combustion control software integration. India's underpenetrated passenger vehicle segment offers most penetrable geography under BIS efficiency norms and PLI scheme incentives. Go-to-market angle targets Tier-1 subsystem calibration contracts rather than discrete component supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized precision machining assets and dormant automotive qualifications. Long-term viability frames around the effective window for internal combustion investment cycles before battery electric substitution compresses addressable demand. Signal to monitor: MIIT Stage VI enforcement pace and hybrid powertrain architecture commitments from Chinese OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive chip production compresses ISO 26262 ASIL-D certification timelines for electromechanical actuators. |
| Camless Valve Train Convergence | Electromechanical actuation merges with advanced combustion software to enable fully flexible valve events. |
| India Market Entry Partnership | BIS efficiency norms and PLI incentives create first-mover positioning for electromechanical system suppliers. |
| Aftermarket Remanufacturing Channel Development | Certified VVT actuator replacement programs capture high-mileage Japanese and German vehicle service demand. |
| Hybrid Powertrain System Integration | Electromechanical valve control enables seamless Atkinson-Otto cycle transitions for dual-mode operation. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor sourcing specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA regulatory filings, MIIT Stage VI enforcement notices, METI top-runner standard documentation, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include actuation physics, combustion architecture, supply chain position, and regional regulatory cluster. CAGRs derived from regression analysis of historical penetration rates applied to projected powertrain investment cycles. Industry-specific inputs incorporated rare earth magnet price indices and hybrid powertrain adoption trajectories.
Material uncertainties — battery electric vehicle substitution velocity, rare earth supply disruptions, and regulatory enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market