
 Global Automotive Brake Components Market | 2026-2036
Global Automotive Brake Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Brake Components Market Analysis
Asset-light leasing models for brake manufacturing equipment is rewriting competitive entry barriers across the supply base. Robert Bosch GmbH leverages captive semiconductor sourcing to sustain integrated brake system output. Continental AG anchors European OEM relationships through specialized electromechanical brake development. Aisin Corporation competes in Asian markets with cost-optimized drum brake manufacturing scale.
Automotive brake components encompass friction-generating assemblies, hydraulic actuation hardware, and electronic control modules engineered to decelerate or immobilize vehicles through kinetic energy conversion to thermal energy; disc brake rotors typically operate within temperature thresholds of 300–800°C depending on vehicle class and duty cycle. Brake pad formulations using ceramic matrix composites command premium positioning in passenger vehicle segments where NVH performance determines OEM selection criteria. Drum brake architectures retain cost advantages in commercial vehicle rear axle applications where sustained load braking generates extreme thermal loads. Aftermarket distribution channels occupy fragmented margin pools across developing economies where vehicle parc age exceeds twelve years on average.
NHTSA Federal Motor Vehicle Safety Standards, ECE R90 brake lining certification, and China's GB 5763 friction material specifications collectively mandate reduced stopping distances and restricted hazardous substance content in brake formulations. These frameworks compel suppliers to reformulate friction materials and validate new compounds through expanded dynamometer testing protocols. Stakeholders must monitor brake-by-wire regulatory homologation timelines as electromechanical systems displace conventional hydraulic architectures across vehicle platforms.
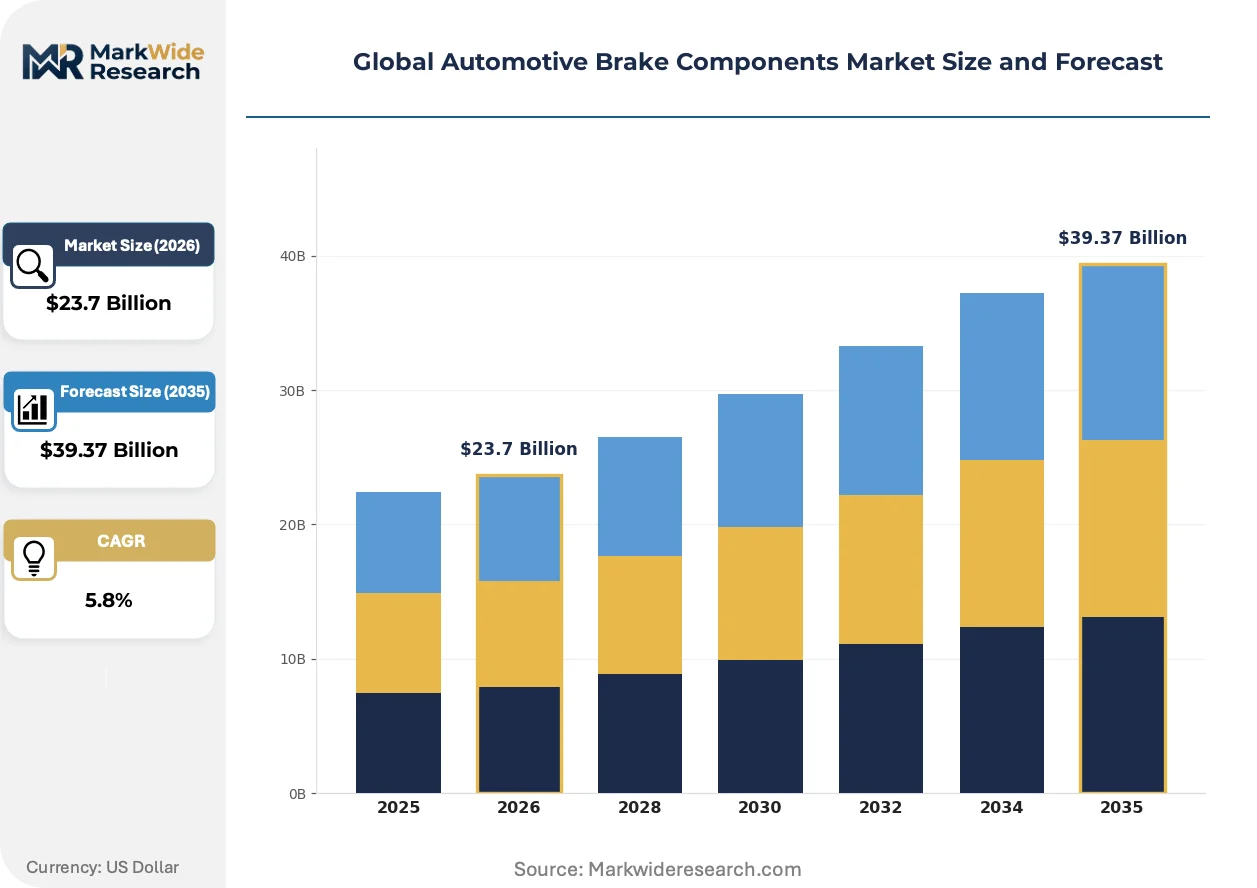
Market Dynamics
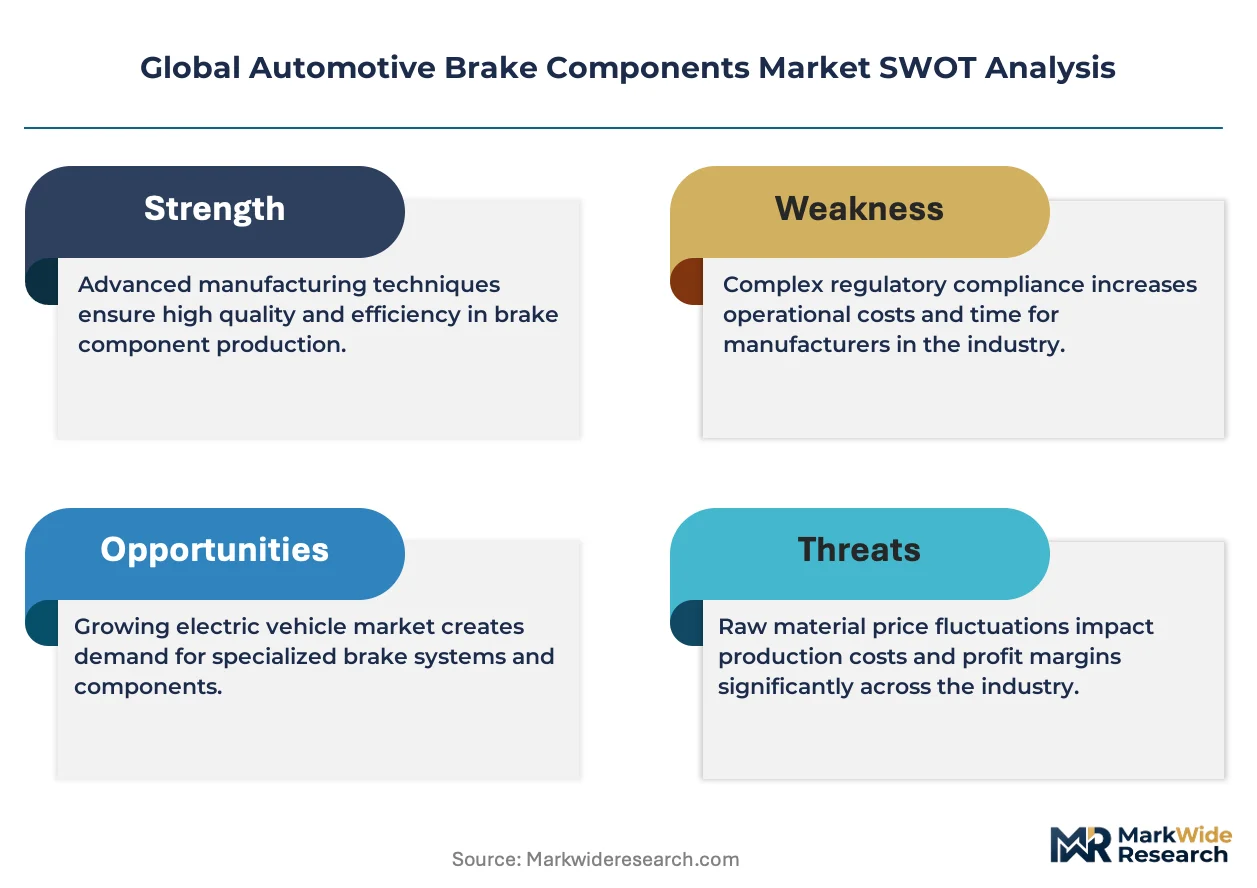
Brake-by-wire electrification is compressing supplier margins while redistributing value toward semiconductor-integrated system architects. Hydraulic component specialists face existential pressure to reconstitute capabilities around electromechanical actuation and software-defined braking protocols.
Growth Catalysts
- NHTSA stopping-distance mandates:Heavy-duty truck and bus manufacturers in the United States must deploy advanced air disc brake configurations to meet tightened Federal Motor Vehicle Safety Standards, pulling friction material upgrades through the supply chain.
- China's electrified platform scale:Domestic OEMs in China are integrating brake-by-wire architectures into dedicated EV skateboards, creating parallel demand for electromechanical calipers and pedal simulators.
- Ceramic matrix composite formulations:Passenger vehicle segments prioritize NVH performance, compelling suppliers to reformulate brake pads around low-metallic and copper-free ceramic matrices that satisfy ECE R90 certification thresholds.
Market Restraints
- Rare earth magnet supply concentration:Electromechanical brake motors depend on neodymium-dysprosium supply chains concentrated in Chinese processing facilities, exposing brake system manufacturers to input cost volatility and export restriction risk.
- Friction material R&D capex intensity:Dynamometer testing protocols for new compound validation require sustained capital deployment that mid-tier suppliers cannot absorb without strategic partnerships.
- Legacy hydraulic infrastructure lock-in:Commercial vehicle fleets retain drum brake architectures on rear axles due to thermal load tolerance, slowing the revenue transition to higher-value disc brake systems.
Strategic Opportunities
- India commercial vehicle fleet modernization:Expanding logistics and e-commerce transportation networks in India create demand for air brake system upgrades as fleet operators prioritize payload efficiency and driver safety compliance.
- EU Green Deal material compliance:REACH restrictions on copper and antimony content in friction materials create first-mover advantage for suppliers with validated copper-free formulations already in European homologation pipelines.
- Aftermarket channel digitization:Independent repair networks in Brazil and Mexico are adopting B2B platform procurement for brake pad and rotor inventory, compressing traditional distributor markups and enabling direct supplier relationships.
Industry Challenges
- Embedded software talent scarcity:Brake-by-wire development requires control systems engineers with functional safety expertise under ISO 26262, a skill set concentrated at Tier 1 automotive electronics suppliers rather than traditional brake manufacturers.
- Homologation timeline compression:Electromechanical braking systems face extended validation cycles under UN R79 and UN R13-H frameworks, delaying revenue recognition for suppliers transitioning from hydraulic to brake-by-wire portfolios.
- Legacy system integration complexity:Hybrid vehicle architectures demand seamless handoff between regenerative braking and friction braking, requiring software calibration expertise that stretches traditional hardware-focused engineering organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Brake Components Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Brake Pads, Brake Shoes Material: Metallic, Non-Metallic, Ceramic, Organic Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles End User: OEMs, Aftermarket Providers, Retailers, Distributors |
| Companies Covered | Brembo S.p.A., Continental AG, ZF Friedrichshafen AG, Akebono Brake Industry Co., Ltd., Robert Bosch GmbH, Knorr-Bremse AG, Aisin Corporation, Hitachi Astemo, Ltd., Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Brake Components Market Emerging Trajectories
Digital twin simulation is collapsing brake system development cycles while predictive maintenance algorithms restructure aftermarket revenue models. Three convergent forces are reconstituting competitive advantage around software-integrated hardware platforms.
Electromechanical brake actuation is virtualizing the hydraulic control layer through motor-driven caliper architectures that eliminate master cylinders and brake fluid circuits. Premium passenger vehicle platforms in Germany and South Korea are adopting these systems at accelerated cadences. This virtualization is compressing the traditional Tier 2 hydraulic component supply base while elevating semiconductor and motor suppliers into direct OEM relationships.
REACH Annex XVII amendments are restricting copper content in brake friction materials to 0.5% by weight, forcing European suppliers to reformulate around alternative fiber matrices and ceramic binders. The regulation is accelerating R&D collaboration between friction material compounders and raw material processors in Spain and Poland. Aftermarket distributors in Italy and France are now certifying supplier compliance as a procurement gate, shifting competitive selection toward environmental credentialing.
Fleet operators are consolidating brake maintenance spend under total-cost-of-ownership contracts that bundle friction components with predictive wear monitoring. Heavy-duty logistics providers in Germany and long-haul operators in Australia are piloting sensor-embedded brake pads that transmit thickness data to fleet management platforms. This unbundling of component supply from service delivery is most visible in North American commercial vehicle leasing structures, where lessors demand brake life guarantees backed by real-time condition data.
Global Automotive Brake Components Market Segmentation
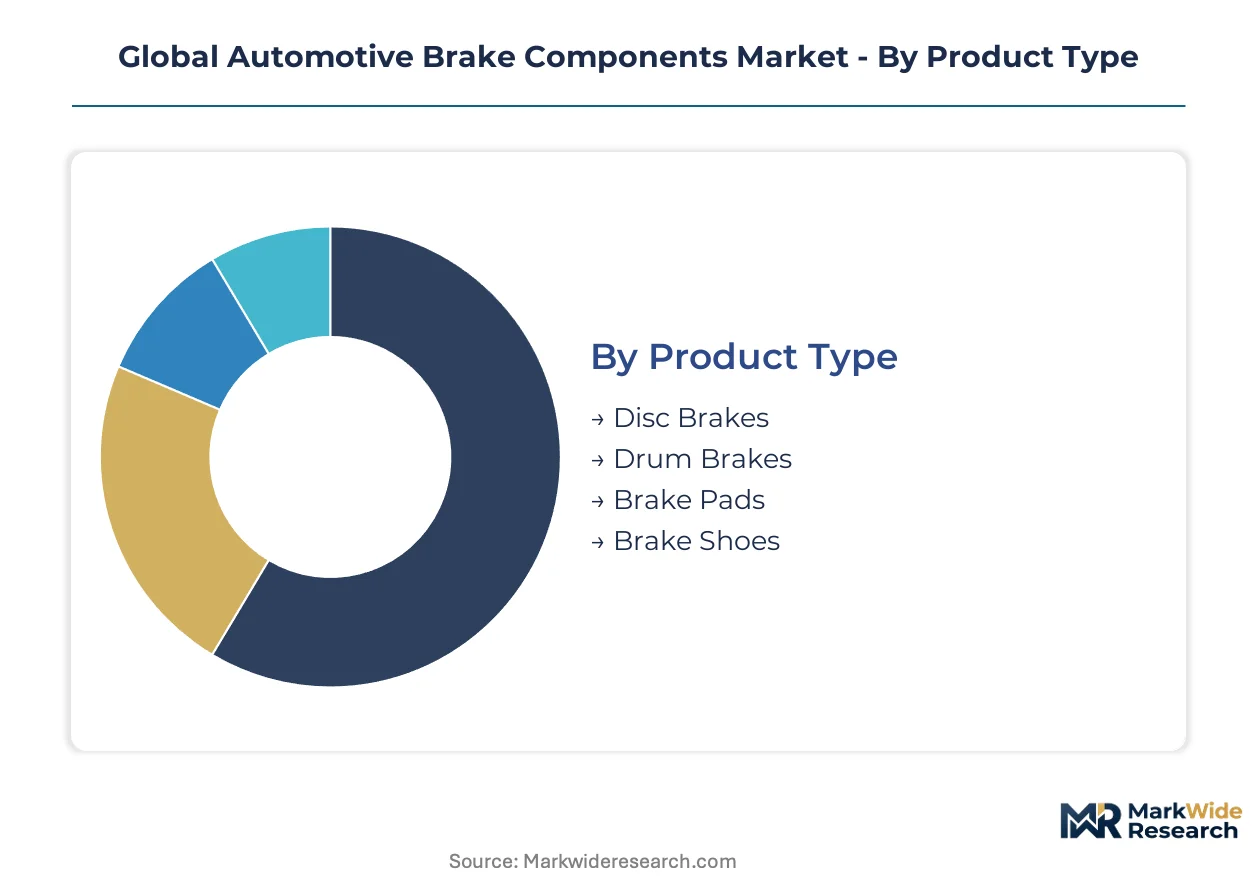
Brake component segmentation reveals divergent technology lifecycles and margin architectures across the supply base. Product and material categories stratify between mature hydraulic systems and emerging electromechanical platforms, while application and channel segments expose fundamentally different procurement behaviors and regulatory exposure profiles.
Product Type:
Mature disc and drum architectures dominate installed base volumes, yet electromechanical actuation is redrawing competitive boundaries between established and emergent product categories.
- Disc Brakes:Rotor-caliper assemblies utilizing cast iron or carbon-ceramic matrices operate across 300–800°C thermal envelopes depending on vehicle duty cycle. Passenger vehicle OEMs in Germany and South Korea are accelerating adoption of electromechanical disc calipers that eliminate hydraulic circuits entirely.
- Drum Brakes:Expanding-shoe mechanisms retain cost advantages in commercial vehicle rear axle applications where sustained load braking generates extreme thermal stress. Fleet operators in India continue specifying drum architectures for payload efficiency despite disc brake performance advantages.
- Brake Pads:Friction material formulations span low-metallic, ceramic, and copper-free matrices governed by ECE R90 and REACH Annex XVII compliance thresholds.
- Brake Shoes:Curved friction segments for drum assemblies serve replacement demand in developing economies where vehicle parc age exceeds twelve years.
Disc brakes retain volume leadership; electromechanical caliper variants hold the steepest expansion curve.
Material:
Cost-to-performance positioning separates commodity metallic formulations from premium ceramic matrices commanding OEM selection priority.
- Metallic:Iron and steel-based friction materials deliver baseline stopping performance at lowest unit cost. Commercial vehicle fleets in Brazil and Mexico specify metallic pads for high-wear duty cycles where replacement frequency dominates total cost calculations.
- Ceramic:Silica-carbide and copper-free ceramic matrices satisfy NVH performance thresholds and REACH copper restrictions below 0.5% by weight. Premium passenger vehicle platforms specify ceramic formulations for reduced dust generation and extended rotor life.
- Non-Metallic:Aramid fiber and glass-reinforced composites occupy mid-tier positioning between metallic cost floors and ceramic performance ceilings.
- Organic:Rubber and resin-bound friction materials serve economy replacement segments with limited thermal tolerance.
Metallic materials retain volume leadership; ceramic formulations gain share fastest amid regulatory copper restrictions.
Application:
Customer type concentration varies sharply between consumer-driven passenger segments and fleet-procured commercial categories with divergent total-cost-of-ownership calculus.
- Passenger Vehicles:Individual ownership models prioritize NVH performance and warranty coverage, driving ceramic pad specification and integrated brake-by-wire adoption. OEMs in China are scaling electromechanical architectures across dedicated EV skateboard platforms.
- Commercial Vehicles:Fleet procurement contracts consolidate brake maintenance spend under predictive wear monitoring agreements. Logistics operators in Germany pilot sensor-embedded pads transmitting thickness data to fleet management platforms.
- Heavy-Duty Trucks:NHTSA stopping-distance mandates compel air disc brake deployment across United States heavy-duty applications, pulling friction material upgrades through supplier tiers.
- Motorcycles:Two-wheeler brake demand concentrates in India and Southeast Asia where drum-drum and disc-drum configurations balance cost against wet-weather performance requirements.
Passenger vehicles retain volume leadership; heavy-duty trucks climb fastest on regulatory compliance spending.
End User:
Channel structure fragments between captive OEM supply relationships and fragmented aftermarket procurement patterns with divergent margin extraction potential.
- OEMs:Vehicle manufacturers specify brake systems at platform design phase, locking in multi-year supply agreements with Tier 1 integrators. Brake-by-wire homologation under UN R79 and UN R13-H extends validation cycles, delaying revenue recognition for electromechanical suppliers.
- Aftermarket Providers:Independent repair networks in Brazil and Mexico are adopting B2B platform procurement for pad and rotor inventory, compressing traditional distributor markups and enabling direct supplier relationships.
- Retailers:Consumer-facing parts channels serve DIY maintenance segments with price-transparent commodity friction materials.
- Distributors:Regional warehousing networks retain relevance in developing economies where independent garages lack capital for direct platform procurement.
OEMs retain volume leadership; aftermarket providers are expanding most quickly through channel digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for brake components favor manufacturing hubs with integrated steel and semiconductor supply chains. China runs substantial surpluses in friction materials and electromechanical calipers. Germany and Japan maintain specialized export positions in premium disc systems and ceramic formulations.
China
Domestic OEMs at BYD and NIO are scaling brake-by-wire architectures across dedicated EV skateboard platforms. GB 5763 friction material specifications mandate restricted hazardous substance content in brake pad formulations. Manufacturing clusters in Shanghai and Guangdong province are attracting electromechanical actuator suppliers seeking proximity to battery pack integrators.
United States
Heavy-duty truck manufacturers face NHTSA stopping-distance mandates requiring advanced air disc brake deployment. Commercial vehicle fleets in Texas and California are consolidating maintenance spend under predictive wear monitoring contracts. Detroit-area suppliers anchor North American production of integrated brake systems for light truck platforms.
Germany
Premium passenger vehicle OEMs in Munich and Stuttgart are accelerating adoption of electromechanical calipers that eliminate hydraulic circuits. REACH Annex XVII copper restrictions below 0.5% by weight are forcing reformulation of friction materials around ceramic binders. Suppliers in Baden-Württemberg are collaborating with raw material processors in Spain and Poland on alternative fiber matrices.
India
Expanding logistics and e-commerce transportation networks are driving demand for air brake system upgrades in commercial vehicle fleets. Bureau of Indian Standards certification requirements are tightening safety compliance for heavy-duty applications. Manufacturing corridors in Maharashtra and Tamil Nadu are scaling drum brake production for cost-sensitive rear axle specifications.
Japan
Automotive electronics specialists in Nagoya and Tokyo are developing ISO 26262-compliant control systems for brake-by-wire platforms. METI industrial policy is channeling R&D subsidies toward copper-free friction material development. Suppliers in the Kansai region are integrating semiconductor sourcing relationships for motor-driven caliper architectures.
Global Automotive Brake Components Market Vendor Landscape
On the supply side, the industry is consolidating around integrated system architects with captive semiconductor sourcing and software-defined braking capabilities. Tier 1 brake manufacturers face margin compression as electromechanical actuation displaces hydraulic component volumes. Three archetypes dominate: diversified automotive electronics conglomerates, specialized friction material compounders, and commercial vehicle air brake specialists. Competitive moves center on backward integration into rare earth magnet supply chains and strategic partnerships for dynamometer testing capacity.
Within the diversified systems tier, Robert Bosch GmbH and Continental AG exemplify integrated brake system architects with European captive supply networks. Aisin Corporation occupies a position among Asian-scale manufacturers competing on cost-optimized drum brake production. Brembo S.p.A. anchors the premium performance segment with Italian heritage in motorsport-derived ceramic formulations. These three represent distinct competitive vectors: semiconductor-integrated system control, manufacturing scale in emerging markets, and brand premiumization through thermal performance engineering.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Continental AG |
| ZF Friedrichshafen AG |
| Akebono Brake Industry Co., Ltd. |
| Robert Bosch GmbH |
| Knorr-Bremse AG |
| Aisin Corporation |
| Hitachi Astemo, Ltd. |
| Mando Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese friction material manufacturing is compressing export pricing while forcing European suppliers toward premium ceramic formulations. This utilization asymmetry between regions creates divergent supplier behavior: Asian producers chase volume through aggressive contract terms while Western specialists extract margin from REACH-compliant copper-free grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across brake system procurement. Pricing stratifies across premium, standard, and economy tiers based on ECE R90 certification level and NVH performance grade. Cost compression in metallic friction materials is intensifying because Brazilian and Mexican commercial fleets prioritize replacement frequency over thermal performance. Fleet operators exhibit highest price sensitivity; German premium passenger OEMs demonstrate lowest sensitivity due to brake-by-wire integration requirements.
Supply Chain Analysis
Export control regimes limiting semiconductor flows to Chinese brake-by-wire actuator manufacturers are reshaping component sourcing patterns. Manufacturing concentrates in China, Germany, and Mexico for friction materials, electromechanical systems, and NAFTA-advantaged assembly respectively. Supply chains draw from neodymium-dysprosium rare earth magnets, cast iron feedstock, and ceramic fiber matrices. Single-source vulnerability in Chinese rare earth processing exposes brake motor suppliers to input disruption. Distribution runs through captive OEM supply agreements and fragmented aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire electrification represents an early-cycle expansion story as dedicated EV skateboard platforms drive electromechanical caliper penetration beyond historical hydraulic replacement rates.
For Market Incumbents: Build captive semiconductor sourcing moats to secure brake-by-wire system output against allocation constraints. Deepen backward integration into rare earth magnet supply chains to offset Chinese processing concentration risk. Expand dynamometer testing capacity through partnerships with Spanish and Polish raw material processors to accelerate REACH-compliant compound validation.
For New Entrants and Emerging Players: Establish a beachhead in India's commercial vehicle air brake aftermarket where fleet modernization outpaces domestic supplier capacity. Target sensor-embedded brake pad development for German logistics operators piloting predictive maintenance contracts. Pursue direct B2B platform relationships with Brazilian and Mexican independent repair networks to bypass traditional distributor markups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical brake development as ISO 26262 functional safety compliance demands embedded software talent acquisition. Five-to-ten year viability favors diversified automotive electronics conglomerates with existing semiconductor relationships over pure-play friction material compounders. Monitor brake-by-wire homologation timeline acceleration under UN R79 and UN R13-H frameworks as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Consolidates Tier 1 supplier relationships around electromechanical architectures eliminating hydraulic circuits. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-dysprosium flows against Chinese export restriction exposure for motor-driven caliper production. |
| Copper-Free Formulation Certification | Accelerates REACH Annex XVII compliance pipelines ahead of European aftermarket distributor procurement gates. |
| Predictive Maintenance Software Integration | Captures fleet operator brake life guarantees through real-time wear monitoring data monetization. |
| India Manufacturing Footprint Expansion | Positions air brake production adjacent to Maharashtra and Tamil Nadu commercial vehicle assembly corridors. |
Methodological Framework
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads anchored the qualitative base. Primary interview insights combined with secondary validation from vehicle production databases, IHS Markit registration data, customs/trade records, and SEC filings from automotive component suppliers. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions across the analysis window.
Scenario-bracketing framed demand projections across low, base, and high penetration cases for brake-by-wire adoption. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis against historical technology substitution patterns and named regulatory compliance deadlines. Forecast inputs included NHTSA stopping-distance mandate implementation pace and China domestic OEM electrified platform rollout schedules.
Stress conditions across rare earth supply disruption, REACH compliance timeline acceleration, and brake-by-wire homologation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology penetration curves and regulatory enforcement intensity. Material shifts in Chinese export control scope or UN R79 validation protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Door Module Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
China Automotive Composites Market
Automotive Components
GCC Automotive Lubrication Services Market