
 Automotive Slack Adjuster Market | 2026-2036
Automotive Slack Adjuster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Slack Adjuster Market Analysis
Fleet operators is unwinding the historical dominance of vehicle manufacturers in slack adjuster procurement, as outsourced maintenance contracts consolidate buying power under single service providers. Haldex AB leverages its integrated brake-system portfolio to capture recurring aftermarket revenue from these fleet contracts. Bendix Commercial Vehicle Systems anchors North American supply through its captive distribution network serving major trucking corridors. Knorr-Bremse AG dominates European rail and road braking, extending its adjuster expertise into integrated mechatronic modules.
An automotive slack adjuster is a mechanical linkage device that maintains optimal brake shoe-to-drum clearance in air-brake systems, typically fabricated from ductile iron or forged steel with precision-machined worm gears and calibrated spring mechanisms rated for millions of adjustment cycles. Its primary function is to compensate for lining wear automatically, ensuring consistent braking performance and regulatory compliance across heavy commercial vehicle duty cycles. Heavy-duty product types command the deepest margin pools due to forging complexity and OEM certification barriers, while electronic technology segments are attracting engineering investment as brake-by-wire architectures displace passive mechanical systems in premium truck platforms. The aftermarket retailer channel remains structurally fragmented, creating pricing pressure on standard manual adjusters even as fleet operators consolidate toward authorized service networks for warranty-critical components.
NHTSA, the EPA, and the EU's ECE R13 braking regulations collectively shape slack adjuster specifications, with NHTSA's automatic brake adjuster mandates driving US OEM specification upgrades and ECE R13 type-approval requirements controlling European market access for non-certified suppliers. The EPA's Phase 2 greenhouse gas standards indirectly tighten adjuster tolerances by linking brake drag to fuel efficiency compliance, forcing redesigns of sealing and return-spring architectures. Stakeholders must monitor how pending updates to ECE R13 and potential NHTSA rulemakings on connected braking systems redefine the boundary between mechanical adjusters and integrated electronic wear sensors.
Market Dynamics
Fleet maintenance outsourcing is compressing the traditional OEM-dealer-channel hierarchy into direct manufacturer-to-fleet contracting, rewiring how slack adjuster volume flows through distribution networks and who captures lifetime value from brake-system components.
Growth Catalysts
- NHTSA automatic brake adjuster mandates:US federal requirements for automatic adjustment mechanisms on commercial vehicles are phasing out manual adjuster installations and forcing specification upgrades across Class 7-8 truck platforms.
- Electronic wear sensing integration:Brake-by-wire architectures in premium truck platforms are embedding intelligent slack adjusters with real-time position feedback, creating new content value per axle.
- Stuttgart-Munich production corridor:Germany's commercial vehicle manufacturing concentration anchors component sourcing decisions, with tier-1 brake suppliers co-locating adjuster production near OEM assembly plants.
Market Restraints
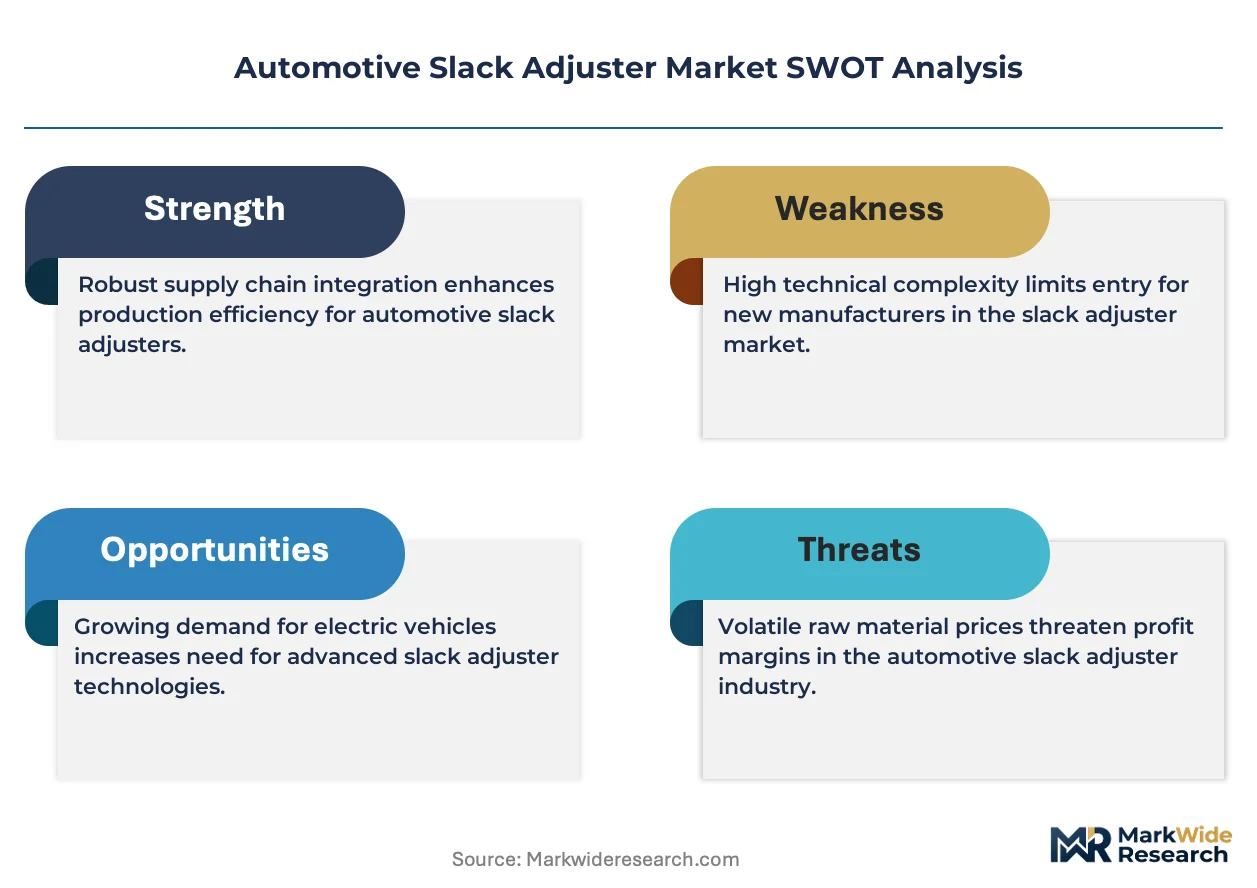
- Ductile iron input volatility:Foundry-grade iron pricing fluctuations compress margin predictability for forged adjuster manufacturers locked into annual supply agreements.
- Single-source worm gear supply:Precision-machined gear production concentrates among specialized European tool-and-die houses, creating geographic concentration risk for non-integrated assemblers.
- Mechanical-to-electronic substitution timeline:Brake-system electrification threatens long-term demand for passive mechanical adjusters, though regulatory grandfathering slows displacement in existing fleets.
Strategic Opportunities
- Connected brake diagnostics convergence:Integration of slack adjuster position data with fleet telematics platforms enables predictive maintenance services and recurring software revenue streams.
- Authorized service network expansion:Fleet operators consolidating procurement under warranty-compliant maintenance contracts create captive demand channels bypassing fragmented aftermarket retailers.
- ECE R13 type-approval harmonization:Pending regulatory alignment across European braking standards may streamline certification pathways for adjuster suppliers seeking multi-country market access.
Industry Challenges
- Mechatronics skill scarcity:Electronic adjuster development requires firmware engineers and sensor calibration specialists scarce among traditional mechanical component suppliers.
- Dual-certification burden:Suppliers must simultaneously maintain NHTSA compliance for US markets and ECE R13 homologation for European access, duplicating testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Slack Adjuster Market |
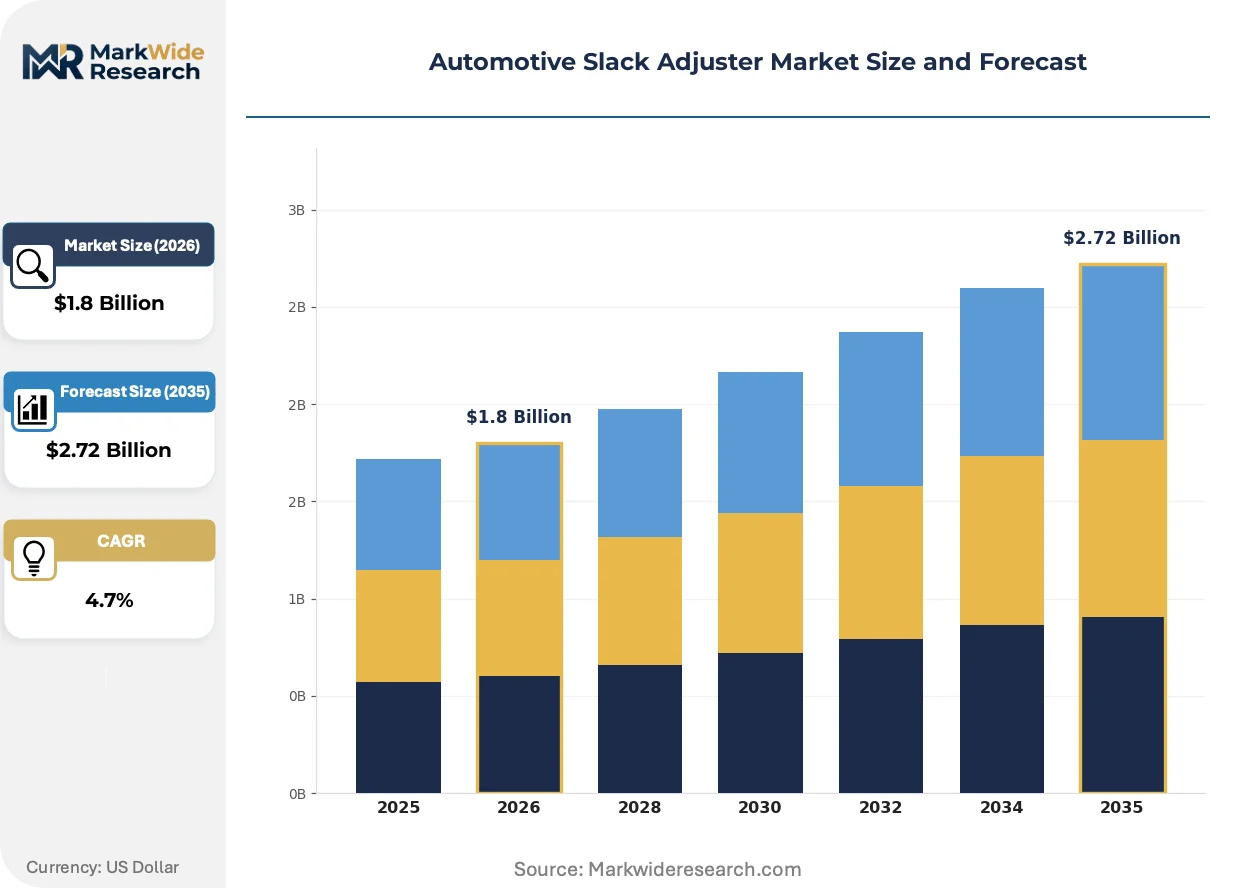
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-duty, Light-duty, Pneumatic, Hydraulic End User: Fleet Operators, Vehicle Manufacturers, Aftermarket Retailers, Maintenance Workshops Technology: Active, Passive, Electronic, Manual Application: Trucks, Buses, Trailers, Commercial Vehicles |
| Companies Covered | Haldex AB, Bendix Commercial Vehicle Systems, Knorr-Bremse AG, SAF-Holland, Wabtec Corporation, ZF Friedrichshafen AG, Accuride Corporation, Ferdinand Bilstein GmbH, Meritor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Slack Adjuster Market Emerging Trajectories
Brake-system digitization is dissolving the boundary between mechanical linkages and electronic control modules, with intelligent adjusters emerging as data acquisition nodes within connected vehicle architectures.
Integrated electronic slack adjusters with embedded Hall-effect position sensors are miniaturizing the traditional mechanical housing while adding real-time stroke monitoring capability. Premium truck OEMs in Germany and the US are specifying these units for new platform launches. The technology is miniaturizing the adjuster footprint enough to package within space-constrained steer axle brake assemblies previously reserved for manual units.
ECE R13 braking regulation updates under technical review are tightening tolerance requirements for automatic brake adjustment systems across European commercial vehicle categories. The proposed amendments would mandate redundant adjustment verification and expanded temperature cycling tests. Heavy-duty drum brake suppliers serving Scania and MAN platforms are pre-emptively redesigning return-spring architectures to meet anticipated compliance thresholds.
Long-term service contracts are displacing transactional parts purchasing as the dominant procurement mode among North American fleet operators with 500+ vehicle holdings. These agreements bundle adjuster replacement into mileage-based maintenance schedules, compressing price visibility and shifting volume toward authorized distributor networks. The pattern is most pronounced along the I-75 and I-95 trucking corridors where consolidated fleet maintenance providers have established regional hub operations.
Automotive Slack Adjuster Market Segmentation
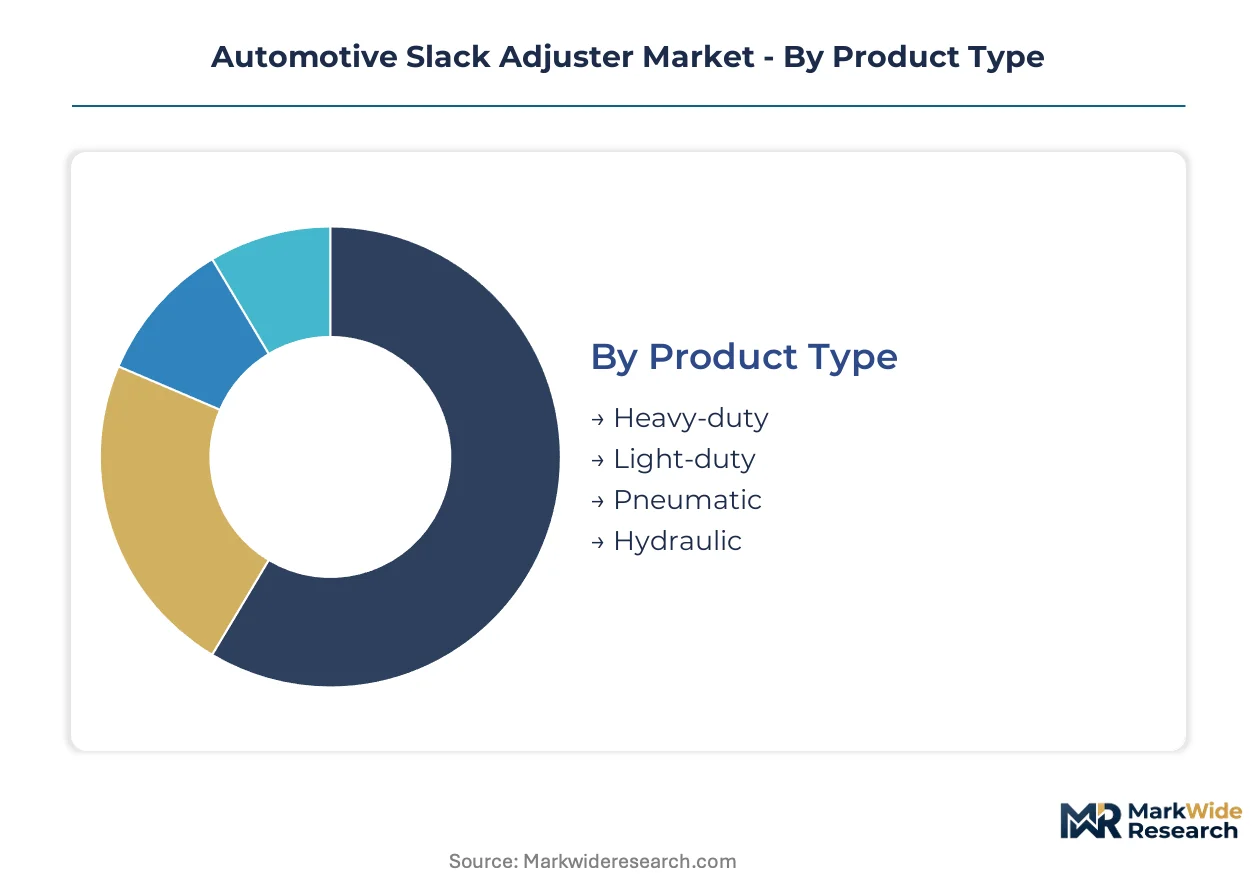
Segmentation in the automotive slack adjuster market exposes how margin capture diverges between mechanical legacy systems and emerging electronic architectures. Procurement channel consolidation and brake-by-wire platform launches are reshaping which segments command pricing power and engineering investment.
Product Type:
Margin pools concentrate in forged components where OEM certification barriers and metallurgical complexity protect pricing.
- Heavy-duty:Forged steel construction with precision-machined worm gears rated for millions of adjustment cycles under extreme axle loads. Demand concentrates among Class 8 truck OEMs in Germany and the US where NHTSA mandates and ECE R13 compliance drive specification upgrades.
- Light-duty:Ductile iron castings serving medium-duty commercial platforms with reduced wear-cycle requirements. Fleet operators in North America are consolidating procurement of these units through outsourced maintenance contracts, compressing aftermarket pricing visibility.
- Pneumatic:Air-actuated adjustment mechanisms integrated with compressed brake systems on European commercial vehicles.
- Hydraulic:Fluid-powered units serving specialty trailer applications with space-constrained brake packaging.
Heavy-duty holds installed capacity. Pneumatic is rotating up the share rankings.
End User:
Volume flows are rewiring as direct manufacturer-to-fleet contracting displaces traditional dealer-channel hierarchies.
- Fleet Operators:Consolidated buyers with 500+ vehicle holdings now contract directly for mileage-based maintenance bundles. These agreements capture lifetime brake-system value and bypass fragmented aftermarket retailers.
- Vehicle Manufacturers:OEM specification decisions are concentrating in Stuttgart and Munich production corridors where tier-1 brake suppliers co-locate adjuster production near assembly plants.
- Aftermarket Retailers:Structurally fragmented channel facing pricing pressure on standard manual adjusters as warranty-compliant service networks capture fleet volume.
- Maintenance Workshops:Authorized service providers along I-75 and I-95 trucking corridors are consolidating regional hub operations to serve consolidated fleet contracts.
Fleet operators hold installed capacity. Maintenance workshops are rotating up the share rankings.
Technology:
Engineering investment is concentrating where brake-by-wire architectures embed intelligent adjustment with real-time position feedback.
- Electronic:Hall-effect sensor integration enabling stroke monitoring and telematics connectivity. Premium truck OEMs in Germany and the US specify these for new platform launches, miniaturizing housings to fit steer axle constraints.
- Active:Self-adjusting mechanisms with continuous wear compensation under dynamic operating conditions.
- Passive:Spring-return systems requiring manual intervention, facing long-term displacement threat from electrification despite regulatory grandfathering slowing fleet turnover.
- Manual:Mechanical linkages phased out of US Class 7-8 platforms under NHTSA automatic brake adjuster mandates.
Passive holds installed capacity. Electronic is climbing the fastest.
Application:
Platform-specific packaging requirements and duty-cycle severity drive specification differentiation across vehicle categories.
- Trucks:Class 7-8 platforms dominate adjuster content per axle with dual-circuit air brake systems. NHTSA mandates and EPA Phase 2 fuel efficiency standards tighten tolerance requirements and drive automatic adjustment adoption.
- Buses:Urban transit duty cycles with frequent stop-start braking accelerate lining wear and adjustment frequency.
- Trailers:Space-constrained brake assemblies on multi-axle configurations favor compact adjuster packaging.
- Commercial Vehicles:Broad category spanning vocational trucks and specialty transport equipment with heterogeneous brake-system architectures.
Trucks hold installed capacity. Buses are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries and forges supply the densest concentration of precision-machined worm gear capacity for brake-system linkages. Stuttgart and Munich anchor component sourcing decisions for European commercial vehicle production.
United States
Class 8 truck assembly plants across Michigan, Ohio, and Texas drive specification volumes for automatic brake adjusters. NHTSA mandates for automatic adjustment mechanisms on commercial vehicles phase out manual installations. Detroit-area brake suppliers co-locate forging operations near OEM final assembly corridors.
Germany
Scania and MAN production platforms in Bavaria and Lower Saxony generate concentrated demand for heavy-duty forged adjusters. ECE R13 braking regulations control type-approval requirements for European market access. Stuttgart-Munich production corridors anchor tier-1 brake supplier co-location strategies.
China
Domestic commercial vehicle manufacturers in Shandong and Hubei provinces scale procurement of ductile iron casting capacity. GB standards for commercial vehicle braking systems shape local certification requirements. Yangtze River Delta forging clusters supply precision-machined gear components to brake-system assemblers.
India
Tata Motors and Ashok Leyland production hubs in Maharashtra and Tamil Nadu drive medium-duty adjuster demand. BIS certification requirements for automotive brake components create compliance thresholds for component suppliers. Pune-Chennai manufacturing corridors concentrate tier-2 forging and machining capacity.
Automotive Slack Adjuster Market Vendor Landscape
Concentration sits with integrated brake-system suppliers possessing captive forging capacity and OEM certification relationships. The vendor base separates into three strategic tiers: multinational brake-system integrators with full-platform portfolios; regional forging specialists supplying precision-machined subassemblies; and aftermarket distributors consolidating procurement for fleet maintenance networks. Dominant competitive moves include backward integration into precision gear machining and geographic co-location near OEM assembly plants.
Within the integrated-system tier, Haldex AB, Knorr-Bremse AG, and Bendix Commercial Vehicle Systems exemplify the archetype of brake-system suppliers capturing recurring aftermarket revenue through fleet service contracts. Haldex anchors European supply through its integrated portfolio. Knorr-Bremse occupies a position spanning rail and road braking expertise. Bendix represents North American market presence through distribution networks serving major trucking corridors.
| Leading Market Players |
|---|
| Haldex AB |
| Bendix Commercial Vehicle Systems |
| Knorr-Bremse AG |
| SAF-Holland |
| Wabtec Corporation |
| ZF Friedrichshafen AG |
| Accuride Corporation |
| Ferdinand Bilstein GmbH |
| Meritor |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in German precision forging establish minimum efficient scale thresholds that filter out marginal producers and sustain price floors for heavy-duty slack adjuster assemblies. This concentration of metallurgical capacity simultaneously anchors supply security for tier-1 brake suppliers and limits downward pricing flexibility on certified components.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified forged units from aftermarket ductile iron castings and unbranded manual replacements. Fleet procurement consolidation compresses margins on standard-tier products while premium electronic adjusters with embedded sensors command sustained price premiums. Cost compression in the aftermarket channel intensifies because fragmented retailers compete for declining transactional volume. Fleet operators with direct manufacturer contracts exhibit lowest price sensitivity, whereas independent maintenance workshops face acute margin pressure from warranty-compliant service networks.
Supply Chain Analysis
Germany and China anchor global production of precision-machined worm gears and ductile iron castings respectively, with India emerging as a secondary forging hub for medium-duty applications. Brake-system assemblers draw from foundry-grade iron, specialized tool-and-die capacity, and calibrated spring mechanisms as critical inputs. Single-source vulnerability concentrates in European precision gear machining, where specialized tool-and-die houses serve multiple tier-1 suppliers. Distribution runs through authorized service networks for fleet contracts and fragmented aftermarket retailers for transactional replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where NHTSA and ECE R13 certification requirements create entrenched switching costs for OEM supply relationships. Incumbents possess durable advantage through captive forging capacity and homologation relationships that new entrants cannot rapidly replicate.
For Market Incumbents: Consolidate precision gear machining capacity through backward integration into European tool-and-die suppliers, eliminating single-source exposure while capturing margin pools currently leaking to specialized subcomponent vendors. Expand authorized service network coverage along I-75 and I-95 corridors to lock in fleet maintenance contract renewals before regional distributors consolidate hub operations.
For New Entrants and Emerging Players: Predictive maintenance data services represent the most penetrable white-space where integrated brake-system suppliers under-serve smaller fleet operators lacking in-house telematics capabilities. Target medium-duty commercial vehicle segments in India and China where BIS and GB certification pathways offer faster market entry than NHTSA or ECE R13 homologation. Pursue white-label sensor calibration partnerships with established brake-system assemblers to bypass direct OEM certification barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with captive fleet service contracts and integrated brake-system portfolios that capture lifetime component value. Long-term viability favors targets with electronic adjuster development capabilities and established ECE R13 type-approval relationships. Monitor NHTSA rulemakings on connected braking systems as the critical inflection signal for mechanical-to-electronic substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gear Machining | Eliminates single-source dependency on German tool-and-die houses while capturing upstream margin pools. |
| Authorized Service Network Expansion | Locks in fleet maintenance contracts along major trucking corridors before regional distributor consolidation completes. |
| Electronic Adjuster Platform Development | Positions suppliers for brake-by-wire architectures in premium truck platforms from Scania and MAN. |
| Predictive Maintenance Data Services | Converts mechanical components into recurring software revenue through telematics integration. |
| ECE R13 Harmonization Compliance Investment | Streamlines multi-country market access as European braking standards align across member states. |
Methodological Framework
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance operations managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with brake-system specialists and validation against secondary sources including NHTSA regulatory filings, ECE R13 type-approval databases, vehicle production registries, and customs trade records. Bottom-up volume modeling from component-level bill-of-materials analysis triangulated against top-down market sizing from brake-system supplier revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks from commercial vehicle production databases and brake-system supplier financial disclosures. The analytical framework modeled demand across product type, end-user channel, technology architecture, and application category throughout the projection horizon. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate implementation schedules and fleet turnover dynamics. Forecast inputs incorporated NHTSA rulemaking timelines, ECE R13 amendment review status, and brake-by-wire platform launch cadence from German and US truck OEMs.
Underlying assumptions cover regulatory grandfathering provisions for existing mechanical adjuster fleets, with deviation risk concentrated in accelerated electronic substitution timelines and foundry input cost volatility. Forecasts reflect these documented assumptions with sensitivity analysis around fleet electrification adoption curves. Recalibration cycles align with material shifts in NHTSA connected braking system rulemakings and ECE R13 harmonization implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market