
 Automotive Brake System Market | 2026-2036
Automotive Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake System Market Intelligence
The capital-intensity divergence between integrated brake system architects and component specialists is redrawing competitive boundaries in automotive braking. Robert Bosch GmbH leverages its electromechanical portfolio to anchor premium EV platforms across German and Chinese vehicle assemblers. ZF Friedrichshafen AG sustains scale advantages in pneumatic and hydraulic modules for commercial vehicle OEMs. Continental AG differentiates through electronic brake control systems that integrate with advanced driver-assistance architectures.
An automotive brake system comprises friction-generating mechanisms, actuation subsystems, and electronic control units engineered to decelerate or immobilize vehicles through kinetic energy conversion into thermal energy, with disc brake assemblies typically specifying rotor diameters from 256 mm to 420 mm depending on vehicle mass and duty cycle. Its primary commercial purpose spans occupant safety compliance, vehicle dynamics control, and regulatory stopping-distance adherence across passenger and commercial transport applications. Disc brake configurations dominate value pools in passenger car and electric vehicle segments where thermal management demands escalate with regenerative braking integration. Electromechanical technology leads growth trajectories as vacuum-assist architectures face displacement by brake-by-wire systems. Aftermarket providers occupy mature, price-sensitive channels for drum brake and hydraulic component replacement cycles.
The U.S. NHTSA enforces FMVSS 135 minimum stopping-distance requirements that mandate iterative friction material and caliper design upgrades, while Europe's ECE R90 governs brake lining replacement part homologation and the EU Green Deal's embodied carbon directives pressure suppliers to reduce foundry emissions in rotor and drum production. China's MIIT and SAMR coordinate GB standards alignment with UN R90-H provisions for domestic market access. Stakeholders must monitor regulatory convergence between UN Economic Commission for Europe frameworks and China's evolving GB brake standards to anticipate homologation cost structures and localize testing capabilities.
Market Dynamics
Electromechanical brake-by-wire architectures are displacing vacuum-boosted hydraulic systems across electric vehicle platforms, compressing established supply relationships and forcing tier-1 suppliers to retool foundry and assembly footprints.
Growth Catalysts
- ECE R90 homologation alignment:Europe's brake lining certification framework is accelerating friction material upgrades across replacement part channels, pulling advanced ceramic and low-metallic formulations into mainstream adoption.
- China's EV production scaling:Domestic vehicle assemblers are deepening captive sourcing relationships with local brake system integrators, concentrating demand for electromechanical calipers and integrated parking brake modules.
- Regenerative braking integration:Kinetic energy recovery systems on battery electric platforms are extending friction brake duty cycles and demanding enhanced thermal management in disc rotor designs.
Market Restraints
- Foundry energy cost volatility:Gray iron and carbon steel input prices for rotor and drum casting remain exposed to electricity tariff fluctuations in European and Chinese manufacturing clusters.
- Homologation timeline friction:UN R90-H testing protocols and China's evolving GB standard alignment are extending certification cycles for replacement part suppliers seeking multi-market access.
- Hydraulic system legacy lock-in:Internal combustion vehicle installed base continues to generate aftermarket demand for conventional master cylinder and brake hose architectures, fragmenting R&D allocation.
Strategic Opportunities
- Software-defined brake control:Integration of brake-by-wire systems with ADAS architectures creates white space for electronic control unit suppliers to capture value from vehicle dynamics algorithms.
- India's commercial vehicle modernization:Stricter Bharat Stage VI enforcement and fleet renewal programs are accelerating pneumatic brake module adoption in heavy-duty truck and bus segments.
- EU Green Deal embodied carbon pressure:Foundry emission reduction mandates are creating first-mover advantage for suppliers deploying electric arc furnace rotor production and recycled content certification.
Industry Challenges
- Mechatronics skill scarcity:Brake system engineering teams face acute shortages in embedded software and functional safety competency for ISO 26262-compliant brake-by-wire development.
- Dual-architecture capex burden:Suppliers must simultaneously maintain hydraulic production lines for legacy vehicle programs and build electromechanical assembly capacity for EV platforms.
- Legacy vehicle integration complexity:Retrofit of electronic brake systems into existing model architectures encounters CAN bus protocol mismatches and calibration validation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake System Market |
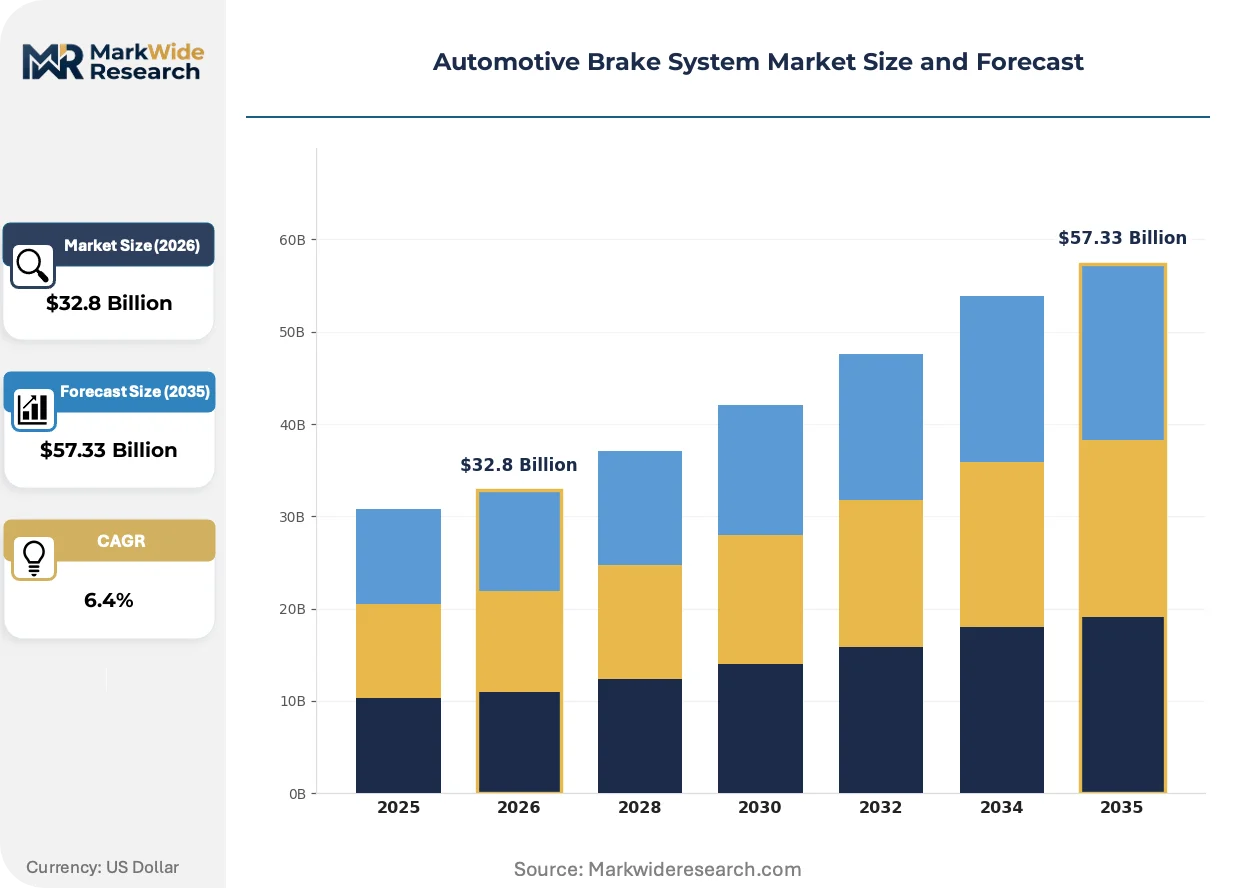
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Anti-lock Brake System, Hydraulic Brake Vehicle Type: Passenger Car, Commercial Vehicle, Two-wheeler, Electric Vehicle Technology: Electromechanical, Pneumatic, Vacuum-assist, Electronic End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Continental AG, Brembo S.p.A, Aisin Corporation, Akebono Brake Industry Co., Ltd., ADVICS Co., Ltd., Hitachi Astemo Ltd., Knorr-Bremse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake System Market Strategic Shifts & Innovations
Brake system architecture is converging with vehicle electrification and automation roadmaps, compressing hardware margins while expanding software and thermal management value pools across passenger and commercial applications.
Electromechanical brake-by-wire systems are displacing conventional vacuum-assisted hydraulic actuation in premium electric vehicle platforms. German and Chinese assemblers are accelerating adoption of integrated brake control modules that consolidate service brake, parking brake, and recuperative functions. This consolidation is displacing discrete component suppliers and forcing hydraulic specialists to acquire mechatronics capabilities or retreat to aftermarket channels.
Europe's ECE R90 brake lining homologation framework is tightening friction material performance thresholds for replacement parts. The regulation mandates dynamic friction coefficient stability and wear rate testing that legacy asbestos-organic formulations cannot satisfy. Aftermarket distributors in Germany, France, and Italy are responding by consolidating supplier relationships around certified low-metallic and ceramic compound manufacturers.
Fleet procurement of brake systems is compressing replacement cycles and unbundling after-sales service from initial equipment supply. Logistics operators in North America and Europe are negotiating direct sourcing agreements with friction material specialists, bypassing traditional tier-1 system integrators for wearable component replenishment. This disintermediation is most visible in long-haul trucking segments where telematics-enabled predictive maintenance triggers just-in-time brake pad replacement orders.
Automotive Brake System Market Segmentation
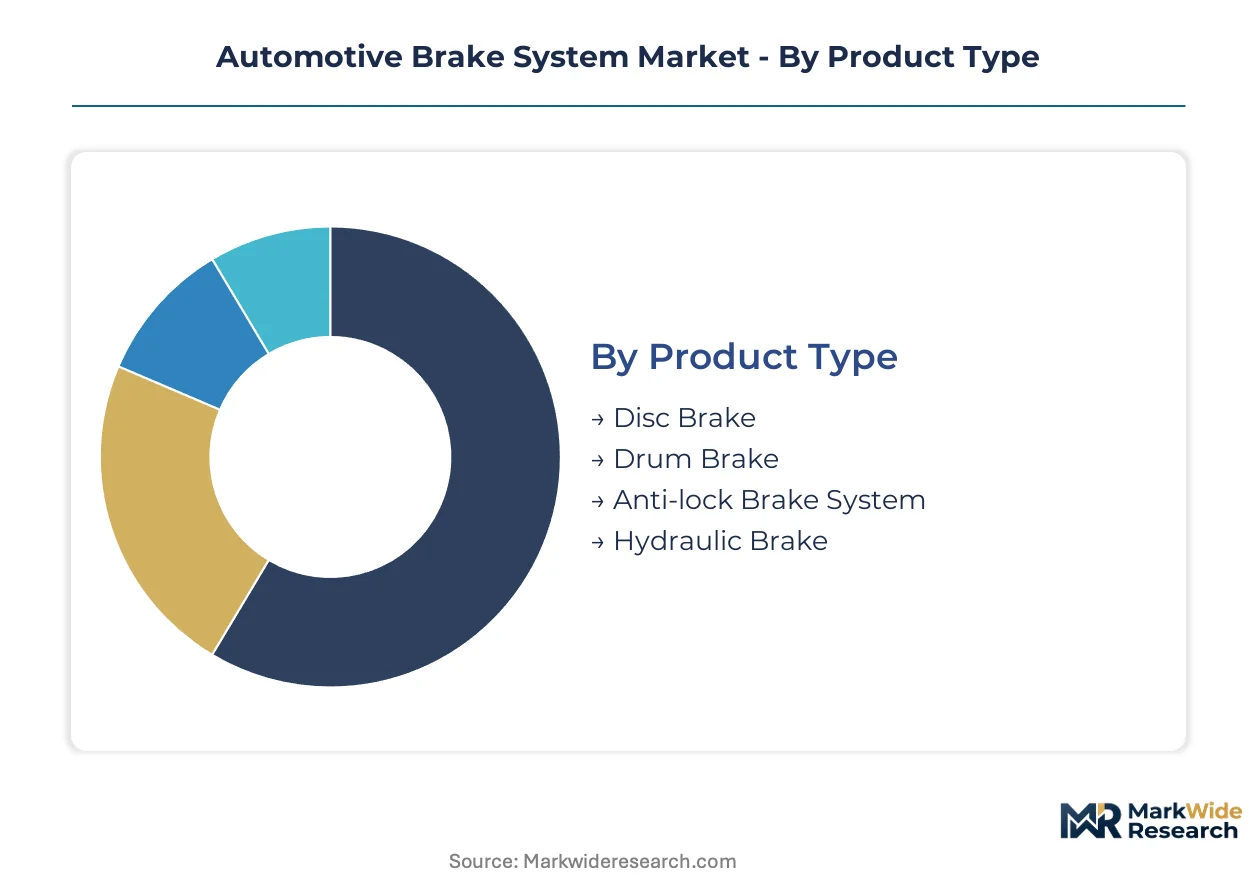
Brake system procurement patterns diverge sharply between captive OEM supply and fragmented aftermarket channels, with technology choices increasingly dictated by electrification roadmaps rather than legacy platform continuity.
Product Type:
Disc brake assemblies dominate export-led supply chains serving German and Chinese electric vehicle platforms, while drum brake production concentrates in domestic-market foundries across India and Brazil serving cost-optimized commercial vehicle segments.
- Disc Brake:Rotor diameters from 256 mm to 420 mm accommodate thermal loads from regenerative braking integration on battery electric platforms. Demand concentrates in Chinese EV production clusters where BYD and NIO specify ventilated rotor designs with enhanced cooling vane geometries for sustained high-speed deceleration cycles.
- Drum Brake:Self-energizing shoe mechanisms persist in rear axle applications for entry-level passenger cars and heavy-duty trucks where parking brake integration simplifies mechanical redundancy. Domestic production in India serves Bharat Stage VI commercial vehicle modernization programs with cast iron drum castings from local foundries.
- Anti-lock Brake System:ABS modulator valves and wheel speed sensor integration now standard across EU and US regulatory jurisdictions.
- Hydraulic Brake:Master cylinder and brake line architectures sustain aftermarket replacement demand from internal combustion vehicle installed base.
Hydraulic brake commands the established base. The steepest expansion runs through disc brake configurations.
Vehicle Type:
Cost tier segmentation separates premium electromechanical platforms from price-sensitive drum brake applications, with volume concentration shifting toward electric vehicle architectures that eliminate vacuum assist dependencies.
- Passenger Car:Multi-piston caliper configurations and ceramic composite rotors anchor premium segment braking performance. German OEMs specify integrated brake control modules combining service and parking functions, compressing component count per axle.
- Electric Vehicle:Brake-by-wire architectures eliminate vacuum boosters and enable recuperative blending algorithms. Chinese domestic assemblers source electromechanical calipers from local tier-1 suppliers deepening captive integration with cell-to-pack battery platforms.
- Commercial Vehicle:Pneumatic S-cam and air disc configurations dominate heavy-duty stopping requirements across North American long-haul fleets.
- Two-wheeler:Combined braking systems and single-piston hydraulic calipers address emerging market motorcycle safety mandates.
Commercial vehicle anchors the replacement parts economy. Electric vehicle is gaining share fastest as production scales accelerate.
Technology:
Application-specific technology choices reflect divergent duty cycles, with electronic control integration advancing most quickly in passenger vehicle segments while pneumatic systems sustain commercial vehicle torque requirements.
- Electromechanical:Motor-driven caliper actuation eliminates hydraulic fluid and enables software-defined brake force distribution. Robert Bosch GmbH and Continental AG anchor supply to German premium EV platforms requiring ISO 26262 functional safety certification for autonomous emergency braking integration.
- Electronic:ESC modules and brake control units consolidate sensor fusion for ADAS architectures. Demand clusters in European and Chinese regulatory environments mandating stability control and automatic emergency braking as standard fitment.
- Pneumatic:Compressed air systems sustain heavy truck and bus applications requiring sustained fade-resistant stopping power.
- Vacuum-assist:Booster-dependent hydraulic architectures face displacement as turbocharged engines and electric powertrains eliminate manifold vacuum sources.
Vacuum-assist retains the largest installed base. Electromechanical is climbing the fastest as brake-by-wire penetration deepens.
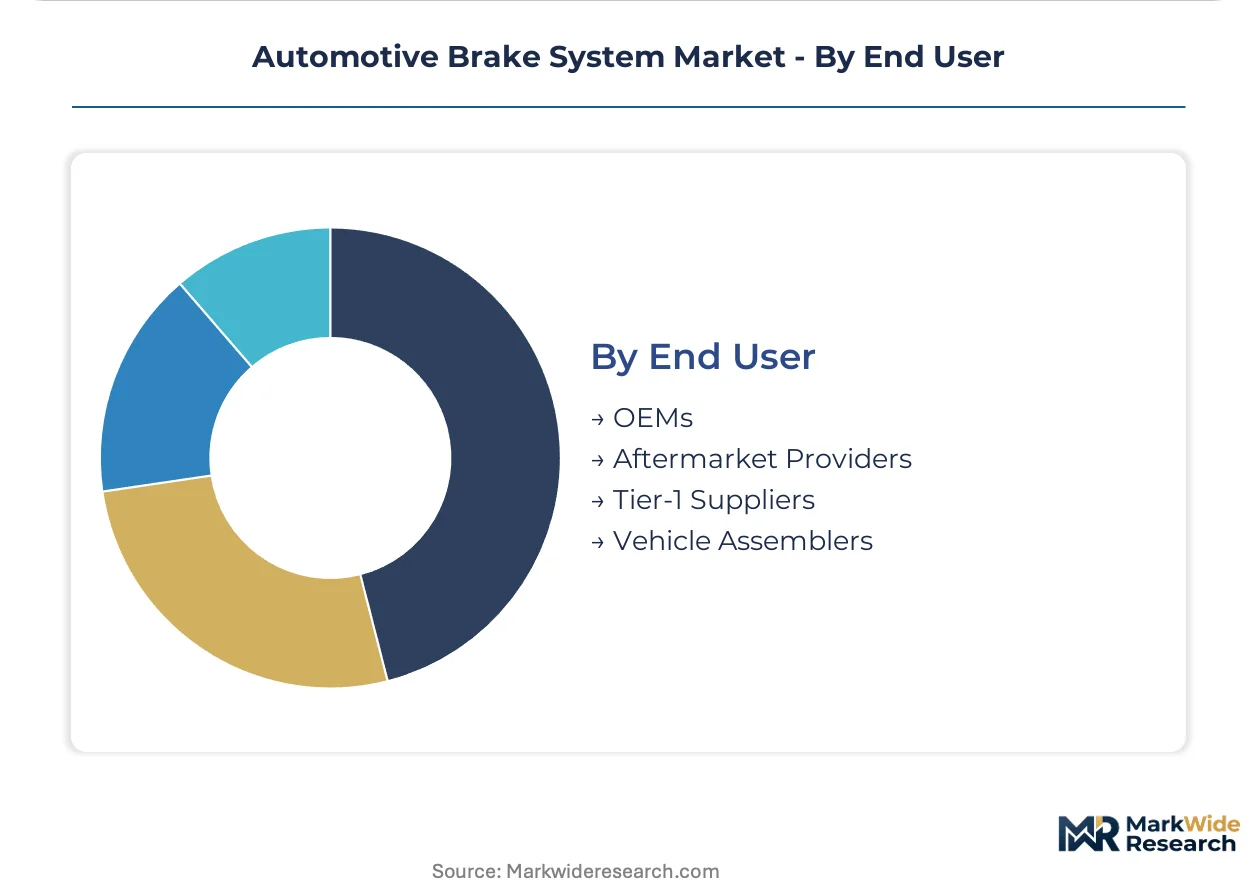
End User:
Customer type segmentation reveals procurement concentration patterns, with OEMs and tier-1 integrators capturing value from electromechanical platform development while aftermarket providers fragment across price-competitive replacement channels.
- OEMs:Vehicle manufacturers specify system-level brake architectures and validate homologation compliance against NHTSA FMVSS 135 and ECE R90 protocols. German and Chinese assemblers increasingly source integrated brake modules rather than discrete components, compressing supplier tiers.
- Tier-1 Suppliers:System integrators such as ZF Friedrichshafen AG and Continental AG consolidate caliper, rotor, and control unit supply under single-source contracts. These suppliers face dual-architecture capital demands maintaining hydraulic capacity for legacy programs while building electromechanical assembly lines.
- Aftermarket Providers:Independent distributors and service chains source ECE R90-certified friction materials for replacement part channels across European markets.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure brake systems through tier-1 intermediaries rather than direct component sourcing.
Aftermarket providers command the established base. Tier-1 suppliers are expanding most quickly through integrated module consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Chinese EV buyers prioritize electromechanical performance over cost, while Indian commercial fleet operators demand drum brake durability at minimal unit economics. European aftermarket channels absorb premium friction material pricing under regulatory compulsion.
China
Domestic EV production scaling drives concentrated demand for brake-by-wire architectures. MIIT and SAMR coordinate GB standards alignment with UN R90-H provisions for homologation compliance. Shanghai and Shenzhen manufacturing clusters host captive tier-1 supplier integration with BYD and NIO cell-to-pack platforms.
Germany
Premium OEM specifications for integrated brake control modules anchor electromechanical system development. ECE R90 homologation mandates dynamic friction coefficient testing that legacy formulations fail. Stuttgart and Munich engineering centers validate ISO 26262 functional safety for autonomous emergency braking integration.
United States
Long-haul fleet operators negotiate direct friction material sourcing agreements, bypassing traditional system integrators. NHTSA FMVSS 135 stopping-distance standards mandate iterative caliper design upgrades. Detroit and Michigan manufacturing corridors sustain hydraulic aftermarket production for legacy internal combustion installed base.
India
Bharat Stage VI enforcement accelerates pneumatic brake module adoption in heavy-duty truck renewal programs. The country's automotive regulator mandates enhanced stopping performance for commercial vehicle categories. Pune and Chennai foundry clusters produce cast iron drum castings for domestic cost-optimized segments.
Japan
Hybrid vehicle platforms sustain demand for electronic brake control systems with recuperative blending algorithms. METI coordinates JIS standards alignment with international homologation frameworks. Nagoya and Kanto manufacturing regions specialize in ABS modulator valve production for export-led supply chains.
Automotive Brake System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the brake system value chain. Integrated system architects consolidate caliper, rotor, and control unit supply under single-source contracts with premium OEMs. Component specialists fragment across aftermarket channels for friction materials and hydraulic replacement parts. Dual-architecture capital demands force tier-1 suppliers to maintain parallel hydraulic and electromechanical production lines. Strategic moves concentrate on captive sourcing relationships with Chinese EV assemblers and ECE R90 certification acquisition for European aftermarket access.
Within the integrated system tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify divergent strategic positioning. Bosch anchors German and Chinese premium EV platform supply through its electromechanical portfolio. ZF occupies scale advantages in pneumatic and hydraulic modules for commercial vehicle OEMs. Continental AG sits within the electronic control specialization, differentiating through brake system integration with advanced driver-assistance architectures. Brembo S.p.A represents Italian precision manufacturing archetype in high-performance friction applications. Aisin Corporation exemplifies Japanese vertical integration from component through system level.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Continental AG |
| Brembo S.p.A |
| Aisin Corporation |
| Akebono Brake Industry Co., Ltd. |
| ADVICS Co., Ltd. |
| Hitachi Astemo Ltd. |
| Knorr-Bremse AG |
| Others |
Cost & Logistics Intelligence
Electromechanical caliper adoption replacing vacuum-boosted hydraulic architectures redraws supplier geography toward China and Germany while compressing margins on legacy foundry operations in India and Brazil. This substitution simultaneously elevates software-defined brake control pricing premiums and depresses commodity rotor casting returns across cost-optimized segments.
Pricing Analysis
Aftermarket friction material replacement cycles anchor lifetime value capture across brake system economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by ECE R90 certification grade and thermal performance tier, with European distributors absorbing premium ceramic compound costs under regulatory compulsion while Indian fleet operators drive cost compression in drum brake shoe segments. Price erosion runs through hydraulic component tiers as electromechanical platforms capture OEM sourcing concentration. Commercial vehicle aftermarket channels exhibit highest price sensitivity; integrated brake control module procurement by German premium EV assemblers shows lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for gray iron and carbon steel rotor castings, contrasting with just-in-time electromechanical caliper assembly flows serving Chinese EV production clusters. Supply concentrates in China, Germany, and Mexico for tier-1 system integration, while India and Brazil retain foundry capacity for drum brake domestic markets. Gray iron feedstock, rare earth magnet motors, and semiconductor brake control chips constitute critical input dependencies. Single-source vulnerability in rare earth motor supply chains from China creates structural exposure. Distribution runs through captive OEM tier-1 contracts for electromechanical platforms and fragmented aftermarket distributor networks for friction materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology architecture fragmentation between hydraulic legacy and electromechanical future creates specialist niches for component suppliers with targeted certification capabilities and regional manufacturing proximity.
For Market Incumbents: Fortify integrated module supply relationships with Chinese EV assemblers through localized electromechanical assembly capacity in Shanghai and Shenzhen manufacturing corridors. Deepen ECE R90 certification coverage across low-metallic and ceramic friction formulations to defend European aftermarket position against emerging compound specialists. Prioritize ISO 26262 functional safety competency acquisition to meet German OEM autonomous emergency braking integration requirements. For New Entrants and Emerging Players: Anchor in India's Bharat Stage VI commercial vehicle modernization programs by establishing cast iron drum foundry partnerships in Pune and Chennai clusters. Target white space in software-defined brake control algorithms for ADAS integration, where embedded software capability scarcity limits incumbent response speed. Pursue direct fleet sourcing agreements with North American long-haul operators to bypass tier-1 system integrator capture in friction material replacement channels. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors dual-architecture capability holders with electromechanical development traction and established hydraulic aftermarket cash flows. Acquisition candidates with electric arc furnace rotor production and recycled content certification offer defensive positioning against EU Green Deal embodied carbon mandates. Watch for brake-by-wire penetration rates in Chinese EV production as inflection indicator for electromechanical supplier valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Platform Standardization | Consolidates service, parking, and recuperative functions into single-source contracts with BYD and NIO. |
| Cell-to-Pack Brake Integration Partnership | Deepens tier-1 supplier captive relationships within Chinese EV battery platform architectures. |
| ECE R90 Certification Acquisition | Unlocks European aftermarket access for low-metallic and ceramic friction material specialists. |
| Electric Arc Furnace Foundry Transition | Positions rotor suppliers ahead of EU Green Deal embodied carbon reduction mandates. |
| Software-Defined Vehicle Brake Control Investment | Captures ADAS algorithm value pools through ISO 26262-compliant electronic control unit development. |
Research Approach
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distribution managers, and foundry operations directors anchored the qualitative base for this study. Primary field engagement combined with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS compliance filings, and ECE R90 homologation records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested forecast robustness across alternative EV penetration scenarios and regulatory alignment timelines over the projection horizon. The analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from iterative reconciliation between historical shipment trajectories and forward-looking OEM platform roadmaps, with brake-by-wire adoption curves and regenerative braking duty cycle assumptions as industry-specific inputs.
Material uncertainties — foundry energy cost volatility, UN R90-H and GB standards convergence friction, rare earth supply concentration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding electromechanical platform penetration rates and regulatory timeline adherence. Revision becomes warranted when brake-by-wire adoption in Chinese EV production crosses threshold divergence from baseline scenario parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Brake Override System Market