
 On-Road Motorcycles Market | 2026-2036
On-Road Motorcycles Market Size, Share, and Industry Trends Forecast 2026-2036
On-Road Motorcycles Market Intelligence
Consolidation among fleet and rental operators is repositioning procurement volumes toward contract-based supply agreements. Honda Motor Co. Ltd. leverages its ASEAN manufacturing footprint to anchor regional cost structures. Yamaha Motor Co. Ltd. differentiates through parallel-twin and crossplane crankshaft architectures in its middleweight portfolio. BMW AG competes in the premium touring segment with shaft-drive systems and integrated rider-assistance electronics.
On-road motorcycles are two-wheeled motorized vehicles engineered for paved surfaces, typically featuring internal combustion or electric powertrains producing between 15 and 200-plus horsepower, with frame geometries optimized for stability at sustained highway speeds. Their primary commercial purpose is personal mobility, recreational riding, and professional dispatch services across urban and intercity corridors. The 401cc-750cc engine capacity bracket captures the strongest margin pools as manufacturers balance performance premiums against accessible price positioning. Naked bikes attract enthusiast upgrades with minimalist bodywork and upright ergonomics, while touring bikes sustain higher average selling prices through integrated luggage, fairing, and connectivity systems.
The EPA and NHTSA in the United States enforce tailpipe and safety standards that constrain powertrain architectures and lighting configurations, while India's BIS and CEA frameworks mandate fuel efficiency benchmarks and electrical system certifications for domestic assembly. Euro 5 requirements across European markets have accelerated liquid-cooled fuel injection adoption and narrowed carburetor availability. Stakeholders must monitor regulatory divergence between emission jurisdictions and assess where platform commonality preserves engineering economies against localized compliance investments.
Market Dynamics
Emission standard convergence across Indonesia, India, and Vietnam is compressing engine architectures toward liquid-cooled fuel injection systems, forcing manufacturers to retire carburetor platforms and consolidate supplier bases around common injection hardware.
Growth Catalysts
- Urban modal shift in Jakarta:Two-wheelers now dominate last-mile connectivity across Southeast Asian megacities, with dedicated motorcycle lanes expanding arterial throughput and reducing commute times relative to four-wheeled alternatives.
- Euro 5 compliance:European emission thresholds have accelerated adoption of closed-loop fuel injection and catalytic converter integration, creating upgrade cycles among fleet operators seeking registration continuity.
- Electric powertrain maturation:Lithium-ion cell cost curves and localized battery assembly in Thailand are enabling competitive total-cost-of-ownership positioning against 125cc-150cc internal combustion benchmarks.
Market Restraints
- Semiconductor input volatility:ECU and sensor chip sourcing remains concentrated among Taiwanese and South Korean foundries, exposing production schedules to automotive-sector allocation competition.
- Steel and aluminum price swings:Frame and swingarm material costs fluctuate with energy-intensive smelting economics, compressing margin buffers on entry-class models where pricing power is weakest.
- Subsidy dependency in electric transition:Battery motorcycle adoption in India hinges on FAME-II incentive continuity, with state-level registration fee waivers creating uneven demand geography.
Strategic Opportunities
- Subscription and lease channels:Gig-economy delivery platforms in São Paulo and Mexico City are piloting fleet-as-a-service models that bundle maintenance, insurance, and battery swap access into per-kilometer tariffs.
- Swappable battery standardization:Gogoro's network architecture in Taiwan demonstrates interoperability potential, with India's battery swapping policy framework inviting platform replication across Delhi and Bangalore.
- Touring segment premiumization:Long-distance recreational riding in Germany and Austria sustains demand for shaft-drive, heated-grip, and integrated navigation configurations that command three-to-four times entry-bike pricing.
Industry Challenges
- Powertrain engineering talent scarcity:Combustion-engine expertise pools are thinning as engineering schools pivot curricula toward electric motor control and thermal management, creating recruitment friction for hybrid platform development.
- Homologation timeline compression:Simultaneous BIS Phase II, Euro 5, and EPA Tier 3 certification requirements demand parallel testing streams, stretching validation facility capacity and delaying market entry by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Road Motorcycles Market |
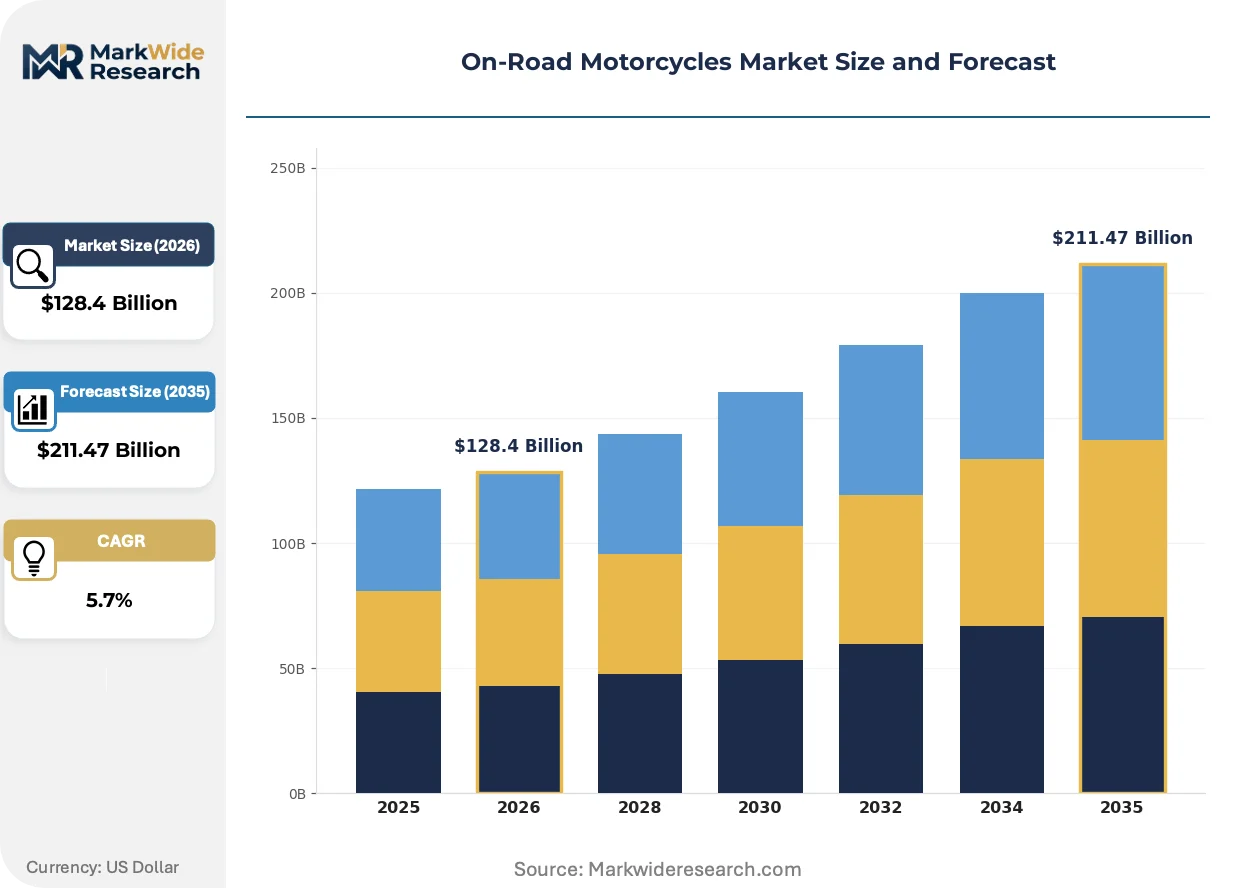
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $211.47 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Bikes, Cruiser Bikes, Touring Bikes, Naked Bikes Engine Capacity: 100cc-250cc, 251cc-400cc, 401cc-750cc, 751cc-1000cc Customer Type: First-Time Buyers, Enthusiasts, Commuters, Professionals Distribution Channel: Online Retail, Dealerships, Authorized Retailers, Rental Services |
| Companies Covered | Harley-Davidson, Honda Motor Co. Ltd., Yamaha Motor Co. Ltd., Kawasaki Heavy Industries Ltd., Suzuki Motor Corporation, BMW AG, Ducati Motor Holding SpA, Triumph Motorcycles Ltd., Bajaj Auto Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Road Motorcycles Market Strategic Shifts & Innovations
Powertrain electrification and connected-rider ecosystems are converging to redefine motorcycle architecture, with hardware platforms increasingly designed around over-the-air update capability and subscription-enabled feature activation.
Integrated vehicle control units are unifying engine management, traction control, and cornering ABS algorithms onto single-chip architectures. Premium manufacturers in Italy and Japan are adopting these consolidated ECUs to reduce wiring harness complexity and enable firmware-defined performance tiers. This consolidation is unifying previously separate supplier tiers around semiconductor-qualified tier-1 integrators.
REACH chemical substance restrictions are phasing out hexavalent chromium plating on exhaust systems and brake hardware, compelling coating suppliers to accelerate trivalent conversion and plasma electrolytic oxidation alternatives. Component manufacturers in Spain and Poland are absorbing reformulation costs while pushing compliance documentation burdens downstream to assembly plants.
Fleet procurement in Indonesian food-delivery and parcel-logistics verticals is consolidating around contract-based supply agreements with maintenance-included terms. Traditional dealer networks are losing volume to direct manufacturer-fleet operator negotiations, with Jakarta-based aggregators now specifying brake-wear monitoring and GPS immobilization as standard equipment requirements.
On-Road Motorcycles Market Segmentation
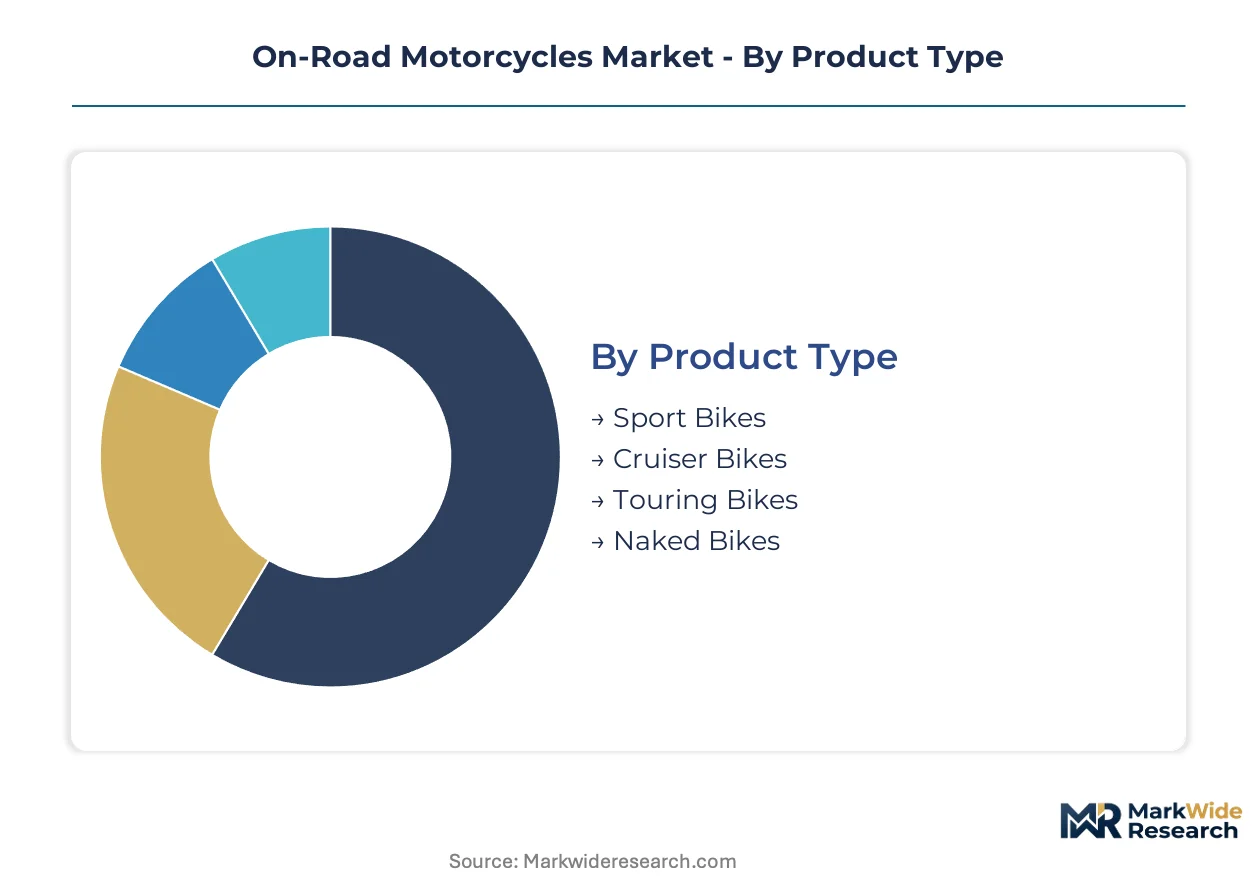
Segmentation in the on-road motorcycles market reflects divergent engineering priorities across use cases and purchasing contexts. Manufacturers configure frame geometries, powertrain mappings, and feature bundles to match distinct rider profiles and channel economics.
Product Type:
Standardization dominates entry segments while premium tiers embrace customization through modular accessories and firmware-defined performance tiers.
- Sport Bikes:Aerodynamic fairings and aggressive riding postures optimize for high-speed stability and cornering precision. Demand concentrates among enthusiasts in Germany and Italy where track-day culture and Alpine canyon riding sustain premium pricing.
- Touring Bikes:Shaft-drive transmissions, integrated luggage systems, and heated grips define this category's long-distance capability. Fleet operators across Austria and Switzerland favor these configurations for intercity courier services where rider comfort directly impacts productivity.
- Cruiser Bikes:Low-slung ergonomics and torque-rich V-twin engines target recreational riders seeking relaxed highway cruising.
- Naked Bikes:Minimalist bodywork and upright ergonomics attract urban commuters upgrading from smaller displacement machines.
Most installed capacity flows through Naked Bikes. Expansion is steepest in Touring Bikes.
Engine Capacity:
Volume manufacturing clusters around smaller displacements where production scale offsets thin per-unit margins, while mid-capacity brackets capture technology differentiation premiums.
- 401cc-750cc:Liquid-cooled parallel-twin and inline-four architectures balance performance accessibility with regulatory compliance flexibility. This bracket anchors manufacturer margins across Southeast Asian export hubs where Euro 5 and BIS Phase II homologation investments amortize across multiple model lines.
- 100cc-250cc:Air-cooled single-cylinder engines with carburetor-to-injection transitions dominate commuter corridors in Indonesia and Vietnam. Jakarta's food-delivery aggregators specify this displacement range for fleet standardization and fuel economy benchmarking.
- 251cc-400cc:Entry-level liquid-cooled platforms serve as stepping stones for first-time buyers upgrading from scooters.
- 751cc-1000cc:Premium multi-cylinder configurations target enthusiast segments with advanced electronics and premium suspension.
Production volume peaks in 100cc-250cc. Technology investment intensity concentrates in 401cc-750cc.
Customer Type:
Purchase behavior varies sharply between price-sensitive utility buyers and specification-driven enthusiasts, with channel strategy adapting accordingly.
- Commuters:Reliability and total-cost-of-ownership calculations dominate purchase decisions. Demand clusters in Indonesian and Vietnamese urban corridors where two-wheelers command modal share advantages over four-wheeled alternatives in dense traffic conditions.
- Enthusiasts:Performance specifications, brand heritage, and aftermarket modification potential drive selection criteria. German and Austrian riders in this segment sustain premium touring bike demand through club-organized long-distance events.
- First-Time Buyers:Financing accessibility and dealer proximity outweigh technical specifications in purchase decisions.
- Professionals:Gig-economy delivery riders prioritize durability and maintenance network density over initial acquisition cost.
Commuters account for the largest addressable base. Enthusiasts generate the highest per-unit contribution margins.
Distribution Channel:
Channel economics are fragmenting as direct fleet procurement and digital platforms displace traditional dealer dependency for volume segments.
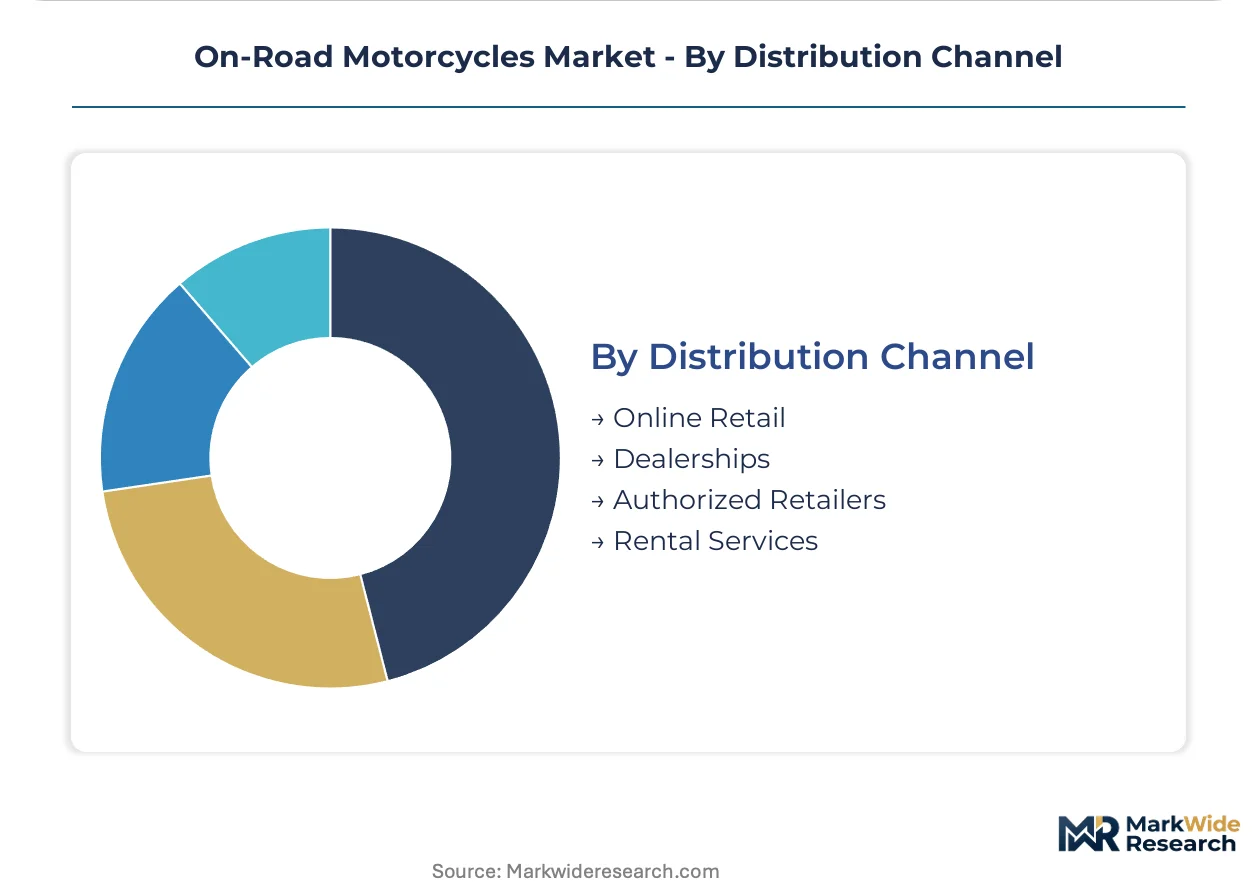
- Dealerships:Physical service infrastructure and financing facilitation sustain relevance for complex purchases and warranty-dependent buyers. India's tier-2 and tier-3 cities rely on dealer networks for BIS certification documentation and state-level registration assistance.
- Rental Services:Fleet-as-a-service models bundle maintenance, insurance, and battery swap access for gig-economy platforms. São Paulo and Mexico City delivery aggregators pilot per-kilometer tariff structures that eliminate capital burden for individual riders.
- Online Retail:Digital configurators and doorstep delivery expand reach in mature markets with established service networks.
- Authorized Retailers:Brand-controlled showrooms concentrate in premium segments where experience-driven purchase journeys justify higher operational investment.
Transaction volume flows predominantly through Dealerships. Channel innovation is advancing most quickly in Rental Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands the largest two-wheeler modal share among major economies, while Germany sustains the highest per-unit value concentration in premium touring configurations.
Indonesia
Jakarta's food-delivery aggregators and parcel-logistics operators are consolidating procurement around 100cc-150cc fleet specifications with integrated GPS tracking. The Ministry of Industry's B35 biodiesel mandate is pressuring carburetor retirement timelines. Manufacturing clusters in Bekasi and Karawang supply ASEAN export markets with fuel-injected commuter platforms.
India
Commuter demand concentrates in Maharashtra and Gujarat where two-wheelers navigate dense urban corridors. BIS Phase II emission norms and the FAME-II subsidy framework are accelerating electric powertrain trials among delivery fleets. Tamil Nadu's Sriperumbudur industrial belt hosts assembly operations serving domestic and African export markets.
Germany
Alpine touring culture and Autobahn cruising sustain premium displacement demand across Bavaria and Baden-Württemberg. KBA type-approval requirements enforce Euro 5 compliance with onboard diagnostics integration. Munich and Stuttgart anchor engineering centers developing shaft-drive architectures and rider-assistance electronics.
United States
Recreational highway riding and motorcycle club culture support cruiser and touring segments across Texas and California. EPA Tier 3 tailpipe standards and NHTSA lighting regulations constrain powertrain and equipment configurations. Wisconsin and Pennsylvania retain manufacturing heritage clusters despite production rationalization toward southern states.
Japan
Domestic demand concentrates in Kanto and Kansai metropolitan areas where parking scarcity favors compact displacement machines. METI carbon-neutrality roadmaps are channeling R&D investment toward hydrogen combustion and solid-state battery architectures. Hamamatsu and Iwata host integrated powertrain and chassis engineering facilities.
On-Road Motorcycles Market Key Industry Players
Japanese producers anchor one tier; European specialists hold premium positioning; Indian manufacturers capture volume-driven emerging market segments. The competitive structure exhibits moderate consolidation with tier-1 players controlling fuel-injection and electronics supplier relationships. Three archetypes dominate: full-line mass-market manufacturers, premium touring specialists, and regional cost-optimized assemblers. Capacity expansion and strategic technology licensing represent the primary competitive vectors.
Among Japanese full-line manufacturers, Honda Motor Co. Ltd. and Yamaha Motor Co. Ltd. exemplify the integrated ASEAN production model that serves Southeast Asian commuter demand. BMW AG occupies a position within the premium touring archetype where shaft-drive differentiation commands pricing multiples. These three entities represent distinct strategic postures across the market's value spectrum without implying specific operational claims.
| Leading Market Players |
|---|
| Harley-Davidson |
| Honda Motor Co. Ltd. |
| Yamaha Motor Co. Ltd. |
| Kawasaki Heavy Industries Ltd. |
| Suzuki Motor Corporation |
| BMW AG |
| Ducati Motor Holding SpA |
| Triumph Motorcycles Ltd. |
| Bajaj Auto Limited |
| Others |
Cost & Logistics Intelligence
Euro 5 emission compliance gates qualified supply access and premium-tier pricing power, as manufacturers must absorb liquid-cooled fuel injection and catalytic converter costs to maintain registration continuity across European markets. This environmental mandate compresses margin buffers on entry-class models while enabling technology premiums in mid-capacity brackets where compliance investments amortize across multiple model lines.
Pricing Analysis
Capacity additions in Thailand and Vietnam are reshaping price floors for 125cc-150cc commuter segments as localized battery assembly and fuel-injection component manufacturing expand. Three-tier pricing structure across premium touring, standard naked bikes, and economy commuters separates shaft-drive configurations with integrated electronics from carburetor-retirement platforms. Cost compression in entry segments intensifies because steel and aluminum price volatility erodes already-thin margins. Fleet operators in Jakarta exhibit highest price sensitivity, while German touring enthusiasts demonstrate lowest sensitivity to specification-driven premiums.
Supply Chain Analysis
Dual-sourcing requirements from Japanese OEMs now mandate qualified secondary suppliers for ECU and sensor chip procurement beyond Taiwanese and South Korean foundries. Manufacturing concentration centers on Indonesia, India, and Thailand for frame fabrication and final assembly, while precision electronics draw from Japan and Germany. Semiconductor allocation competition with automotive sectors creates single-source vulnerability during demand spikes. Distribution runs through direct fleet procurement channels that bypass traditional dealer networks for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in 401cc-750cc brackets where liquid-cooled platforms command technology premiums against fixed compliance cost bases. Electric powertrain maturation in Thailand offers additional cost-down runway as lithium-ion cell economics improve.
For Market Incumbents: Anchor ASEAN manufacturing footprints to preserve cost structures against emerging electric entrants from China. Consolidate fuel-injection supplier relationships around tier-1 integrators capable of consolidated ECU architectures. Defend against battery-swapping platform disruption by piloting interoperability standards in Jakarta and Delhi corridors. Prioritize homologation capacity investments to compress Euro 5, BIS Phase II, and EPA Tier 3 certification timelines. For New Entrants and Emerging Players: Begin with swappable battery fleet-as-a-service models in São Paulo and Mexico City where gig-economy aggregators seek per-kilometer tariff structures. Target India's state-level FAME-II subsidy corridors for electric two-wheeler penetration. Exploit homologation timeline compression gaps by focusing on single-jurisdiction certification before parallel multi-market entry. Partner with established maintenance networks to overcome service infrastructure deficits. For Investors and Strategic Acquirers: Roll-up economics work for regional fleet operators because contract-based procurement is displacing dealer-dependent volume in Indonesian food-delivery verticals. Platform consolidation across maintenance-included supply agreements offers recurring revenue visibility over five-to-ten year horizons. Acquisition targets should demonstrate GPS telematics integration and brake-wear monitoring capabilities specified by Jakarta-based aggregators. Watch for FAME-II incentive continuity decisions as inflection signals for Indian electric motorcycle demand geography.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Partnership | Gogoro's Taiwan network demonstrates interoperability potential for Delhi and Bangalore replication. |
| Fuel Injection Platform Standardization | Consolidated ECU architectures reduce wiring complexity and enable firmware-defined performance tiers. |
| Direct Fleet Procurement Channel | Bypasses traditional dealer networks for Jakarta food-delivery and parcel-logistics volume consolidation. |
| Shaft-Drive Technology Licensing | BMW's premium touring differentiation commands pricing multiples in German and Austrian markets. |
| Homologation Testing Facility Investment | Parallel certification streams for Euro 5, BIS Phase II, and EPA Tier 3 compress market entry delays. |
Research Approach
Bottom-up commuter and enthusiast demand modeling reconciled against top-down ASEAN manufacturing capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 fuel injection suppliers, fleet procurement managers at Jakarta-based aggregators, and dealer network operators across Indian tier-2 cities combined with secondary validation from EPA certification databases, KBA type-approval records, BIS emission compliance filings, and ASEAN automotive trade statistics. Triangulation between supply-side capacity announcements and demand-side registration data ensures consistency across volume and value estimates.
Input-output matrices map engine capacity brackets against customer archetypes and distribution channel economics throughout the forecast period. Segmentation dimensions include product type, displacement tier, propulsion architecture, and regional regulatory cluster. CAGRs derive from regression analysis of historical production volumes against emission standard implementation timelines and electric powertrain cost curves. Industry-specific forecast inputs incorporate lithium-ion cell price trajectories and biodiesel mandate compliance costs.
Caveats apply where semiconductor allocation priorities or steel and aluminum price volatility could materially shift the outlook. Forecasts reflect assumptions regarding FAME-II subsidy continuity, Euro 5 enforcement stringency, and fleet operator consolidation trajectories. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Cargo Bike Market