
 Saudi Arabia Passenger Vehicles Lubricants Market | 2026-2036
Saudi Arabia Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Passenger Vehicles Lubricants Market Analytics
Subscription-based oil change and fleet maintenance packages is hardening into a distinct revenue layer beyond standalone product sales. Petromin Corporation leverages its nationwide service center network to bundle lubricant supply with preventive maintenance contracts. ExxonMobil Corporation anchors premium positioning through synthetic formulations engineered for high-temperature Saudi operating conditions. Royal Dutch Shell PLC competes via integrated supply agreements with dealership chains and independent workshops.
Saudi Arabia passenger vehicles lubricants comprise refined base oils blended with performance additives to reduce friction, dissipate heat, and protect engine components under extreme thermal loads exceeding 50°C ambient temperatures. These formulations must maintain viscosity stability across severe start-stop urban cycles and sustained highway operation in desert climates. Engine oil occupies the dominant value share given higher consumption frequency and premium synthetic migration, while 5W-30 viscosity grade segments expand fastest as OEM fill specifications shift toward lighter grades for fuel efficiency. Detergent and anti-wear additive packages concentrate margin pools where specialized formulations command technical premiums.
SASO enforces lubricant quality certifications that mandate compliance with API SN Plus and ILSAC GF-6 standards, directly shaping product registration requirements and import clearance protocols. SFDA oversight of workshop chemical handling and waste oil disposal adds operational compliance dimensions for service providers. Stakeholders must monitor evolving OEM service interval extensions and electrification timelines that could recalibrate lubricant volume assumptions even as the installed ICE fleet continues expanding.
Market Dynamics
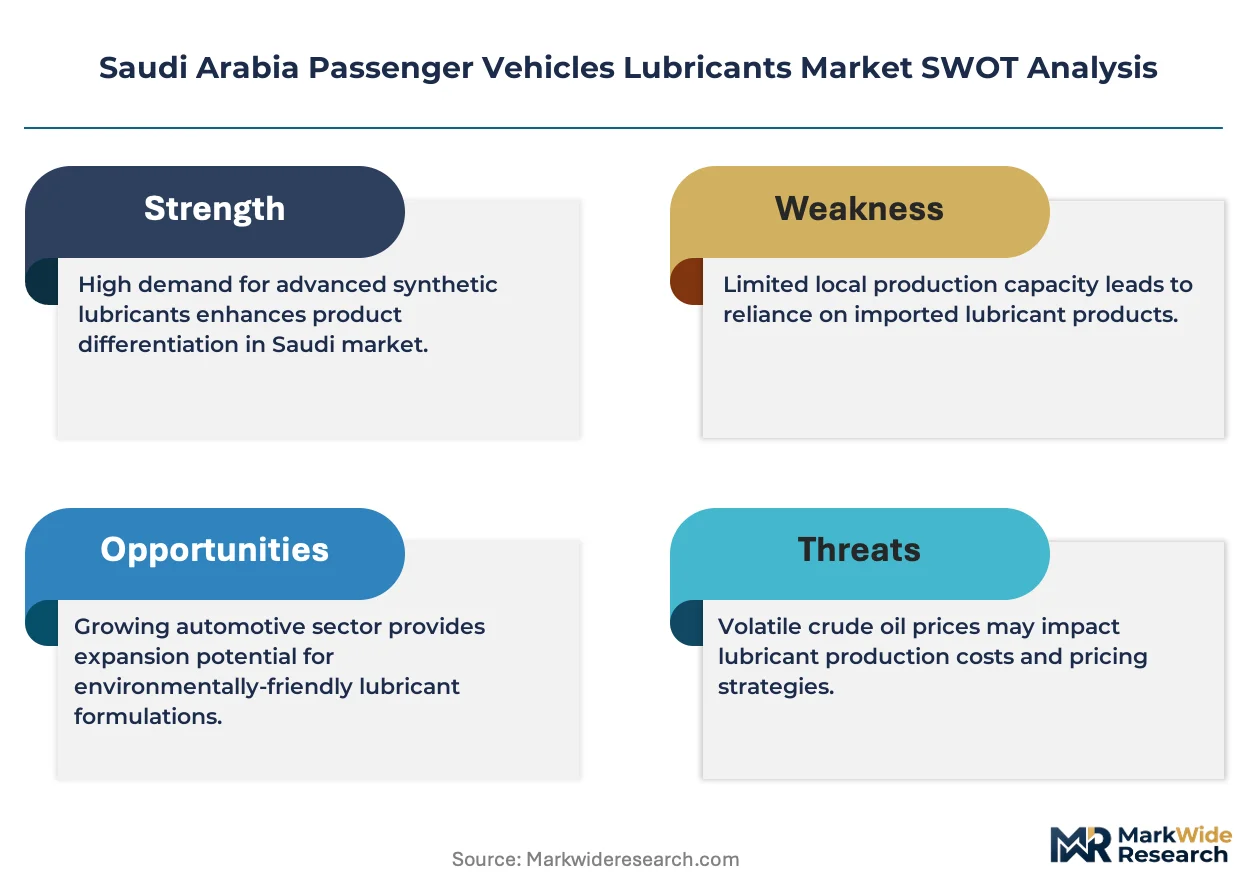
SASO's progressive tightening of lubricant performance benchmarks under Vision 2030 is compressing product registration timelines and forcing reformulation investments, while fleet operator consolidation accelerates volume concentration among fewer buyers with greater negotiating leverage.
Growth Catalysts
- Fleet Operator Consolidation:Ride-hailing platforms and commercial leasing companies are expanding vehicle counts, driving bulk lubricant procurement and preventive maintenance contract bundling across Riyadh and Jeddah.
- API SN Plus Mandate:SASO's adoption of this standard for low-speed pre-ignition protection is compelling lubricant upgrades and expanding synthetic penetration in newer turbocharged engines.
- Urban Heat Stress:Ambient temperatures exceeding 50°C in desert corridors are accelerating oil degradation cycles, shortening drain intervals and sustaining replacement demand.
Market Restraints
- Group II/III Base Oil Import Dependency:Domestic refining capacity for high-quality base stocks remains limited, exposing blenders to feedstock cost volatility and shipping disruptions from Asian suppliers.
- Electrification Timeline Uncertainty:OEM announcements of EV transition targets are compressing long-term ICE lubricant demand visibility, deterring capacity expansion commitments.
- Extended Drain Intervals:Synthetic formulations achieving 15,000+ kilometer service life are structurally reducing per-vehicle lubricant consumption volumes despite fleet expansion.
Strategic Opportunities
- Eastern Province Penetration:Dammam and Khobar exhibit lower workshop density than Riyadh despite rising vehicle registrations, presenting whitespace for service network expansion.
- Waste Oil Re-refining Integration:Circular economy incentives under Vision 2030 are creating regulatory tailwinds for closed-loop collection and re-refining infrastructure investments.
- Digital Fleet Management Convergence:Telematics-enabled oil condition monitoring is enabling predictive maintenance subscriptions, shifting revenue from transactional product sales to recurring service fees.
Industry Challenges
- Additive Package Sourcing Complexity:Specialized detergent and dispersant chemistries require qualified suppliers with SASO registration, lengthening new product development cycles.
- Workshop Technician Certification:SFDA chemical handling protocols and evolving OEM specifications demand continuous training investment, constraining independent service provider scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Passenger Vehicles Lubricants Market |
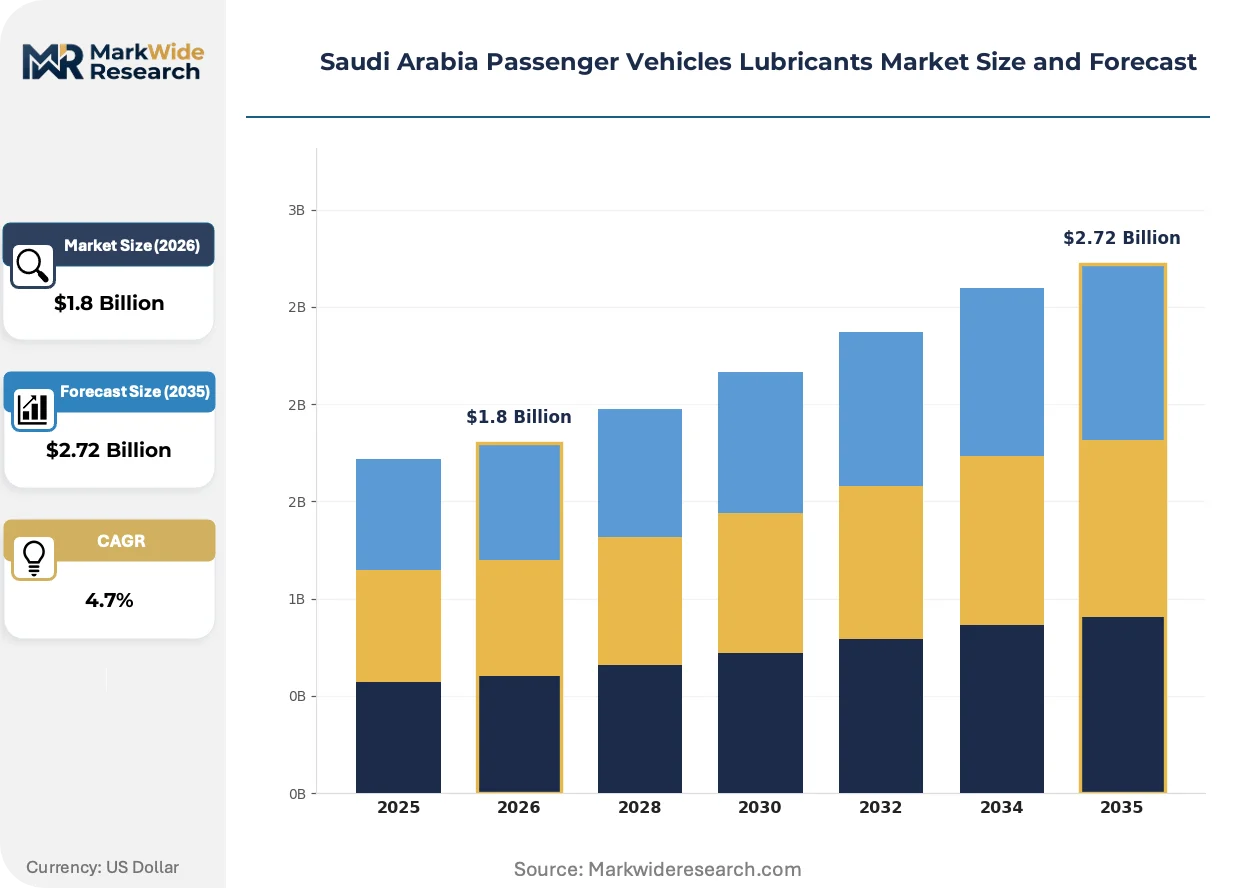
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Additive Type: Detergent, Anti-Wear, Lubricity Improver, Adhesion Agent Packaging Type: Drum, Bottle, Pail, Bulk |
| Companies Covered | Petromin Corporation, ExxonMobil Corporation, Royal Dutch Shell PLC, BP PLC (Castrol), FUCHS, TotalEnergies, Al-Jomaih and Shell Lubricating Oil Company, PETRONAS Lubricants International, United Lube Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and buyer procurement models are undergoing simultaneous recalibration as thermal performance demands intensify and service relationships digitize.
Low-viscosity 0W-16 and 0W-20 synthetic formulations are electrifying the premium segment as OEMs chase fuel economy credits. Japanese and Korean automakers with substantial Saudi market presence are factory-filling these grades, compressing demand for legacy 10W-40 conventional oils. The shift is electrifying margin pools toward additive-intensive specialized chemistries while commoditizing mineral-based volume products.
SASO's alignment with ILSAC GF-6 and API SP standards is forcing comprehensive product re-registration and testing protocol updates. Blenders must resubmit formulation data and performance documentation, extending time-to-market for new SKUs. Smaller import-dependent distributors face disproportionate compliance burdens, accelerating market share consolidation toward integrated domestic manufacturers.
Fleet procurement is fragmenting across subscription-based maintenance packages and traditional spot purchasing. Large ride-hailing operators are negotiating enterprise lubricant supply agreements with embedded oil analysis and scheduled replacement services. This bifurcation is most visible in Riyadh, where centralized fleet depots coexist with dispersed independent workshops serving individual vehicle owners.
Saudi Arabia Passenger Vehicles Lubricants Market Segmentation
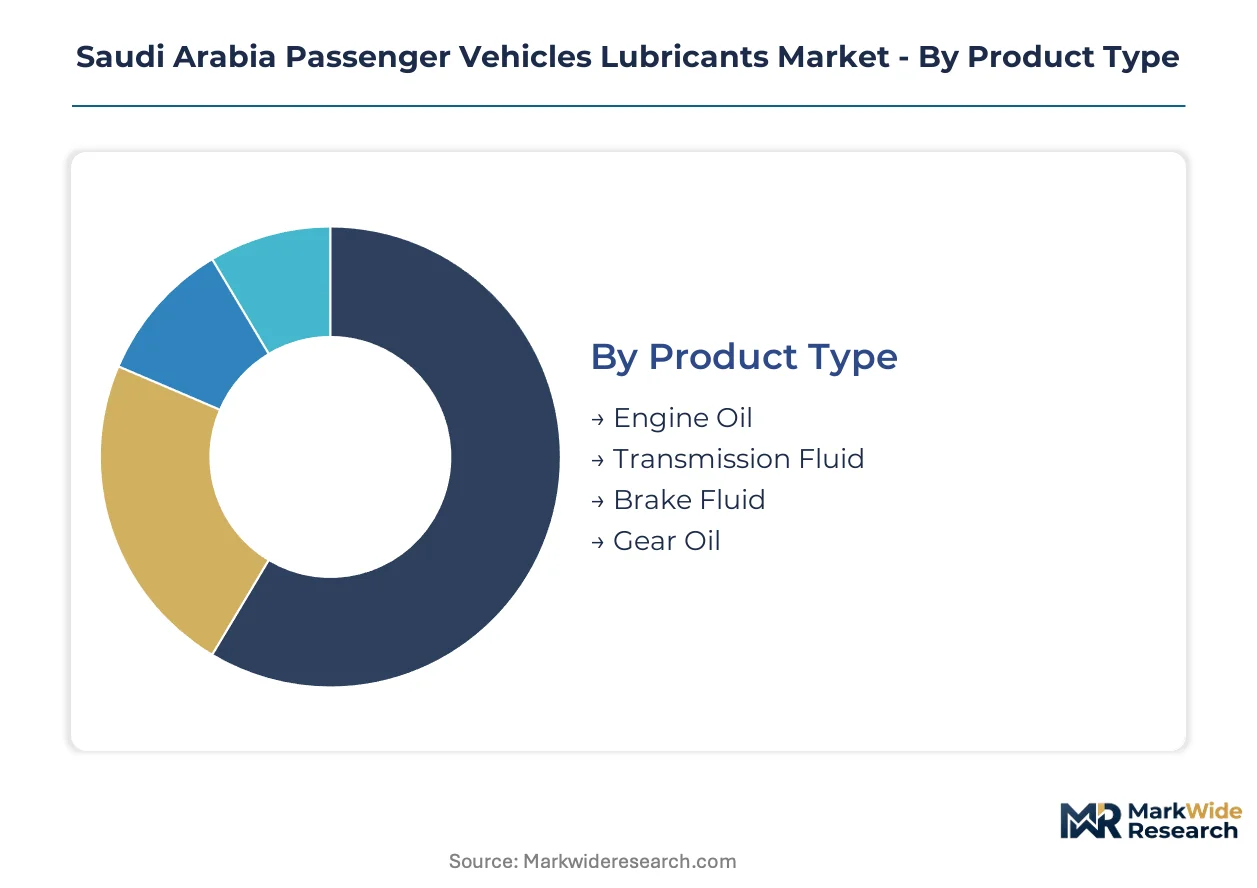
Segmentation in Saudi Arabia's passenger vehicle lubricants market reveals divergent margin structures across product categories. Fleet procurement patterns and OEM specification shifts create distinct volume-premium tradeoffs that reshape competitive positioning within each dimension.
Product Type:
Engine oil dominates volume flows while transmission fluid commands the steepest premium per liter across Riyadh and Jeddah service networks.
- Engine Oil:Refined base oil formulations blended with detergent-dispersant packages protect against oxidation at ambient temperatures exceeding 50°C. Demand concentrates in quick-lube chains and dealership service bays where synthetic 5W-30 upgrades drive margin expansion. SASO's API SN Plus mandate accelerates reformulation investments among domestic blenders.
- Transmission Fluid:Specialized friction-modified chemistries maintain shift quality in automatic gearboxes under sustained desert highway loads. Workshop density in Eastern Province lags Riyadh despite rising vehicle registrations, creating whitespace for technical service bundling. Extended drain intervals of 60,000+ kilometers compress replacement frequency but elevate per-service value capture.
- Brake Fluid:Hygroscopic glycol-ether formulations absorb moisture intrusion from humidity spikes in coastal Jeddah.
- Gear Oil:Extreme-pressure additive packages protect differentials during low-speed desert off-road operation.
Today's leader: Engine Oil. Tomorrow's challenger: Transmission Fluid.
Viscosity Grade:
Specification migration toward lighter grades restructures procurement economics across temperature-stressed operating environments.
- 0W-20:Full-synthetic low-viscosity formulations reduce cold-crank friction in Riyadh's stop-start urban cycles. Japanese OEM factory fill specifications displace legacy grades in newer turbocharged fleets. Premium positioning commands additive-intensive chemistry costs.
- 5W-30:The workhorse grade balancing fuel economy targets with thermal stability under 50°C ambient loads. Independent workshops in Jeddah report fastest inventory turnover as OEM service intervals extend. Synthetic penetration climbs fastest here among price-sensitive buyers.
- 10W-40:Conventional mineral base stocks serve aging fleet segments in secondary cities.
- 15W-50:Heavy-duty protection for high-mileage vehicles and commercial taxi fleets.
Volume concentrates in 5W-30. Value expansion accelerates in 0W-20.
Additive Type:
Functional chemistry specialization determines formulation cost structures and technical differentiation in SASO-registered products.
- Detergent:Metallic soap and ashless dispersant packages neutralize combustion acids and suspend soot particles in extended-drain synthetic formulations. Riyadh fleet operators prioritize high Total Base Number chemistries for severe service intervals. Margin pools concentrate where specialized suppliers hold SASO registration.
- Anti-Wear:Zinc dialkyldithiophosphate compounds protect cam lobes and bearing surfaces in high-load turbocharged engines. OEM warranty compliance demands precise phosphorus content limits. Technical premiums widen between API SP-certified and legacy formulations.
- Lubricity Improver:Ester and fatty acid derivatives reduce boundary friction in fuel-efficient low-viscosity grades.
- Adhesion Agent:Polymer tackifiers maintain protective films during intermittent operation in ride-hailing stop-start patterns.
Detergent packages anchor current profitability. Anti-wear specialization defines tomorrow's technical barriers.
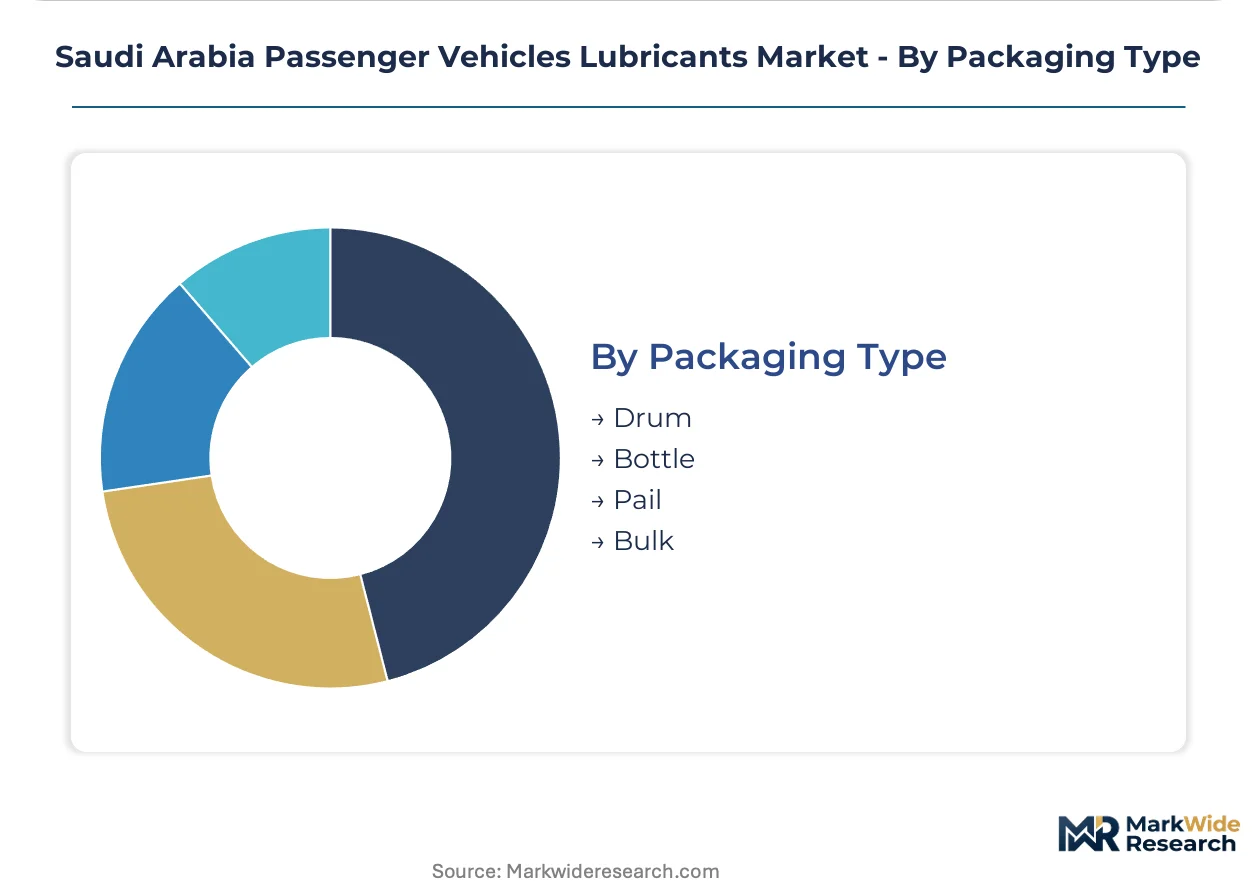
Packaging Type:
Container format selection reflects buyer scale and inventory velocity across fragmented workshop networks.
- Drum:200-liter steel containers serve high-throughput quick-lube chains and centralized fleet depots in Riyadh. Bulk handling infrastructure investments favor integrated distributors with captive logistics. Unit economics improve at volume thresholds above 5,000 liters monthly.
- Bottle:Retail 1-liter and 4-liter formats dominate independent workshop spot purchases and consumer DIY segments. Shelf space competition intensifies in Jeddah automotive retail corridors. Brand visibility investments concentrate here for premium synthetic positioning.
- Pail:20-liter plastic containers bridge mid-scale workshops without drum handling equipment.
- Bulk:Tanker-delivered unbranded base oil and additive packages feed captive blending operations.
Drum formats capture fleet consolidation benefits. Bottle packaging defends retail brand equity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blending capacity concentrates where regulatory compliance costs remain manageable relative to import tariffs, creating geographic arbitrage for lubricant formulation and packaging operations.
Riyadh
Fleet operator consolidation and ride-hailing platform expansion drive concentrated bulk procurement across centralized depots. SASO certification requirements for API SN Plus compliance filter distributor networks, favoring established blenders with in-house testing laboratories. Quick-lube chains and dealership service bays cluster along King Fahd Road and peripheral industrial zones.
Jeddah
Coastal humidity and Red Sea port access shape distinct demand for moisture-resistant brake fluid formulations and import-dependent base oil supply chains. SFDA chemical handling protocols govern workshop operations in the Balad district and northern suburbs. Retail bottle packaging dominates spot purchasing from independent workshops serving individual vehicle owners.
Eastern Province
Dammam and Khobar exhibit rising vehicle registrations against lower workshop density than Riyadh, creating service network whitespace. Petrochemical feedstock proximity from Jubail Industrial City offers potential backward integration for domestic base oil production. Fleet maintenance contracts for Aramco-affiliated vehicle pools concentrate procurement volumes.
Western Region
Makkah and Madinah pilgrimage traffic generates seasonal spikes in commercial taxi and bus fleet utilization. High thermal loads from desert highway corridors accelerate oil degradation in long-distance transport applications. Workshop infrastructure expansion lags vehicle growth, pressuring service capacity during peak pilgrimage periods.
Saudi Arabia Passenger Vehicles Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated domestic blenders capturing fleet consolidation benefits while multinational oil majors defend premium synthetic positioning through technical service bundling. The vendor base separates into three archetypes: national oil company affiliates with captive distribution networks, global lubricant marketers leveraging additive technology partnerships, and regional distributors dependent on import supply chains. Competitive moves concentrate on preventive maintenance contract bundling and waste oil collection infrastructure buildout.
Among the integrated domestic tier, Petromin Corporation anchors national coverage through its service center network, while Al-Jomaih and Shell Lubricating Oil Company occupies a joint-venture position blending multinational technology with local market access. ExxonMobil Corporation exemplifies the premium synthetic archetype through high-temperature formulation specialization. These three represent distinct strategic postures: captive infrastructure, partnership-based blending, and technical premium positioning.
| Leading Market Players |
|---|
| Petromin Corporation |
| ExxonMobil Corporation |
| Royal Dutch Shell PLC |
| BP PLC (Castrol) |
| FUCHS |
| TotalEnergies |
| Al-Jomaih and Shell Lubricating Oil Company |
| PETRONAS Lubricants International |
| United Lube Oil Company |
| Others |
Value Network & Pricing Analysis
API SN Plus certification divergence between premium synthetic and mineral-based lubricants manifests in divergent margin structures across Saudi Arabia's procurement channels, with SASO-registered formulations commanding technical premiums while commodity imports compete on landed cost. This bifurcation feeds directly into inventory positioning decisions, as distributors weigh working capital commitments against the pricing power conferred by domestic blending capabilities.
Pricing Analysis
Distributor margin layers absorb the steepest compression in Saudi Arabia's lubricant trade, with authorized dealers capturing markup differentials of 15-25 percentage points above import-parity pricing for API-certified synthetics. Three-tier pricing structure across premium, standard, and economy levels stratifies by base oil quality and additive package sophistication, with 0W-20 full-synthetics at the apex and Group I mineral oils at the base. Cost compression in the standard tier is intensifying because fleet operators consolidate procurement volumes and negotiate enterprise discounts. Individual vehicle owners in Jeddah's independent workshop corridor exhibit highest price sensitivity, while Aramco-affiliated fleet managers prioritize technical compliance over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian base oil suppliers exerts persistent margin pressure on Saudi blenders, with container rates from South Korea and Singapore fluctuating in response to Red Sea shipping disruptions. Geographic supply concentration centers on South Korea, Singapore, and the UAE for Group II/III base stocks, while additive packages draw from specialty chemical producers in the United States and Germany. Raw material dependencies rest on vacuum gas oil feedstocks, detergent-dispersant chemistries, and viscosity index improvers. Single-source vulnerability in high-performance additive sourcing lengthens new product development cycles. Distribution runs through Petromin's captive service center network, multinational oil major direct sales teams, and independent distributor channels serving secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's passenger vehicle lubricants market represents a late-cycle quality story as OEM fill specifications migrate toward low-viscosity synthetics and SASO tightens performance benchmarks, compressing demand for legacy mineral formulations.
For Market Incumbents: To counter synthetic formulation commoditization, Petromin and integrated domestic blenders should deepen backward integration into base oil production via Jubail Industrial City feedstock access, while ExxonMobil and Shell defend premium positioning through embedded oil analysis subscriptions that lock in fleet maintenance contracts. For New Entrants and Emerging Players: Mid-scale independent workshops in Dammam and Khobar present the most penetrable buyer archetype, as Eastern Province service network density lags Riyadh despite rising vehicle registrations. New entrants should target telematics-enabled predictive maintenance bundles as the go-to-market angle, converting transactional lubricant sales into recurring service fees. For Investors and Strategic Acquirers: Consolidation pressure builds where SASO registration burdens and reformulation costs disproportionately strain import-dependent distributors lacking in-house testing laboratories. Long-term viability favors integrated domestic manufacturers with captive logistics and waste oil collection infrastructure. The signal to watch is electrification timeline acceleration by Japanese and Korean OEMs, which would compress ICE lubricant demand visibility and trigger portfolio rebalancing toward industrial and marine applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Jubail Industrial City petrochemical proximity enables captive Group II/III supply security against Asian import volatility. |
| Waste Oil Re-refining Infrastructure Buildout | Vision 2030 circular economy incentives create regulatory tailwinds for closed-loop collection and re-refining investments. |
| Telematics-Enabled Predictive Maintenance Platform | Oil condition monitoring shifts revenue from transactional product sales to recurring subscription fees across fleet operators. |
| API SP/ILSAC GF-6 Product Re-registration | SASO alignment with international standards extends time-to-market but filters competition toward compliant integrated blenders. |
| Eastern Province Service Network Expansion | Dammam and Khobar workshop density gaps present whitespace for technical service bundling and fleet contract capture. |
Research Methodology
Coverage spans Riyadh, Jeddah, Eastern Province, and Western Region, with primary inputs from each major demand cluster. The research combines structured interviews with lubricant blenders, fleet procurement managers, independent workshop operators, and SASO regulatory officials with secondary validation from customs trade records, SASO certification databases, and OEM technical service bulletins. Bottom-up demand modeling triangulates against top-down market sizing from petrochemical feedstock flows and vehicle registration data.
Granularity-level framing applies separate volume and value projections across product type, viscosity grade, additive chemistry, and packaging format dimensions, with fleet versus retail channel splits modeled at the provincial level. CAGRs were derived from trend extrapolation of synthetic penetration rates, OEM service interval extensions, and fleet operator consolidation patterns across the projection horizon. Industry-specific inputs include ambient temperature stress coefficients for oil degradation modeling and electrification scenario weights from OEM public disclosures.
Inputs from lubricant blenders, fleet operators, and regulatory officials were available through the study window; gaps in real-time inventory positioning data from independent distributors introduce uncertainty bands around channel-share estimates. Forecasts reflect assumptions about SASO enforcement consistency, base oil import cost trajectories, and ICE fleet expansion rates. Stakeholders should weight assumptions against their own operating context and monitor OEM electrification announcements for demand trajectory revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Oil Filter Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Drum Brake Market