
 Europe Automotive Parts Zinc Die Casting Market | 2026-2036
Europe Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Parts Zinc Die Casting Market Foresight
Multi-source procurement from specialized zinc die casters is expanding across European automotive supply chains. Bruschi S.p.A. leverages its Italian manufacturing base to serve premium OEM programs with precision transmission cases. Dynacast sustains pan-European capacity through networked hot-chamber facilities. Kemlows Diecasting Products Ltd anchors UK-based production for domestic vehicle assemblers requiring just-in-time brake component delivery.
Europe automotive parts zinc die casting involves injecting Zamak alloys at temperatures near 420°C into hardened steel molds to produce net-shape components with wall thicknesses below one millimeter. This process delivers corrosion-resistant, high-strength parts for underhood and chassis applications where aluminum weight penalties are unacceptable. Engine components dominate volume demand while vacuum die casting technology captures expanding margin pools through porosity reduction. Electrical connectors represent the fastest-growing product category as vehicle electrification multiplies terminal counts per platform. Hot chamber technology leads European installed capacity due to zinc's low melting point and cycle efficiency.
REACH restrictions on heavy metal content and the EU F-Gas Regulation on process emissions are reshaping alloy formulations and melting practices across the region. ECHA substance evaluations now require die casters to document full material composition chains for automotive qualification. CE marking obligations under the EU Machinery Directive affect equipment upgrades at aging foundries. Stakeholders must monitor evolving end-of-vehicle-life recycling mandates that will alter scrap recovery economics and closed-loop sourcing requirements.
Market Dynamics
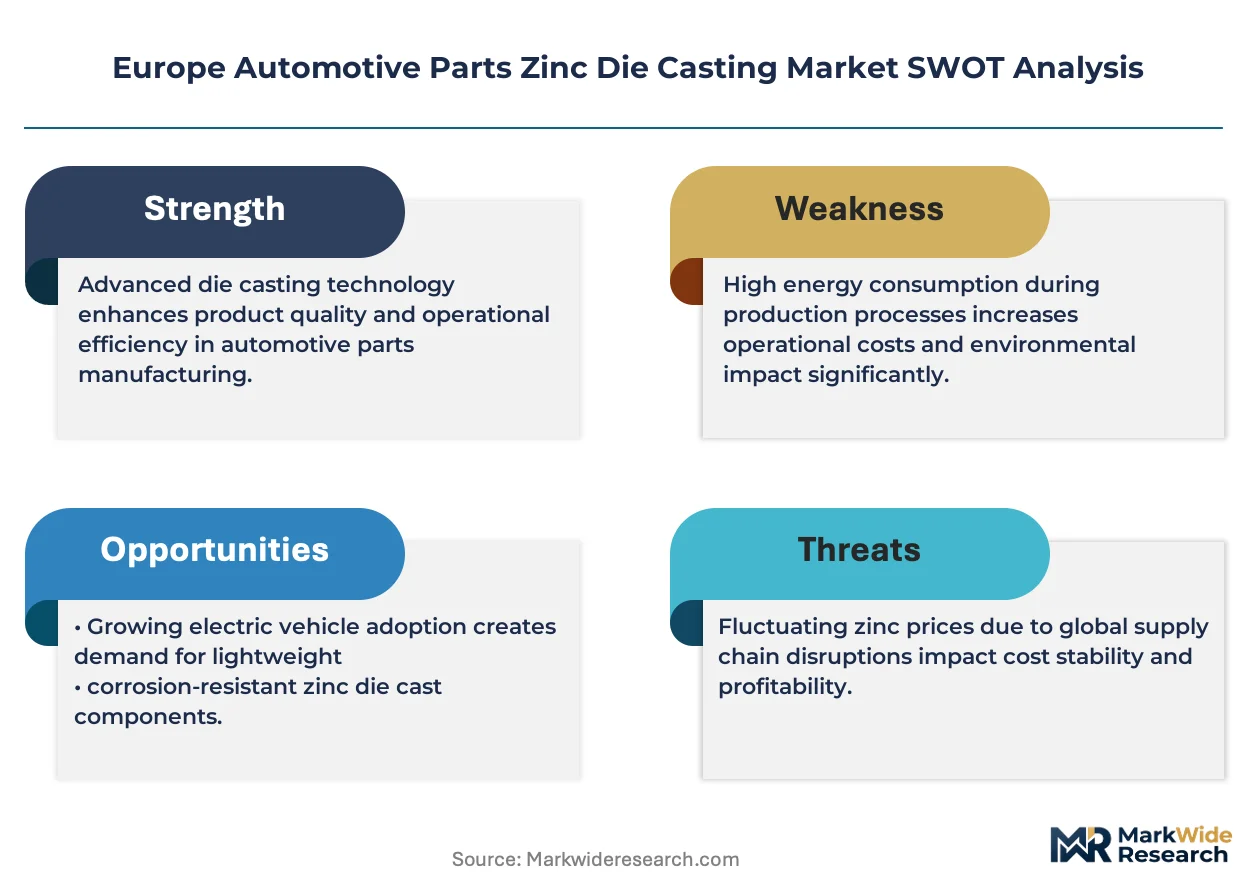
EU F-Gas Regulation enforcement and REACH substance restrictions are forcing zinc die casters across Germany, Czech Republic, and Poland to retool melting operations and alloy formulations simultaneously.
Growth Catalysts
- Vehicle electrification:Terminal block demand for battery management systems pulls precision zinc castings into high-voltage architectures. OEMs specify Zamak 5 for connector housings requiring EMI shielding.
- REACH compliance timelines:ECHA substance evaluations accelerate qualification of low-cadmium alloy variants. Die casters documenting full material chains gain preferred supplier status with German premium brands.
- Polish assembly cluster expansion:Stellantis and Volkswagen Group capacity additions near Gliwice create captive demand for just-in-time chassis hardware from regional zinc foundries.
Market Restraints
- Zamak alloy cost volatility:London Metal Exchange zinc pricing swings compress foundry margins on fixed-price OEM contracts. Smaller Czech operators lack hedging infrastructure.
- Aluminum substitution in underhood:High-pressure aluminum die casting captures brake caliper brackets above 800 grams where thermal mass requirements relax.
- EU F-Gas retrofit mandates:Aging Italian hot-chamber installations face six-figure equipment upgrades or production halts under 2027 emission thresholds.
Strategic Opportunities
- Romanian greenfield capacity:Underpenetrated relative to per-vehicle zinc content in Dacia and Ford Otosan supply chains. Brownfield industrial zones near Craiova offer utility cost advantages.
- Closed-loop scrap recovery:End-of-vehicle-life mandates under EU Battery Regulation create captive feedstock streams. Foundries integrating shredder residue sorting capture alloy cost premiums.
- Vacuum die casting-robotic finishing convergence:Porosity elimination meets automated deburring for Class A cosmetic surfaces. Tier 2 suppliers in Portugal deploy hybrid cells for mirror housing programs.
Industry Challenges
- Hot-chamber technician scarcity:Czech and Polish vocational pipelines produce insufficient mold maintenance specialists. German foundries poach experienced operators with 40% wage premiums.
- CE marking compliance timelines:EU Machinery Directive upgrades for aging Italian equipment require 18-month certification cycles. Production interruptions risk OEM supply agreement penalties.
- Legacy ERP integration:ECHA substance documentation demands clash with 1990s-era foundry management systems. Mid-tier Spanish operators delay digital traceability investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Parts Zinc Die Casting Market |
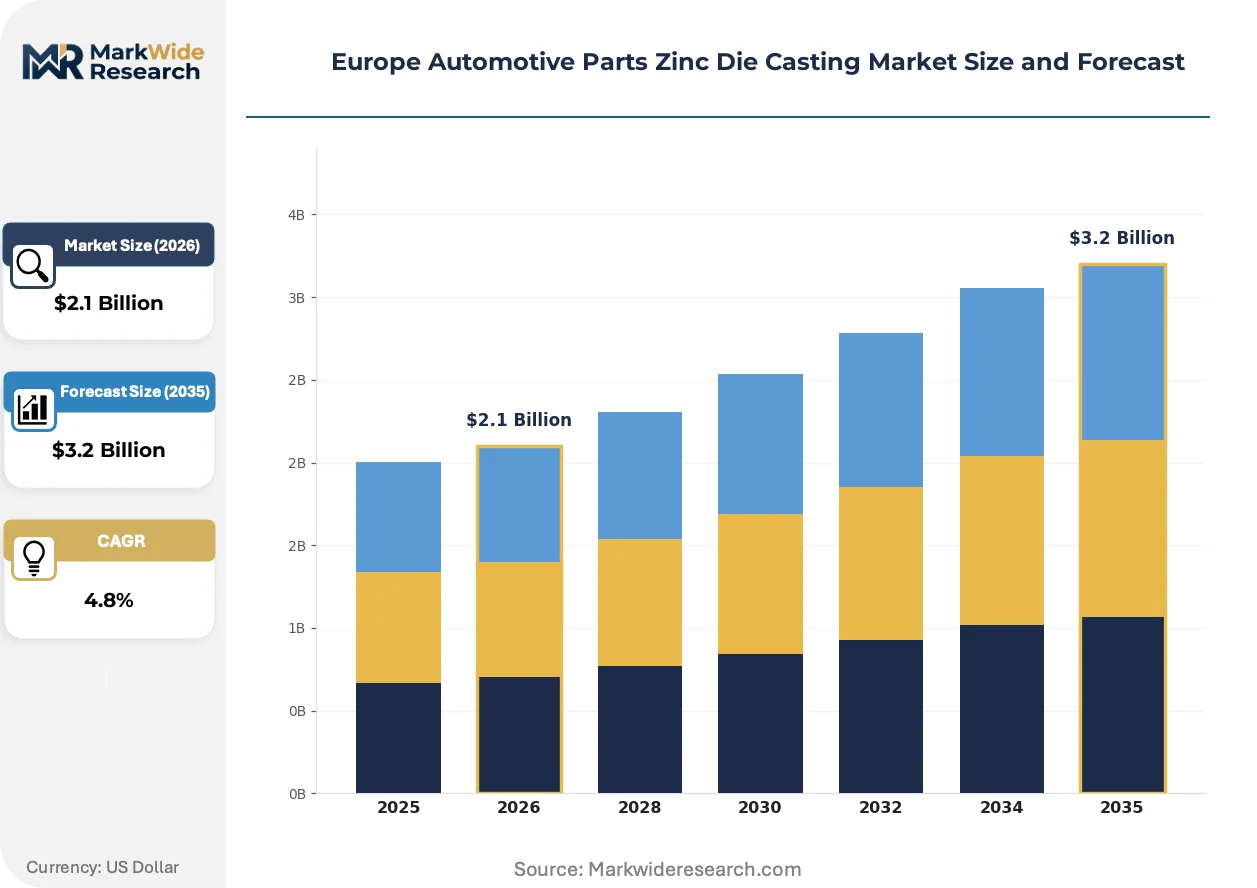
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Brake Parts, Electrical Connectors Application: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Prototype, Mass Production, Custom Components, High-Volume Production Technology: Hot Chamber, Cold Chamber, Vacuum Die Casting, Precision Die Casting |
| Companies Covered | Brillcast Manufacturing LLC, Ashok Minda Group, Sandhar Technologies Ltd, Cascade Die Casting Group Inc, Empire Casting Co, Dynacast, Kemlows Diecasting Products Ltd, Bruschi S.p.A., Pace Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process digitization and alloy innovation are compressing development cycles for European zinc die casters while regulatory documentation demands reshape competitive qualification barriers.
Thin-wall vacuum die casting is decentralizing production geography for precision transmission cases. German OEMs now source sub-0.8mm wall thickness housings from Polish and Czech foundries previously limited to commodity brackets. The technology is decentralizing supply base concentration that historically favored Italian precision specialists.
EU F-Gas Regulation phase-down schedules force immediate melting furnace retrofits across German and Czech production floors. Foundries converting to electric induction systems eliminate SF6 cover gas dependencies but absorb 24-month capital recovery timelines. Vacuum-assist casting operations face heightened scrutiny due to pump seal maintenance protocols.
Consolidated tier-one procurement desks now mandate real-time alloy composition certificates via blockchain-linked supplier portals. Continental and ZF Group purchasing organizations disintermediate traditional distributor relationships for direct foundry contracts. Spanish and Portuguese suppliers struggle with IT infrastructure gaps visible in German OEM supplier scorecards.
Europe Automotive Parts Zinc Die Casting Market Segmentation
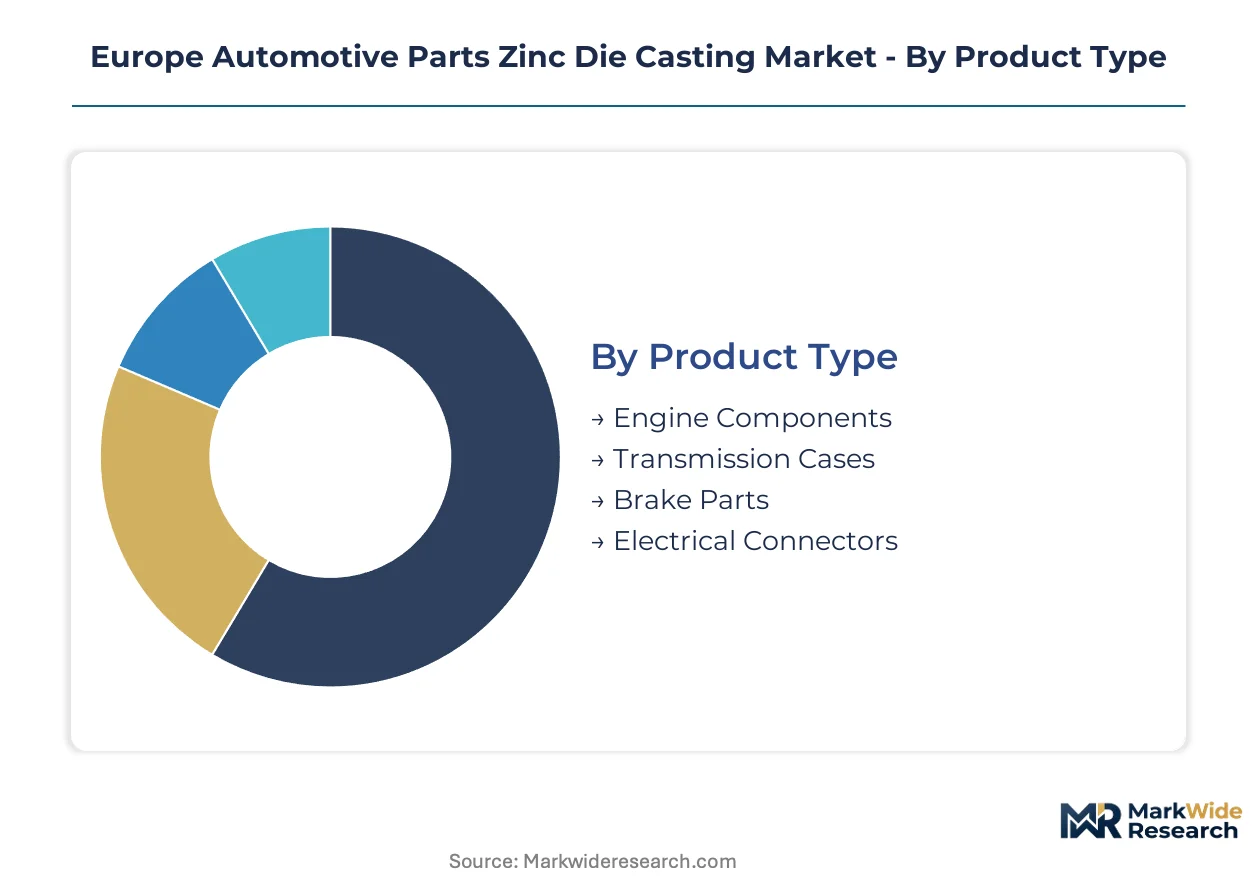
Segmentation in European automotive zinc die casting reveals distinct margin profiles and qualification barriers across product categories. Each dimension—product type, application, manufacturing stage, and technology—carries specific regulatory and commercial implications for foundry operators serving German, Czech, and Polish vehicle assembly clusters.
Product Type:
Engine components dominate tonnage demand while electrical connectors command premium pricing per kilogram as electrification multiplies terminal counts across European platforms.
- Engine Components:Valve covers, timing chain housings, and oil pump bodies utilize Zamak 3 alloys for corrosion resistance in underhood thermal cycling. German premium OEMs specify these for four-cylinder turbocharged architectures where aluminum weight penalties are unacceptable. Foundries in Czech Republic capture volume contracts through just-in-time delivery to Volkswagen Group assembly plants.
- Electrical Connectors:Battery management terminal blocks and high-voltage interlock housings demand Zamak 5 for EMI shielding properties. Polish foundries near Gliwice supply Stellantis electrification programs with precision-cast connector bodies. REACH low-cadmium alloy documentation is mandatory for German OEM qualification.
- Transmission Cases:Manual and dual-clutch transmission housings require sub-millimeter wall thickness control. Italian specialists historically dominated this precision segment.
- Brake Parts:Caliper brackets and master cylinder reservoirs face aluminum substitution above 800 grams where thermal mass requirements relax.
Today's leader: Engine Components. Tomorrow's challenger: Electrical Connectors.
Application:
Customer type determines contract structure, with OEM direct relationships demanding full ECHA material chain documentation that Tier-2 suppliers often cannot provide.
- OEMs:Volkswagen Group, Stellantis, and BMW Group specify zinc die castings for chassis hardware and underhood brackets. Direct foundry contracts require real-time alloy composition certificates via blockchain-linked portals. REACH compliance timelines accelerate preferred supplier status for documented low-cadmium variants.
- Tier-1 Suppliers:Continental and ZF Group procurement desks consolidate purchasing across brake and transmission programs. These intermediaries disintermediate traditional distributor relationships for direct foundry contracts, pressuring margin structures at mid-tier Czech and Polish operators.
- Aftermarket Providers:Replacement brake components and electrical terminals serve independent repair networks with less stringent material documentation requirements.
- Vehicle Assemblers:Dacia and Ford Otosan facilities in Romania source regionally for captive demand in lower-margin vehicle segments.
OEM direct contracts concentrate margin capture. Tier-1 consolidation is compressing intermediary margins fastest.
Manufacturing Stage:
Volume scale separates amortized tooling investments from prototype flexibility, with mass production commanding dedicated furnace allocations at major German foundries.
- Mass Production:Dedicated hot-chamber cells run 24-hour cycles for transmission case programs. German foundries achieve lowest per-unit costs through automated robotic finishing integration. Vacuum die casting technology captures expanding margin pools through porosity reduction in these high-volume environments.
- Prototype:Low-volume tooling and rapid alloy iteration serve German OEM pre-production validation. Czech operators leverage shorter qualification cycles for development-phase contracts.
- Custom Components:Specialized mirror housings and cosmetic trim pieces require Class A surface finishing. Portuguese Tier-2 suppliers deploy hybrid vacuum-robotic cells for premium OEM programs.
- High-Volume Production:Distinct from mass production through dedicated logistics integration with Polish and Czech assembly plants.
Mass production locks in furnace capacity. Prototype services command premium pricing but unpredictable utilization.
Technology:
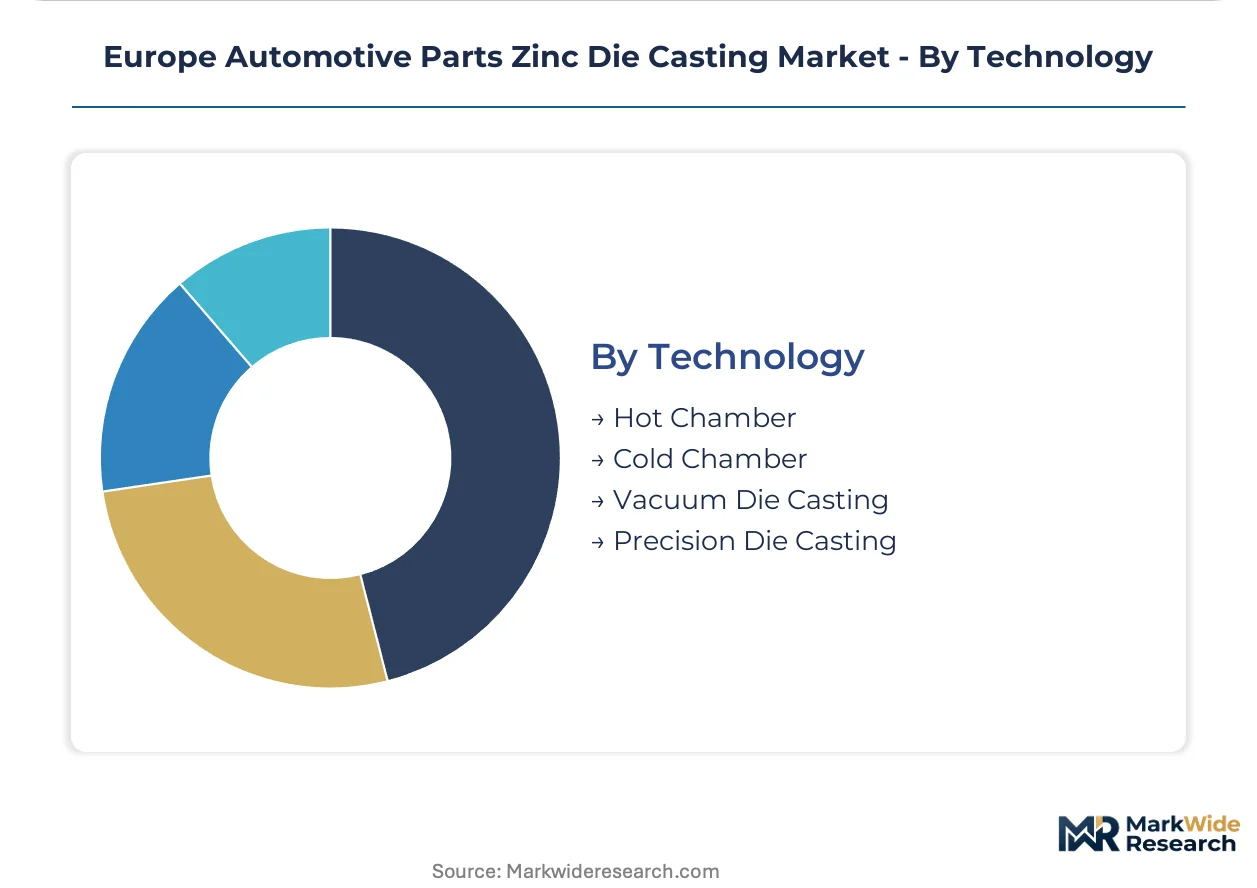
Process selection determines cycle efficiency and porosity control, with hot-chamber dominance reflecting zinc's low melting point advantages across European installed base.
- Hot Chamber:Molten zinc remains in constant contact with the injection system, enabling 5-second cycle times for small brackets and connectors. European capacity concentrates in this technology due to energy efficiency and throughput advantages. Aging Italian installations face EU F-Gas Regulation retrofit mandates by 2027.
- Vacuum Die Casting:Porosity elimination through mold cavity evacuation enables sub-0.8mm wall thickness for transmission cases. Polish and Czech foundries deploy this technology to challenge Italian precision specialists. Pump seal maintenance protocols face heightened scrutiny under emission regulations.
- Cold Chamber:Required for aluminum-zinc alloys with higher melting points. Limited European adoption for pure zinc applications.
- Precision Die Casting:Tolerance control for electrical connector housings with terminal position accuracy below 50 microns.
Hot chamber anchors European capacity. Vacuum technology is climbing fastest as wall thickness requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing zinc die casting capacity across Europe as cost-of-compliance gaps widen between established industrial zones and emerging production corridors. Foundries migrate toward jurisdictions offering streamlined REACH documentation pathways and lower emission retrofit burdens.
Germany
Volkswagen Group and BMW Group chassis hardware demand anchors the largest European zinc die casting consumption base. ECHA substance evaluation protocols force rapid low-cadmium alloy qualification cycles at Bavarian and Baden-Württemberg foundries. The Stuttgart industrial corridor concentrates vacuum die casting investments for sub-millimeter transmission case production.
Poland
Stellantis and Volkswagen Group assembly expansion near Gliwice generates captive demand for just-in-time brake component delivery. EU F-Gas Regulation phase-down schedules accelerate electric induction furnace conversions at Upper Silesian foundries. The Katowice-Gliwice manufacturing belt attracts German tier-one procurement desks seeking logistics-cost arbitrage.
Czech Republic
Skoda Auto and Hyundai Motor manufacturing clusters drive precision connector housing demand for battery management systems. REACH compliance documentation requirements strain legacy ERP systems at mid-tier Czech operators. The Ostrava industrial zone hosts hot-chamber capacity serving Volkswagen Group transmission programs.
Italy
Historical dominance in thin-wall transmission case precision casting faces erosion from Polish and Czech vacuum technology adoption. CE marking obligations under the EU Machinery Directive threaten production interruptions at aging Lombard and Piedmont hot-chamber installations. Bruschi S.p.A. leverages its Brescia manufacturing base for premium OEM direct contracts.
Romania
Dacia and Ford Otosan vehicle assembly creates underpenetrated zinc content opportunity relative to Western European per-vehicle averages. Brownfield industrial zones near Craiova offer utility cost advantages for greenfield foundry investment. The country's national environmental regulator applies transitional emission thresholds less stringent than core EU manufacturing zones.
Europe Automotive Parts Zinc Die Casting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vacuum-assisted precision niches and electrification component specialization. The vendor base concentrates around three strategic archetypes: Italian precision specialists commanding transmission case premiums, German tier-one integrated suppliers capturing OEM direct contracts, and Polish-Czech scale operators exploiting logistics proximity to assembly clusters. Competitive dynamics center on M&A consolidation among mid-tier foundries and capacity expansion into Romanian greenfield corridors.
Among Italy-based fabricators, Bruschi S.p.A. exemplifies the precision-specialist archetype, while Dynacast represents pan-European networked capacity. Kemlows Diecasting Products Ltd anchors UK-based production for domestic vehicle assemblers. These three entities illustrate the geographic segmentation that defines competitive positioning across the region.
| Leading Market Players |
|---|
| Brillcast Manufacturing LLC |
| Ashok Minda Group |
| Sandhar Technologies Ltd |
| Cascade Die Casting Group Inc |
| Empire Casting Co |
| Dynacast |
| Kemlows Diecasting Products Ltd |
| Bruschi S.p.A. |
| Pace Industries |
| Others |
Supply & Pricing Matrix
REACH certification tiers bifurcate European zinc die casting into premium documented suppliers and commodity undocumented operators, with German OEMs paying alloy-traceability premiums while Polish foundries compete on logistics proximity alone. This tier divergence concentrates margin capture at Bavarian vacuum-casting specialists and compresses returns at aging Italian hot-chamber installations facing CE marking retrofit deadlines.
Pricing Analysis
Distributor margins of 12-18 percent persist for undocumented Zamak alloys sold through Czech trading houses to Tier-2 brake component assemblers. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-certified OEM direct contracts from spot-market scrap-dependent production. Cost compression in economy-tier connector housings intensifies because Stellantis procurement desks consolidate purchasing volumes across Polish supply bases. Tier-1 suppliers exhibit highest price sensitivity due to fixed-price chassis hardware contracts, while premium German OEMs accept alloy-premium pricing for full ECHA material chain documentation.
Supply Chain Analysis
REACH qualification gating restricts automotive-grade Zamak supply to German, Polish, and Czech foundries with ECHA-submitted low-cadmium alloy certifications. Raw material flows draw from London Metal Exchange zinc warehouses, Italian secondary alloy refiners, and Romanian shredder residue recovery streams. Single-source vulnerability concentrates in Lombard hot-chamber maintenance expertise as vocational pipelines dry up. Distribution runs through Continental and ZF Group procurement desks consolidating direct foundry contracts, disintermediating traditional Czech distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle electrification terminal demand positions this market as a stable compounder, with battery management system connector volumes compounding irrespective of powertrain mix shifts.
For Market Incumbents: Hedge aluminum substitution risk in brake caliper brackets above 800 grams by deepening vacuum die casting capabilities for sub-0.8mm transmission case walls. Acquire Romanian brownfield capacity near Craiova to capture Dacia and Ford Otosan captive demand before greenfield entrants secure utility cost advantages. Prioritize CE marking compliance investments at aging Italian installations to avoid production halts under EU Machinery Directive enforcement.
For New Entrants and Emerging Players: Launch via direct OEM qualification pathways bypassing Tier-1 procurement consolidation, targeting Romanian vehicle assembly clusters with underpenetrated per-vehicle zinc content relative to Western European averages. Capture Polish electrification connector demand near Gliwice with vacuum-assist casting cells serving Stellantis battery management programs. Exploit IT infrastructure gaps at mid-tier Spanish operators by offering blockchain-linked alloy composition certificates as a service.
For Investors and Strategic Acquirers: Asymmetric upside sits with Polish-Czech scale operators possessing vacuum technology adoption curves and proximity to German OEM assembly clusters. Five-to-ten year viability hinges on closed-loop scrap recovery integration under EU Battery Regulation end-of-vehicle-life mandates. Watch for inflection upon ECHA substance evaluation acceleration forcing low-cadmium alloy documentation as a non-negotiable qualification barrier.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Polish foundries near Gliwice capture Stellantis electrification program volumes through just-in-time logistics integration. |
| Backward Integration | Closed-loop scrap recovery from shredder residue sorting captures alloy cost premiums under EU Battery Regulation mandates. |
| Green Manufacturing Transition | Electric induction furnace conversions eliminate SF6 cover gas dependencies ahead of EU F-Gas Regulation phase-down deadlines. |
| Long-term Supply Agreement | Direct foundry contracts with Continental and ZF Group procurement desks disintermediate traditional Czech distributor relationships. |
| Joint Venture | Romanian greenfield partnerships near Craiova exploit utility cost advantages and transitional emission thresholds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement managers, OEM platform engineers, zinc alloy technical directors, and aftermarket distribution heads with secondary validation from vehicle production databases, IHS Markit registration data, ECHA substance evaluation filings, and SEC disclosures from listed automotive suppliers. Bottom-up volume builds across product categories and top-down demand validation from assembly plant sourcing data were triangulated to converge estimates.
Historical reference periods anchored the projection horizon to observed production volumes, alloy pricing cycles, and regulatory implementation timelines. Segmentation dimensions modeled include product type, application tier, manufacturing stage, and technology platform, with vehicle class and regional production cluster as automotive-specific cross-cuts. CAGRs were derived from fitted growth curves applied to normalized baseline consumption, incorporating electrification content-per-vehicle trajectories and REACH compliance adoption rates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden London Metal Exchange zinc price dislocations, accelerated aluminum substitution in thermal management components, and unilateral OEM platform cancellations. Forecasts reflect assumptions about EU F-Gas Regulation enforcement timelines and ECHA evaluation completion schedules. A model refresh is warranted upon material change in low-cadmium alloy qualification velocity or Polish assembly cluster expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
North America Automotive AHSS Market