
 Middle East Automotive Lubricants Market | 2026-2036
Middle East Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Automotive Lubricants Market Foresight
Market Context with Strategic Players
Product bundling of engine oil with filter-change packages is pivoting fleet procurement toward integrated service contracts rather than standalone lubricant purchases. Petromin Corporation leverages its captive retail network across Saudi Arabia to dominate service-station distribution. Shell anchors its position through backward integration into base-oil supply and technical partnerships with original equipment manufacturers. TotalEnergies differentiates via high-performance synthetic formulations engineered for extreme ambient temperatures.
Technical Definition and Structural Segments
Middle East automotive lubricants comprise formulated fluids with viscosity grades typically spanning SAE 0W-20 to 20W-50, incorporating detergent-dispersant, anti-wear, and antioxidant additive packages to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines. These products serve the primary commercial purpose of extending powertrain life under severe operating conditions characterized by high thermal loads, dust ingress, and extended idling cycles common to regional traffic patterns. Engine oil occupies the largest value share given universal application across all vehicle classes, while synthetic formulations represent the fastest-expanding segment as original equipment manufacturer specifications tighten and fleet operators seek longer drain intervals. Heavy-duty trucks concentrate margin pools due to higher per-unit lubricant volumes and stringent OEM warranty requirements that lock buyers into approved product tiers.
Regulatory Frame and Forward-Looking Close
Saudi Arabia's SFDA enforces product quality standards for petroleum derivatives, while the UAE's Emirates Authority for Standardization and Metrology mandates labeling and performance certification for lubricants sold domestically. Gulf Standards Organization harmonization efforts across GCC member states are reducing regulatory fragmentation but elevating compliance costs for smaller blenders. ADNOC and Behran Oil Company navigate this landscape through in-house testing laboratories that accelerate certification timelines. Stakeholders must monitor evolving OEM specifications from European and Asian manufacturers as these cascade into regional import requirements and reshape formulation R&D priorities.
Market Dynamics
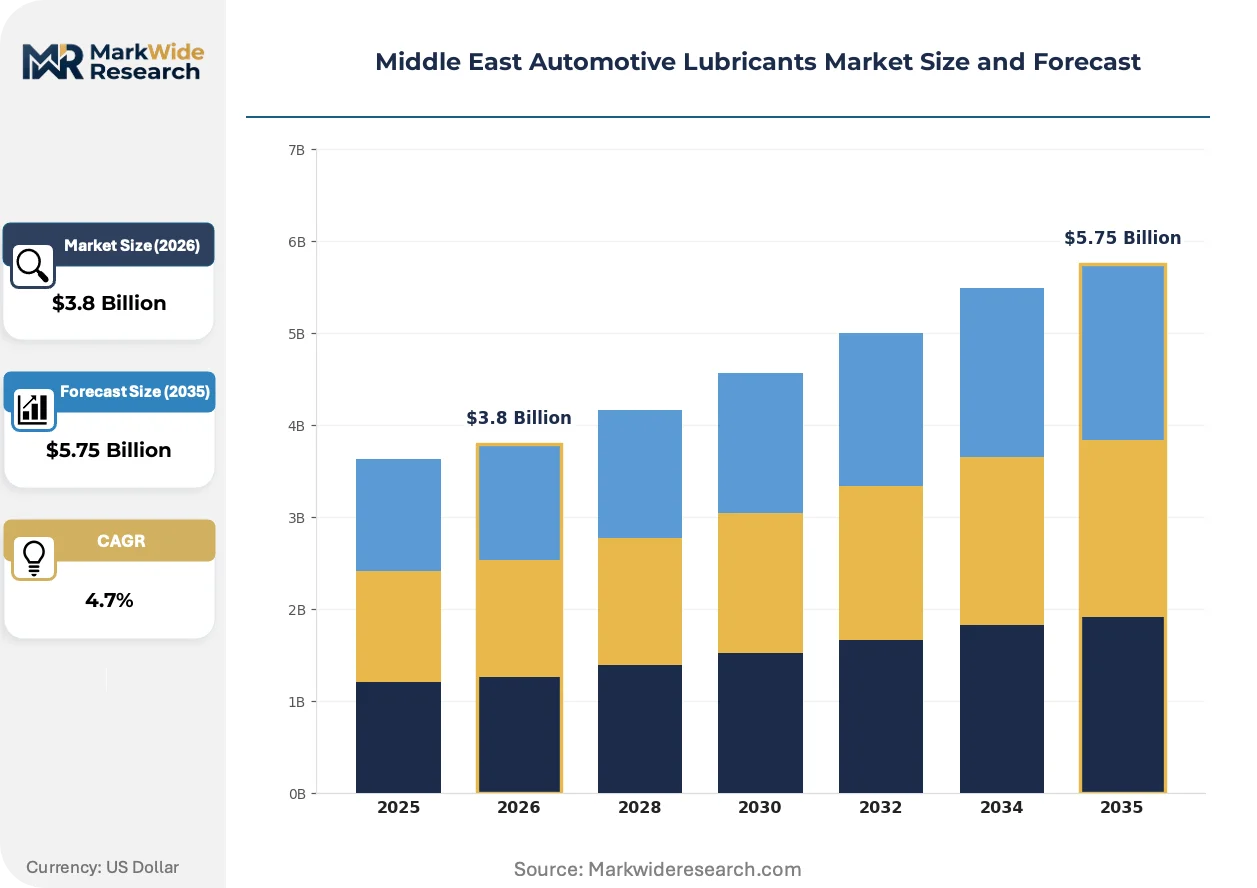
Fleet operators across the Gulf Cooperation Council are compressing total cost of ownership through synthetic lubricant adoption, forcing blenders to reformulate around extended-drain specifications rather than commodity price competition.
Growth Catalysts
- SFDA quality enforcement:Saudi Arabia's petroleum derivatives standards mandate performance certification that elevates technical barriers and rewards R&D-capable suppliers.
- Logistics fleet expansion:Commercial vehicle operators in desert operating conditions require premium formulations that withstand thermal degradation and dust ingress.
- Group II/III base oil upgrading:Regional refiners are expanding hydrocracker capacity to produce higher-viscosity-index feedstocks for synthetic lubricant manufacturing.
Market Restraints
- API Group I base oil dependency:Smaller blenders remain tethered to lower-quality feedstock economics that cannot meet tightening OEM specifications.
- SFDA certification timelines:Product registration protocols extend commercialization cycles and freeze working capital in inventory.
- Electric vehicle lubricant displacement:Battery electric powertrains eliminate engine oil demand entirely from the fastest-growing vehicle segment.
Strategic Opportunities
- UAE service-station bundling:Integrated oil-change and filter-replacement packages capture fleet procurement through convenience consolidation.
- Group III+ base oil localization:ADNOC and Behran Oil Company are building captive hydrocracker capacity to reduce import dependence.
- Transmission and axle fluid diversification:E-axle thermal management requirements in hybrid vehicles create adjacent formulation demand beyond engine oils.
Industry Challenges
- Formulation chemist scarcity:GCC universities produce limited lubricant-specific technical talent, forcing blenders to recruit from European and Asian competitor markets.
- OEM approval fragmentation:Divergent specifications from European, Japanese, and Korean manufacturers multiply SKU complexity and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Automotive Lubricants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Formulation: Synthetic, Mineral, Semi-Synthetic, Biodegradable Distribution Channel: Retail, Online, Wholesalers, Service Stations |
| Companies Covered | Petromin Corporation, Behran Oil Company, TotalEnergies, Shell, BP (Castrol), ExxonMobil, FUCHS, ADNOC, Aljomaih and Shell Lubricating Oil Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Automotive Lubricants Market Shifts & Advancements
Synthetic base oil technology is compressing traditional formulation economics while regulatory pressure from Saudi Arabia and the UAE elevates performance verification standards. Three developments are restructuring competitive positioning.
Polyalphaolefin and ester-based synthetic formulations are integrating into fleet maintenance protocols as operators calculate lifecycle cost advantages from extended drain intervals. Heavy-duty truck operators in Saudi Arabia's logistics corridor are adopting SAE 5W-40 and 10W-40 synthetics at the fastest regional pace. This shift is compressing market share for mineral-based products that cannot meet OEM warranty requirements.
Saudi Arabia's SFDA and the UAE's Emirates Authority for Standardization and Metrology are tightening labeling and performance certification mandates for petroleum derivatives sold domestically. Gulf Standards Organization harmonization efforts are reducing cross-border regulatory friction but elevating compliance costs for importers. Smaller blenders without in-house testing laboratories face extended approval timelines that disadvantage them against integrated suppliers.
Fleet procurement departments are consolidating lubricant purchasing into integrated service contracts that bundle oil, filters, and labor. Standalone lubricant distributors lose volume to service-station networks and OEM-affiliated maintenance chains. This pattern concentrates most visibly in Saudi Arabia's commercial vehicle sector, where Petromin Corporation's captive retail network captures fleet accounts through convenience and warranty compliance.
Middle East Automotive Lubricants Market Segmentation
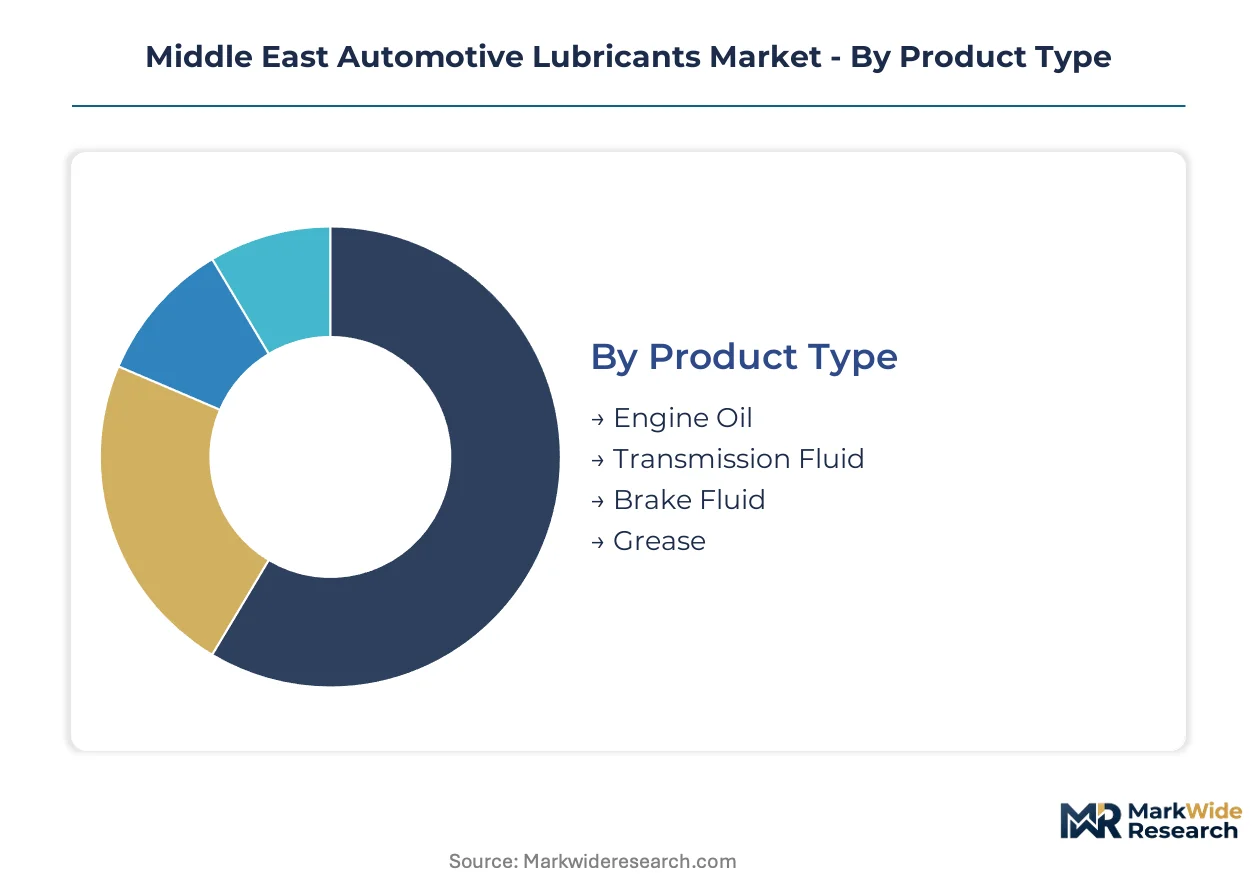
Segmentation in Middle East automotive lubricants reveals how formulation chemistry, vehicle duty cycles, and procurement channels create distinct margin pools. Fleet operators and retail consumers prioritize different performance attributes, forcing suppliers to maintain parallel product architectures.
Product Type:
Replacement cycles vary dramatically across lubricant categories, with powertrain fluids demanding more frequent service than sealed systems.
- Engine Oil:Formulated with detergent-dispersant and anti-wear additive packages across SAE 0W-20 to 20W-50 viscosity grades. Demand concentrates in Saudi Arabia's commercial vehicle sector, where desert operating conditions and extended idling accelerate thermal degradation and drive premium synthetic uptake.
- Transmission Fluid:Specialized formulations for automatic, manual, and continuously variable transmissions with friction modifier additives. Heavy-duty truck operators in the GCC logistics corridor are adopting synthetic ATF for extended service intervals, though volumes trail engine oil by an order of magnitude.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, and DOT 5.1 specifications. Replacement follows corrosion-based triggers rather than mileage.
- Grease:Thickened lubricants for chassis, wheel bearings, and universal joints. Mining and construction equipment in the UAE and Oman drives lithium-complex and calcium-sulfonate demand.
Volume placements concentrate in Engine Oil; the faster expansion belongs to Transmission Fluid as automatic transmissions proliferate in GCC passenger vehicles.
Application:
Operating severity and utilization rates create tiered pricing power across vehicle classes.
- Passenger Vehicles:Light-duty formulations emphasizing fuel economy and emissions compatibility. Synthetic 0W-20 and 5W-30 grades dominate OEM fill and dealer service in Saudi Arabia and the UAE.
- Commercial Vehicles:Fleet operators calculate total cost of ownership through extended drain intervals, forcing blenders to certify products against multiple OEM specifications simultaneously.
- Two-Wheelers:JASO MA/MA2 certified motorcycle oils for wet clutch compatibility. Saudi Arabia's recreational motorcycle segment and UAE delivery fleets sustain modest volumes.
- Heavy-Duty Trucks:API CK-4 and FA-4 formulations for Euro V and VI engines operating across the GCC logistics corridor. Per-unit lubricant volumes and warranty compliance requirements lock buyers into approved supplier tiers.
Revenue concentration sits with Heavy-Duty Trucks; Two-Wheelers claim the steepest expansion trajectory as last-mile delivery fleets multiply.
Formulation:
Base oil group economics determine which suppliers can meet tightening OEM specifications.
- Synthetic:Polyalphaolefin and Group III+ hydrocracked base oils with engineered additive packages. Fleet procurement in Saudi Arabia and the UAE is shifting service contracts toward synthetic-only specifications.
- Mineral:API Group I and II base oils constrained by viscosity index limitations and shorter drain intervals. Price-sensitive independent workshops in smaller GCC markets sustain residual demand.
- Semi-Synthetic:Blended formulations balancing cost and performance for mid-market vehicle owners. Service stations promote these as upgrade paths from mineral products.
- Biodegradable:Ester-based formulations for environmentally sensitive applications. Offshore and marine operators in UAE coastal zones drive niche adoption.
Margin pools align with Synthetic; Semi-Synthetic gains share fastest as mid-fleet operators trade up from mineral basestocks.
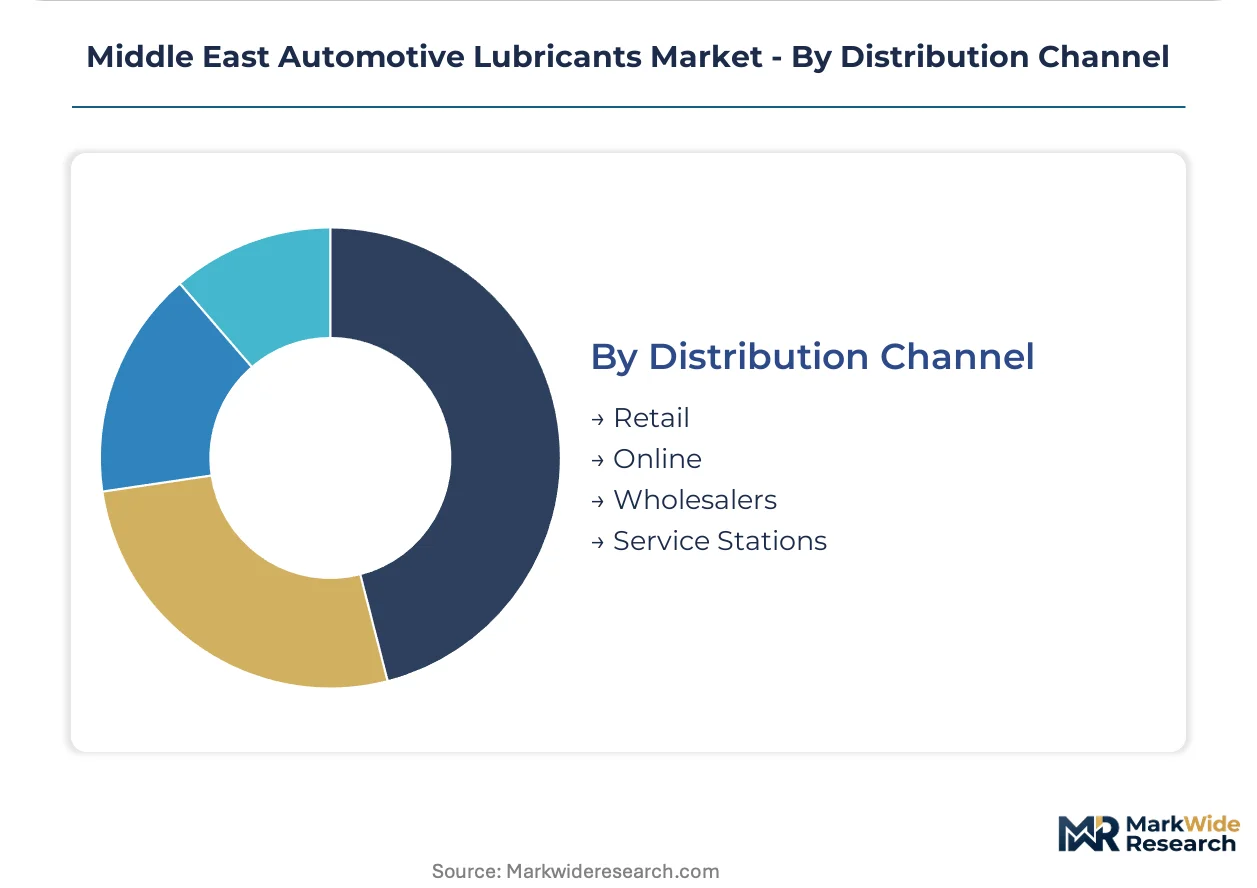
Distribution Channel:
Channel selection reflects purchase urgency, technical support needs, and fleet scale.
- Retail:Branded lubricant sales through auto parts stores and hypermarkets. DIY maintenance culture remains limited in the GCC compared to Western markets.
- Online:E-commerce platforms capturing price-sensitive consumers and small fleet operators. SFDA and ESMA labeling requirements complicate cross-border fulfillment.
- Wholesalers:Bulk distribution to independent workshops and secondary retailers. Inventory financing and credit terms determine supplier relationships.
- Service Stations:Integrated oil-change packages bundling lubricant, filter, and labor. Petromin Corporation's captive network in Saudi Arabia exemplifies this channel's volume concentration.
Transaction volumes cluster at Service Stations; Online is climbing the fastest as procurement digitization penetrates mid-size fleet operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional refiners in the Middle East produce surplus base oil feedstocks, yet lubricant formulation and blending capacity concentrates in Saudi Arabia and the UAE. This production-consumption asymmetry shapes trade flows and competitive positioning across the Gulf Cooperation Council.
Saudi Arabia
Commercial vehicle fleets along the Riyadh-Jeddah logistics corridor consume premium synthetic lubricants to manage thermal degradation in desert operating conditions. The Saudi Food and Drug Authority enforces petroleum derivatives standards that mandate performance certification before product registration. Petromin Corporation operates a captive retail network across the Kingdom, capturing fleet accounts through integrated service contracts.
United Arab Emirates
Dubai's logistics hub and Abu Dhabi's industrial zones drive demand for heavy-duty truck lubricants meeting Euro VI specifications. The Emirates Authority for Standardization and Metrology mandates labeling and performance certification for all lubricants sold domestically. ADNOC is expanding hydrocracker capacity in Ruwais to produce Group III+ base oils for synthetic lubricant manufacturing.
Kuwait
Independent workshops and smaller fleet operators sustain demand for semi-synthetic formulations balancing cost and performance. The country's national standards body participates in Gulf Standards Organization harmonization efforts that reduce cross-border regulatory friction. Al Ahmadi's industrial corridor hosts blending facilities serving domestic and re-export markets.
Qatar
Construction equipment and mining operations in the Doha metropolitan area drive grease and hydraulic fluid consumption. National infrastructure projects require lubricants meeting international OEM warranty specifications. Ras Laffan's industrial city concentrates heavy machinery deployment that sustains specialized lubricant demand.
Oman
Mining and construction equipment in the Sohar industrial port area consumes lithium-complex greases for chassis and wheel bearing applications. The country's standards regulator aligns with GCC harmonization protocols for petroleum product quality. Muscat's commercial vehicle service sector is adopting synthetic transmission fluids as automatic transmissions proliferate.
Middle East Automotive Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, distribution, and service integration vectors. The market structure tilts toward integrated suppliers with captive base oil production and retail network control. Three archetypes dominate: national oil companies with backward integration into feedstock supply, international majors leveraging technical partnerships with OEMs, and regional blenders competing on price in independent workshop channels. Competitive moves center on hydrocracker capacity expansion for synthetic base oil localization and service-station network consolidation to capture fleet procurement.
Among Saudi-based integrated suppliers, Petromin Corporation exemplifies the national oil company archetype with captive retail distribution. Shell anchors the international major tier through technical partnerships and base oil supply integration. ADNOC represents the Gulf-based diversified energy conglomerate expanding into premium lubricant manufacturing. These three occupy positions that illustrate how feedstock access, distribution control, and OEM relationships stratify competitive advantage.
| Leading Market Players |
|---|
| Petromin Corporation |
| Behran Oil Company |
| TotalEnergies |
| Shell |
| BP (Castrol) |
| ExxonMobil |
| FUCHS |
| ADNOC |
| Aljomaih and Shell Lubricating Oil Company |
| Others |
Supply & Pricing Matrix
Fleet procurement departments in Saudi Arabia's logistics corridor concentrate purchasing power through integrated service contracts, anchoring a contract-based long-term offtake model that rewards suppliers with captive retail networks and OEM certification depth.
Pricing Analysis
Margin tightening in synthetic formulations reflects Group III+ base oil import dependence and extended SFDA certification timelines that freeze working capital. Three-tier pricing structure across premium, standard, and economy levels stratifies by OEM approval tier and volume commitment scale. Cost-down pressure on mineral-based products accelerates because fleet operators calculate total cost of ownership through extended drain intervals. Independent workshops in smaller GCC markets exhibit highest price sensitivity; heavy-duty truck fleets with warranty compliance requirements show lowest.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Dammam form a hub-and-spoke pattern that feeds secondary wholesalers across the GCC. Supply concentrates in Saudi Arabia, the UAE, and Kuwait for blending capacity, while base oil feedstock draws from regional refinery expansions in Ruwais and Jubail. Raw material dependencies center on polyalphaolefin imports, additive package sourcing, and hydrocracker output from ADNOC and Behran Oil Company facilities. Single-source vulnerability in Group III+ base oil supply elevates risk for synthetic-dependent blenders. Distribution runs through service-station networks and OEM-affiliated maintenance chains that bundle lubricant with labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
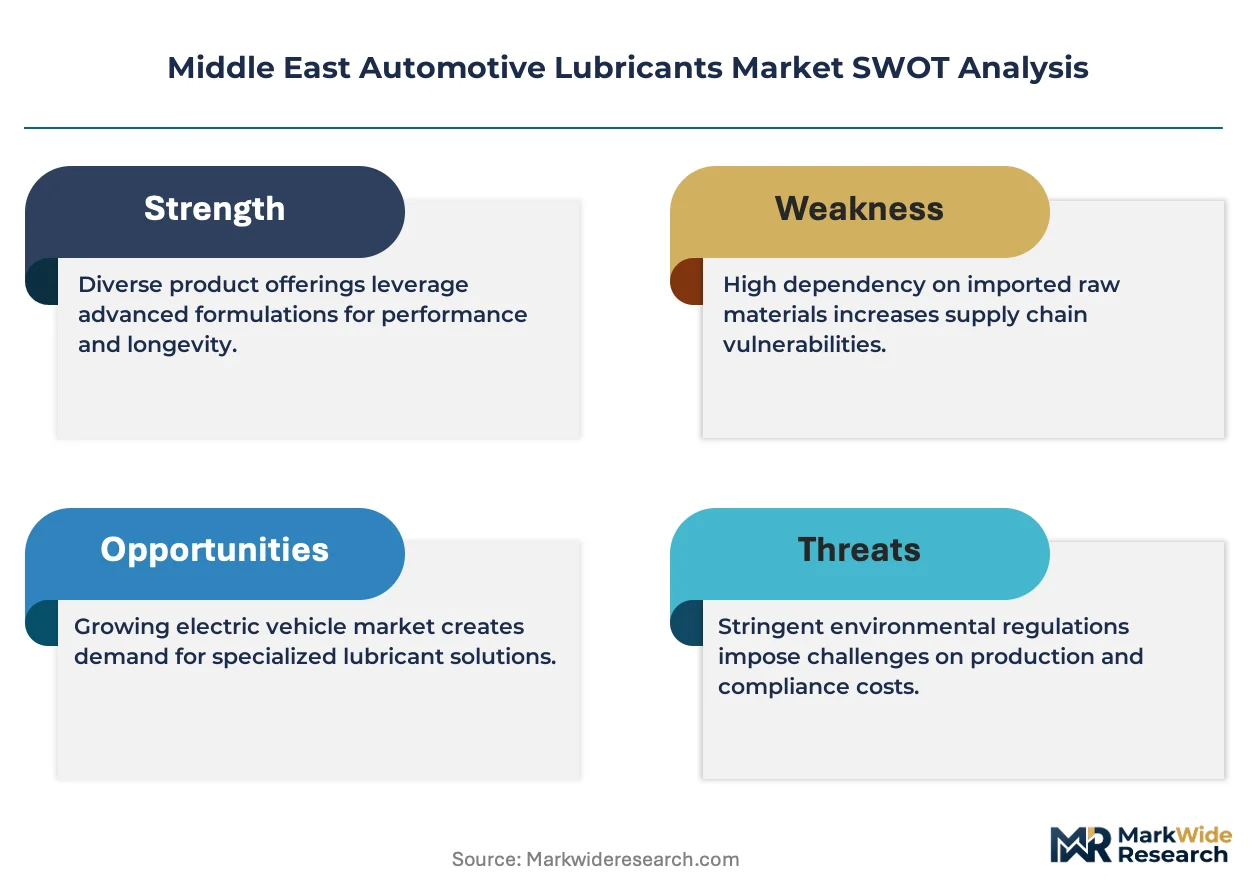
This market functions as a consolidation play where SFDA quality enforcement and OEM specification fragmentation force smaller blenders without in-house testing laboratories toward exit or acquisition.
For Market Incumbents: Extend hydrocracker capacity in Ruwais and Jubail to secure captive Group III+ feedstock supply against import volatility. Deepen service-station network control through exclusive fleet service contracts that lock out standalone distributors. Electric vehicle lubricant displacement threatens engine oil volumes; diversify into transmission and axle fluids for hybrid thermal management. For New Entrants and Emerging Players: Capture semi-synthetic demand among mid-size fleet operators in Kuwait and Oman trading up from mineral basestocks. White-space exists in biodegradable ester formulations for UAE offshore marine operators facing environmental compliance pressure. Enter through e-commerce platforms serving digitizing mid-size fleet procurement with SFDA-compliant labeling and cross-border fulfillment capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional blenders with established ESMA certification and wholesale distribution relationships in the UAE. Long-term viability rests on synthetic formulation R&D capability and OEM approval portfolio breadth across European, Japanese, and Korean manufacturer specifications. Watch Group III+ base oil localization announcements from ADNOC and Behran Oil Company as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Group III+ Base Oil Localization | ADNOC and Behran Oil Company hydrocracker expansions in Ruwais and Jubail reduce import dependence for synthetic feedstock. |
| Service-Station Network Consolidation | Petromin Corporation's captive retail footprint across Saudi Arabia captures fleet procurement through bundled oil-change packages. |
| OEM Approval Portfolio Expansion | Certification against Euro VI, JASO MA2, and API CK-4 specifications locks heavy-duty truck fleets into approved supplier tiers. |
| E-axle Thermal Management Formulation | Transmission and axle fluid diversification addresses hybrid vehicle cooling requirements beyond traditional engine oil demand. |
| Synthetic-Only Fleet Contract Conversion | Integrated service contracts specifying polyalphaolefin formulations displace mineral products through lifecycle cost calculations. |
Research Methodology
Multi-period observation of SFDA registration timelines, OEM specification cascades, and fleet procurement contract structures anchored the trend analysis, supplemented by interviews with lubricant formulation chemists, commercial vehicle fleet managers, aftermarket distribution channel heads, and base oil procurement leads at regional refiners. Secondary validation drew from Gulf Standards Organization harmonization protocols, Emirates Authority for Standardization and Metrology certification databases, customs trade records for base oil imports, and SEC filings of listed energy conglomerates with lubricant divisions. Bottom-up volume estimates from individual country consumption patterns triangulated against top-down refinery output and blending capacity assessments.
Segment-weighting across formulation chemistry, vehicle duty cycle, and distribution channel dimensions structured the analytical framework across the analysis window. CAGRs derived from logistic curve fitting to synthetic adoption rates in heavy-duty truck fleets and passenger vehicle OEM fill specifications. Industry-specific forecast inputs incorporated hydrocracker capacity expansion announcements from ADNOC and Behran Oil Company, plus electric vehicle penetration scenarios affecting engine oil displacement.
The model holds under continued SFDA and ESMA enforcement intensity and stable GCC logistics fleet expansion; deviation in electric vehicle adoption acceleration or Group III+ base oil supply disruption would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive Paint Robots Market