
 Vehicle Emission Testers Market | 2026-2036
Vehicle Emission Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Emission Testers Market Analysis
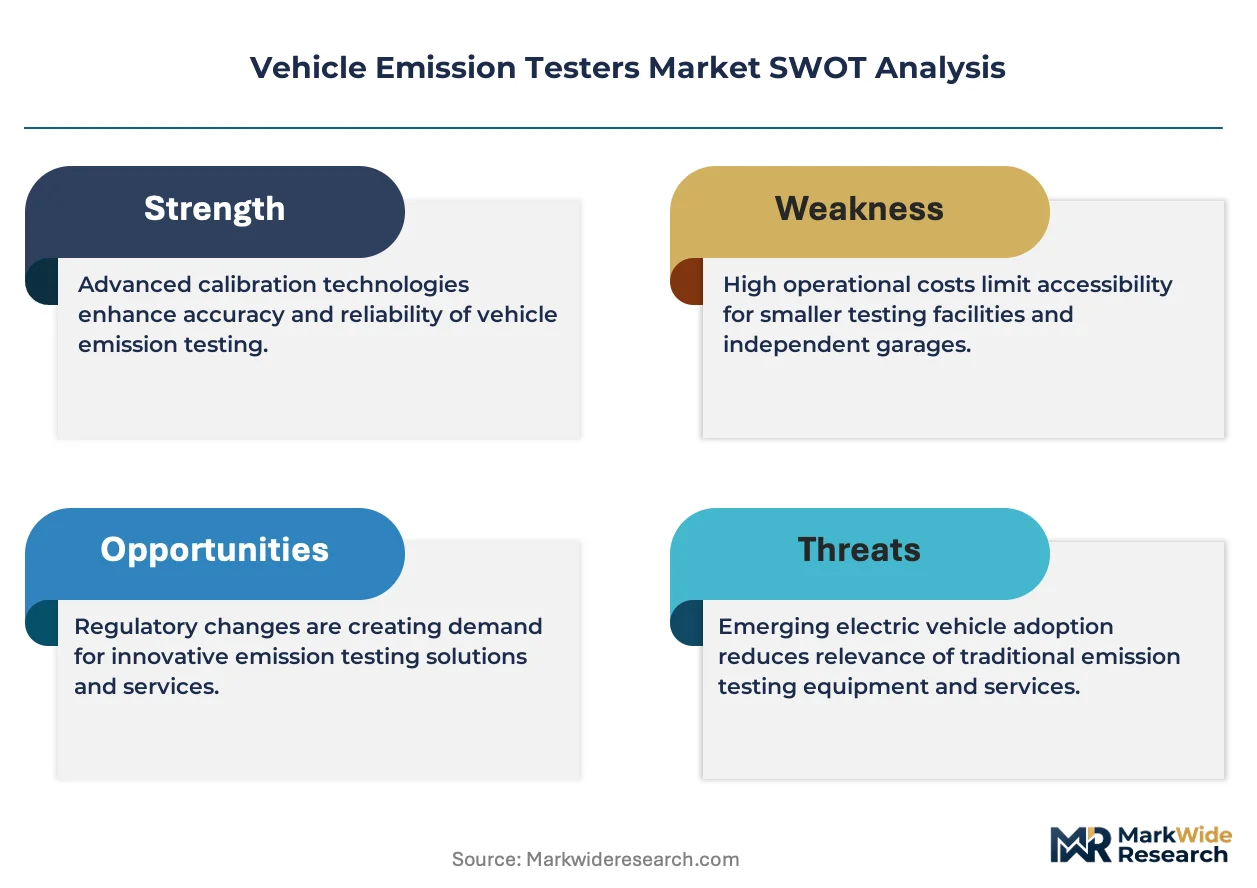
The capital-intensity divergence between full-system manufacturers and component suppliers is rotating competitive advantage toward vertically integrated players. HORIBA, Ltd. leverages its in-house spectrometry expertise to control critical sensor supply chains. AVL List GmbH anchors its position through deep integration with European OEM powertrain development programs. Bosch Limited competes by extending its automotive electronics footprint into diagnostic software layers.
Vehicle emission testers measure exhaust constituents including CO, CO2, HC, NOx, and particulate matter using detection methods such as non-dispersive infrared absorption and chemiluminescence reaction, serving regulatory compliance verification and engine calibration across passenger and commercial vehicle categories. Portable emission analyzers dominate service bay deployments due to lower capital barriers and flexibility across mixed fleets, while mass spectrometry-based systems command premium positioning in research institutions where trace-level detection thresholds matter. On-board diagnostics segments are gaining structural share as real-driving emissions protocols shift verification from laboratory to in-use conditions.
EPA Tier 3 and CARB standards in the United States, Euro 6 regulations enforced by national type-approval authorities across Europe, and China's MIIT emission certification requirements collectively tighten allowable pollutant thresholds and expand mandatory testing frequencies. The EU AI Act and emerging software-defined vehicle regulations introduce new compliance dimensions for automated diagnostic systems. Stakeholders must monitor divergence between laboratory certification protocols and real-world enforcement methodologies as the primary source of product specification risk.
Market Dynamics
The transition from laboratory certification to real-driving emissions testing is compressing equipment procurement cycles and forcing hardware suppliers to embed continuous monitoring capabilities directly into vehicle architectures.
Growth Catalysts
- EPA Tier 3 and CARB Standards:Tightening NOx and particulate matter thresholds in the United States mandate expanded testing frequencies and upgraded analyzer sensitivity, driving replacement demand across state inspection programs.
- China's MIIT Certification Requirements:The Ministry of Industry and Information Technology's enforcement of China VI standards accelerates adoption of portable emission analyzers in domestic vehicle manufacturing and aftermarket service networks.
- On-Board Diagnostic Integration:Fleet operators deploying connected vehicle platforms require embedded emission sensors that transmit real-time data, creating pull-through demand for calibration and verification equipment.
Market Restraints
- Platinum Group Metal Volatility:Chemiluminescence detectors and catalytic sensor elements depend on platinum and palladium inputs subject to price swings from South African and Russian supply concentration.
- Technical Limitation of Portable Units:Handheld analyzers struggle to achieve the parts-per-billion detection thresholds required for Euro 6d-TEMP certification without laboratory-grade mass spectrometry backup.
- Regulatory Friction from Divergent Protocols:Misalignment between EPA laboratory procedures and European RDE test conditions forces manufacturers to maintain parallel product configurations, elevating compliance overhead.
Strategic Opportunities
- India's BIS Emission Norms:Implementation of Bharat Stage VI standards creates underpenetrated demand for affordable portable analyzers in the country's fragmented vehicle service sector.
- Software-Defined Vehicle Convergence:Integration of emission diagnostics with over-the-air update platforms enables subscription-based calibration services, shifting revenue from hardware sales to recurring software licensing.
- EU Green Deal Procurement Mandates:Public fleet operators across Germany, France, and the Netherlands face binding electrification timelines that require hybrid vehicle emission verification, expanding the addressable equipment base.
Industry Challenges
- Spectroscopy Talent Scarcity:Design and calibration of non-dispersive infrared systems requires specialized optical engineering expertise concentrated in German and Japanese research institutions.
- Certification Timeline Compression:Type-approval authorities in China and Europe have shortened validation windows for new analyzer models, compressing R&D-to-revenue cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Emission Testers Market |
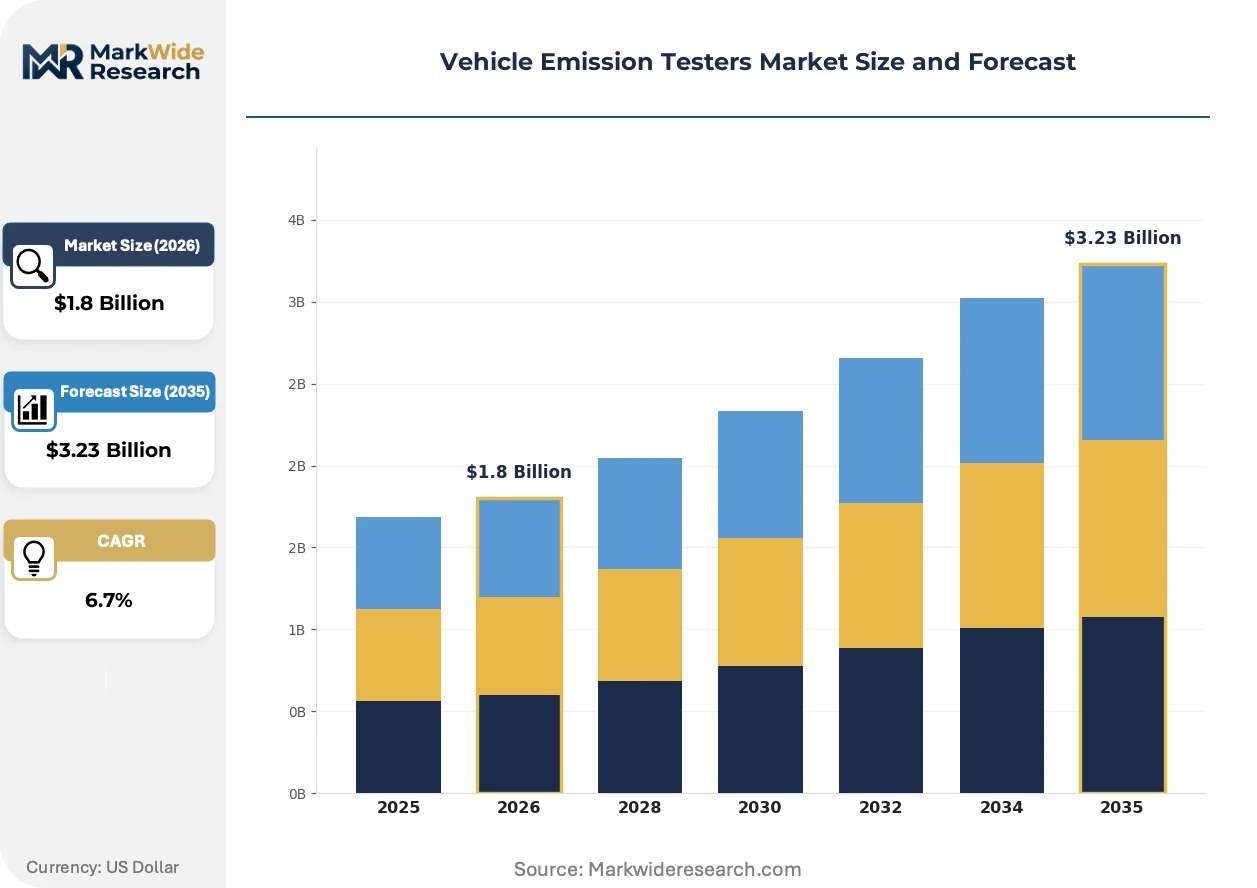
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Emission Analyzers, On-board Diagnostics, Exhaust Gas Analyzers, Smoke Meters Technology: Non-Dispersive Infrared Sensors, Chemiluminescence, Flame Ionization, Mass Spectrometry End User: Automotive Workshops, Government Authorities, Fleet Operators, Research Institutions Compliance Standard: Euro 6, EPA Tier 3, OBD II, CARB |
| Companies Covered | HORIBA, Ltd., AVL List GmbH, Bosch Limited, TÜV NORD GROUP, Siemens, SGS SA, Opus Group AB, TEXA S.p.A., Applus+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Emission Testers Market Emerging Trajectories
Sensor fusion architectures and edge computing capabilities are redefining how emission data is captured, processed, and transmitted across vehicle lifecycles. Hardware suppliers must now compete on software integration depth.
Micro-electromechanical systems for NOx detection is miniaturizing from laboratory bench units to chip-scale packages suitable for permanent vehicle installation. Tier 1 suppliers in Germany and Japan are adopting these MEMS platforms for 2027 model year powertrains. This compression of form factor is miniaturizing the addressable market for traditional portable analyzer manufacturers while expanding the embedded sensor segment.
The EU AI Act's risk classification framework subjects automated diagnostic algorithms to conformity assessment procedures previously reserved for safety-critical automotive components. European OEMs must now document training data provenance and algorithmic transparency for emission prediction models. Powertrain engineering departments are responding by segregating AI-enabled calibration tools from legacy rule-based systems to isolate compliance exposure.
Fleet maintenance departments are unbundling emission verification from bundled service contracts and sourcing portable analyzers through direct manufacturer relationships. This disintermediation of traditional distribution channels is most pronounced in North American heavy-duty trucking, where large operators bypass jobber networks to secure volume pricing and dedicated technical support. Equipment manufacturers are building captive service organizations to capture this margin pool.
Vehicle Emission Testers Market Segmentation
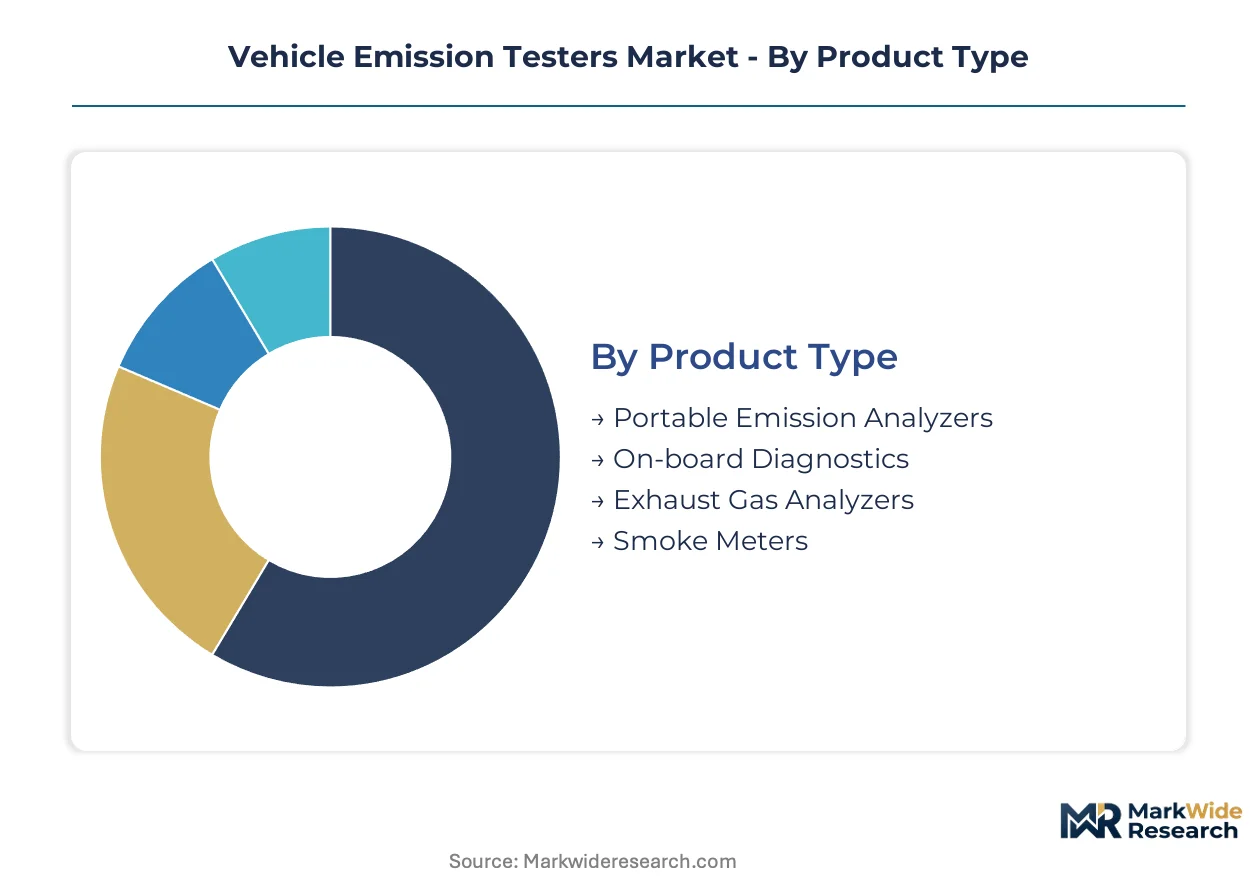
Equipment specification diverges sharply between regulatory verification mandates and research-grade precision requirements. Procurement patterns fragment across state inspection programs, OEM calibration facilities, and fleet maintenance networks with distinct performance thresholds and capital constraints.
Product Type:
Portable emission analyzers face the most acute substitution pressure from embedded sensor networks as real-driving emissions protocols shift verification from laboratory bays to in-use conditions.
- Portable Emission Analyzers:Handheld units employing non-dispersive infrared and electrochemical cells for CO, CO2, HC, and NOx quantification in service bay environments. Demand concentrates in Germany's TÜV inspection stations and China's MIIT-certified vehicle manufacturing facilities as Bharat Stage VI implementation accelerates aftermarket penetration in India.
- On-board Diagnostics:Permanent vehicle-integrated systems transmitting real-time emission data via telematics platforms to fleet management dashboards. Heavy-duty trucking operators across the United States bypass traditional distribution channels to secure direct manufacturer relationships and dedicated calibration support.
- Exhaust Gas Analyzers:Fixed installation systems for laboratory certification and type-approval testing with higher sensitivity thresholds.
- Smoke Meters:Opacity measurement devices for diesel particulate verification in commercial vehicle inspection lanes.
Portable emission analyzers retain volume leadership; on-board diagnostics holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium research-grade detection from mass-market service bay equipment, with platinum group metal inputs driving volatility in mid-tier chemiluminescence platforms.
- Non-Dispersive Infrared Sensors:Benchtop and portable units measuring CO and CO2 absorption at specific infrared wavelengths using gas filter correlation. Automotive workshops in the United States dominate procurement for state inspection program compliance as EPA Tier 3 mandates expand testing frequency.
- Chemiluminescence:Reaction-based NOx detection achieving parts-per-billion sensitivity required for Euro 6d-TEMP certification. Research institutions and European OEM powertrain development programs anchor demand despite platinum catalyst price exposure from South African supply concentration.
- Flame Ionization:Hydrocarbon quantification through combustion ionization current measurement in laboratory environments.
- Mass Spectrometry:Trace-level multi-species detection for regulatory research and algorithm validation studies.
Non-dispersive infrared sensors retain volume leadership; mass spectrometry holds the steepest expansion curve.
End User:
Customer type fragmentation intensifies as fleet operators disintermediate traditional distribution channels and government authorities compress type-approval timelines.
- Automotive Workshops:Independent service facilities and dealership bays performing periodic emission inspections and repair verification. China's fragmented vehicle service sector generates underpenetrated demand for affordable portable analyzers as domestic MIIT enforcement tightens.
- Fleet Operators:Commercial vehicle and logistics companies deploying connected diagnostic platforms for predictive maintenance. North American heavy-duty trucking procurement is shifting toward direct manufacturer relationships to secure volume pricing and captive technical support organizations.
- Government Authorities:State and national inspection programs mandating periodic emission verification for vehicle registration.
- Research Institutions:Universities and regulatory laboratories developing certification protocols and emission factor databases.
Automotive workshops retain volume leadership; fleet operators hold the steepest expansion curve.
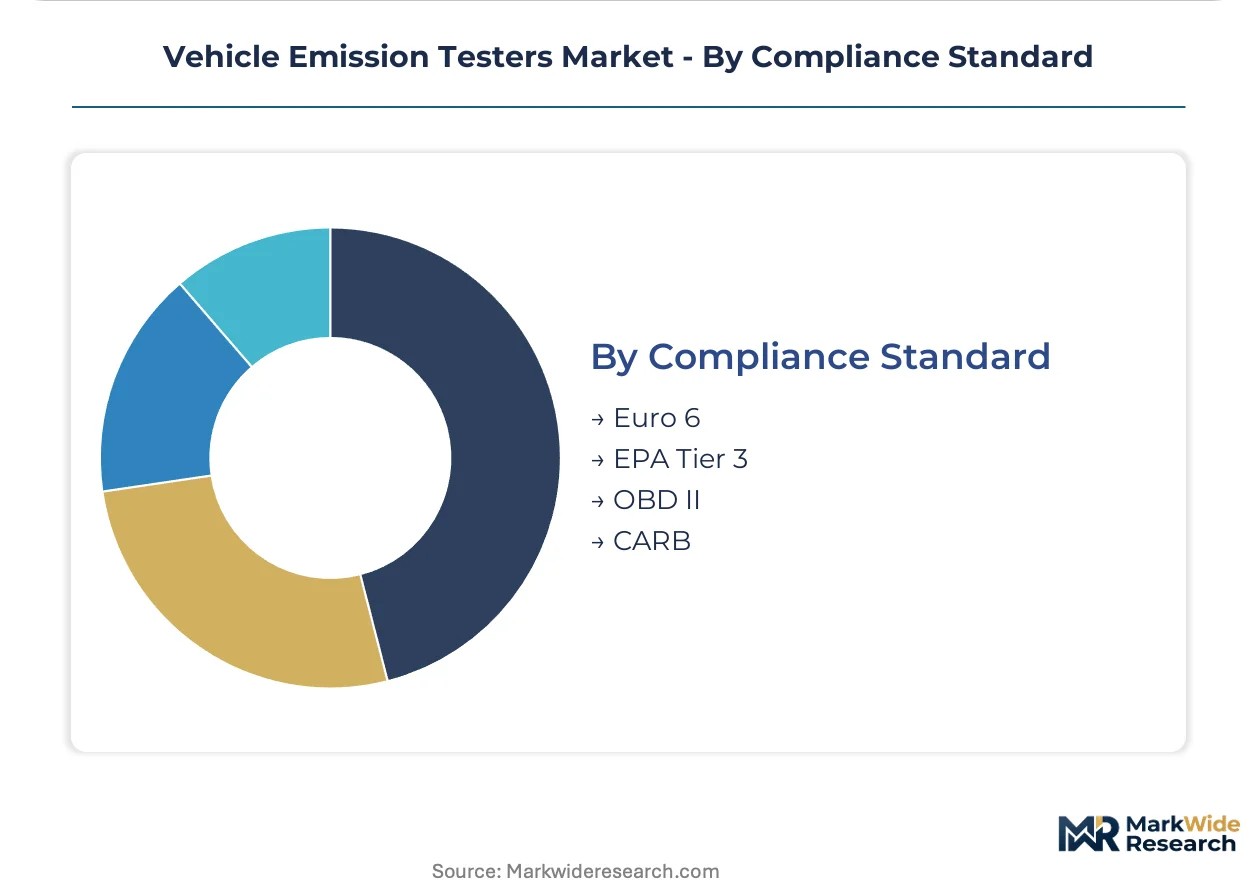
Compliance Standard:
Geography-driven specification divergence forces manufacturers to maintain parallel product configurations, elevating compliance overhead across export-oriented suppliers.
- Euro 6:European Union emission certification enforced by Germany's KBA and national type-approval authorities with real-driving emissions test conditions. OEM powertrain engineering departments in Germany and France face binding EU Green Deal procurement mandates for public fleet electrification timelines requiring hybrid verification equipment.
- EPA Tier 3:United States federal standards tightening NOx and particulate matter thresholds with expanded state inspection program coverage. California's CARB regulations create additional specification layers for equipment sold into the country's largest single-state vehicle market.
- OBD II:On-board diagnostic communication protocols standardized across light-duty vehicles for fault code retrieval and emission system monitoring.
- CARB:California Air Resources Board standards exceeding federal thresholds and influencing equipment specification for sixteen additional adopting states.
Euro 6 retains volume leadership; EPA Tier 3 holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys emission testers primarily for OEM powertrain calibration and type-approval laboratories, while the United States concentrates procurement in state inspection programs and heavy-duty fleet maintenance networks. China's MIIT enforcement drives manufacturing-floor verification demand. India's fragmented service sector creates distinct affordability requirements.
Germany
KBA type-approval authorities and TÜV inspection stations anchor equipment demand for Euro 6d-TEMP certification. The EU AI Act imposes conformity assessment on automated diagnostic algorithms used in emission prediction models. Stuttgart and Munich host OEM engineering centers where MEMS-based NOx sensors undergo 2027 powertrain integration.
United States
EPA Tier 3 mandates expand testing frequencies across state inspection programs, while CARB regulations layer additional specifications for California and sixteen adopting states. California's Air Resources Board maintains the nation's most stringent NOx thresholds. Detroit-area heavy-duty trucking operators disintermediate jobber networks to secure direct manufacturer relationships for fleet-scale procurement.
China
MIIT enforcement of China VI standards accelerates portable analyzer adoption in domestic vehicle manufacturing and aftermarket service networks. The Ministry of Industry and Information Technology compresses type-approval timelines for new analyzer models. Shanghai and Beijing concentrate procurement for state-owned vehicle manufacturer certification facilities.
India
Bharat Stage VI implementation generates underpenetrated demand for affordable portable analyzers in the country's fragmented vehicle service sector. BIS emission norms create regulatory pull without the capital intensity of European laboratory-grade systems. Maharashtra and Gujarat host the densest concentrations of commercial vehicle workshops requiring basic CO and HC verification capability.
Vehicle Emission Testers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertically integrated spectrometry and automotive electronics players controlling critical sensor supply chains against component-focused challengers. The upper tier combines in-house optical engineering with captive diagnostic software development, while mid-tier competitors rely on outsourced platinum-group-metal sensors and third-party calibration protocols. Three archetypes dominate: full-system manufacturers with spectrometry heritage, automotive electronics conglomerates extending into diagnostic layers, and testing-service conglomerates backward-integrating into equipment supply. Competitive moves center on strategic partnerships with telematics platforms and geographic expansion into India's fragmented service sector.
Within the integrated-system tier, HORIBA, Ltd. and AVL List GmbH exemplify spectrometry-led positioning, while Bosch Limited anchors the automotive-electronics extension archetype. HORIBA's Japanese corporate structure reflects long-standing optical engineering concentration, AVL's Austrian GmbH form signals European powertrain-development integration, and Bosch's Limited designation indicates Indian-market operational scale. These three occupy positions where in-house sensor production meets embedded software capability, representing the vertical-integration threshold that component suppliers struggle to cross.
| Leading Market Players |
|---|
| HORIBA, Ltd. |
| AVL List GmbH |
| Bosch Limited |
| TÜV NORD GROUP |
| Siemens |
| SGS SA |
| Opus Group AB |
| TEXA S.p.A. |
| Applus+ |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for platinum-group-metal sensors directly tie equipment margins to South African and Russian supply volatility, compressing pricing power for mid-tier portable analyzer manufacturers while amplifying captive sourcing advantages for integrated spectrometry houses.
Pricing Analysis
Long-term offtake contracts dominate procurement between OEM calibration facilities and full-system manufacturers, though spot-market spot purchases persist for replacement sensor elements. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry research systems from TÜV-certified portable units and basic smoke meters for emerging markets. Cost compression in mid-tier chemiluminescence platforms is intensifying because platinum catalyst price exposure from South African supply concentration. Automotive workshops in India's fragmented service sector exhibit the highest price sensitivity, while European OEM powertrain engineering departments prioritize detection threshold precision over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision optical component fabrication, with Stuttgart and Munich hosting MEMS foundries for 2027 powertrain NOx sensor integration. China concentrates final assembly for portable emission analyzers serving domestic MIIT enforcement and export markets. South Africa and Russia feed platinum and palladium inputs for chemiluminescence detectors. Single-source vulnerability runs through South African platinum group metal refining. Distribution runs through captive service organizations for heavy-duty fleet operators, traditional jobber networks for independent workshops, and direct manufacturer relationships for OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-driving emissions protocol adoption constitutes a high-growth disruption, compressing equipment procurement cycles from laboratory certification to continuous in-use monitoring and forcing hardware suppliers to embed edge-computing capabilities directly into vehicle architectures.
For Market Incumbents: Consolidate sensor supply chains through backward integration into MEMS fabrication or exclusive platinum-group-metal offtake agreements to defend against embedded sensor substitution. Deepen software integration with telematics platforms to capture recurring calibration revenue streams threatened by over-the-air update platforms. Lock in TÜV and MIIT certification timelines through preemptive regulatory engagement to compress competitor R&D-to-revenue windows. For New Entrants and Emerging Players: Bharat Stage VI certification fast-track positions affordable portable analyzers for India's underpenetrated vehicle service sector, where fragmented workshop density exceeds European TÜV station concentration. Fleet operator direct procurement disintermediation creates white-space for technical support organizations bypassing traditional distribution. Target embedded sensor calibration services for 2027 powertrain integration programs where MEMS packaging expertise concentrates in German and Japanese tier-1 suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive electronics conglomerates seeking to divest non-core diagnostic hardware divisions amid software-defined vehicle convergence. Long-term viability favors vertically integrated spectrometry specialists with captive optical engineering and diagnostic software stacks over component-dependent assemblers. Monitor divergence between EPA laboratory procedures and European RDE test conditions as the primary signal for product specification risk and parallel configuration overhead.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Platform Integration | Miniaturizes NOx detection from benchtop units to chip-scale vehicle installation, displacing portable analyzer demand. |
| Telematics Platform Partnership | Enables real-time emission data transmission to fleet management dashboards, creating pull-through calibration service demand. |
| India Service Network Expansion | Captures Bharat Stage VI aftermarket penetration in fragmented vehicle workshops across Maharashtra and Gujarat. |
| AI Diagnostic Algorithm Certification | Addresses EU AI Act conformity assessment requirements for automated emission prediction models in European OEM programs. |
| Platinum Group Metal Supply Agreement | Hedges chemiluminescence detector input costs against South African and Russian supply concentration volatility. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with OEM powertrain engineering directors, TÜV inspection station operators, fleet maintenance procurement managers, and MIIT certification facility heads; and secondary validation through EPA Tier 3 regulatory filings, Euro 6d-TEMP type-approval databases, China VI enforcement bulletins, and vehicle production registration records. Bottom-up equipment shipment triangulation crossed with top-down regulatory mandate sizing across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, technology detection method, end-user procurement archetype, and compliance standard geography. CAGRs derived from segment-level equipment replacement cycles, regulatory timeline enforcement, and fleet telematics adoption curves. Forecast inputs incorporated platinum group metal price volatility bands and MEMS sensor integration roadmaps from German and Japanese tier-1 suppliers.
Underlying assumptions cover sustained EPA Tier 3 and Euro 6 enforcement trajectory, with deviation risk concentrated in regulatory protocol divergence between laboratory certification and real-driving emissions test conditions. Recalibration cycles align with material shifts in RDE protocol harmonization, platinum supply disruptions, and software-defined vehicle diagnostic platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market