
 Automotive Trailing Arm Market | 2026-2036
Automotive Trailing Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trailing Arm Market Analytics
OEM procurement for electric vehicle platforms is bifurcating from conventional ICE trailing arm specifications. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to anchor supply relationships with European premium manufacturers. Magna International Inc. competes through manufacturing scale across North American and Asian production corridors. DRiV Incorporated differentiates via aftermarket channel density and service-part interoperability.
An automotive trailing arm is a suspension linkage that connects the vehicle body or subframe to the wheel hub, maintaining wheel alignment under vertical travel and transmitting lateral and braking loads; modern variants employ stamped steel, cast aluminum, or carbon fiber-reinforced polymer construction with bonded bushings to achieve targeted stiffness-to-weight ratios for ride-handling trade-offs. Control arms dominate volume production for passenger car applications where cost efficiency and proven durability matter most, while composite arms represent the fastest-expanding material category as OEMs pursue mass reduction for EV range extension. Steel trailing arms retain margin strength in commercial vehicle segments where load capacity and impact resistance override weight priorities.
NHTSA Federal Motor Vehicle Safety Standards govern structural integrity and occupant protection requirements that directly influence trailing arm load-case specifications and testing protocols in the United States, while EPA Corporate Average Fuel Economy regulations incentivize mass reduction that accelerates aluminum and carbon fiber substitution. The EU Green Deal and associated automotive CO2 targets through EEA implementation are tightening material sourcing and recyclability standards for European suppliers. Stakeholders must monitor how battery pack placement in skateboard architectures is eliminating traditional rear subframe attachment points and forcing trailing arm redesigns for load-path reconfiguration.
Market Dynamics
Skateboard battery architectures are eliminating traditional rear subframe mounting geometries, forcing trailing arm redesigns that reroute load paths around battery pack housings while preserving suspension kinematics.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:Mass reduction targets accelerate aluminum and carbon fiber substitution in passenger car rear suspension modules.
- Electric vehicle platform proliferation:Dedicated EV architectures require lightweight trailing arm configurations to offset battery weight and extend range.
- Germany's premium OEM engineering concentration:Battery-electric vehicle programs in Stuttgart and Munich are driving redesign contracts for integrated rear suspension modules.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum cost swings compress margin on cast trailing arm production for mid-market vehicle segments.
- Carbon fiber supply concentration:Precursor acrylonitrile and carbon fiber tow production clusters in Japan and the United States create single-source vulnerability.
- REACH substance restrictions:European chemical registration requirements limit bonding adhesive chemistries for composite bushing attachment.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives attract trailing arm manufacturing for export-oriented EV platforms.
- Aftermarket service-part digitization:VIN-matched configuration databases enable direct-to-workshop distribution bypassing traditional wholesale tiers.
- Closed-loop aluminum recycling:EU Green Deal circularity mandates create certified recycled-content premiums for sustainable material sourcing.
Industry Challenges
- Multi-material joining expertise:Hybrid steel-aluminum-composite arm construction requires adhesive bonding and mechanical fastening competencies scarce in conventional stamping operations.
- Homologation timeline compression:NHTSA Federal Motor Vehicle Safety Standards validation protocols for modified load paths extend development cycles for skateboard-platform adaptations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trailing Arm Market |
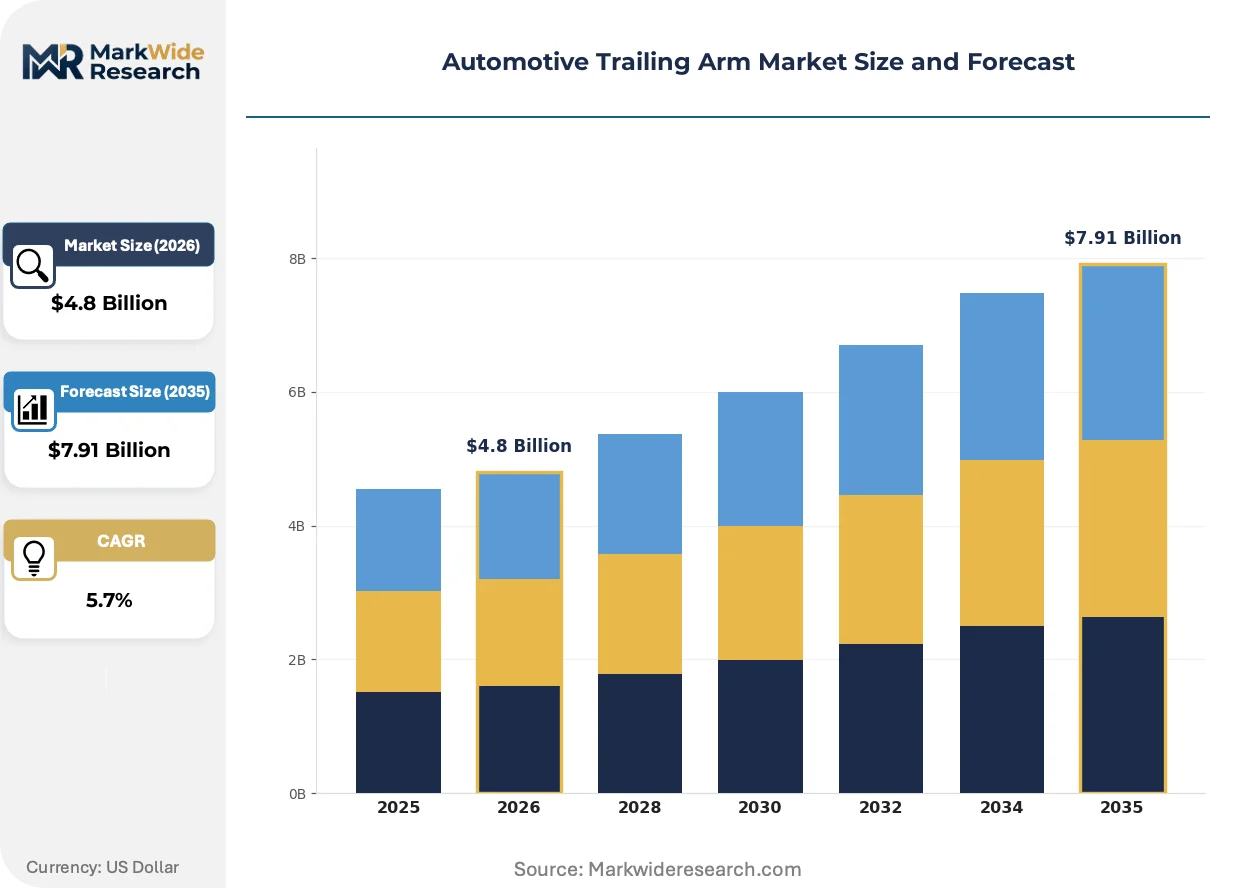
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Arm, Swing Arm, Composite Arm, Adjustable Arm Material: Aluminum, Steel, Carbon Fiber, Plastic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Cars, Commercial Vehicles, SUVs, Motorsports |
| Companies Covered | ZF Friedrichshafen AG, Magna International Inc., DRiV Incorporated, Aludyne, Mevotech, ACDelco, Dorman Products, MOOG, TRW Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trailing Arm Market Evolving Landscape
Material science advances and regulatory pressure are converging to transform trailing arm construction methods, with manufacturing process innovation now outpacing traditional component design cycles.
Carbon fiber-reinforced polymer trailing arms are decomposing the historical steel-dominant supply structure. European premium EV platforms are adopting braided thermoplastic composite arms at production scale. The technology is decomposing incumbent stamping equipment investments and compressing supplier qualification timelines for lightweight chassis programs.
EU Green Deal automotive CO2 targets through EEA implementation are tightening material sourcing and recyclability standards. European suppliers must document end-of-life recovery pathways for composite arms and bonded joints. German Tier-1 engineering centers are responding with design-for-disassembly protocols and reversible adhesive systems.
Fleet procurement departments are consolidating chassis component sourcing under platform-level contracts rather than discrete part negotiations. Direct OEM-trailing arm manufacturer relationships are replacing multi-tier distribution for high-volume EV programs. This concentration is most visible in North American electric truck and SUV launches where single-source module supply reduces integration risk.
Automotive Trailing Arm Market Segmentation
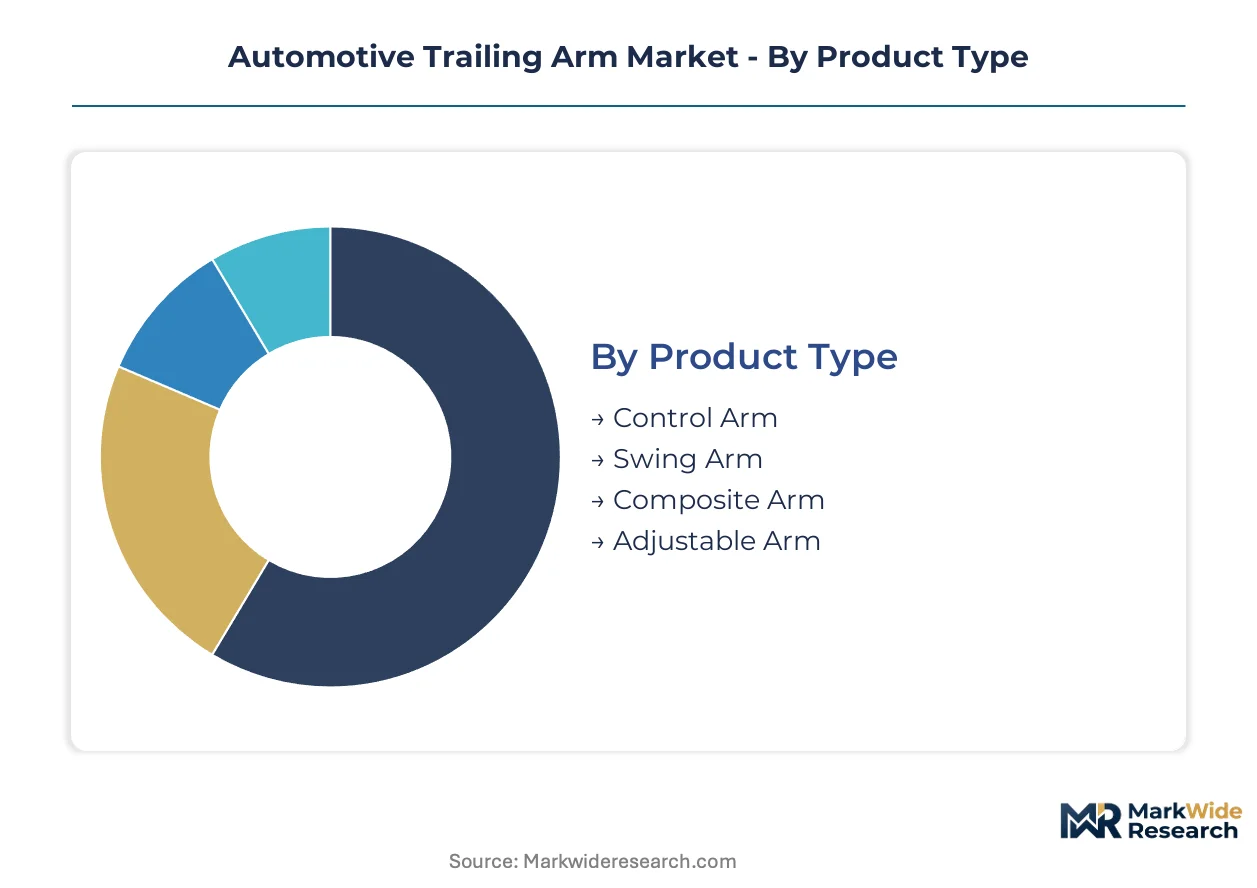
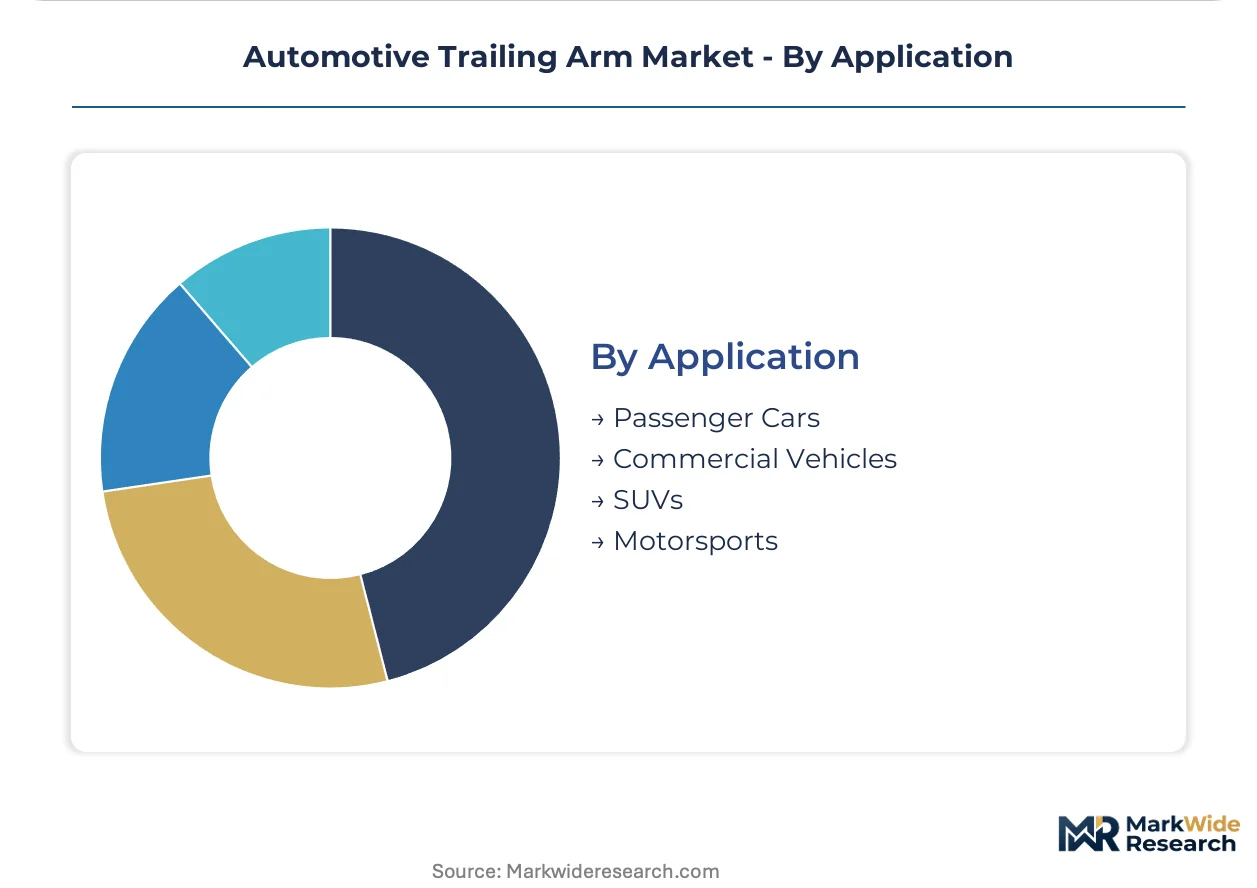
Trailing arm procurement patterns diverge sharply across product architectures and material specifications. OEM platform strategies and regulatory compliance requirements reshape which segment combinations capture contract value in electric vehicle programs.
Product Type:
Substitution pressure from composite architectures is fragmenting the traditional steel-dominated supply base, with stamped and cast configurations facing displacement from thermoplastic alternatives.
- Control Arm:Stamped steel or cast aluminum linkages with integrated bushing housings dominate passenger car volume production where cost-per-unit and proven fatigue life outweigh mass considerations. Demand concentrates in mid-market sedan and hatchback programs across Germany, Japan, and the United States where NHTSA durability protocols govern specification.
- Composite Arm:Braided carbon fiber-reinforced polymer or thermoplastic constructions achieve 40-60% mass reduction versus steel equivalents. European premium OEMs in Stuttgart and Munich are qualifying these for battery-electric rear suspension modules where range extension justifies material cost premiums.
- Swing Arm:Single-sided pivot designs common to motorcycle-derived architectures and compact urban EV platforms.
- Adjustable Arm:Camber- and toe-adjustable variants serving aftermarket performance tuning and motorsports homologation requirements.
Control arms retain volume leadership; composite arms hold the steepest expansion curve.
Material:
Cost tier stratification separates aerospace-grade carbon fiber from commodity aluminum and steel, with recycled-content premiums emerging as a new pricing dimension under EU circularity mandates.
- Aluminum:Cast and forged alloys dominate premium passenger car applications where stiffness-to-weight optimization meets EPA fuel economy targets. Primary ingot price volatility compresses margins on mid-market programs.
- Carbon Fiber:PAN-based precursor tow converted to epoxy or thermoplastic matrices enables extreme mass reduction for EV range maximization. Acrylonitrile supply concentration in Japan and the United States creates single-source vulnerability.
- Steel:High-strength low-alloy stampings retain commercial vehicle dominance where load capacity and impact resistance override weight priorities.
- Plastic:Glass-filled nylon and PEEK compounds occupy niche bushing carrier and isolation functions.
Steel retains installed-base dominance; carbon fiber climbs the fastest on new-platform penetration.
End User:
Customer-type concentration is bifurcating procurement between consolidated OEM platform contracts and fragmented aftermarket service-part channels.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz AG integrate trailing arm specification into skateboard chassis module sourcing for dedicated EV architectures. Direct manufacturer relationships are replacing multi-tier distribution.
- Tier-1 Suppliers:ZF Friedrichshafen AG and Continental AG consolidate rear suspension module production under integrated chassis systems contracts.
- Aftermarket Providers:DRiV Incorporated and Moog maintain channel density through VIN-matched configuration databases enabling direct-to-workshop distribution.
- Vehicle Assemblers:Contract manufacturers and EV startups sourcing pre-integrated subassemblies rather than discrete components.
OEMs command specification authority; Tier-1 suppliers capture the steepest contract expansion.
Application:
Application maturity varies sharply, with passenger car segments facing the most intense material-transition disruption while commercial vehicle demand preserves legacy steel specifications.
- Passenger Cars:C-segment and D-segment sedans drive aluminum control arm volume where EPA Corporate Average Fuel Economy mandates accelerate mass reduction. German premium OEMs are redesigning rear modules for battery-electric compatibility.
- SUVs:Unibody and body-on-frame sport utility platforms require reinforced trailing arm capacities to manage higher center-of-gravity loads and towing ratings.
- Commercial Vehicles:Class 3-8 trucks and vans prioritize impact resistance and service life over weight, preserving steel dominance.
- Motorsports:Formula and GT categories drive carbon fiber arm development with rapid technology transfer to road car programs.
Passenger cars anchor volume demand; SUVs gain share fastest on platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as Europe's primary chassis component logistics hub, connecting Stuttgart engineering centers to Asian precursor supply chains and North American assembly plants.
United States
EPA Corporate Average Fuel Economy mandates accelerate aluminum substitution in rear suspension modules for Detroit's electric truck and SUV launches. NHTSA Federal Motor Vehicle Safety Standards govern structural integrity testing protocols that extend development cycles for modified load paths. Michigan and Ohio production corridors host concentrated stamping and casting operations serving domestic OEM platform contracts.
Germany
Premium OEM battery-electric vehicle programs in Stuttgart and Munich drive redesign contracts for integrated rear suspension modules. EU Green Deal circularity mandates create certified recycled-content premiums for aluminum sourcing under EEA implementation. Baden-Württemberg engineering centers qualify braided thermoplastic composite arms for production-scale EV architectures.
China
Dual carbon goals and NEV subsidies propel domestic EV platform proliferation requiring lightweight trailing arm configurations. MIIT GB standards govern suspension component durability and safety certification for passenger car applications. Yangtze River Delta manufacturing clusters concentrate aluminum forging and composite precursor processing capacity.
Japan
METI industrial policy supports carbon fiber supply chain security for automotive lightweighting applications. JIS standards specify material grades and testing protocols for chassis linkages in domestic vehicle programs. Nagoya and Tokyo metropolitan areas host precursor acrylonitrile and carbon fiber tow production facilities serving Asian OEM demand.
India
PLI scheme production-linked incentives attract trailing arm manufacturing for export-oriented EV platforms serving European and North American markets. BIS automotive component standards align with UN ECE regulations for chassis system homologation. Tamil Nadu and Maharashtra automotive corridors concentrate stamping and casting operations for domestic and export supply.
Automotive Trailing Arm Market Competitive Landscape
Concentration sits with integrated chassis systems specialists and diversified Tier-1 suppliers. The supply structure fragments between premium OEM direct relationships and mid-market wholesale distribution channels. Three archetypes dominate: full-system integrators anchoring platform-level contracts, component specialists defending aftermarket channel density, and diversified automotive suppliers leveraging manufacturing scale across production corridors. M&A activity targets composite material competencies and regional manufacturing footprint expansion.
Within the integrated systems tier, ZF Friedrichshafen AG anchors European premium OEM relationships through chassis module consolidation. Magna International Inc. exemplifies scale-driven manufacturing across North American and Asian production corridors. DRiV Incorporated occupies a position within aftermarket channel architecture, leveraging service-part interoperability and VIN-matched distribution databases.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Magna International Inc. |
| DRiV Incorporated |
| Aludyne |
| Mevotech |
| ACDelco |
| Dorman Products |
| MOOG |
| TRW Automotive |
| Others |
Value Network & Pricing Analysis
NHTSA Federal Motor Vehicle Safety Standards certification gates both supplier qualification and price tiering simultaneously, with crashworthiness validation protocols separating premium aluminum-composite suppliers from commodity steel stampers and creating certified-content premiums that OEMs pay for documented load-path integrity.
Pricing Analysis
Volume-discount tiering structures separate contract-based long-term offtake agreements for high-volume EV platforms from spot-market transactions serving aftermarket channels. Price differentiation hinges on NHTSA certification tier and aluminum ingot quality grade, with bonded composite arms commanding material-cost premiums over stamped steel equivalents. Pricing pressure stems from primary aluminum volatility compressing margins on mid-market cast arm production. Fleet procurement departments show lowest price sensitivity for integrated chassis modules, while independent repair workshops exhibit highest sensitivity to service-part markups.
Supply Chain Analysis
Acrylonitrile precursor supply concentration in Japan and the United States creates single-source vulnerability for carbon fiber tow production feeding European composite arm qualification programs. Manufacturing gravity centers on Germany, China, and Mexico, with Baden-Württemberg engineering clusters drawing from Japanese precursor supply and Yangtze River Delta forging capacity feeding Asian OEM demand. Raw material dependencies span primary aluminum ingot, PAN-based carbon fiber tow, and high-strength low-alloy steel coil. Distribution runs through platform-level direct contracts for OEMs and VIN-matched databases for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive trailing arm market sits in early-cycle expansion, with electric vehicle platform proliferation driving material-transition contracts that displace legacy steel specifications before market saturation sets in.
For Market Incumbents: Secure backward integration into aluminum recycling streams to capture EU Green Deal circularity premiums and defend margin position against ingot price volatility. Lock in multi-year composite precursor supply agreements with Japanese acrylonitrile producers before capacity constraints tighten. Prioritize NHTSA homologation expertise as a certification moat against emerging composite specialists lacking crash-test validation track records. For New Entrants and Emerging Players: CE marking fast-track pathways for thermoplastic composite arms open access to German premium OEM supplier development programs without incumbent stamping equipment legacy costs. Target India's PLI scheme production corridors for export-oriented EV platform supply, where government incentives offset capital intensity. Pursue direct-to-workshop aftermarket distribution using VIN-matched configuration databases to bypass entrenched wholesale tiers controlled by established service-part networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum forging specialists holding stranded capacity in mid-market passenger car segments facing composite substitution pressure. Five-to-ten year viability hinges on successful material-transition execution rather than volume scale alone. Monitor carbon fiber tow capacity expansion announcements from Japanese precursor producers as the inflection signal for composite arm cost-competitiveness against aluminum equivalents.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling duplication across EV skateboard architectures for Stuttgart and Munich OEMs. |
| Battery Supply Agreement | Secures cell capacity commitments that enable trailing arm load-path redesign around pack housings. |
| Software-Defined Vehicle Investment | Integrates predictive suspension wear algorithms into chassis module specification requirements. |
| Geographic Manufacturing Footprint | Positions stamping and composite operations near Detroit electric truck launch corridors. |
| Charging Infrastructure Partnership | Aligns fleet electrification timelines with trailing arm service-life warranties for commercial vehicle segments. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement data anchors the qualitative findings on contract concentration and material-transition timelines. Primary interviews with chassis systems engineers, aftermarket distribution managers, aluminum procurement leads, and composite manufacturing specialists combine with secondary validation against NHTSA FMVSS filing databases, EPA CAFE compliance records, vehicle production registries, and EU EEA implementation guidance documents. Bottom-up build from discrete component specifications and top-down reconciliation against platform-level bill-of-materials estimates ensure triangulation integrity.
Sensitivity analysis on aluminum ingot price trajectories and carbon fiber tow capacity expansion schedules shapes the analytical framework across the projection horizon. Segmentation dimensions span product architecture, material specification, end-user type, and regional production cluster, with vehicle class and propulsion architecture as automotive-specific modeling layers. CAGRs derive from production volume build-ups weighted by content-per-vehicle assumptions and platform penetration curves, calibrated against OEM electrification commitment announcements and regulatory compliance deadlines.
Underlying assumptions cover NHTSA homologation timeline stability, EU Green Deal circularity mandate enforcement intensity, and EV platform architecture standardization, with deviation risk concentrated in carbon fiber supply chain disruption and mid-market OEM composite adoption delays. Practitioners should keep alternative scenarios live as battery-electric vehicle penetration rates and material substitution elasticities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Tappet Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market