
 Air Filter Cartridges Market | 2026-2036
Air Filter Cartridges Market Size, Share, and Industry Trends Forecast 2026-2036
Air Filter Cartridges Market Analysis
EU F-Gas Regulation phase-down schedules is rebalancing demand toward lower-pressure-drop cartridge designs in commercial HVAC retrofits. MANN + HUMMEL Group leverages its vertical integration into nonwoven media production to control input costs across European aftermarket channels. Donaldson Company, Inc. anchors its position through specialized membrane technologies for industrial dust collection. Eaton Corporation competes on filtration-electrical system integration for data center cooling architectures.
Air filter cartridges are cylindrical or pleated replaceable elements, typically constructed from cellulose, synthetic fibers, or composite media with MERV ratings from 6 to 16 and operating face velocities between 500 and 2500 fpm, designed to remove particulate contaminants from airstreams in enclosed mechanical systems. HEPA-grade cartridges command premium positioning in pharmaceutical and semiconductor cleanrooms where 99.97% efficiency at 0.3 microns represents a non-negotiable specification. Paper-based cartridges occupy mature volume pools in automotive engine intake applications, while activated carbon configurations are gaining fastest in cabin air and industrial vapor recovery segments where molecular contamination control adds incremental value.
EPA NESHAP standards for maximum achievable control technology constrain industrial cartridge specifications in US metalworking and chemical processing facilities. Ecodesign requirements under the EU Green Deal mandate minimum filtration efficiencies and pressure drop thresholds for commercial building ventilation products. China's GB/T 14295 standard governs air filter performance classifications in HVAC applications. Stakeholders must monitor divergence between regional test protocols—ASHRAE 52.2, EN 779, and GB/T methodologies produce non-comparable efficiency ratings that complicate product platform standardization across multinational supply chains.
Market Dynamics
Nanofiber media from melt-blown electret processes is compressing replacement cycles and reconfiguring supply chains as pharmaceutical cleanrooms and semiconductor fabs demand higher efficiency at lower pressure drops.
Growth Catalysts
- EU GMP Annex 1 Revisions:Pharmaceutical cleanrooms in Germany are expanding cartridge replacement schedules, creating pull for HEPA-grade configurations with validated 99.97% efficiency at 0.3 microns.
- Semiconductor Clustering:China's Yangtze River Delta manufacturing corridor is concentrating demand as new fabs and EV battery plants specify nanofiber media for sub-micron contamination control.
- F-Gas Regulation Phase-Down:Commercial HVAC retrofits across Europe are rebalancing demand toward lower-pressure-drop cartridge designs that reduce fan energy consumption.
Market Restraints
- Raw Material Concentration:Polypropylene resin supply for melt-blown electret processes concentrates in petrochemical corridors, exposing converters to feedstock volatility.
- Test Protocol Divergence:ASHRAE 52.2, EN 779, and GB/T methodologies produce non-comparable efficiency ratings that complicate product platform standardization across multinational supply chains.
- Glass Microfiber Legacy:Traditional high-efficiency media retains entrenched qualification status in aerospace and nuclear applications where recertification timelines stretch 18-36 months.
Strategic Opportunities
- Data Center Cooling Integration:Filtration-electrical system convergence is opening architecture-specification channels where Eaton Corporation and similar integrators capture bundled procurement decisions.
- Industrial Vapor Recovery:Activated carbon configurations are gaining traction in chemical processing segments where EPA NESHAP standards for maximum achievable control technology mandate molecular contamination control.
- Membrane Technology Specialization:Specialized membrane technologies for industrial dust collection represent white space for technical differentiation in metalworking and mineral processing verticals.
Industry Challenges
- Certification Timeline Compression:EU Ecodesign requirements under the Green Deal mandate simultaneous compliance with minimum filtration efficiencies and pressure drop thresholds, stretching R&D validation resources.
- Legacy System Integration:Retrofit installations in commercial building ventilation must accommodate existing plenum dimensions and face velocities between 500-2500 fpm, constraining media innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Filter Cartridges Market |
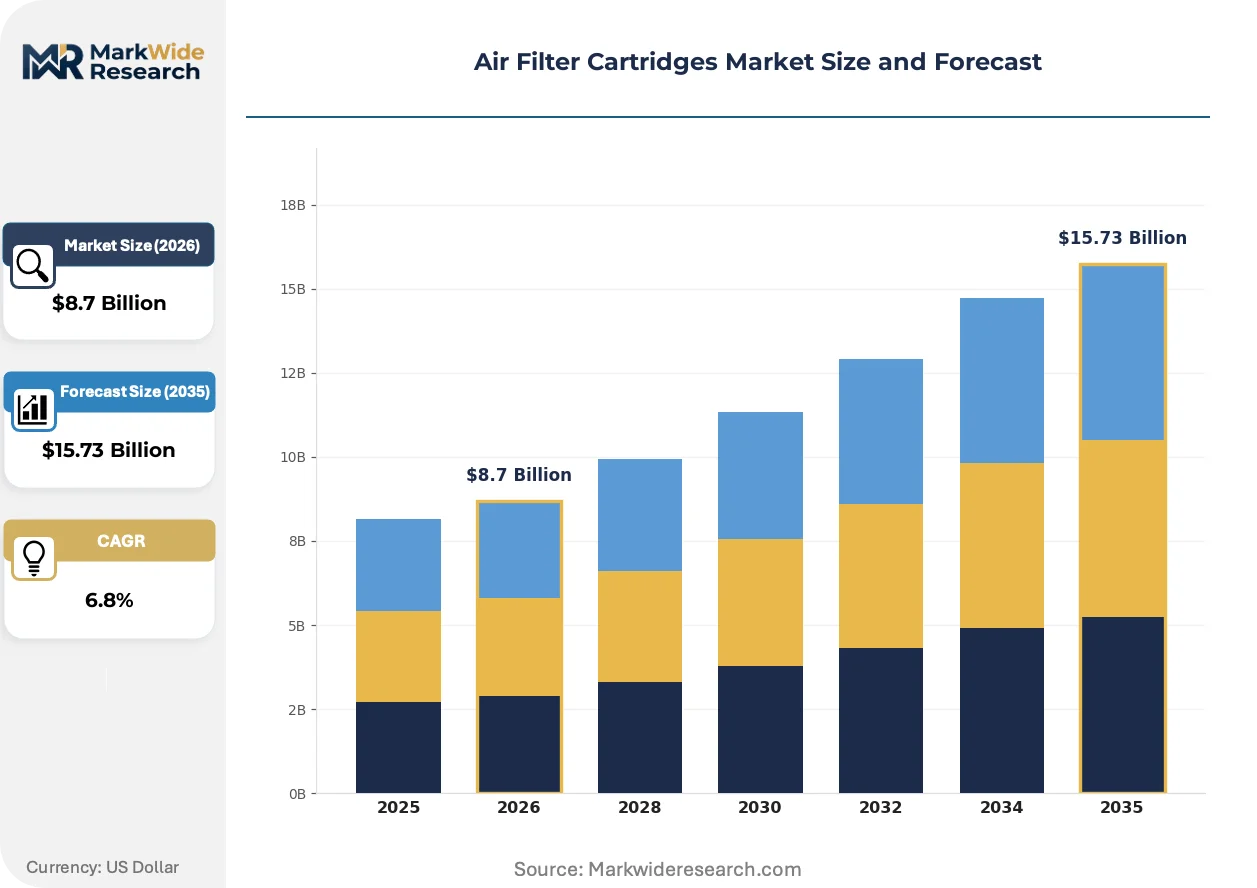
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Foam, Paper End User: Automotive, Industrial Equipment, HVAC Systems, Marine Application: Air Purification, Fuel Filtration, Cabin Filters, Engine Intake Technology: Electrostatic, Mechanical, Chemical, Thermal |
| Companies Covered | MANN + HUMMEL Group, Eaton Corporation, Donaldson Company, Inc., Sogefi Group, 3M, Parker Hannifin Corporation, Pall Corporation, Johnson Controls, Inc., Camfil Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Filter Cartridges Market Emerging Trajectories
Material science advances and regulatory stringency are converging to compress product lifecycles and reward specialized membrane capabilities over commodity cellulose offerings.
Melt-blown electret nanofiber media is overtaking traditional glass microfiber in high-efficiency grades by delivering comparable arrestance at 40% lower pressure drop. Semiconductor fabs in Taiwan and Germany are specifying these configurations for sub-0.3-micron particle capture. The technology is overtaking incumbent supply relationships as OEMs requalify cartridge platforms around energy efficiency metrics rather than legacy efficiency ratings alone.
EPA NESHAP standards for maximum achievable control technology are tightening particulate emission limits in US metalworking and chemical processing facilities. Industrial end-users must upgrade dust collection systems to cartridge configurations meeting 99.9% collection efficiency on 0.5-micron particles. Metal fabrication shops in Ohio and Texas are responding by consolidating supplier bases around vendors with validated membrane technologies and in-house testing capabilities.
Specification decisions are migrating from facilities maintenance to sustainability procurement offices as CSRD disclosure requirements elevate filtration energy consumption into Scope 2 reporting. Corporate buyers are unbundling cartridge supply from OEM equipment contracts to negotiate direct media supply agreements. This pattern is most visible in German pharmaceutical manufacturing where EU GMP Annex 1 compliance documentation now requires traceable media provenance and batch-level performance validation.
Air Filter Cartridges Market Segmentation
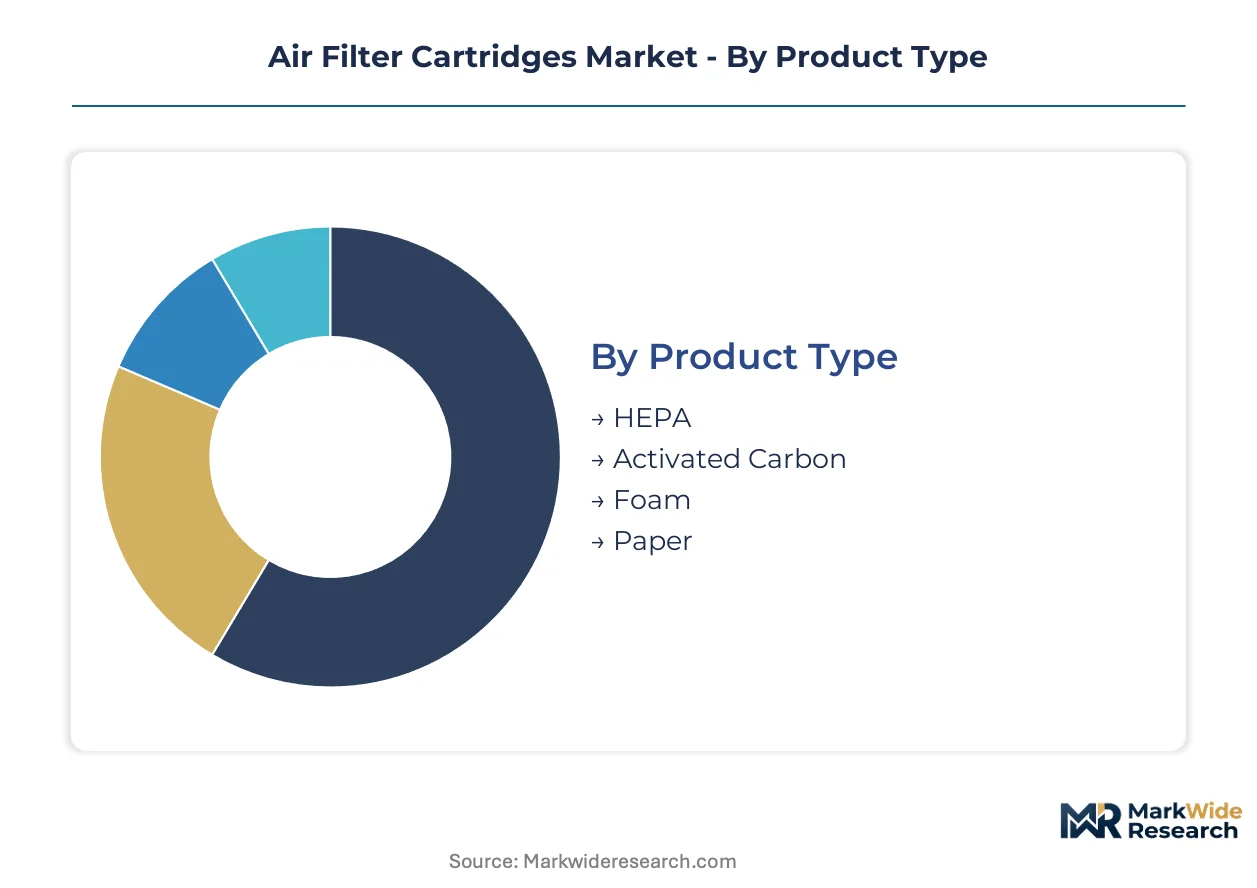
Air filter cartridge specifications fragment sharply across contamination control requirements, with pharmaceutical cleanrooms, semiconductor fabs, and automotive OEMs each demanding validated performance envelopes that resist platform standardization. Segmentation discipline separates commodity volume pools from premium replacement cycles governed by regulatory recertification timelines.
Product Type:
Customization intensity spans validated HEPA configurations with batch-level traceability against standardized foam inserts for consumer appliances.
- HEPA:Pleated glass microfiber or nanofiber media delivering 99.97% efficiency at 0.3 microns, mandatory for pharmaceutical cleanrooms in Germany under EU GMP Annex 1 revisions. Demand concentrates in Taiwan's semiconductor corridor where sub-micron contamination control commands premium positioning.
- Activated Carbon:Impregnated carbon pellets or bonded fiber matrices adsorbing molecular contaminants, specified for cabin air and industrial vapor recovery where EPA NESHAP standards mandate emission control. Automotive OEMs in Stuttgart and Detroit are expanding specifications for volatile organic compound capture.
- Foam:Open-cell polyurethane or reticulated polyester structures for coarse particulate pre-filtration in consumer appliances and marine engine intakes.
- Paper:Cellulose-based pleated media with resin binders occupying mature automotive engine intake volumes where cost efficiency dominates specification.
Leading the category by volume: Paper. Growing fastest: Activated Carbon.
End User:
Cost tier stratification separates aftermarket replacement velocity from OEM specification lock-in across industrial and mobility applications.
- Automotive:Engine intake and cabin air configurations with OEM-specified media grades, replacement cycles tied to vehicle service intervals. China's EV battery plants are specifying nanofiber media for manufacturing environment control.
- Industrial Equipment:Dust collection and process air systems where EPA NESHAP standards constrain metalworking facilities in Ohio and Texas to 99.9% collection efficiency on 0.5-micron particles.
- HVAC Systems:Commercial building ventilation cartridges governed by EU Ecodesign minimum efficiency thresholds and pressure drop mandates under the Green Deal.
- Marine:Salt-resistant configurations for engine intake and accommodation ventilation, specifications driven by classification society rules for corrosion resistance.
Volume leader: Automotive. Steepest expansion trajectory: Industrial Equipment.
Application:
Application design rules diverge between particulate arrestance metrics and molecular contamination control, with certification protocols fragmenting procurement.
- Air Purification:HEPA and activated carbon combinations for cleanroom and healthcare environments, efficiency validation requiring ASHRAE 52.2 or EN 779 test protocol compliance. German pharmaceutical manufacturers are unbundling cartridge supply from OEM contracts to negotiate direct media agreements.
- Fuel Filtration:Water separation and particulate control for diesel and aviation fuel systems, specifications governed by engine manufacturer warranty requirements.
- Cabin Filters:Combined particulate and activated carbon configurations for passenger vehicle interior air quality, replacement cycles accelerating with consumer awareness of filtration performance.
- Engine Intake:Cellulose and synthetic media protecting turbocharger and combustion components, cost-optimized specifications dominating aftermarket channels.
Dominant by replacement frequency: Engine Intake. Climbing the fastest: Air Purification.
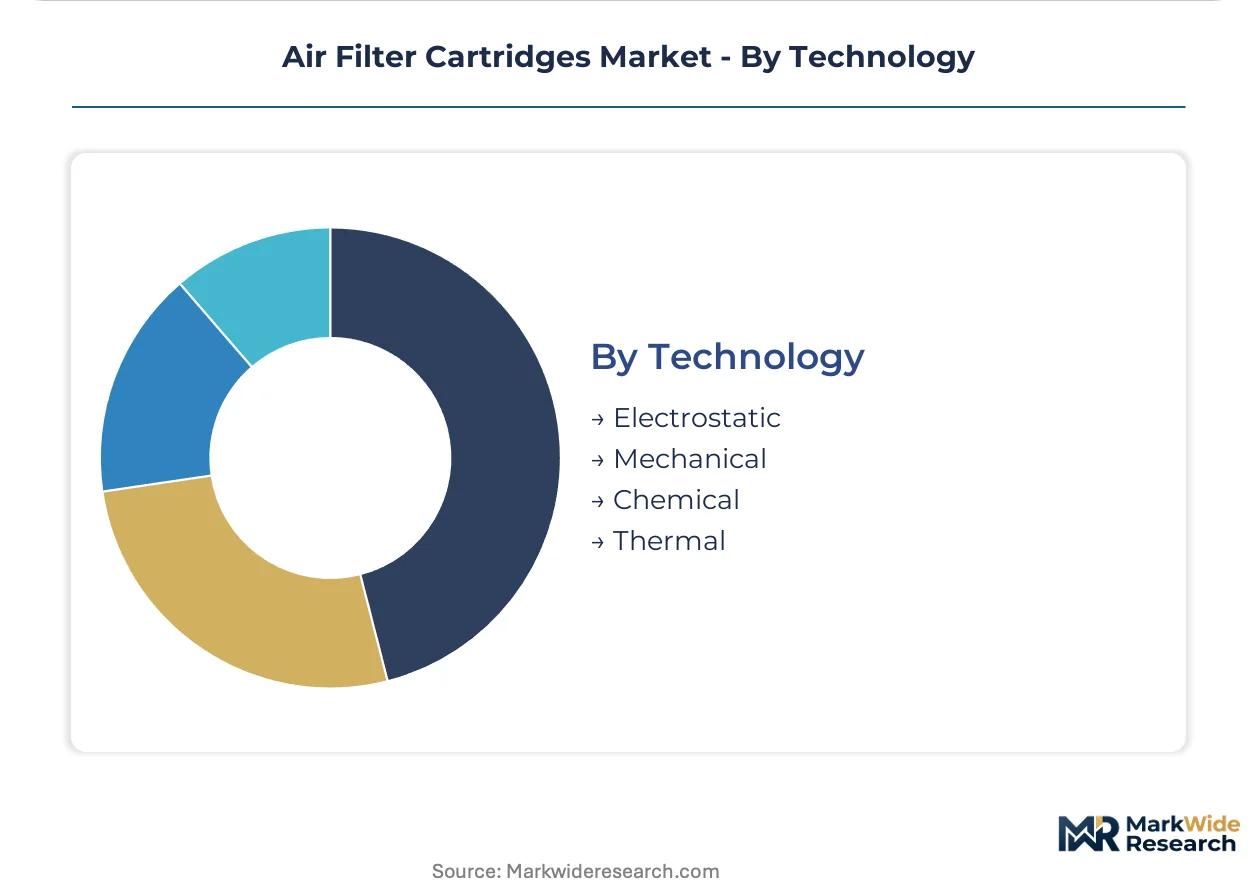
Technology:
Technology selection traces the efficiency-pressure drop frontier, with electret processes displacing legacy mechanical capture in high-performance grades.
- Electrostatic:Melt-blown electret nanofiber media delivering sub-micron capture at 40% lower pressure drop than mechanical alternatives, overtaking glass microfiber in semiconductor fab specifications across Taiwan and Germany.
- Mechanical:Depth filtration through cellulose, synthetic, or glass fiber matrices, retaining entrenched qualification in aerospace and nuclear applications where recertification timelines stretch 18-36 months.
- Chemical:Activated carbon and impregnated media for molecular contamination control, gaining traction in EPA-regulated industrial vapor recovery segments.
- Thermal:High-temperature resistant ceramic or metal fiber configurations for exhaust and process gas applications exceeding 500°F operational limits.
Installed base leader: Mechanical. Gaining share fastest: Electrostatic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridor concentrates the most intensive demand expansion as semiconductor fabs and EV battery plants cluster across Shanghai, Suzhou, and Wuxi.
United States
Metal fabrication shops in Ohio and Texas drive industrial dust collection upgrades under EPA NESHAP standards for maximum achievable control technology. The EPA mandates 99.9% collection efficiency on 0.5-micron particles for metalworking facilities. Houston's petrochemical corridor concentrates demand for activated carbon configurations in vapor recovery applications.
Germany
Pharmaceutical cleanrooms in Stuttgart and Frankfurt expand cartridge replacement schedules following EU GMP Annex 1 revisions. The EU Green Deal Ecodesign requirements impose simultaneous minimum filtration efficiencies and pressure drop thresholds. Mannheim's automotive engineering cluster specifies nanofiber media for EV battery manufacturing environment control.
China
Semiconductor fabs in Wuxi and Hefei specify melt-blown electret nanofiber media for sub-0.3-micron particle capture. GB/T 14295 standard governs air filter performance classifications in HVAC applications. Shenzhen's electronics manufacturing corridor concentrates procurement decisions for data center cooling architectures.
Japan
Precision equipment manufacturers in Nagoya and Osaka demand HEPA-grade configurations with validated batch-level traceability. METI efficiency standards accelerate replacement cycles in commercial building ventilation. Kyushu's semiconductor materials cluster qualifies new media technologies through extended field validation protocols.
South Korea
Memory chip fabs in Hwaseong and Pyeongtaek drive specifications for lower-pressure-drop cartridge designs to reduce cleanroom energy intensity. MFDS pharmaceutical manufacturing guidelines align with EU GMP Annex 1 efficiency benchmarks. Seoul Capital Area data centers bundle filtration-electrical system procurement for cooling infrastructure.
Air Filter Cartridges Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive media production capabilities. Market concentration remains moderate as specialized membrane technology providers defend niche positions in pharmaceutical and semiconductor verticals. Three archetypes dominate: vertically integrated filtration-electrical system integrators, nonwoven media producers with backward integration into resin supply, and membrane technology specialists focused on industrial dust collection. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified supply positions in clustered manufacturing corridors.
Among diversified industrial conglomerates, MANN + HUMMEL Group and Eaton Corporation occupy positions spanning automotive OEM specification and data center infrastructure integration. Donaldson Company, Inc. exemplifies the membrane technology specialist archetype with concentrated presence in industrial dust collection verticals. These three entities represent distinct strategic postures: captive nonwoven media production, filtration-electrical system convergence, and specialized membrane capabilities respectively.
| Leading Market Players |
|---|
| MANN + HUMMEL Group |
| Eaton Corporation |
| Donaldson Company, Inc. |
| Sogefi Group |
| 3M |
| Parker Hannifin Corporation |
| Pall Corporation |
| Johnson Controls, Inc. |
| Camfil Group |
| Others |
Supply Flow & Price Mechanics
Melt-blown electret nanofiber production lines are compressing unit economics while concentrating supply leverage among resin-integrated converters, simultaneously lowering per-cartridge manufacturing costs and tightening feedstock control around Yangtze River Delta petrochemical corridors.
Pricing Analysis
Yield-based pricing anchors HEPA-grade cartridge contracts in pharmaceutical cleanrooms, where validated 99.97% efficiency at 0.3 microns commands premium positioning against commodity cellulose alternatives. Three-tier pricing structure across premium, standard, and economy levels separates validated batch-traceable configurations from unqualified imports, with certification grade and volume scale driving differentiation. Cost compression in standard-grade HVAC cartridges is intensifying because polypropylene resin volatility transmits directly to converter margins. Aftermarket automotive channels exhibit highest price sensitivity, while semiconductor fabs prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Polypropylene resin supply for melt-blown electret processes rests on petrochemical production clusters in China, South Korea, and Saudi Arabia, with specialty-grade electret additives sourcing predominantly from Japanese and German chemical producers. Spunbond substrate, nanofiber coating equipment, and pleating machinery constitute critical component dependencies. Single-source vulnerability concentrates in electret charge stability additives, where two specialty chemical producers dominate qualified supply. Distribution runs through OEM equipment bundling for industrial verticals, direct media supply agreements for pharmaceutical accounts, and aftermarket distributor networks for automotive replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air filter cartridges market is executing a technology-transition phase as melt-blown electret nanofiber media displaces glass microfiber in high-efficiency grades, rewarding converters with captive resin supply and validated membrane capabilities.
For Market Incumbents: Hedge against feedstock volatility by securing long-term polypropylene offtake agreements with Yangtze River Delta petrochemical producers, while accelerating in-house production of electret charge stability additives to reduce Japanese supplier dependency. Invest in batch-level traceability systems to defend pharmaceutical specification lock-in against emerging membrane specialists. For New Entrants and Emerging Players: EU GMP Annex 1 revisions in Germany open a window for specialized HEPA cartridge producers with validated documentation capabilities, targeting Stuttgart and Frankfurt pharmaceutical cleanrooms where incumbent qualification timelines create procurement friction. EPA NESHAP standards in US metalworking verticals present a secondary entry point through membrane technology specialization for dust collection upgrades. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking filtration-electrical system integration capabilities, with membrane technology specialists commanding premium multiples in semiconductor and pharmaceutical verticals. Watch for inflection in direct media supply agreement prevalence as corporate sustainability procurement offices unbundle cartridge sourcing from OEM equipment contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene feedstock insulates converters from petrochemical price volatility in Yangtze River Delta. |
| Membrane Technology Specialization | Validated sub-micron capture capabilities differentiate suppliers for EPA NESHAP-compliant metalworking facilities in Ohio. |
| Batch-Level Traceability Investment | EU GMP Annex 1 documentation requirements in German pharmaceutical cleanrooms mandate provenance tracking systems. |
| Filtration-Electrical System Integration | Eaton Corporation's bundled procurement model captures data center cooling architecture specifications in Seoul Capital Area. |
| Direct Media Supply Agreements | CSRD disclosure requirements elevate filtration energy consumption into Scope 2 reporting, unbundling cartridge procurement from OEM contracts. |
Methodological Framework
Multi-period observation of cartridge replacement cycle compression, nanofiber media penetration rates, and regulatory recertification timelines anchored the trend analysis, supplemented by interviews with plant engineers at semiconductor fabs, pharmaceutical manufacturing directors, HVAC procurement leads, and aftermarket distribution channel heads. Secondary validation drew from EPA NESHAP enforcement data, EU Ecodesign implementation reports, GB/T 14295 standard revisions, and customs trade records for polypropylene resin and nonwoven media. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting across product type, end user, application, and technology dimensions structured the analytical framework, with technology transition velocity and regional regulatory clustering as additional modeled variables. CAGRs derived from fitted growth curves against historical replacement cycle data and projected cleanroom expansion schedules. Forecast inputs incorporated semiconductor fab buildout pipelines in Taiwan and China, EV battery plant contamination control specifications, and commercial HVAC retrofit velocities under F-Gas Regulation phase-down schedules.
The model assumes a particular technology adoption path; alternative pathways for electret nanofiber media qualification timelines in aerospace and nuclear applications would alter the outlook. Forecasts reflect assumptions about resin supply stability, regulatory enforcement consistency, and test protocol harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
South America Gear Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Europe Roll Forming Body in White Market