
 Traffic Control Products Market | 2026-2036
Traffic Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Control Products Market Analytics
The gap between premium intelligent traffic systems and commodity signage hardware is repositioning procurement dynamics across the sector. 3M leverages its materials science heritage to dominate reflective sheeting and high-visibility road markings. Siemens AG anchors its position through deep integration of traffic management software with urban rail and transit ecosystems. Kapsch TrafficCom competes on end-to-end tolling and free-flow intersection platforms across European and North American deployments.
Traffic control products encompass signal heads, pavement markings, channelization devices, and intelligent transportation hardware engineered to regulate vehicle and pedestrian flow, typically manufactured from aluminum alloys, polycarbonate lenses, retroreflective sheeting, and embedded sensor arrays. The product category spans traffic signals, road barriers, cones, and speed bumps, with smart signal systems capturing expanding margin pools as cities prioritize real-time adaptive control, while LED displays sustain volume leadership due to energy efficiency mandates and universal retrofit compatibility. Municipalities and government agencies represent the dominant end-user channel, though construction firms are gaining procurement share for temporary work-zone configurations.
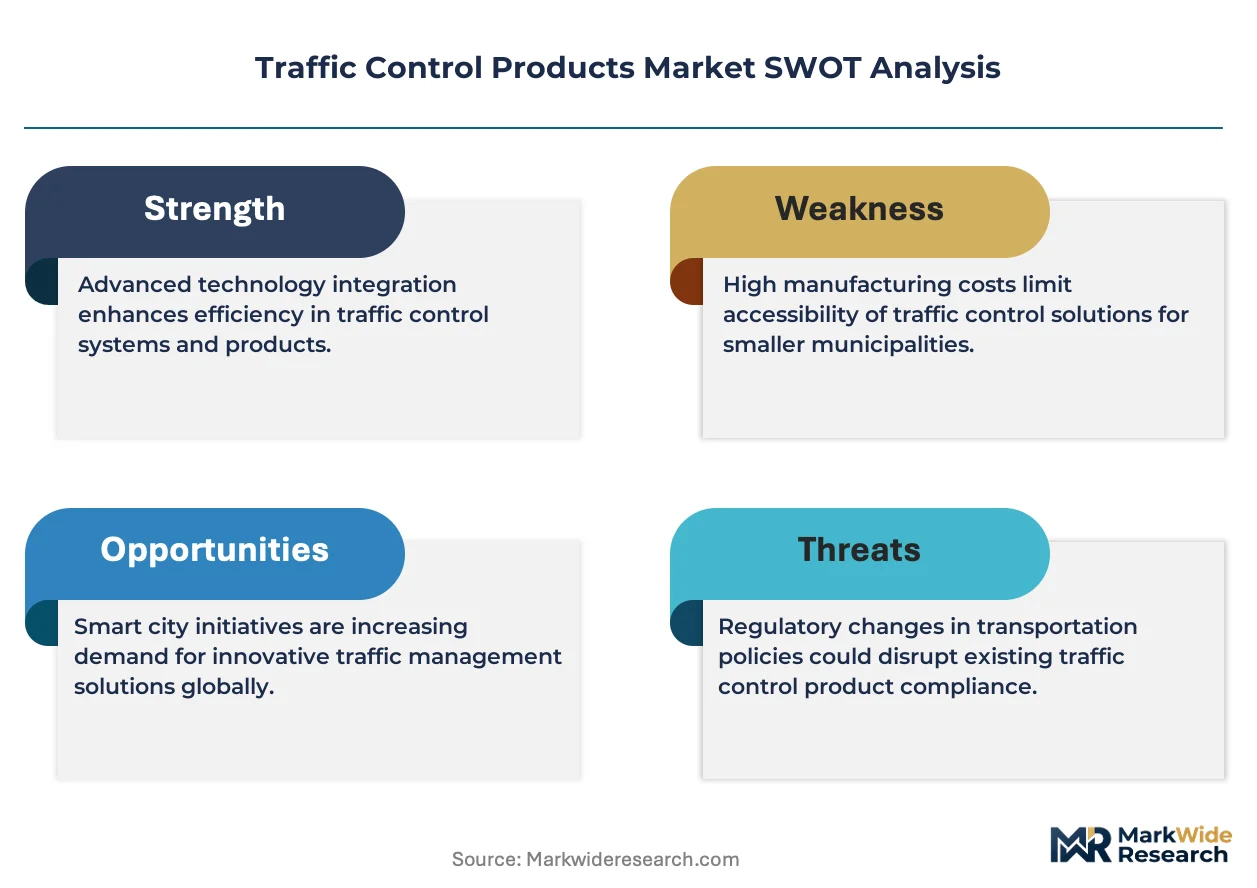
FHWA's Manual on Uniform Traffic Control Devices (MUTCD), the EU's CE marking framework for roadside equipment, and ISO 14819 traffic and traveler information standards collectively define product compliance thresholds and cross-border market access conditions. These frameworks compel manufacturers to certify durability, photometric performance, and electromagnetic compatibility before public agency eligibility. Stakeholders must weigh the capital intensity of smart system transitions against the operational savings from predictive maintenance and reduced intersection congestion.
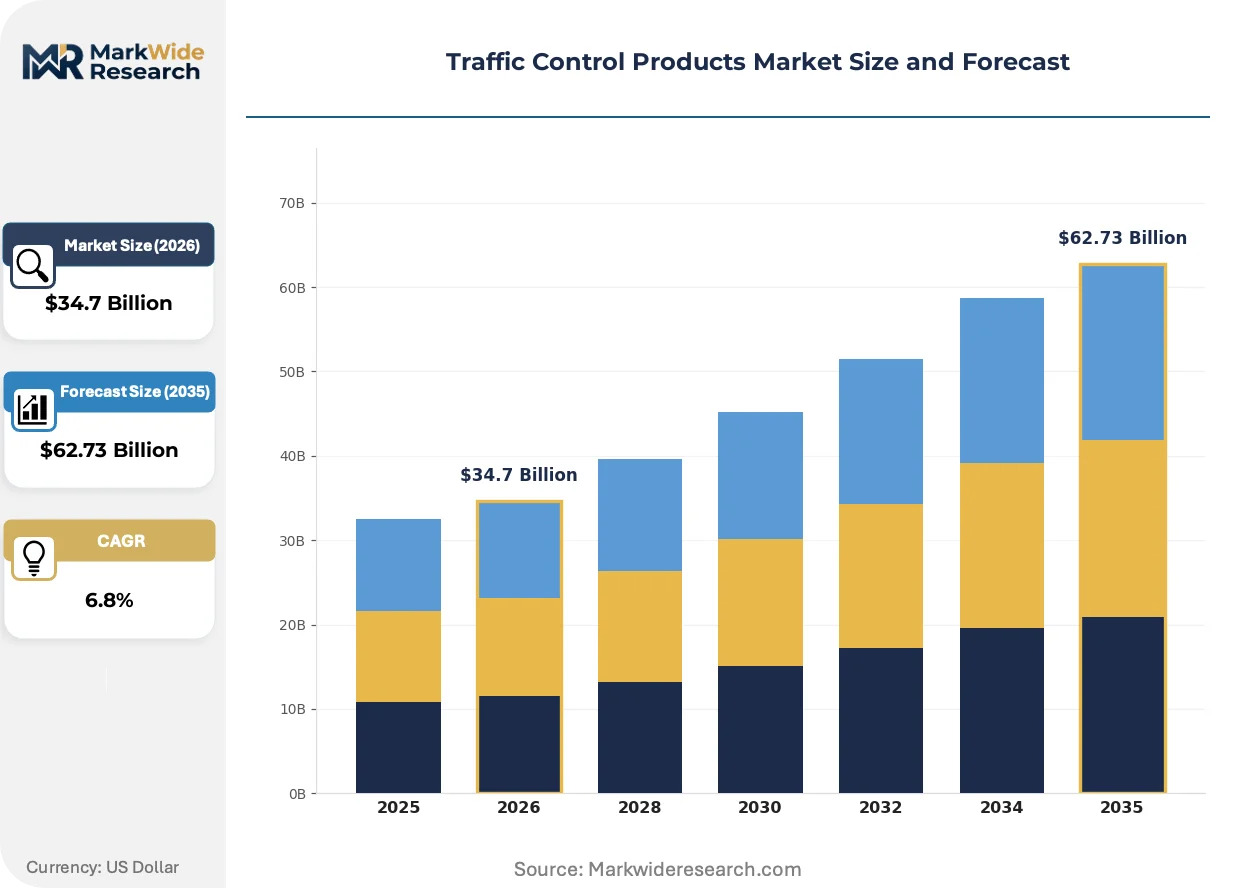
Market Dynamics
The transition from static traffic infrastructure to adaptive, sensor-driven intersection management is compressing replacement cycles and elevating software-embedded hardware procurement criteria for municipal agencies.
Growth Catalysts
- FHWA MUTCD 11th Edition:The updated federal guidelines mandate enhanced retroreflectivity standards and pedestrian signal head upgrades, forcing systematic infrastructure refresh cycles across US state DOTs.
- Polycarbonate lens arrays:Advanced optical-grade polymers with embedded LED matrices enable modular signal head replacement without full pole reconstruction, reducing labor costs for urban maintenance crews.
- German federal highway investment:The Bundesfernstraßengesetz framework prioritizes connected corridor pilot zones, channeling procurement toward V2X-enabled signal controllers and edge-computing roadside units.
Market Restraints
- Aluminum alloy price volatility:Signal mast arm and pole fabrication faces input cost pressure from London Metal Exchange pricing swings, squeezing margin on standardized hardware contracts.
- Retroreflective sheeting supply concentration:Glass bead and microprismatic substrate production clusters in East Asian chemical processing zones, creating single-source vulnerability for North American signage manufacturers.
- Legacy electromechanical signal compatibility:Decades-old NEMA TS2 cabinet standards limit seamless integration with IP-based adaptive systems, forcing parallel maintenance of analog and digital control networks.
Strategic Opportunities
- India National Highway expansion:The Bharatmala Pariyojana program's phase-II corridor development creates first-mover positioning for intelligent tolling and lane management system providers in underpenetrated secondary cities.
- EU Green Deal procurement mandates:Public agency tender specifications increasingly weight lifecycle carbon metrics, advantaging LED signal retrofit specialists and solar-powered temporary work-zone device manufacturers.
- LiDAR-camera fusion:Converging optical sensing technologies enable pedestrian-bicycle-vehicle trajectory prediction without inductive loop installation, opening retrofit markets for existing signalized intersections.
Industry Challenges
- Embedded systems firmware engineering:Municipal agencies lack in-house expertise to configure adaptive signal timing algorithms, forcing extended vendor dependency for optimization and troubleshooting.
- ISO 14819 certification timelines:Multi-quarter electromagnetic compatibility and photometric testing protocols delay product launches for traveler information display manufacturers targeting European deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Control Products Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Signals, Road Barriers, Cones, Speed Bumps Application: Urban Planning, Highway Management, Construction Zones, School Areas End User: Government Agencies, Construction Firms, Event Organizers, Municipalities Technology: Solar-Powered Devices, Smart Signal Systems, Manual Controls, LED Displays |
| Companies Covered | Siemens AG, 3M, Swarco, Kapsch TrafficCom, Q-Free, Econolite, Johnson Controls, Cubic Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Control Products Market Evolving Landscape
Edge computing architectures and real-time traffic data fusion are displacing centralized traffic management centers, distributing computational load to intersection-level processors and compressing system response latency.
Multi-sensor fusion arrays combining radar, thermal imaging, and acoustic detection are integrating pedestrian and cyclist recognition into adaptive signal phase allocation. Dutch municipal agencies in Rotterdam and Utrecht deploy these systems at high-conflict intersections, reducing clearance interval waste while maintaining safety compliance. The technology is integrating formerly separate vehicle detection and vulnerable road user monitoring into unified hardware platforms, consolidating supplier relationships.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free LED thermal management designs for signal heads in extreme climate zones. Manufacturers must redesign heat dissipation architectures without conventional cooling systems, elevating aluminum casting and thermal interface material specifications. Nordic transport authorities in Sweden and Finland drive adoption timelines due to extended sub-zero operational requirements.
Performance-based maintenance contracts are displacing traditional capital purchase models for intelligent intersection systems. State DOTs in Texas and Florida now specify uptime guarantees and congestion reduction metrics rather than equipment procurement, transferring operational risk to integrators. This reconfiguration concentrates vendor selection on software analytics capabilities and predictive diagnostic platforms rather than hardware durability alone.
Traffic Control Products Market Segmentation
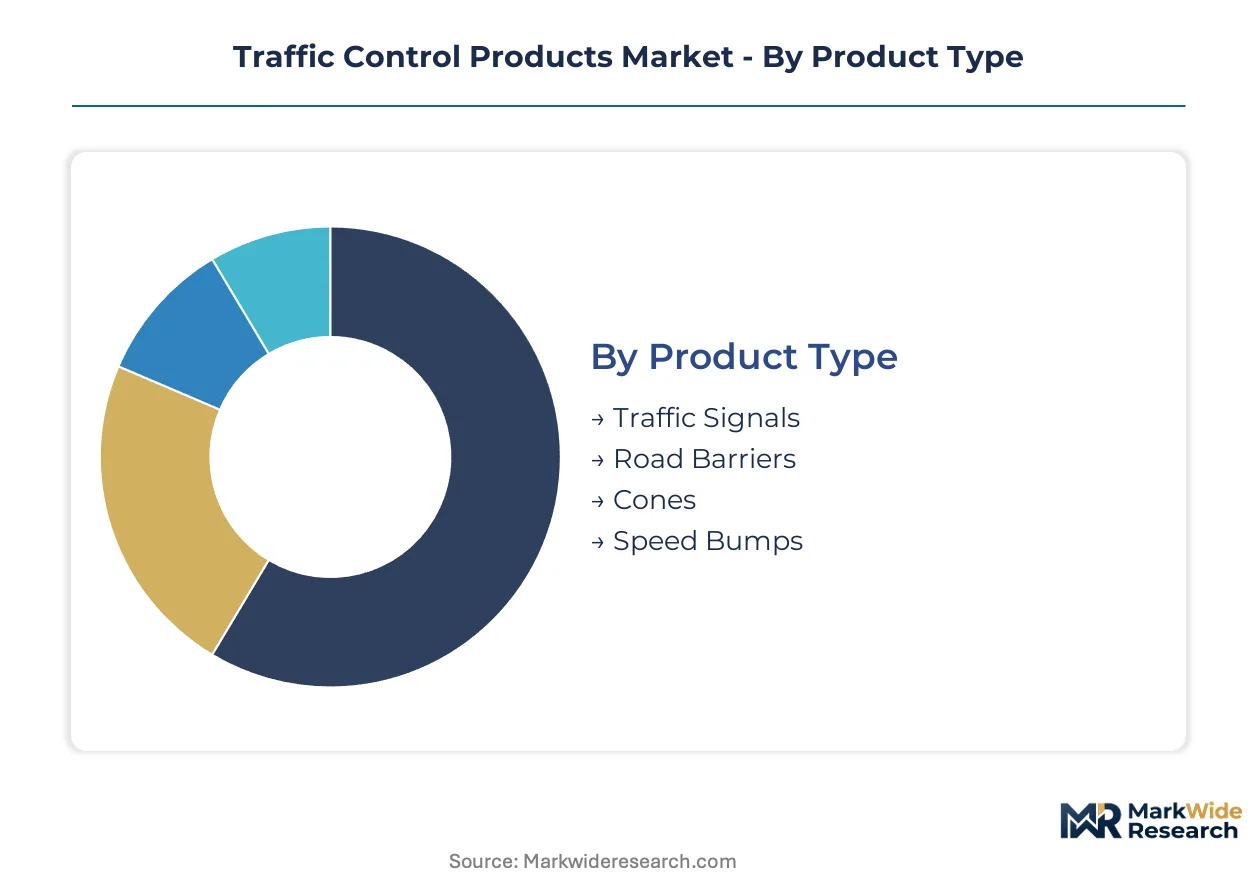
Traffic control products span functional hardware and embedded intelligence systems with divergent margin profiles and procurement cycles. Understanding segment boundaries clarifies where capital investment concentrates versus where commodity replacement dominates.
Product Type:
Standardization pressures from federal highway specifications clash with rising demand for adaptive, sensor-integrated configurations across this category.
- Traffic Signals:Aluminum alloy mast arms support polycarbonate lens housings with embedded LED matrices. Municipalities in Germany prioritize V2X-enabled adaptive controllers under federal highway investment frameworks, compressing replacement cycles for legacy electromechanical cabinets.
- Road Barriers:Steel-reinforced polymer or concrete channelization devices engineered for high-speed impact absorption. Highway management agencies in Texas and Florida specify these for work-zone configurations, with procurement shifting toward performance-based uptime contracts rather than capital purchase.
- Cones:Flexible PVC or rubber-base temporary delineators with retroreflective collars.
- Speed Bumps:Molded rubber or asphalt-composite vertical deflection elements.
Leading the category by volume: Traffic Signals. Growing fastest: Road Barriers.
Application:
Procurement authority fragmentation shapes demand patterns across deployment contexts, with permanent infrastructure contrasting sharply with temporary mobilization requirements.
- Urban Planning:Integrated corridor management encompassing signal coordination, pedestrian priority phasing, and multimodal intersection design. Rotterdam and Utrecht municipal agencies deploy multi-sensor fusion arrays for cyclist-vehicle conflict reduction, consolidating detection hardware procurement.
- Highway Management:Long-distance corridor control including variable message signing, lane control signals, and incident detection networks. India's Bharatmala Pariyojana phase-II development creates deployment opportunities for intelligent tolling and lane management in secondary cities.
- Construction Zones:Temporary work-zone protection systems including portable changeable message signs and truck-mounted attenuators.
- School Areas:Reduced-speed zone enforcement with flashing beacon systems and high-visibility crosswalk markings.
Highest procurement concentration: Urban Planning. Steepest expansion trajectory: Highway Management.
End User:
Budget cycle alignment and technical capability gaps differentiate procurement behavior between institutional buyers and mobilization-focused contractors.
- Government Agencies:State DOTs and federal highway administrations with multi-year capital programs and compliance mandates. FHWA MUTCD 11th Edition retroreflectivity standards force systematic infrastructure refresh cycles across US state departments of transportation.
- Construction Firms:Project-based temporary traffic control procurement for work-zone safety compliance. These entities gain procurement share as performance-based maintenance contracts displace traditional equipment purchase models.
- Event Organizers:Short-duration crowd and vehicle flow management for sporting venues and festivals.
- Municipalities:City-level street departments with constrained maintenance budgets and legacy system interoperability challenges.
Dominant procurement volume: Government Agencies. Gaining share fastest: Construction Firms.
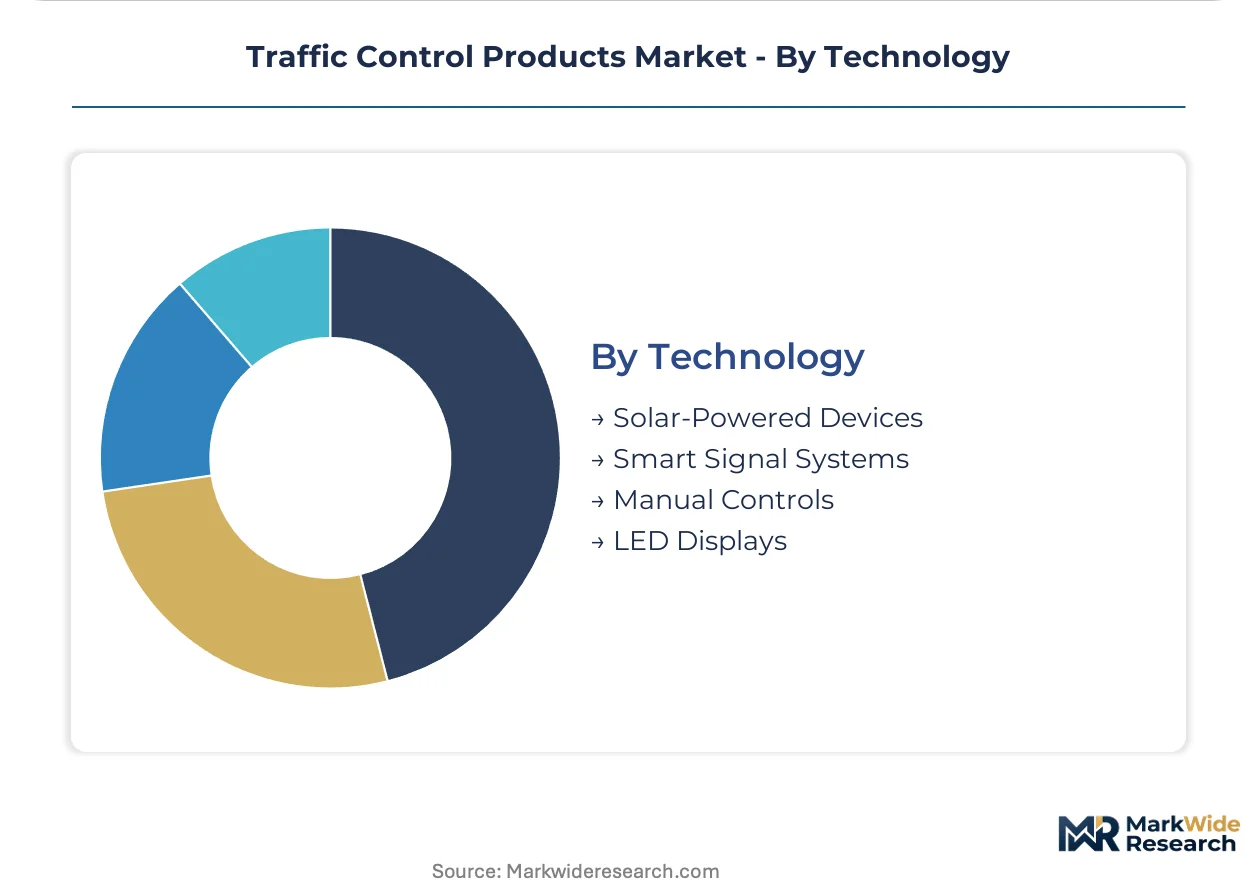
Technology:
Energy sourcing and connectivity architecture separate legacy hardware from next-generation platform investments in this category.
- Smart Signal Systems:Edge-computing intersection controllers with real-time data fusion and adaptive phase optimization. Dutch deployments in Rotterdam demonstrate pedestrian-bicycle-vehicle trajectory prediction capabilities, consolidating formerly separate detection systems into unified hardware platforms.
- LED Displays:Solid-state illumination for signal heads and changeable message signs with extended operational life. EU Green Deal procurement mandates weight lifecycle carbon metrics, advantaging retrofit specialists in this segment.
- Solar-Powered Devices:Photovoltaic-equipped temporary work-zone equipment and remote intersection signals.
- Manual Controls:Push-button pedestrian actuation and time-of-day fixed timing plans for low-volume intersections.
Highest installed base: LED Displays. Climbing the fastest: Smart Signal Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European deployment of multi-sensor fusion arrays for cyclist-vehicle conflict reduction, while German federal highway investment channels procurement toward V2X-enabled corridors. Municipal agencies in Texas and Florida now specify performance-based uptime contracts rather than capital purchase models.
United States
State DOTs in Texas and Florida drive demand through performance-based maintenance contracts with uptime guarantees. FHWA MUTCD 11th Edition mandates enhanced retroreflectivity standards and pedestrian signal head upgrades. The Southeast corridor concentrates deployment of intelligent intersection systems with edge-computing roadside units.
Germany
Federal highway investment under the Bundesfernstraßengesetz framework prioritizes connected corridor pilot zones. KBA certification requirements shape V2X-enabled signal controller procurement criteria. The Rhine-Ruhr metropolitan region hosts dense deployments of adaptive signal networks and multimodal intersection management platforms.
India
The Bharatmala Pariyojana program's phase-II corridor development creates demand for intelligent tolling and lane management in secondary cities. BIS standards govern roadside equipment certification for national highway expansion. Maharashtra and Gujarat concentrate procurement activity for first-mover positioning in underpenetrated urban corridors.
Netherlands
Rotterdam and Utrecht municipal agencies deploy multi-sensor fusion arrays reducing clearance interval waste while maintaining safety compliance. EU Green Deal procurement mandates weight lifecycle carbon metrics in tender specifications. The Randstad conurbation leads integration of pedestrian-bicycle-vehicle trajectory prediction into unified hardware platforms.
Traffic Control Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-embedded hardware and materials science dimensions. The vendor base stratifies between integrated traffic management platforms, reflective materials specialists, and end-to-end tolling system providers. Three archetypes dominate: diversified industrial conglomerates with urban rail integration capabilities, materials science heritage firms commanding retroreflective substrates, and dedicated intelligent transportation system pure-plays. Competitive moves concentrate on strategic partnerships for edge-computing architectures and portfolio diversification into predictive maintenance service layers.
Within the diversified industrial tier, Siemens AG and Thales Group exemplify platform integration strategies spanning traffic management software with broader urban mobility ecosystems. 3M occupies a position reflecting materials science heritage in retroreflective sheeting and high-visibility road markings. Kapsch TrafficCom sits within the dedicated intelligent transportation pure-play archetype, anchoring end-to-end tolling and free-flow intersection deployment expertise across European and North American markets.
| Leading Market Players |
|---|
| Siemens AG |
| 3M |
| Swarco |
| Kapsch TrafficCom |
| Q-Free |
| Econolite |
| Johnson Controls |
| Cubic Corporation |
| Thales Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in signal head fabrication and retroreflective substrate production anchor supply behavior through conservative capacity expansion and long-term municipal contract pricing discipline. Their ownership structure limits access to growth capital for vertical integration, compressing margin recovery when aluminum alloy or polycarbonate resin costs spike.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for intelligent intersection systems, with Texas and Florida DOTs specifying congestion reduction metrics rather than equipment procurement. Three-tier pricing structure across premium adaptive controllers, standard LED retrofits, and commodity signage hardware reflects certification grade and software analytics bundling. Pricing pressure stems from aluminum alloy volatility on London Metal Exchange, squeezing standardized hardware contracts. Construction firms exhibit highest price sensitivity due to project-based temporary work-zone procurement, while government agencies absorb premium pricing for compliance-mandated MUTCD upgrades.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China coordinate hub-and-spoke patterns for signal mast arms and polycarbonate lens arrays. Manufacturing concentrates in Germany for V2X-enabled controllers, China for LED matrix components, and the United States for aluminum alloy pole fabrication. Raw material dependencies include aluminum alloys, optical-grade polycarbonate resins, and microprismatic retroreflective substrates. Single-source vulnerability in East Asian glass bead and microprismatic substrate production elevates supply chain risk. Distribution runs through municipal procurement portals and construction firm rental networks for temporary devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microprismatic sheeting production capacity constraints in East Asian chemical processing zones prop pricing discipline for retroreflective substrates, limiting margin compression for integrated manufacturers.
For Market Incumbents: Extend software analytics capabilities into predictive maintenance service layers to capture performance-based contract expansion in Texas and Florida. Deepen backward integration into aluminum alloy sourcing through captive supply agreements with German and US smelters to defend against London Metal Exchange volatility. Counter emerging pure-play ITS specialists by bundling edge-computing roadside units with legacy NEMA TS2 cabinet retrofit programs. For New Entrants and Emerging Players: Capture first-mover positioning in India's Bharatmala Pariyojana phase-II secondary cities for intelligent tolling and lane management systems. Target underpenetrated construction zone rental markets with solar-powered temporary work-zone devices meeting EU Green Deal procurement mandates. Pursue channel partnerships with state DOT maintenance departments lacking in-house adaptive signal timing expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor materials science heritage firms with retroreflective substrate production in Germany and the United States when aluminum alloy price spikes strain commodity hardware margins. Long-term viability hinges on adaptive controller software recurring revenue streams replacing transactional equipment sales. Monitor FHWA MUTCD revision timelines as inflection indicator for systematic infrastructure refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Platform Integration | Distributed intersection processing reduces latency for Rotterdam and Utrecht cyclist-vehicle conflict systems. |
| Backward Integration into Aluminum Supply | Captive smelter agreements insulate German signal mast arm producers from London Metal Exchange swings. |
| LiDAR-Camera Fusion Product Launch | Pedestrian-bicycle-vehicle trajectory prediction opens retrofit markets without inductive loop installation. |
| Performance-Based Maintenance Contract Expansion | Uptime guarantees transfer operational risk from Texas DOTs to integrators with predictive diagnostic platforms. |
| EU Green Deal Certification Program | Lifecycle carbon metrics in tender specifications advantage LED retrofit specialists over conventional suppliers. |
Research Methodology
Independent corroboration across state DOT procurement officers, adaptive signal firmware engineers, and retroreflective sheeting plant managers underwrites the qualitative findings on technology transition timelines. Municipal traffic operations directors, construction firm safety compliance leads, and edge-computing roadside unit integration specialists provided primary perspective on procurement behavior shifts. Secondary validation drew from FHWA MUTCD documentation, EU CE marking frameworks, ISO 14819 traffic information standards, and Bundesfernstraßengesetz investment disclosures. Bottom-up segment sizing triangulated against top-down infrastructure spend forecasts.
Comparable-period anchoring to historical MUTCD compliance cycles and federal highway investment waves structured the projection horizon across product type, application, end user, and technology dimensions. Modeled segmentation captured adaptive versus static signal systems, permanent infrastructure versus temporary work-zone deployment, government agency versus construction firm procurement channels, and edge-computing versus centralized control architectures. CAGRs derived from infrastructure replacement cycle compression rates and smart system penetration curves. Forecast inputs included aluminum alloy price trajectory assumptions and V2X corridor pilot zone deployment schedules.
The model holds under sustained federal and state highway investment commitments; deviation in municipal budget austerity or electromechanical legacy system extended retention would shift equipment refresh timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market