
 Engine Bearings Market | 2026-2036
Engine Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Bearings Market Intelligence
The shift toward lead-free, high-performance bearing materials is unwinding the long-held dominance of traditional Babbitt metal compositions. Schaeffler Group leverages its material science expertise to develop advanced polymer-coated bearings for automotive applications. SKF sustains its market position through a focus on rolling element bearings for heavy machinery. NSK specializes in precision bearings for a wide range of industrial and automotive engine types.
Engine bearings are critical components designed to support and guide rotating or sliding shafts within an internal combustion or electric motor. They operate with a thin film of lubricant to minimize friction and wear, often manufactured from multi-layered materials like aluminum or copper alloys. Rolling element bearings command a significant portion of the market due to their use in high-speed applications. The aviation engines application represents a high-margin segment, demanding specialized plain bearings made from advanced composite materials.
Environmental regulations, including the EU's REACH framework and directives from the US EPA, restrict the use of hazardous materials like lead in bearing compositions. Concurrently, ISO standards for engine components mandate specific performance and durability criteria, influencing material selection and manufacturing processes. Suppliers must now balance compliance with these evolving material restrictions against the escalating performance demands from engine manufacturers.
Market Dynamics
The primary structural force is the tension between stringent environmental mandates, such as the EU's REACH framework, and escalating performance requirements from high-output engine applications. This dynamic compels innovation in material science while simultaneously increasing compliance costs for manufacturers.
Growth Catalysts
- Advanced Composite Materials:The development of polymer and composite-based bearing materials enables higher load capacities and longer service life, meeting the demands of high-margin sectors like aviation and performance automotive engines.
- Power Generation Demand:Expansion of energy infrastructure, particularly in industrializing economies like China and India, drives the need for durable, high-performance bearings in large-scale gas and steam turbines.
- Stricter Emission Standards:Global regulations aimed at reducing vehicular and industrial emissions push engine designers to create more efficient systems, which in turn require advanced bearings that minimize frictional losses.
Market Restraints
- Raw Material Volatility:Price fluctuations in key metals like copper, aluminum, and tin directly impact manufacturing costs and profit margins, creating uncertainty for bearing producers and their customers.
- Threat of Bearing-less Designs:In certain high-speed, specialized applications, the emergence of technologies like active magnetic bearings presents a long-term substitution threat, completely eliminating the need for traditional contact bearings.
- Manufacturing Complexity:Producing advanced multi-layer, coated bearings requires significant capital investment and process control expertise, creating high barriers to entry and limiting the pool of qualified suppliers.
Strategic Opportunities
- Electric Vehicle Powertrains:The transition to electric mobility opens a significant market for specialized bearings designed to handle the high rotational speeds and unique load characteristics of EV motors and transmissions.
- Lead-Free Material Leadership:Companies that successfully develop and commercialize high-performance, cost-effective lead-free bearing alloys can capture market share from competitors reliant on traditional materials restricted by EPA and ECHA regulations.
- Industrialization in Southeast Asia:Rapid industrial growth in nations such as Vietnam and Indonesia creates new demand for engine bearings across manufacturing, marine, and energy production applications.
Industry Challenges
- Fragmented Regulatory Compliance:Manufacturers face significant operational overhead in ensuring that a single product portfolio complies with the distinct material and performance standards of the EU's REACH, the US EPA, and China's GB standards.
- Material Science Talent Gap:A shortage of engineers and scientists with expertise in tribology and advanced polymer chemistry hinders the pace of new material development and validation, creating a bottleneck for innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Bearings Market |
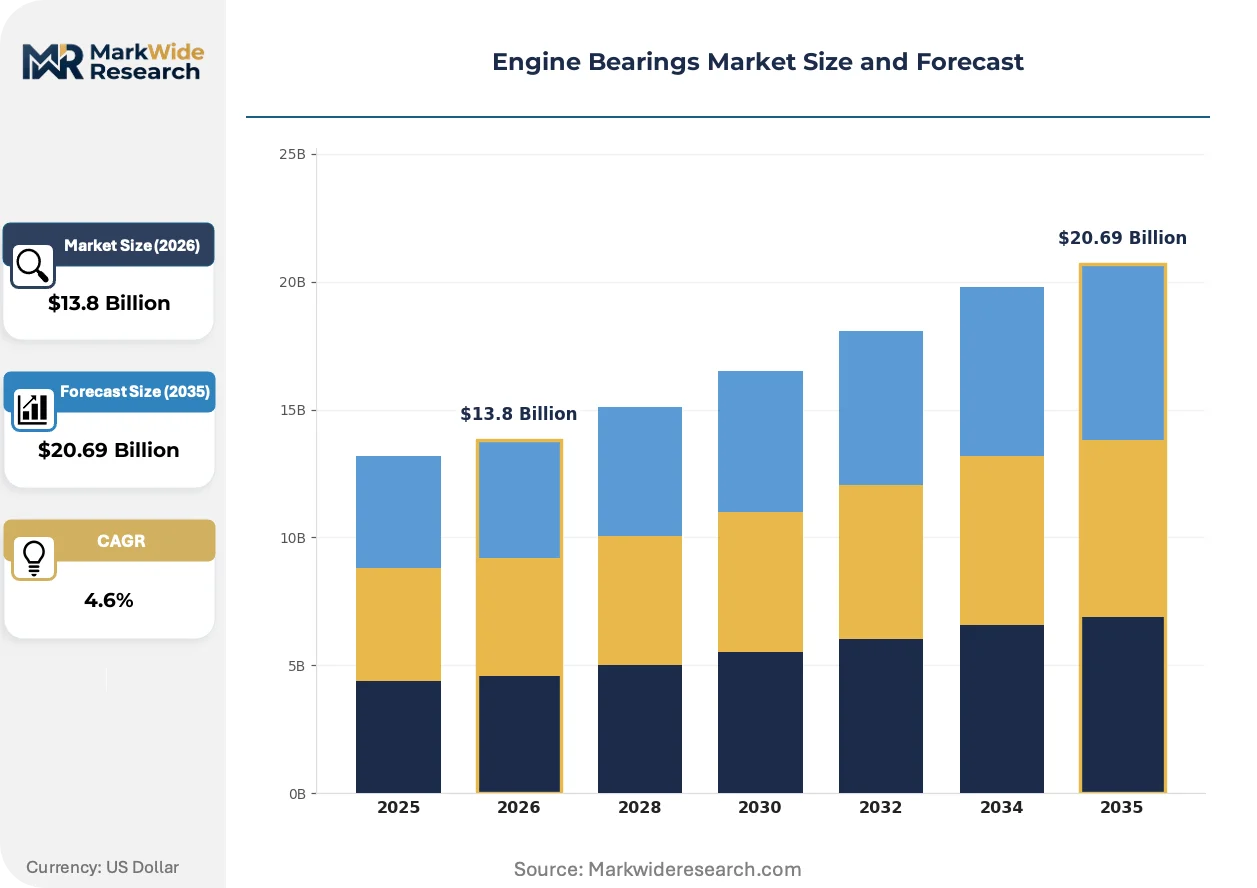
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plain Bearings, Rolling Element Bearings, Fluid Bearings, Magnetic Bearings Material: Copper Alloys, Aluminum Alloys, Plastics, Composite Materials, Babbitt Metal Application: Marine Engines, Construction Equipment, Agricultural Machinery, Power Generation Units, Aviation Engines End User: Engine Manufacturers, Heavy Machinery Producers, Power Plant Operators, Aerospace Manufacturers, Equipment Maintenance Services |
| Companies Covered | NTN, JTEKT Corporation, SKF, MinebeaMitsumi, NACHI, Schaeffler Group, TIMKEN, Regal Rexnord, NSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Bearings Market Strategic Shifts & Innovations
Material science advancements are converging with powertrain electrification and stringent environmental regulations. This intersection is fundamentally altering bearing design, material selection, and performance expectations across the industrial and automotive sectors.
Advanced polymer-coated bearings provide a low-friction, wear-resistant surface for high-stress engine environments. Automotive OEMs are accelerating their adoption for downsized, turbocharged engines that operate under higher thermal and mechanical loads. This polymer-coating technology is supplanting traditional tri-metal Babbitt bearings, particularly in applications where lead-free compliance is mandatory.
The EU's REACH regulation continues to restrict substances of very high concern, including lead compounds used in legacy bearing alloys. This regulatory pressure compels a fundamental redesign of bearing compositions and accelerates the phase-out of leaded materials. The heavy machinery segment, a long-time user of lead-bronze bearings, is most affected and is now actively qualifying lead-free alternatives to maintain market access in Europe.
End-users in industrial sectors are increasingly prioritizing total cost of ownership and extended service intervals over initial component price. This shift moves purchasing decisions away from commodity-based procurement toward partnerships with suppliers offering validated long-life bearing solutions. The trend is most visible within the power generation and heavy-duty commercial vehicle segments, where equipment downtime costs are exceptionally high.
Engine Bearings Market Segmentation
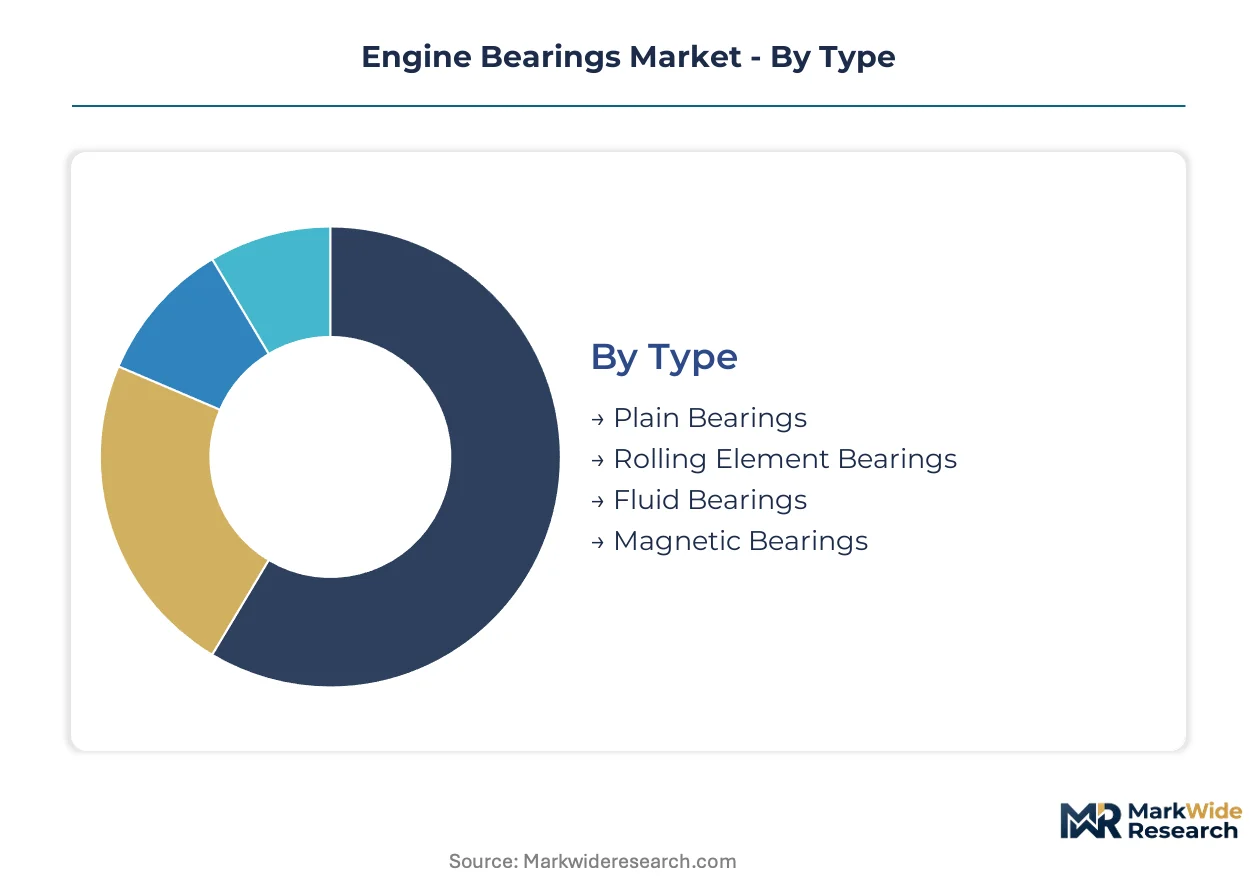
The Engine Bearings Market categorizes its product offerings and applications to reflect distinct technological requirements and end-user demands. This segmentation clarifies component specialization, material innovation, and the specific industry verticals driving demand.
Type:
Regulatory frameworks increasingly differentiate bearing types based on environmental impact and operational efficiency. This influences material selection and design, compelling manufacturers to align product development with compliance.
- Rolling Element Bearings:These bearings use rolling elements to reduce friction and support high-speed rotation. Widespread application in heavy machinery drives substantial demand, particularly in industrializing economies.
- Plain Bearings:These bearings feature a simple sliding surface, relying on a lubricant film in combustion engines. EU's REACH framework mandates a shift to lead-free materials for these components.
- Fluid Bearings:Support loads on a thin film of pressurized fluid, offering low friction for high-speed turbines.
- Magnetic Bearings:Levitate a shaft using electromagnetic forces, eliminating friction and wear in ultra-high-speed applications.
Rolling Element Bearings handle most throughput; Fluid Bearings are the fastest mover on share in high-precision segments.
Material:
Supply concentration for critical raw materials significantly influences the cost and availability of various bearing compositions. Geopolitical factors impact procurement of essential metals and polymers.
- Composite Materials:Advanced polymer-based composites offer superior strength-to-weight ratios and enhanced wear resistance. Aviation engines and performance automotive applications adopt them for extended service life.
- Aluminum Alloys:These alloys offer good thermal conductivity, corrosion resistance, and lead-free characteristics, ideal for automotive and light-duty engines. US EPA and ECHA regulations accelerate adoption.
- Copper Alloys:Provide excellent load-carrying capacity and fatigue strength, traditionally used in heavy-duty diesel engines.
- Plastics:Offer self-lubricating properties and corrosion resistance, suitable for low-load, maintenance-free applications.
- Babbitt Metal:This soft alloy forms a conformable surface layer, used in large, slow-speed machinery for its anti-friction properties.
The shift towards composite materials is driven by performance; copper alloys maintain their niche in heavy-duty industrial segments.
Application:
The margin profiles across engine bearing applications differ significantly, reflecting specialized performance requirements, certification costs, and component criticality. High-stakes applications command premium pricing.
- Aviation Engines:Demand high-precision, lightweight, and durable bearings for extreme temperatures and rotational speeds. This high-margin segment requires specialized plain bearings, subject to FAA and EASA certifications.
- Power Generation Units:Large-scale gas and steam turbines require robust, long-life bearings for continuous operation and heavy loads. Expansion of energy infrastructure in China and India drives demand.
- Marine Engines:Require bearings for high load capacities and corrosion resistance in harsh saltwater environments.
- Construction Equipment:Bearings must endure heavy shock loads, abrasive conditions, and prolonged operation in demanding outdoor settings.
- Agricultural Machinery:Bearings operate in dusty, dirty environments, requiring robust sealing and contamination resistance for reliability.
Demand for power generation units is expanding rapidly; construction equipment represents a stable, foundational segment.
End User:
Different end-user segments exhibit distinct procurement patterns and technical requirements, influencing supplier relationships and product customization. Strategic partnerships are crucial for market penetration.
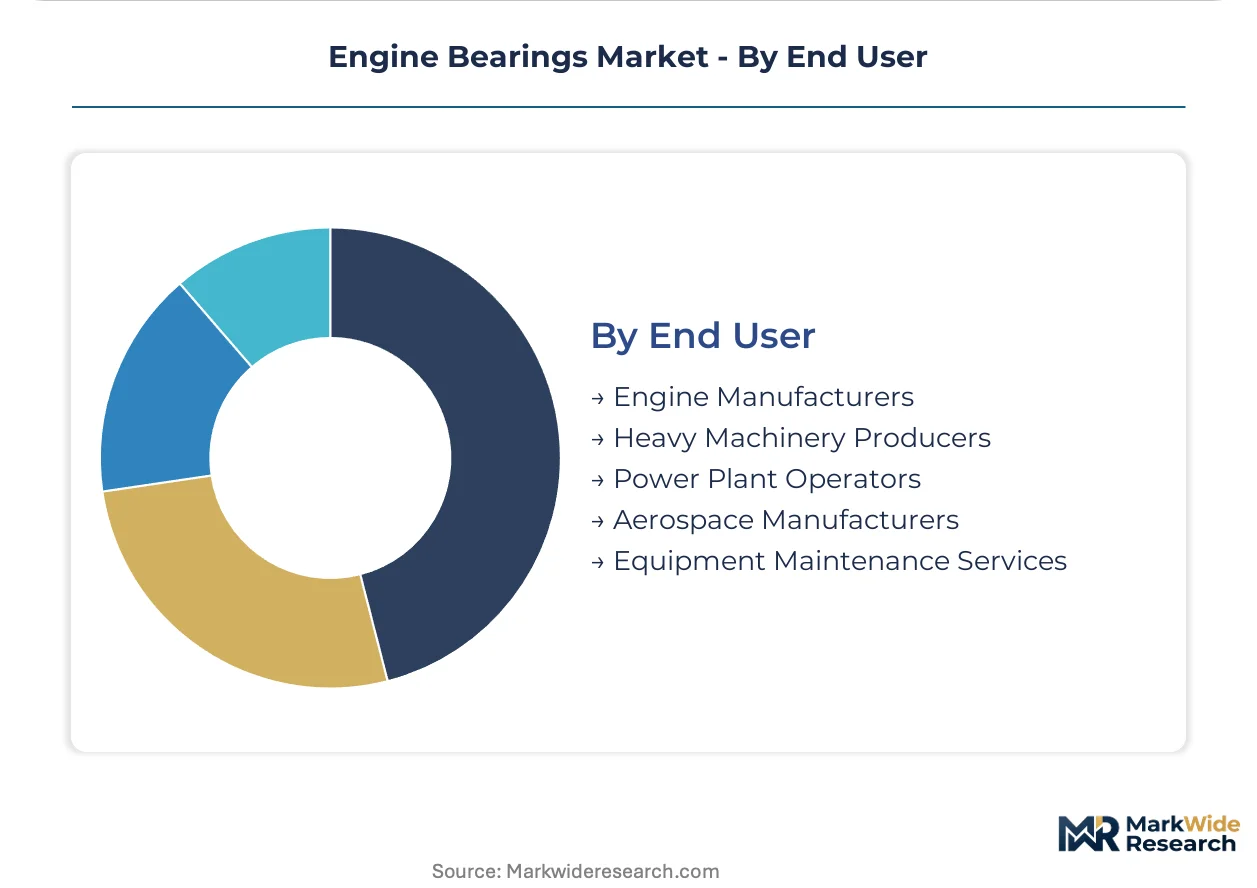
- Engine Manufacturers:These primary customers integrate bearings directly into new engine designs, demanding custom solutions and extensive validation. Partnerships with major OEMs are critical.
- Aerospace Manufacturers:Require bearings meeting extreme performance and strict regulatory compliance from bodies like the FAA. They often engage in co-development for specialized, high-reliability components.
- Heavy Machinery Producers:Procure bearings in large volumes for robust and durable operational demands in agricultural and construction equipment.
- Power Plant Operators:Purchase bearings for maintenance and replacement in large-scale turbines, prioritizing longevity and minimal downtime.
- Equipment Maintenance Services:Source replacement bearings for repair and overhaul across industrial and automotive equipment, focusing on availability and cost-effectiveness.
Engine manufacturers drive initial volume; equipment maintenance services ensure consistent aftermarket demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine bearing components from established manufacturing hubs in Germany and Japan increasingly supply the complex industrial and automotive value chains across Asia and North America. This trade dynamic underscores the global nature of material sourcing and specialized production capabilities. Demand patterns reflect localized industrial growth and regulatory pressures.
China
China's robust industrial expansion and its rapidly growing automotive sector create substantial demand for engine bearings. The country's GB standards for engine components increasingly influence material specifications. The Yangtze River Delta region, a hub for automotive and heavy machinery production, drives significant bearing consumption.
Germany
German demand for engine bearings stems from its advanced automotive industry and precision industrial machinery sectors. The EU's REACH framework compels manufacturers to adopt lead-free and environmentally compliant bearing materials. Bavaria, with its concentration of automotive OEMs, requires high-precision, long-life bearing solutions.
United States
The United States market sees strong demand from its aerospace, power generation, and heavy-duty commercial vehicle segments. US EPA regulations increasingly restrict hazardous materials, pushing for advanced lead-free alternatives. The industrial heartland, particularly around Detroit, drives innovation in engine bearing materials and high-performance designs.
India
India's expanding power generation capacity and its burgeoning automotive and construction sectors fuel considerable demand for engine bearings. The Bureau of Indian Standards (BIS) mandates specific performance and durability criteria for critical infrastructure components. Maharashtra, a prominent industrial state, fuels demand for robust bearings in its manufacturing and energy projects.
Japan
Japanese demand is characterized by its advanced automotive manufacturing and high-precision industrial equipment sectors. METI industrial policies and stringent JIS standards ensure a focus on quality and durability in engine components. The Kanto region, encompassing Tokyo, drives demand for specialized precision bearings from its automotive and electronics manufacturers.
Engine Bearings Market Key Industry Players
Listed leaders compete with private specialists across material science innovation and application-specific engineering within the engine bearings market. The industry exhibits a tiered structure, with established global players dominating high-volume and high-performance segments. Strategic archetypes include diversified industrial conglomerates and niche precision component manufacturers. Dominant competitive moves involve strategic partnerships for new material development and geographic expansion into industrializing economies.
Among the established global players, SKF exemplifies a focus on rolling element bearings, serving diverse heavy machinery and industrial applications with its extensive product portfolio and global distribution network. Schaeffler Group, known for its material science expertise, occupies a strategic position in advanced polymer-coated bearings, particularly for high-performance automotive applications where lead-free compliance is critical. NSK further represents specialists in precision bearings, catering to a wide range of industrial and automotive engine types, thereby anchoring critical segments and driving innovation across diverse geographies.
| Leading Market Players |
|---|
| NTN |
| JTEKT Corporation |
| SKF |
| MinebeaMitsumi |
| NACHI |
| Schaeffler Group |
| TIMKEN |
| Regal Rexnord |
| NSK |
| Others |
Cost & Logistics Intelligence
Extended inventory days for specialized composite materials directly influence the pricing power of advanced bearing manufacturers, reflecting the concentrated nature of their raw material supply chains. This dynamic creates a cost-plus pricing environment for high-performance components, while commodity segments face intense competition.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for engine bearings. Pricing differentiation stems from certification level, particularly FAA and EASA approvals for aviation, and the degree of customization required for specific engine platforms. Pricing pressure stems from raw material volatility in copper and aluminum, alongside increasing compliance costs associated with EU REACH regulations. Equipment maintenance services represent the most price-sensitive segment, while aerospace manufacturers exhibit the lowest price sensitivity due to stringent performance requirements.
Supply Chain Analysis
China anchors significant production of standard engine bearings and raw material processing, while Germany and Japan specialize in precision manufacturing and advanced material components. The supply chain draws from critical raw materials including copper, aluminum, and advanced polymers. A structural risk involves commodity price volatility for key metals, impacting manufacturing costs for bearing producers. Distribution runs through direct sales channels to major engine OEMs and a fragmented network of specialized distributors serving the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Engine Bearings Market is a high-growth disruption, driven by the fundamental redesign of components mandated by stringent environmental regulations like the EU's REACH framework.
For Market Incumbents:Compound investments in lead-free material research and development to mitigate the threat of regulatory non-compliance. Expand advanced polymer-coated bearing production capacity, particularly for high-performance automotive applications, to meet evolving OEM demands. Pursue strategic partnerships with material science firms to secure access to next-generation composites, leveraging existing certification investments and channel control. Focus on tribology expertise to minimize frictional losses in new engine designs.
For New Entrants and Emerging Players:Anchor in specialized bearing solutions for electric vehicle powertrains, capitalizing on unique load characteristics and high rotational speeds. Target the industrialization in Southeast Asia, particularly Vietnam and Indonesia, for standard plain bearings where local supply is nascent. A viable go-to-market angle involves offering cost-effective, lead-free alternatives that meet regional GB standards and EPA guidelines. Focus on niche applications requiring specific material properties.
For Investors and Strategic Acquirers:Long-term, this sits as a sustainable growth play because continuous innovation in material science and powertrain electrification ensures ongoing demand. Identify acquisition targets among niche specialists in advanced composite materials or EV-specific bearing technology. The signal to watch for inflection is the widespread adoption rates of polymer-coated bearings in new automotive platforms. Focus on companies with strong intellectual property in compliant material formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Material Development | Ensures compliance with environmental regulations and unlocks access to restricted markets. |
| EV Powertrain Bearing Specialization | Captures new demand from electric mobility and diversifies application portfolio. |
| Advanced Composite Manufacturing Capacity | Meets performance demands from high-margin aviation and performance automotive sectors. |
| Strategic Partnerships for Certification | Accelerates market entry for new materials by leveraging established regulatory pathways. |
| Geographic Expansion in Southeast Asia | Addresses burgeoning demand from industrializing economies and expands market footprint. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary interviews engaged engine manufacturers' R&D heads, aerospace procurement specialists, heavy machinery engineers, and material science experts. Secondary sources included EU REACH documents, US EPA guidelines, ISO standards, and industry association reports, providing robust data for bottom-up and top-down triangulation.
Quantitative modeling across the projection horizon utilized a comprehensive analytical framework. Segmentation dimensions included bearing type, material composition, application sector, end-user segment, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data extrapolation, adjusted for future market dynamics. Key forecast inputs included raw material price forecasts and global automotive production volumes.
Material uncertainties — geopolitical shifts affecting raw material supply, unforeseen technological breakthroughs in bearing-less designs, or new environmental mandates — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Windshield Repair Kit Market