
 Russia Passenger Vehicles Lubricants Market | 2026-2036
Russia Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Passenger Vehicles Lubricants Market Analytics
Synthetic base oil technology is reshaping how lubricant formulators design products for Russia's passenger vehicle parc. LUKOIL leverages its captive refinery network to secure Group III base stock supply chains that foreign competitors cannot replicate. ROSNEFT anchors its position through vertical integration from crude extraction to finished lubricant bottling at Yaroslavl and Angarsk facilities. ExxonMobil Corporation competes by importing premium synthetic grades that target high-end SUV and light truck applications in Moscow and Saint Petersburg.
Russia passenger vehicles lubricants comprise refined petroleum-based or synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines and drivetrains, with viscosity grades typically ranging from 0W-20 to 15W-40 per SAE J300 standards and additive packages containing detergents, dispersants, anti-wear agents, and friction modifiers. Engine Oil dominates product type revenue due to mandatory drain intervals and the sheer volume of passenger cars requiring periodic servicing across Russia's climatic extremes. Fleet Operators represent the most structurally attractive end user segment because centralized procurement contracts reward volume consistency and technical support capabilities that workshops and individual car owners cannot match.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST R and TR CU standards that dictate minimum oil performance benchmarks, while the Federal Service for Environmental, Technological and Nuclear Supervision (Rostekhnadzor) monitors compliance at blending and storage facilities. These frameworks elevate compliance costs for smaller blenders while creating regulatory moats for established producers with in-house testing laboratories. Stakeholders must monitor how import substitution policies and evolving emissions standards for the Russian automotive parc reshape formulation requirements and sourcing strategies.
Market Dynamics
Synthetic base oil adoption is compressing the addressable market for conventional mineral formulations as Russian blenders retool toward Group III+ capacity to satisfy TR CU 030/2012 performance mandates.
Growth Catalysts
- Commercial fleet pooling:Centralized procurement contracts across the Volga Federal District reward volume consistency and technical support capabilities that individual service stations cannot match.
- TR CU 030/2012:Stricter oil performance standards are pushing domestic blenders toward higher-grade formulations that command premium positioning.
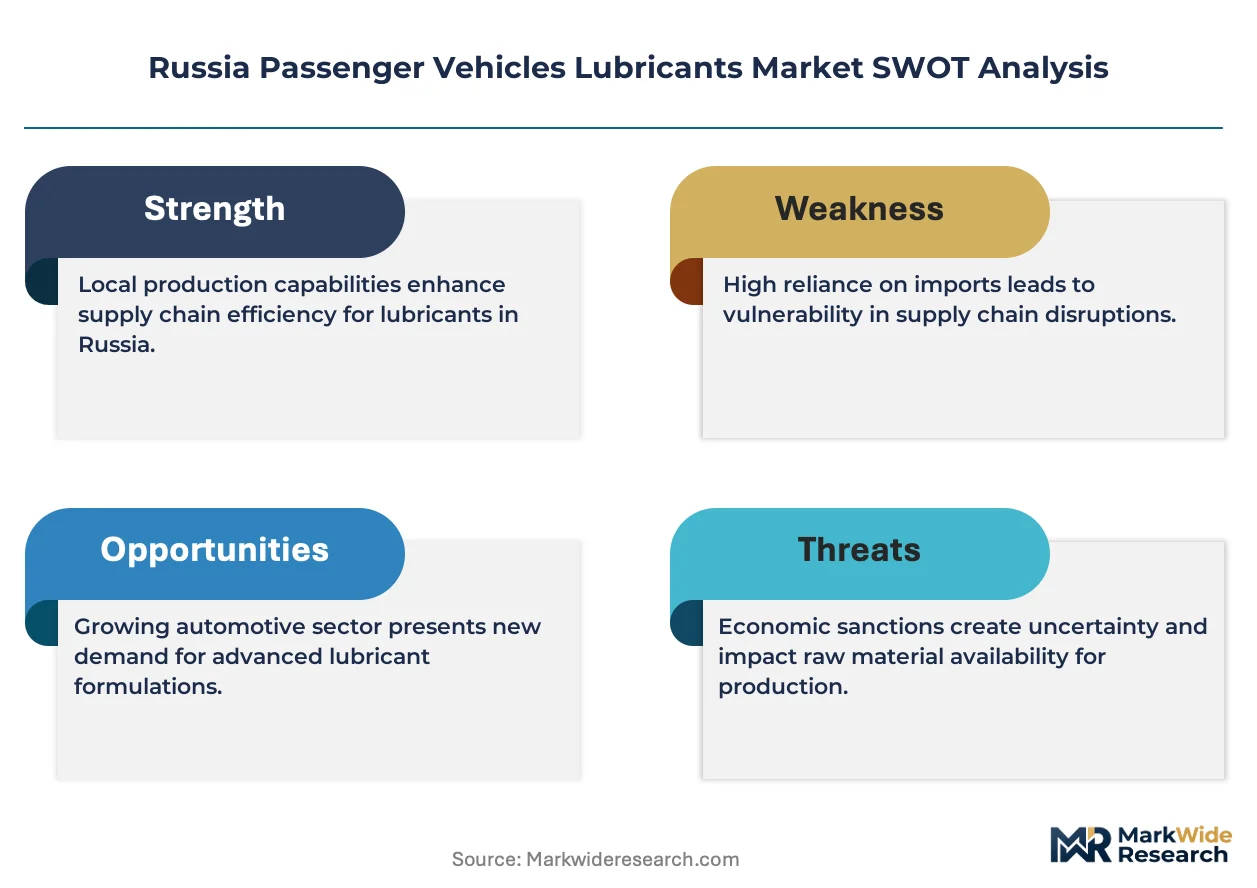
- Group III base stock localization:Captive refinery networks are securing supply chains that insulate producers from import volatility.
Market Restraints
- Additive package import dependency:PPDs, detergents, and dispersants remain concentrated among foreign specialty chemical suppliers, exposing blenders to currency and logistics risk.
- Extended drain interval technology:OEM-recommended service cycles now stretch to 15,000-20,000 kilometers, compressing lubricant consumption per vehicle.
- Rosstandart compliance costs:Mandatory GOST R certification and in-house testing laboratory investments create capital barriers for smaller regional blenders.
Strategic Opportunities
- Siberian and Far Eastern Federal Districts:Vehicle density and service infrastructure lag Moscow by a factor of four, creating whitespace for distribution network expansion.
- Hybrid-electric compatibility formulations:Low-viscosity 0W-16 and 0W-8 grades engineered for start-stop systems and electrified powertrains represent an emerging specification tier.
- Digital service integration:Fleet management platforms that embed lubricant consumption monitoring and predictive maintenance scheduling are opening direct OEM-to-operator channels.
Industry Challenges
- Formulation chemist scarcity:Russian technical universities produce fewer tribology specialists than the blending sector requires, forcing producers to recruit from petrochemical or coatings industries.
- Multigrade certification timelines:Cold-crank simulator and high-temperature high-shear testing protocols through Rosstandart-accredited laboratories extend new product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Passenger Vehicles Lubricants Market |
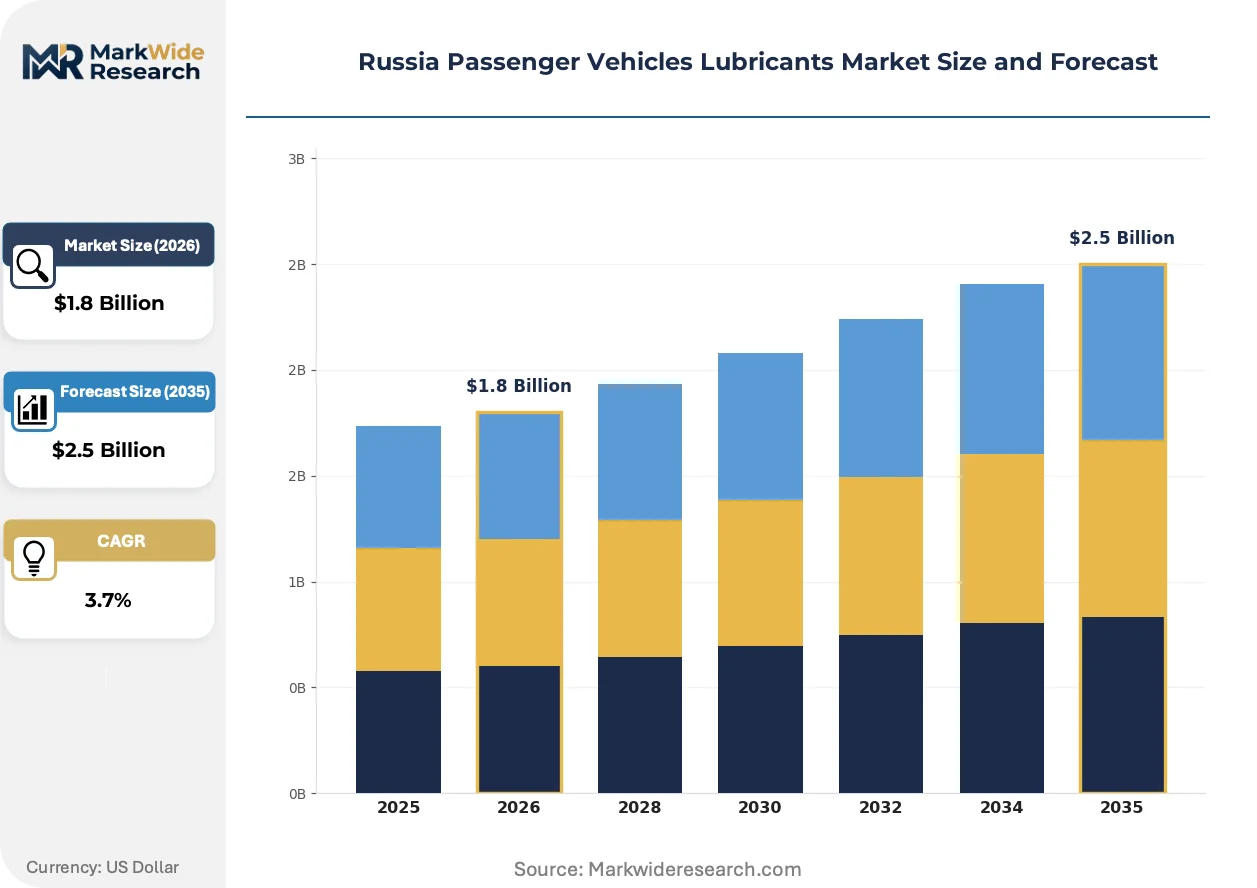
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: Car Owners, Fleet Operators, Workshops, OEMs Distribution Channel: Retail Stores, Online Platforms, Service Stations, Wholesalers Application: Passenger Cars, SUVs, Light Trucks, Specialty Vehicles |
| Companies Covered | LUKOIL, ROSNEFT, Gazprom, DelfinGroup, Royal Dutch Shell Plc, ExxonMobil Corporation, BP PLC (Castrol), LIQUI MOLY, Obninskorgsintez (SINTEC GROUP), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Passenger Vehicles Lubricants Market Evolving Landscape
Digital lubricant monitoring systems are compressing the traditional preventive maintenance model toward condition-based service intervals. This shift rewards suppliers who can integrate hardware sensors with fluid analytics platforms.
Artificial intelligence-driven oil analysis is virtualizing the role of laboratory testing infrastructure. Fleet operators in the Central Federal District are adopting cloud-connected dipstick sensors that transmit viscosity, oxidation, and contamination data in real time. This technology is virtualizing the economics of centralized laboratory networks by displacing batch sampling with continuous monitoring.
Rostekhnadzor facility audits under TR CU 030/2012 are tightening storage and blending environmental controls. The regulation mandates secondary containment systems and vapor recovery units at all lubricant terminals. Blending facilities in Saint Petersburg and Nizhny Novgorod are investing in closed-loop solvent recovery to preempt enforcement actions and secure operating permits.
Consolidated fleet procurement is displacing the fragmented workshop channel. Large logistics operators in Moscow and the surrounding oblasts now negotiate direct supply agreements with blenders, bypassing traditional distributor markups. This concentration is most visible in the light commercial vehicle segment, where pooled maintenance contracts specify single-source lubricant supply with technical support embedded in the service level agreement.
Russia Passenger Vehicles Lubricants Market Segmentation
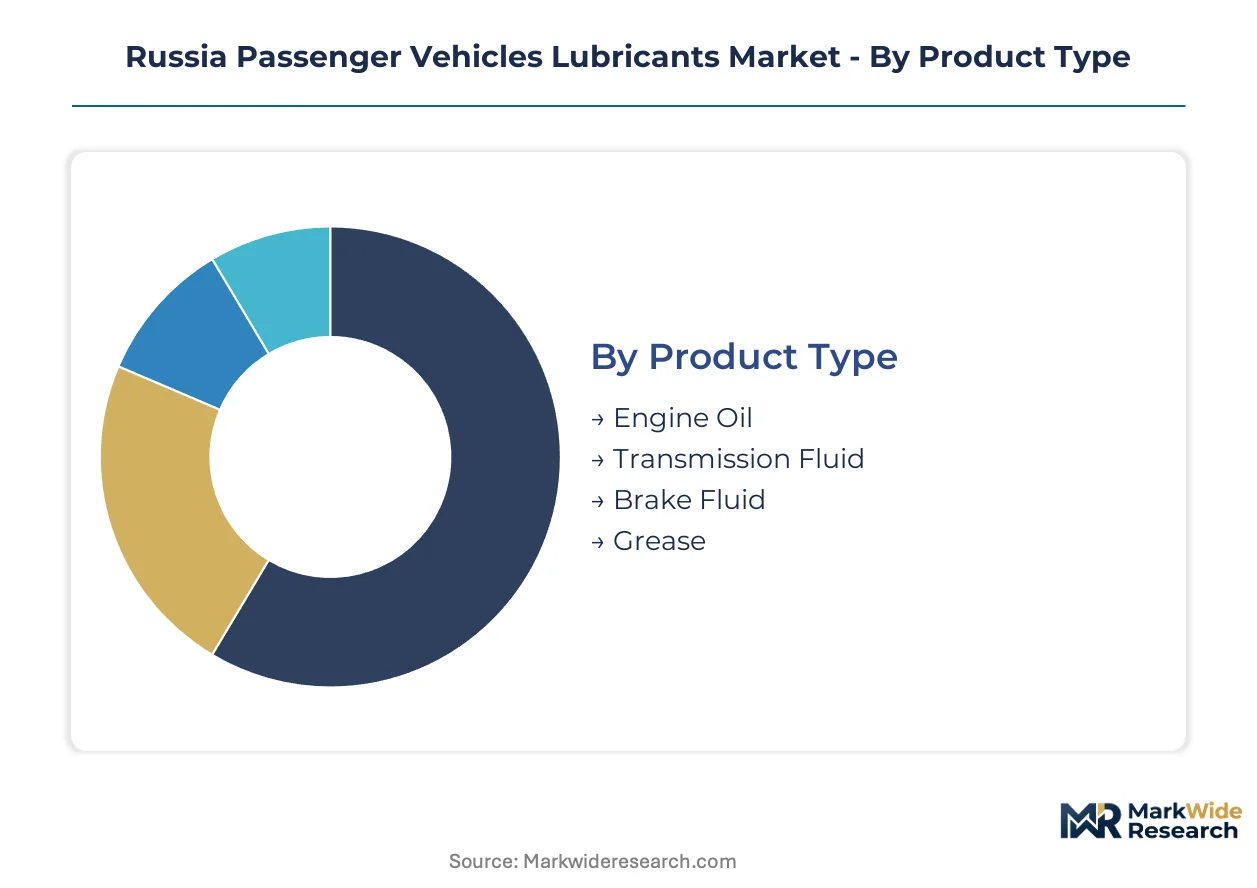
Segmentation in Russia's passenger vehicle lubricants market reveals how formulation requirements, procurement patterns, and distribution economics diverge across customer types and vehicle applications. Understanding these fault lines allows suppliers to align technical capabilities with the specific compliance and service demands of each buyer cluster.
Product Type:
Cost tier determines margin structure and technical investment intensity across lubricant categories, with premium synthetic grades commanding substantially different economics than commodity mineral formulations.
- Engine Oil:Formulations span SAE 0W-20 through 15W-40 viscosity grades with additive packages containing detergents, dispersants, and anti-wear agents per TR CU 030/2012 mandates. Demand concentrates most intensely in Moscow and the Central Federal District where vehicle density and mandatory drain intervals create sustained volume pull.
- Transmission Fluid:Specialized ATF and CVT formulations require precise friction coefficient engineering for Russian climatic extremes from Siberian cold starts to southern high-temperature operation. Fleet operators in the Volga Federal District are consolidating procurement around single-source technical supply agreements that embed fluid analysis services.
- Brake Fluid:DOT 3, DOT 4, and DOT 5.1 specifications serve hydraulic braking systems across the passenger vehicle parc with moisture absorption resistance critical for seasonal temperature swings.
- Grease:NLGI Grade 2 lithium complex and calcium sulfonate thickeners protect chassis components, wheel bearings, and universal joints in vehicles operating on unpaved road surfaces.
Engine Oil holds installed capacity. Transmission Fluid is rotating up the share rankings.
End User:
Customer type shapes procurement scale, price sensitivity, and technical support requirements with stark differences between fragmented individual buyers and consolidated fleet operations.
- Fleet Operators:Centralized procurement contracts across logistics and ride-hailing pools reward volume consistency, predictive maintenance integration, and direct blender relationships that bypass distributor markups. The Volga Federal District is expanding commercial vehicle pooling fastest, creating concentrated demand nodes.
- Car Owners:Individual purchasers prioritize retail accessibility and brand recognition over technical specifications, driving traffic toward service stations and hypermarket automotive aisles in Moscow and Saint Petersburg.
- Workshops:Independent service garages balance inventory turnover against OEM warranty compliance, sourcing through wholesaler networks that offer credit terms and technical training support.
- OEMs:Factory-fill agreements and authorized service network specifications require formulation certification through Rosstandart-accredited laboratories with extended drain interval technology compressing per-vehicle consumption.
Fleet Operators capture the steepest expansion trajectory. Workshops are defending share through technical service bundling.
Distribution Channel:
Supply concentration varies dramatically by channel, with captive refinery networks competing against import-dependent specialty distributors for shelf space and direct procurement relationships.
- Service Stations:LUKOIL and ROSNEFT leverage vertical refinery-to-pump infrastructure to secure preferential placement and bundled fuel-lubricant loyalty programs across the Central Federal District.
- Retail Stores:Hypermarket and automotive specialty chains in Moscow stock premium imported synthetics targeting SUV and light truck owners with higher performance specifications.
- Online Platforms:E-commerce penetration remains limited by consumer preference for immediate availability and installation services, though fleet procurement portals are gaining traction.
- Wholesalers:Regional distributors maintain inventory buffers for smaller blenders and independent workshops, absorbing currency risk on imported additive packages.
Service Stations anchor volume throughput. Online Platforms are climbing the fastest among emerging channels.
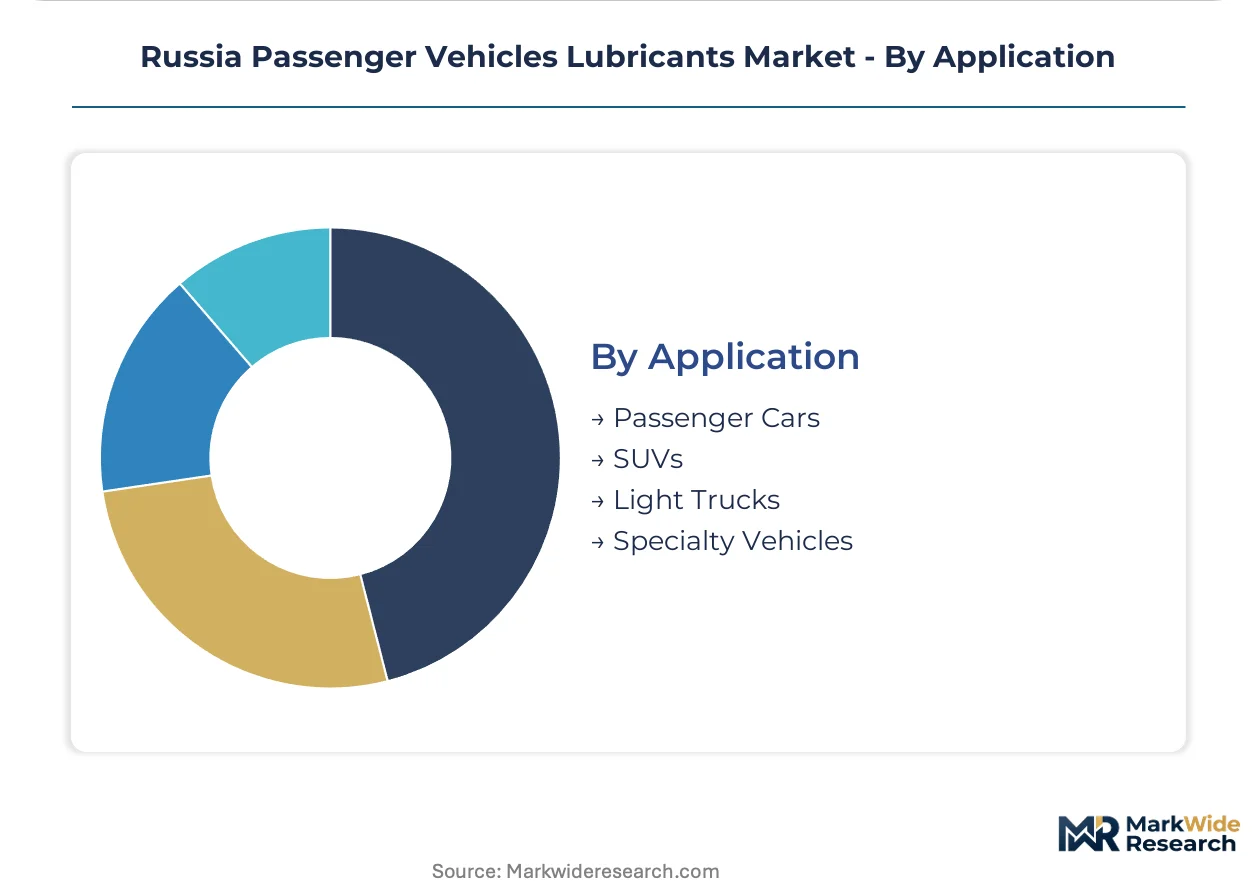
Application:
Vehicle category dictates viscosity grade requirements, drain interval economics, and the relative importance of cold-crank performance versus high-temperature shear stability.
- Passenger Cars:Sedan and hatchback parc dominates unit volume with 5W-30 and 5W-40 grades standard, though 0W-20 adoption is accelerating among newer vehicles in Moscow.
- SUVs:Higher displacement engines and all-wheel-drive differentials demand robust thermal stability and specialized transfer case fluids, with premium synthetic positioning most pronounced in Saint Petersburg and Moscow.
- Light Trucks:Commercial delivery and utility vehicles in the Volga Federal District prioritize extended drain intervals and bulk procurement economics over specification sophistication.
- Specialty Vehicles:Ambulance, taxi, and government fleet applications require rapid oil analysis turnaround and guaranteed supply continuity under severe duty cycles.
Passenger Cars maintain the largest installed base. SUVs are gaining share fastest in premium lubricant consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia exports refined petroleum products and lubricant base stocks to neighboring Commonwealth of Independent States markets while importing specialized additive packages from Western European chemical manufacturers. This trade-flow structure shapes regional supply security priorities and formulation cost structures across the domestic market.
Central Federal District
Moscow concentrates the highest vehicle density and premium lubricant consumption nationwide. Rosstandart certification requirements for GOST R compliance elevate barriers for imported formulations. Fleet operators in Moscow and surrounding oblasts negotiate direct supply agreements that bypass traditional wholesale channels.
Volga Federal District
Commercial vehicle pooling expands fastest here, creating concentrated demand nodes for bulk transmission fluid and engine oil procurement. TR CU 030/2012 enforcement through Rostekhnadzor audits tightens blending facility environmental controls. Nizhny Novgorod hosts closed-loop solvent recovery investments that preempt regulatory enforcement actions.
Siberian Federal District
Vehicle density lags Moscow by a factor of four, creating distribution network whitespace for regional blenders. Extreme cold-start conditions from Omsk to Krasnoyarsk demand robust low-temperature viscosity performance in 0W-20 and 5W-30 grades. Novosibirsk serves as the logistical hub for eastward supply chain extension.
Northwestern Federal District
Saint Petersburg anchors premium synthetic consumption for SUV and light truck applications with higher performance specifications. Import substitution policies reshape sourcing strategies for additive packages previously supplied through Baltic transit routes. The city maintains Rosstandart-accredited testing laboratories that extend certification timelines for new product launches.
Far Eastern Federal District
Proximity to Asian supply chains creates alternative sourcing corridors for base stocks and finished lubricants. Service infrastructure gaps persist from Vladivostok to Khabarovsk, constraining aftermarket penetration. Regional blenders face currency risk exposure on imported additive components from Chinese and South Korean specialty chemical suppliers.
Russia Passenger Vehicles Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that rewards captive refinery networks and vertical integration. Domestic producers with upstream crude extraction assets hold structural advantages in base stock supply security. Three archetypes dominate: state-affiliated integrated oil companies, foreign multinationals with premium import positioning, and independent regional blenders serving fragmented workshop channels. Competitive moves concentrate on distribution network densification and formulation certification speed.
Among state-affiliated integrated producers, LUKOIL and ROSNEFT occupy positions that exemplify backward integration from crude extraction through finished lubricant bottling. ExxonMobil Corporation represents the foreign multinational archetype, anchoring premium synthetic positioning in Moscow and Saint Petersburg through import-dependent supply chains. These three companies illustrate how divergent sourcing strategies—captive refinery networks versus import logistics—create distinct competitive positions within the same regulatory framework.
| Leading Market Players |
|---|
| LUKOIL |
| ROSNEFT |
| Gazprom |
| DelfinGroup |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| LIQUI MOLY |
| Obninskorgsintez (SINTEC GROUP) |
| Others |
Value Network & Pricing Analysis
Rail freight corridors from Angarsk to Moscow transmit base stock cost volatility directly into finished lubricant pricing, compressing margins for blenders without captive refinery capacity while amplifying price differentiation between Group III synthetics and mineral formulations across fleet procurement contracts.
Pricing Analysis
Cost-plus contracts indexed to Platts Group II/III base oil assessments dominate fleet procurement in the Volga Federal District, with pricing stratifying across premium synthetic, standard hydrocracked, and economy mineral tiers based on TR CU 030/2012 certification grade and volume commitment scale. Price erosion runs through the economy mineral segment as extended drain interval technology compresses per-vehicle consumption, while premium synthetics maintain pricing power through Rosstandart certification scarcity. Fleet operators exhibit lowest price sensitivity due to total cost of ownership modeling, whereas individual car owners in retail channels show highest elasticity to pump price fluctuations.
Supply Chain Analysis
Upstream feedstock supply concentrates in Russia's domestic refinery network at Yaroslavl, Angarsk, and Nizhny Novgorod, with Group III base stock production drawing from captive crude extraction through LUKOIL and ROSNEFT integrated assets. Additive package inputs—PPDs, detergents, and dispersants—hinge on specialty chemical suppliers in Germany, Belgium, and the United States, creating tariff exposure through Baltic and Black Sea transit routes. Distribution runs through captive refinery-to-pump infrastructure for volume throughput, while regional wholesalers absorb currency risk on imported components for independent blender networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity constrains new product launch velocity, with Russian technical universities producing fewer tribology specialists than the blending sector requires. This capability gap rewards incumbents with established laboratory infrastructure and pressures new entrants to recruit from adjacent petrochemical industries.
For Market Incumbents: Entrench market position through backward integration into additive package blending capabilities to reduce import dependency exposure, while expanding Rosstandart-accredited testing laboratory capacity to compress certification timelines for multigrade formulations. Defend against emerging regional blenders by locking in long-term fleet procurement contracts across the Volga Federal District that embed predictive maintenance analytics. For New Entrants and Emerging Players: Establish a beachhead in the Siberian Federal District's distribution whitespace, where vehicle density gaps and extreme cold-start performance requirements create demand for specialized low-viscosity formulations that incumbent networks underserve. Penetrate through technical service bundling with independent workshops, offering fluid analysis capabilities that match fleet-operator procurement specifications without requiring direct blender relationships. For Investors and Strategic Acquirers: Independent regional blenders with established wholesaler relationships and GOST R certification infrastructure represent the most defensible acquisition archetype in a market consolidating around vertical integration. Long-term viability hinges on import substitution policy durability and electrified powertrain penetration rates. Watch hybrid-electric compatibility formulation adoption among Moscow fleet operators as the inflection signal for premium synthetic demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Reduces currency exposure on imported PPD and detergent packages from German specialty chemical suppliers. |
| Rosstandert Laboratory Accreditation Investment | Compresses 8-14 month multigrade certification timelines that currently delay new product launches. |
| Siberian Distribution Network Expansion | Captures whitespace in Omsk and Krasnoyarsk where service infrastructure lags Moscow by factor of four. |
| Hybrid-Electric Formulation Development | Positions for 0W-16 and 0W-8 demand from start-stop systems and electrified powertrains in Moscow parc. |
| Fleet Management Platform Integration | Opens direct OEM-to-operator channels that bypass traditional distributor markups in consolidated procurement. |
Research Methodology
Desk research of customs trade data, Rosstandart certification registries, and refinery capacity disclosures preceded structured interviews with lubricant blending plant managers, fleet procurement directors at logistics operators, additive package suppliers, and Rosstandart laboratory accreditation officers. Secondary validation drew from TR CU regulatory filings, base stock trade flow databases, and automotive parc registration statistics. Bottom-up volume modeling triangulated against top-down value estimates derived from refinery throughput and finished product pricing benchmarks.
Assumptions held fixed include TR CU 030/2012 enforcement continuity and current import substitution policy trajectory, while variables tested across the analysis window encompass electrified powertrain penetration rates, additive package sourcing corridor shifts, and fleet pooling consolidation velocity. Segmentation dimensions modeled comprise viscosity grade tier, end user procurement scale, distribution channel structure, and regional climatic demand pattern. CAGRs were derived from regression analysis against vehicle parc growth, drain interval extension rates, and synthetic grade substitution elasticity.
Stress conditions across base stock price volatility, ruble exchange rate fluctuation, and regulatory certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity and technology adoption curves. Cross-checking against IHS Markit vehicle registration data and refinery utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Drum Brake Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Motorcycle Top Box Market