
 Engine Oil Market | 2026-2036
Engine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Oil Market Analysis
Subscription-based oil analysis and predictive maintenance programs are broadening the revenue model beyond bulk fluid sales. ExxonMobil leverages its Mobil Serv lubricant analysis platform to lock in fleet retention through condition-monitoring contracts. Shell anchors its position with differentiated service bundles tied to carbon-neutral product lines. BP competes through Castrol ON, its dedicated electric vehicle fluid range, as powertrain electrification fragments traditional demand pools.
Engine oil is a formulated lubricant comprising base stocks and additive packages designed to reduce friction, dissipate heat, and neutralize combustion acids in internal combustion engines, with viscosity grades such as 5W-30 and 0W-20 defining cold-start flow and high-temperature film strength. Synthetic formulations command premium positioning due to extended drain intervals and OEM factory-fill mandates, while conventional segments face structural compression in passenger vehicle applications. High-mileage grades occupy a defensive niche as vehicle age profiles lengthen in developed economies.
The US EPA and California Air Resources Board set tailpipe emissions standards that cascade into oil performance specifications through GF-6 and API SP requirements, while Europe's REACH framework restricts certain boron and phosphorus additive chemistries. India's BIS certification and PLI scheme for automotive components are accelerating local blending capacity to meet stricter OEM standards. Stakeholders must monitor regulatory divergence between emissions-focused jurisdictions and additive-restrictive frameworks when configuring regional product portfolios.
Market Dynamics
Powertrain electrification fragments traditional demand pools as hybrid and battery-electric vehicles displace conventional internal combustion architectures, forcing blenders to recalibrate portfolio weights between legacy lubricants and electrified-thermal-fluid formulations.
Growth Catalysts
- API SP grade upgrades:India's BIS certification mandates and PLI scheme for automotive components accelerate local blending capacity to meet stricter OEM factory-fill specifications, compressing legacy API SL inventory.
- REACH additive chemistry protocols:Europe's F-Gas Regulation and ECHA restrictions on boron and phosphorus compounds drive R&D investment in compliant friction-modifier packages.
- Long-drain service contracts:Commercial fleet operators in North America and Europe expand predictive maintenance programs as a core procurement criterion, locking in synthetic formulation volumes.
Market Restraints
- Group III base oil supply concentration:Middle Eastern and Asian refinery expansions create geographic dependency for high-viscosity-index feedstocks, exposing blenders to freight and tariff volatility.
- Electric vehicle fluid substitution:Battery thermal management fluids and e-axle lubricants displace traditional engine oil volumes in OEM fill channels as electrification penetrates passenger segments.
- REACH registration timelines:ECHA's extended authorization periods for novel additive chemistries delay product launches by 18-36 months, compressing first-mover windows.
Strategic Opportunities
- India aftermarket upgrade cycle:Independent workshops in Maharashtra and Tamil Nadu transition from mineral to semi-synthetic grades as vehicle parc ages and consumer awareness of drain-interval economics spreads.
- Carbon-neutral product lines:EU Green Deal alignment and CSRD disclosure requirements create premium positioning for mass-balance-certified formulations using bio-based base stocks.
- Subscription-based oil analysis:Condition-monitoring platforms bundled with fluid supply contracts deepen fleet retention and generate recurring revenue beyond bulk product sales.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and additive-package synergies concentrates at legacy majors, constraining mid-tier blenders' speed-to-market for next-generation specifications.
- GF-6/SP certification costs:OEM sequence testing and dexos licensing fees exceed $500,000 per formulation variant, creating capital barriers for regional players targeting factory-fill approvals.
- Base stock-plant reconfiguration:Conventional Group I capacity idling in Europe and North America generates stranded-asset risk as demand tilts toward Group II/III and gas-to-liquids feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Oil Market |
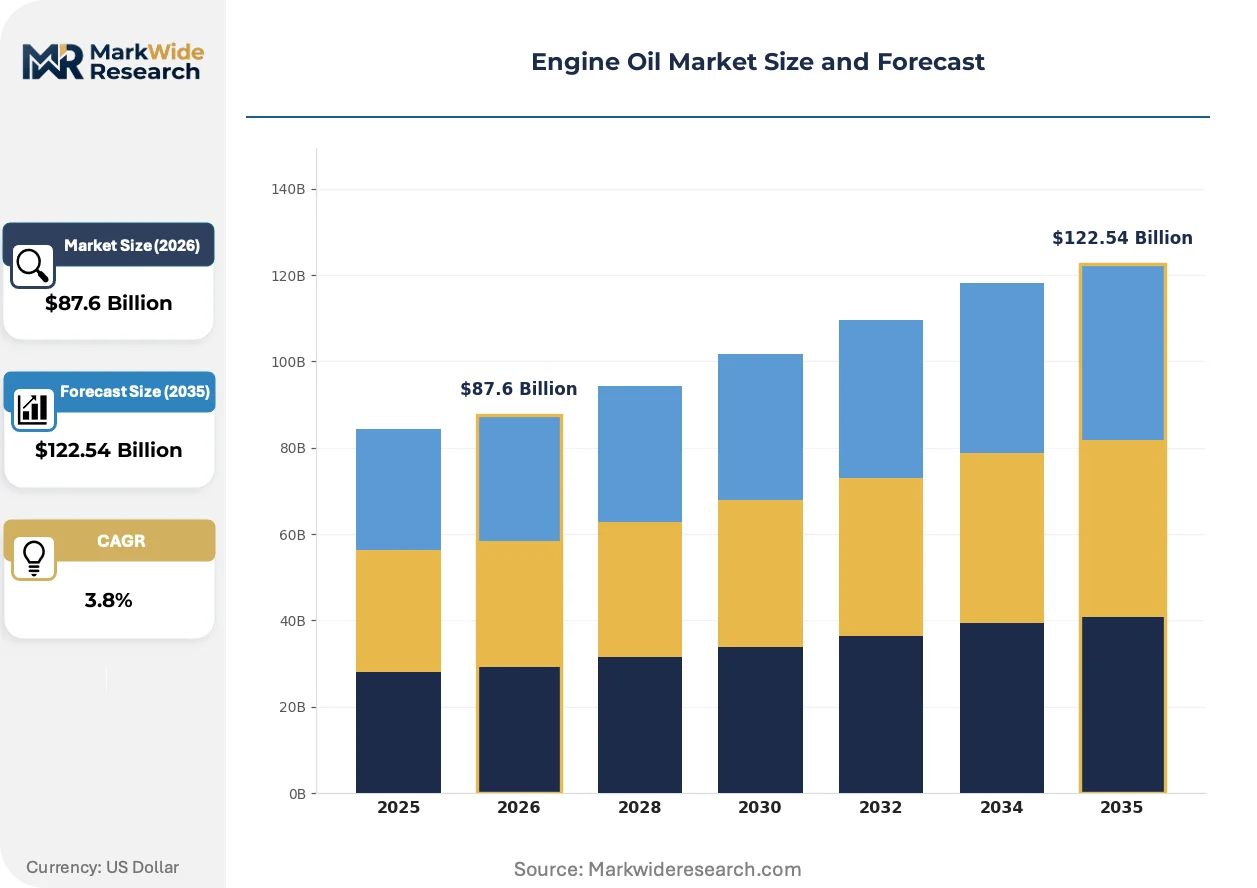
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, Semi-Synthetic, High-Mileage Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Industrial Engines Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Additive Type: Detergents, Anti-Wear Agents, Viscosity Modifiers, Corrosion Inhibitors |
| Companies Covered | ExxonMobil, Shell, BP, Chevron Corporation, TotalEnergies, Castrol, Valvoline, Lukoil, Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Oil Market Emerging Trajectories
Digital integration and chemistry innovation are compressing traditional product lifecycles while regulatory stringency accelerates specification turnover, forcing blenders to synchronize R&D pipelines with emissions-framework cadences rather than mechanical wear cycles alone.
Polyalkylene glycol (PAG) base stocks are converging with hybrid-electric thermal management requirements, offering superior oxidative stability and dielectric properties for battery cooling circuits. Japanese and German OEMs specify PAG-enhanced formulations for dedicated hybrid transmissions, compressing demand for conventional ATF chemistry in electrified powertrains.
Europe's F-Gas Regulation and REACH framework are tightening restrictions on fluorinated greenhouse gases and boron-containing friction modifiers, cascading into reformulated additive packages. Blenders serving EU-27 markets must revalidate dispersant and anti-wear chemistries, with passenger vehicle OEMs accelerating factory-fill approvals for compliant low-SAPS grades ahead of 2025 fleet-average CO2 targets.
Fleet procurement departments now unbundle fluid supply from maintenance labor, negotiating direct contracts with blenders for bulk delivery and in-house analysis. North American long-haul operators and European logistics consortia lead this disintermediation, displacing traditional jobber-distributor relationships with direct vendor-managed inventory programs tied to telematics-triggered replenishment.
Engine Oil Market Segmentation
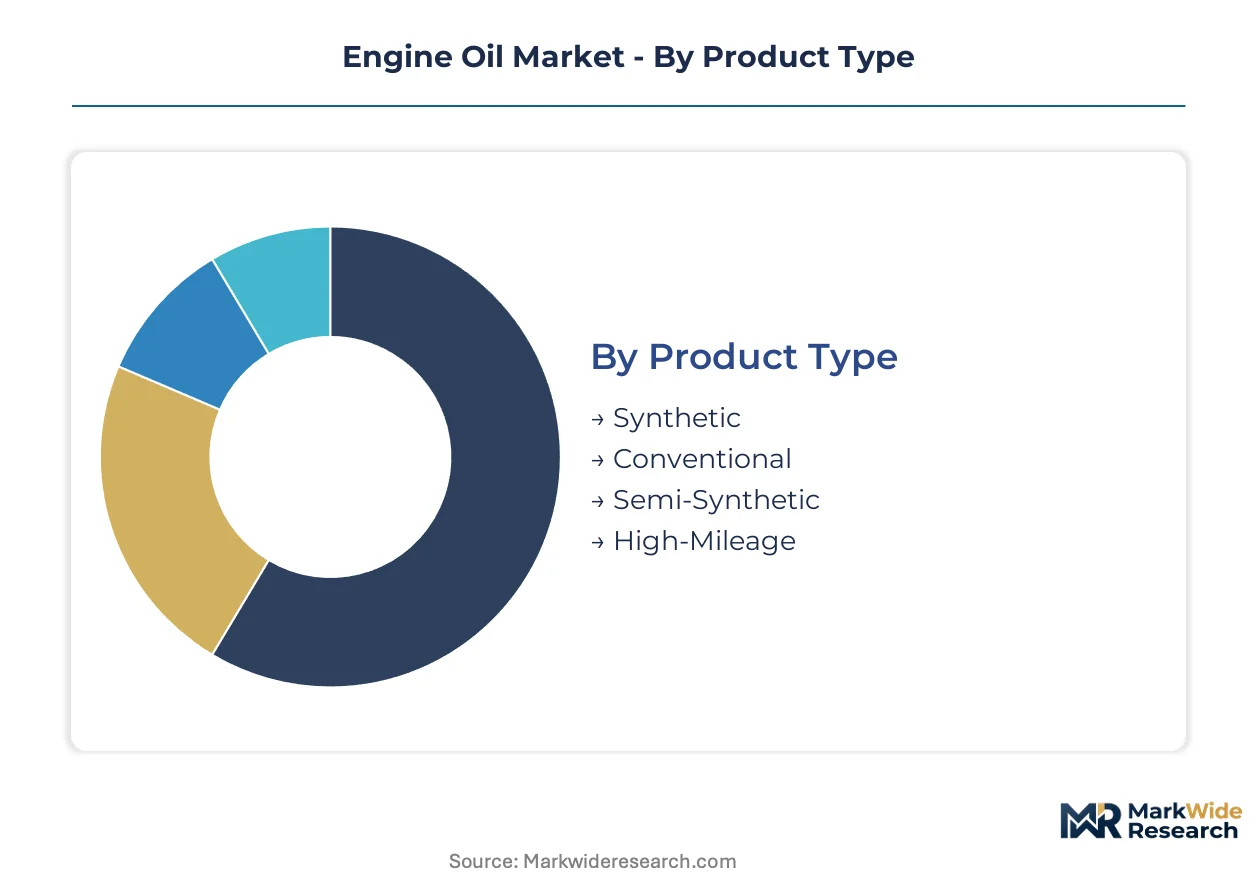
Engine oil segmentation reveals divergent margin structures across formulation chemistry and end-use applications. Blend portfolios must balance factory-fill synthetic mandates against aftermarket price sensitivity in aging vehicle parcs.
Product Type:
Volume concentrates in conventional grades, while value capture tilts toward synthetic and semi-synthetic formulations commanding extended drain-interval premiums.
- Synthetic:Full-synthetic formulations using Group III or PAO base stocks deliver oxidative stability for 10,000+ mile drain intervals. OEM factory-fill mandates from Toyota, Honda, and Volkswagen in the US, Germany, and Japan concentrate demand, though Group III feedstock dependency on Middle Eastern and Asian refineries exposes blenders to freight volatility.
- Conventional:Mineral-based formulations refined from Group I/II base stocks dominate emerging aftermarket channels by volume. India's independent workshops in Maharashtra and Gujarat remain heavy consumers as BIS certification upgrades compress legacy API SL inventory, yet margin compression accelerates as semi-synthetic alternatives penetrate price-sensitive tiers.
- Semi-Synthetic:Blended formulations offering mid-tier drain intervals capture upgrade cycles from conventional users in India's aging vehicle parc.
- High-Mileage:Seal conditioners and anti-wear packages target vehicles exceeding 75,000 miles, defending a niche as US and European fleet age profiles lengthen.
Today's leader: Synthetic. Tomorrow's challenger: Semi-Synthetic.
Application:
Passenger and commercial vehicle segments diverge sharply in procurement behavior, with fleet operators unbundling fluid supply from maintenance labor.
- Passenger Vehicles:Light-duty OEM fill channels specify low-viscosity synthetics to meet CAFE and EU fleet CO2 targets. US EPA tailpipe standards cascade into GF-6 and API SP lubricant requirements, while European REACH restrictions on boron additives force reformulation of friction-modifier packages for EU-27 markets.
- Commercial Vehicles:Long-haul fleets in the US, Germany, and Brazil negotiate direct vendor-managed inventory contracts tied to telematics-triggered replenishment. Predictive maintenance programs lock in synthetic volumes as core procurement criteria, displacing traditional jobber-distributor relationships.
- Motorcycles:Wet-clutch compatibility requirements drive specialized JASO MA/MA2 formulations for two-wheeler concentrations in India, Vietnam, and Indonesia.
- Industrial Engines:Stationary power generation and off-highway equipment sustain Group II/III demand in markets with slower electrification timelines.
Fleet procurement is concentrating fastest in commercial vehicles; motorcycle formulations face electrification substitution from battery two-wheelers in Asian cities.
Viscosity Grade:
Low-viscosity trends dominate OEM engineering specifications, while legacy grades defend aftermarket replacement demand.
- 0W-20:Ultra-low-viscosity formulations reduce cold-start friction for hybrid and downsized turbocharged engines. Toyota and Honda factory-fill specifications across US, Japanese, and Indian assembly plants concentrate demand, though shear stability under high-temperature operation demands premium base stock investment.
- 5W-30:The workhorse grade balances cold-flow performance with high-temperature film strength across temperate climates. European OEM dexos and ACEA C-series approvals fragment specifications, creating formulation complexity for blenders serving multiple export markets.
- 10W-40:Higher viscosity defends commercial and high-mileage applications in warmer climates and older engine architectures.
- 15W-50:Heavy-duty protection for performance and severe-service applications retains niche positioning in motorsport and industrial segments.
5W-30 anchors current volume; 0W-20 climbs fastest as hybrid penetration accelerates.
Additive Type:
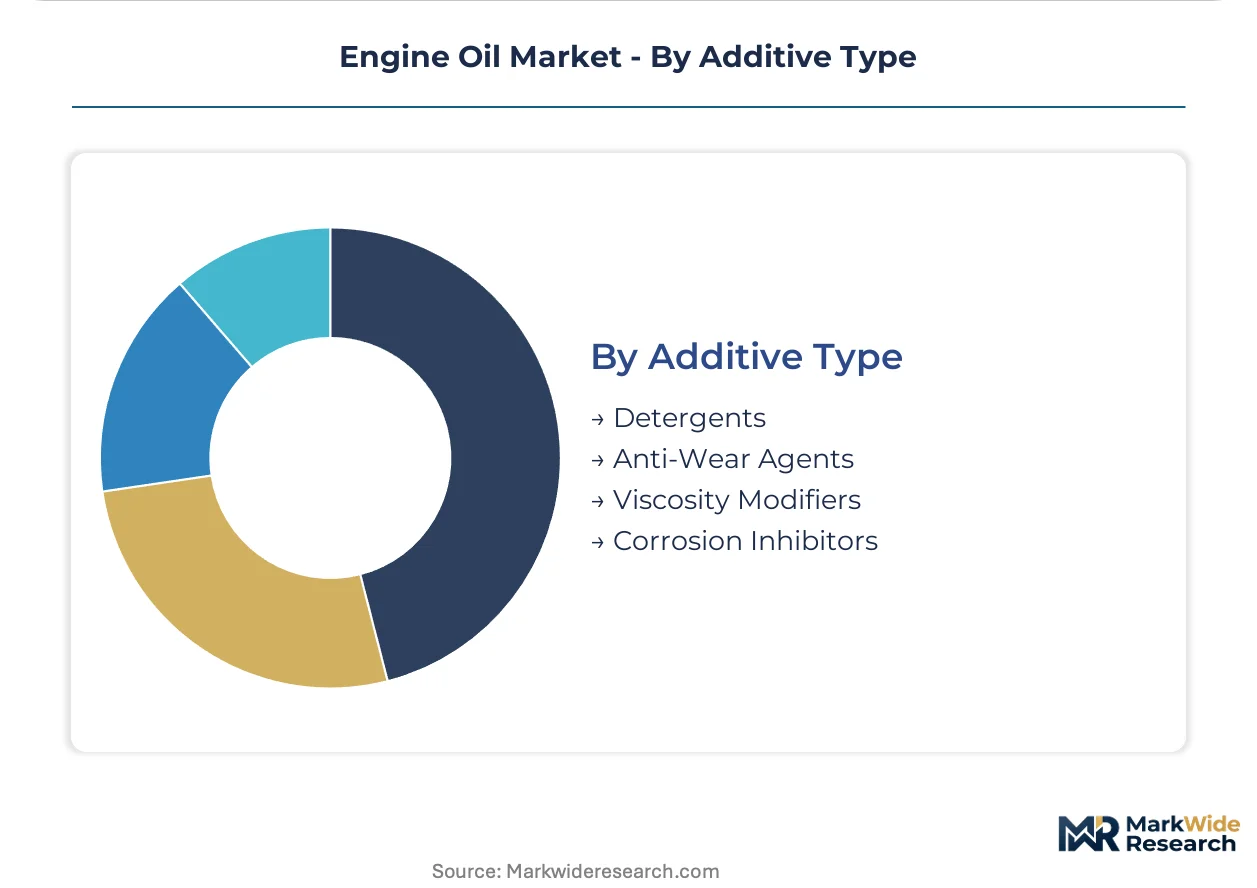
Regulatory chemistry restrictions are reshaping additive package composition faster than traditional mechanical wear-cycle timelines.
- Detergents:Calcium and magnesium sulfonate packages neutralize combustion acids and suspend deposits. REACH authorization timelines for novel detergent chemistries delay product launches by 18-36 months, compressing first-mover windows for EU-27 market entrants.
- Anti-Wear Agents:ZDDP (zinc dialkyldithiophosphate) formulations face phosphorus caps from US EPA and European emissions regulations. Low-SAPS (sulfated ash, phosphorus, sulfur) grades for gasoline particulate filter protection command R&D investment from blenders targeting Euro 6 and forthcoming Euro 7 compliance.
- Viscosity Modifiers:PAMA and OCP polymers enable multi-grade performance across temperature ranges, with shear stability critical for extended drain intervals.
- Corrosion Inhibitors:Rust prevention chemistry defends engine longevity in humid climates and intermittent-use vehicles, particularly relevant for Southeast Asian and Latin American aftermarket channels.
Detergents lead formulation spend; anti-wear agents face steepest regulatory-driven reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's aftermarket upgrade cycle outpaces Germany's factory-fill concentration, while US fleet procurement patterns diverge sharply from China's state-mandated electrification timeline. Regulatory stringency and powertrain transition speed create distinct competitive arenas across major lubricant-consuming economies.
United States
Commercial long-haul operators in Texas and Ohio unbundle fluid supply from maintenance contracts, negotiating direct vendor-managed inventory with telematics-triggered replenishment. EPA tailpipe standards cascade into GF-6 lubricant requirements that compress legacy formulation windows. The Permian Basin and Great Lakes manufacturing corridors anchor synthetic blending capacity serving both OEM fill and aftermarket channels.
Germany
ACEA C-series approvals fragment specification complexity for blenders targeting export markets from Stuttgart and Munich engineering clusters. REACH restrictions on boron-containing friction modifiers force reformulation of additive packages ahead of Euro 7 compliance deadlines. The Ruhr industrial belt sustains Group III base oil demand even as passenger electrification accelerates in Bavaria.
India
Maharashtra and Tamil Nadu independent workshops transition from mineral to semi-synthetic grades as vehicle parc ages and drain-interval economics penetrate consumer awareness. BIS certification mandates and PLI scheme incentives accelerate local blending capacity for API SP factory-fill specifications. Gujarat's Jamnagar refining complex supplies high-viscosity-index feedstocks to domestic formulators.
China
Dual carbon goals and MIIT electrification mandates compress traditional engine oil demand in coastal manufacturing zones while sustaining industrial lubricant consumption inland. GB standards for low-viscosity formulations align with NEV thermal management fluid requirements in the Yangtze River Delta. Sinopec's integrated refining positions anchor Group II/III supply for domestic blenders.
Brazil
São Paulo and Minas Gerais fleet operators adopt predictive maintenance programs modeled on North American procurement patterns, locking in synthetic volumes for long-haul corridors. ANVISA-equivalent automotive standards lag OECD specification timelines, creating formulation complexity for exporters. The Southeast industrial belt concentrates blending capacity serving Mercosur factory-fill and aftermarket replacement demand.
Engine Oil Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with factory-fill channels consolidating around formulation-certified majors while aftermarket price competition fragments regional tiers. Three strategic archetypes dominate: integrated energy majors with captive base stock supply, independent lubricant specialists with service-bundled retention models, and regional blenders competing on specification agility for emerging market upgrade cycles. Capacity reconfiguration and direct fleet contracting represent the dominant competitive vectors reshaping channel economics.
Among the integrated majors, ExxonMobil and Shell exemplify divergent strategic positioning within the same archetype. ExxonMobil anchors the condition-monitoring service tier through bundled analysis platforms that deepen fleet retention beyond bulk fluid transactions. Shell occupies the carbon-neutral product positioning tier, leveraging mass-balance certification to capture EU Green Deal-aligned procurement. BP's Castrol ON range represents the electrification-transition specialist archetype, capturing thermal-fluid demand as powertrain architectures fragment traditional lubricant pools. These three majors collectively illustrate how base stock integration, service bundling, and specification timing create defensible positions against mid-tier challengers.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP |
| Chevron Corporation |
| TotalEnergies |
| Castrol |
| Valvoline |
| Lukoil |
| Sinopec |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Middle Eastern refiners and private-equity-rolled-up blending specialists anchor feedstock ownership patterns that discipline pricing power across synthetic and conventional tiers, while long-drain service contracts and carbon-neutral certification premiums reshape how buyers value fluid economics beyond per-liter spot comparisons.
Pricing Analysis
Capacity additions in South Korea and the Middle East are reshaping price floors for Group III base stocks, compressing margins on premium synthetic formulations even as OEM factory-fill mandates sustain volume concentration. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy conventional levels stratifies by certification grade and drain-interval performance, with API SP and dexos licensing fees embedding fixed costs that disadvantage regional blenders. Pricing pressure stems from electric vehicle fluid substitution eroding traditional engine oil offtake in passenger OEM channels. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership modeling, while India's independent workshops remain most responsive to per-liter differentials.
Supply Chain Analysis
Freight cost volatility from Middle Eastern and Asian refinery hubs to European and North American blending plants exposes margin structures to bunker fuel index swings and canal transit constraints. Geographic supply concentration centers on South Korea, Saudi Arabia, and Singapore for Group III high-viscosity-index feedstocks, with Qatar and Malaysia expanding gas-to-liquids capacity. Raw material dependencies span polyalphaolefin base stocks, PAMA viscosity modifiers, and ZDDP anti-wear packages sourced from specialized chemical manufacturers. Single-source vulnerability concentrates in boron-free friction modifier supply chains as REACH authorization timelines stretch. Distribution runs through direct vendor-managed inventory programs for fleet accounts and traditional jobber-distributor networks for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on synthetic formulation premiums and service-bundled retention models that capture value beyond bulk fluid transactions, with electrification-transition fluid portfolios offering defensible positioning as powertrain architectures fragment.
For Market Incumbents: Acquire condition-monitoring platform capabilities and predictive maintenance software assets to deepen fleet retention against emerging digital-native competitors. Consolidate backward integration into Group III base stock supply through offtake agreements with Middle Eastern and Asian refiners, reducing exposure to freight volatility and tariff disruption. Defend factory-fill positioning by accelerating API SP and ACEA C-series certification investments ahead of Euro 7 compliance deadlines. For New Entrants and Emerging Players: Direct-to-fleet digital procurement portals offer the lowest friction entry path for synthetic volume capture in North American and European long-haul segments. Target India's semi-synthetic upgrade cycle in Maharashtra and Tamil Nadu independent workshops, where consumer education on drain-interval economics outpaces brand loyalty penetration. Lead with carbon-neutral mass-balance certification and telematics-triggered replenishment bundling to differentiate from legacy distributor relationships. For Investors and Strategic Acquirers: Integrated energy majors with captive base stock supply are the most active acquirers in this space, seeking additive-package specialists and regional blending assets to fill geographic gaps. Five-to-ten year viability hinges on electrified-thermal-fluid formulation capabilities that capture battery and e-axle lubricant demand as traditional engine oil volumes plateau. Monitor OEM thermal management fluid specification releases as the critical inflection signal for portfolio reweighting decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Long-drain Service Contract Expansion | Locks in synthetic volume commitments from commercial fleets through predictive maintenance bundling. |
| REACH-Compliant Additive Reformulation | Accelerates low-SAPS grade approvals for EU-27 factory-fill channels ahead of emissions deadlines. |
| Carbon-Neutral Product Line Certification | Captures EU Green Deal-aligned procurement premiums through mass-balance bio-based base stocks. |
| Direct Fleet Vendor-Managed Inventory | Disintermediates traditional jobber-distributor relationships via telematics-triggered replenishment. |
| Electrified-Thermal-Fluid R&D Investment | Positions for battery cooling and e-axle lubricant demand as powertrain electrification accelerates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blenders, fleet procurement managers, OEM platform engineers, and additive-package chemists with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up formulation-grade volume estimates triangulated against top-down regional consumption models derived from refinery output and import-export flows.
Segment-weighting approaches distributed value and volume across synthetic, semi-synthetic, and conventional chemistry tiers; passenger, commercial, motorcycle, and industrial engine applications; and viscosity grade specifications from 0W-20 through 15W-50. CAGRs were derived from regression analysis of historical specification turnover rates and OEM factory-fill mandate timelines, with electrification penetration curves and regulatory compliance deadlines as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for battery-electric vehicle penetration would alter the outlook for traditional engine oil demand trajectories. Forecasts reflect assumptions regarding REACH authorization timelines, base stock capacity expansion schedules, and fleet electrification commitments that carry revision risk from regulatory acceleration or delay. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Tire Mold Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Global Automotive Cup Holder Market