
 Manifold Assembly Market | 2026-2036
Manifold Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Manifold Assembly Market Insights
The manifold assembly market is restructuring around a widening gulf between precision-engineered aerospace-grade products and commodity hydraulic blocks for construction equipment. Parker Hannifin leverages its captive forging capacity to dominate high-pressure hydraulic manifold supply for mobile machinery. Swagelok sustains premium positioning through exacting surface-finish standards that command outsized margins in semiconductor and life-science fluid systems. Bosch Rexroth anchors European demand with integrated manifold-valve assemblies that reduce plumbing complexity in industrial automation.
A manifold assembly is a machined or cast metal block containing internal passages and ports that distribute fluids or gases among multiple components in a sealed system, typically machined from aluminum or ductile iron with port tolerances measured in micrometers. Its primary purpose is to consolidate plumbing, reduce leak points, and enable compact system design in fluid power and engine architectures. Casting still leads volume production for intake and exhaust manifolds in automotive and power generation equipment, while additive manufacturing is capturing prototype and low-run aerospace applications where topology-optimized internal channels improve thermal or flow performance. Machining dominates hydraulic and pneumatic manifolds where SAE or ISO port precision determines seal reliability under cyclic pressure loads.
The EPA enforces Tier 4 Final and emerging Stage V-aligned emissions rules that force redesigns of exhaust manifold geometry to accommodate exhaust gas recirculation and aftertreatment integration. ISO 4406 cleanliness standards and SAE J1926 port specifications shape product qualification requirements for hydraulic manifold suppliers serving mobile and industrial OEMs. Stakeholders must monitor how additive manufacturing qualification pathways at the FAA and EASA rewrite certification economics for aerospace manifold programs.
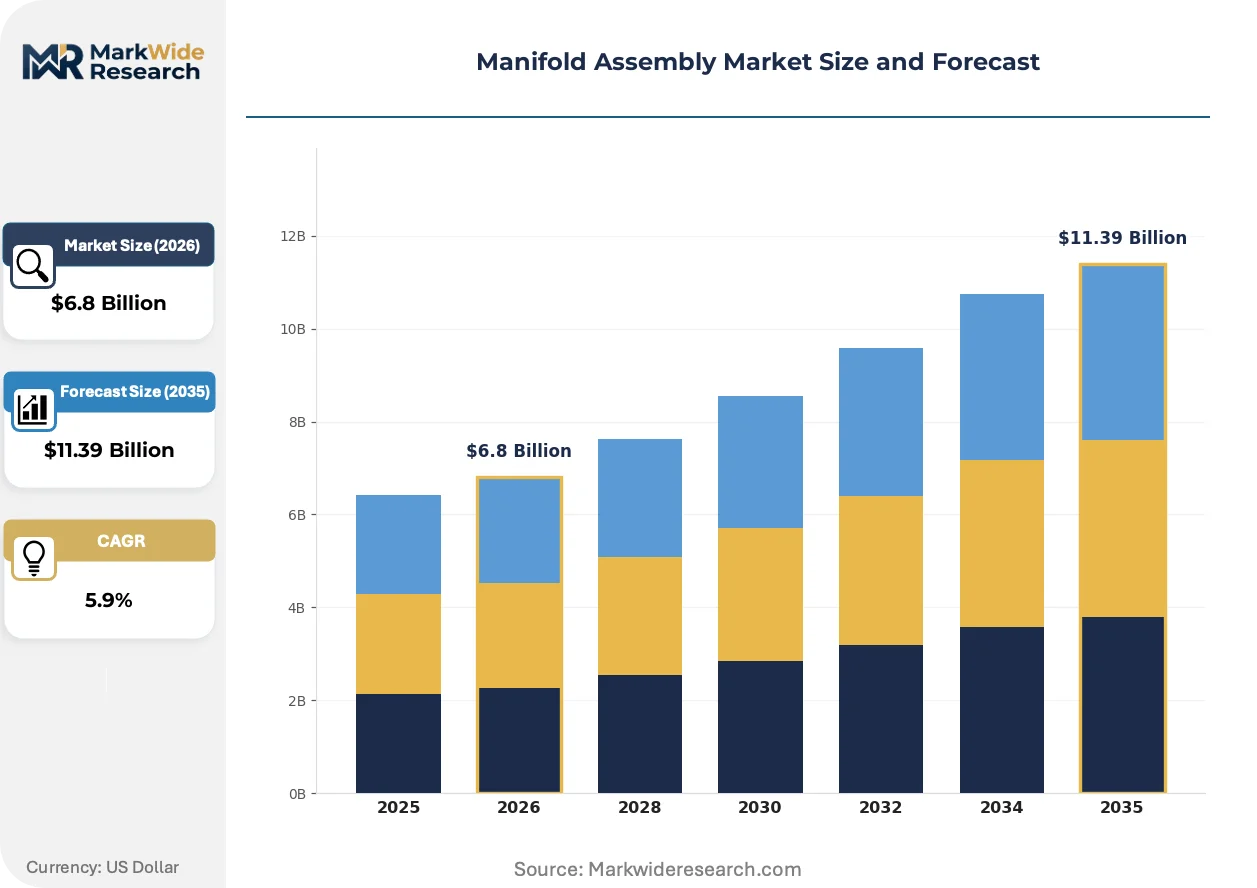
Market Dynamics
EPA Tier 4 Final and Stage V emissions mandates are forcing exhaust manifold redesigns to integrate exhaust gas recirculation and aftertreatment hardware, while hydraulic OEMs consolidate fluid power architectures around integrated manifold-valve assemblies to reduce leak points and assembly labor.
Growth Catalysts
- Stage V emissions alignment:European off-road diesel regulations compel exhaust manifold geometry changes that create replacement demand across agricultural and construction equipment fleets.
- Fluid power consolidation:Mobile machinery OEMs specify integrated manifold-valve assemblies to eliminate external plumbing and reduce warranty claims from connection failures.
- Stuttgart precision cluster:Germany's aerospace and automotive engineering concentration sustains demand for micrometer-tolerance manifold machining serving satellite propulsion and motorsport programs.
Market Restraints
- Aluminum ingot volatility:Input cost swings for aerospace-grade billet compress margin predictability for precision hydraulic manifold producers.
- Casting capacity concentration:Ductile iron foundry consolidation in specific industrial regions creates supply vulnerability for high-volume automotive intake manifold programs.
- Topology optimization barriers:Additive manufacturing qualification pathways at FAA and EASA remain unresolved, limiting aerospace adoption of lattice-structured cooling manifolds.
Strategic Opportunities
- Semiconductor fluid systems:Ultra-high purity manifold demand for wafer processing equipment creates premium pricing potential for surface-finish specialists.
- Life-science instrumentation:Diagnostic and bioprocessing OEMs specify electropolished stainless manifolds with documentation packages that command margin premiums.
- Industrial automation retrofit:Legacy pneumatic installations in Japanese and German factory automation present replacement demand for compact manifold-valve terminals.
Industry Challenges
- Multi-axis machining talent:Five-axis CNC programming expertise for complex port geometries remains scarce relative to demand from aerospace and medical device programs.
- Cleanliness certification timelines:ISO 4406 compliance documentation for hydraulic manifolds extends qualification cycles for suppliers entering mobile OEM supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manifold Assembly Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intake Manifolds, Exhaust Manifolds, Fuel Manifolds, Hydraulic Manifolds, Pneumatic Manifolds Technology: Casting, Machining, Additive Manufacturing, Forging, Welding Application: Power Generation Equipment, Heavy Machinery, Agricultural Equipment, Aerospace Systems, Marine Engines End User: Vehicle Manufacturers, Construction Equipment Producers, Aircraft OEMs, Marine Vessel Builders, Mining Companies |
| Companies Covered | Parker Hannifin, Swagelok, Emerson, Bosch Rexroth, HydraForce, Oliver Valves, Hy-Lok, DK-LOK, FITOK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manifold Assembly Market Trends and Innovations
Additive manufacturing is rewriting manifold design rules by enabling non-linear internal channels impossible with conventional drilling, while regulatory pressure on emissions and fluid cleanliness tightens qualification standards across end-use verticals.
Directed energy deposition and powder-bed fusion processes are expanding into aerospace manifold prototyping and low-rate production. Satellite propulsion and unmanned aerial vehicle manufacturers adopt topology-optimized aluminum and titanium manifolds that reduce weight by eliminating machining access constraints. The technology is expanding into qualification pathways at FAA and EASA that will determine whether additive manifolds achieve production scale or remain confined to repair and prototype applications.
EPA enforcement of Tier 4 Final standards and the EU's Stage V alignment for off-road diesel engines mandate exhaust manifold architectures that accommodate cooled exhaust gas recirculation and selective catalytic reduction dosing ports. Engine manufacturers redesign casting cores and machining fixtures to integrate these aftertreatment interfaces without compromising thermal fatigue performance. Agricultural and construction equipment OEMs in North America and Europe absorb the largest compliance costs, with smaller engine displacements facing proportionally higher redesign burdens.
Fluid power buyers increasingly specify documented cleanliness levels and traceable material certifications rather than accepting standard catalog products. Mobile machinery OEMs and semiconductor equipment manufacturers now require ISO 4406 particle count reports and material test certificates with each manifold shipment, shifting procurement criteria from price-per-port to total qualification reliability. This specification intensity is most pronounced in German automotive automation and Japanese precision equipment supply chains, where supplier quality documentation directly determines platform eligibility.
Manifold Assembly Market Segmentation
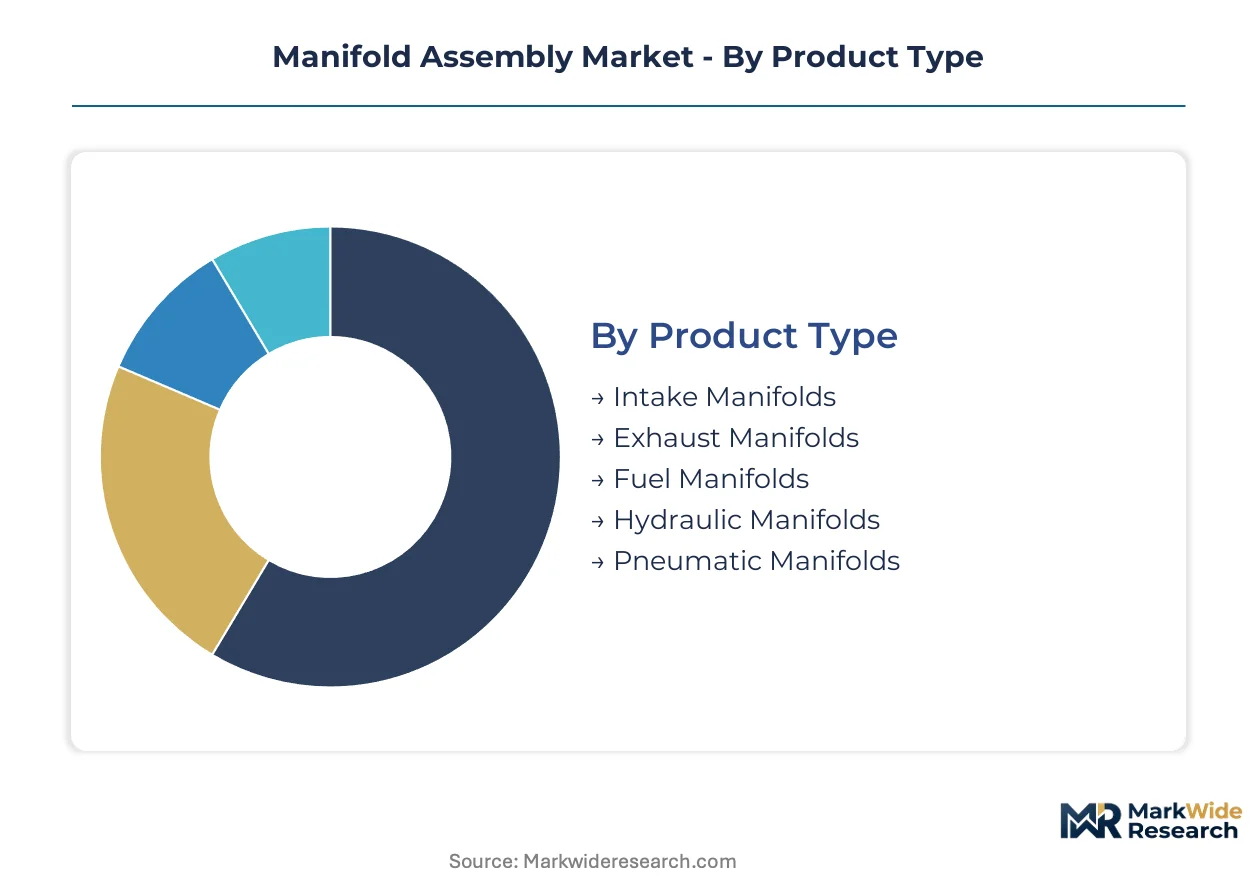
Manifold assembly segmentation reveals how manufacturing process constraints and end-use performance requirements create distinct competitive arenas. Product type and technology choices determine margin structures, while application and end-user categories expose where specification intensity concentrates procurement power.
Product Type:
The customization-to-standardization spectrum runs from engine-integrated castings with vehicle-specific geometries to catalog hydraulic blocks with SAE-standard port patterns.
- Intake Manifolds:These cast aluminum or composite components distribute air-fuel mixtures to cylinder heads with runner lengths tuned for torque curves. Demand clusters in Stuttgart and Munich automotive engineering corridors where OEMs specify variable-length runner systems for efficiency compliance.
- Hydraulic Manifolds:Machined from aluminum billet or ductile iron, these blocks consolidate valve functions with micrometer-tolerance SAE J1926 ports. Construction equipment fleets in Germany and mobile machinery OEMs in Japan drive specification intensity for integrated manifold-valve assemblies that eliminate external plumbing failure points.
- Exhaust Manifolds:Cast iron or stainless steel headers withstand thermal cycling while accommodating EGR and aftertreatment hardware mandated by EPA Tier 4 Final and EU Stage V regulations.
- Fuel Manifolds:Precision-machined rails deliver pressurized fuel to direct-injection systems with leakage tolerances measured in drops per hour.
- Pneumatic Manifolds:Anodized aluminum terminals distribute compressed air in factory automation with modular valve island integration.
Leading the category by volume: Intake Manifolds. Growing fastest: Hydraulic Manifolds.
Technology:
Cost tiers separate high-volume casting from precision machining and emerging additive methods, with capital intensity and batch size determining process selection.
- Machining:Five-axis CNC centers carve complex internal passages from solid billet with surface finishes critical for seal reliability under cyclic pressure. German and Japanese aerospace programs specify machined manifolds for satellite propulsion where porosity risks eliminate casting options.
- Casting:Sand and permanent mold processes dominate automotive intake and exhaust manifold volume with ductile iron and aluminum alloys. Foundry capacity concentration in specific industrial regions creates supply vulnerability for high-volume automotive programs.
- Additive Manufacturing:Powder-bed fusion builds topology-optimized aluminum and titanium manifolds with non-linear cooling channels impossible through drilling. FAA and EASA qualification pathways remain unresolved, limiting aerospace adoption to prototyping and repair.
- Forging:Closed-die forming produces grain-aligned high-pressure hydraulic blocks with fatigue resistance exceeding cast equivalents.
- Welding:Fabricated stainless headers serve aftermarket and racing applications with custom runner geometries.
Dominating by production volume: Casting. Expanding most quickly: Additive Manufacturing.
Application:
Customer maturity varies from specification-heavy aerospace to price-sensitive agricultural equipment, with certification burden and performance margins defining supplier relationships.
- Aerospace Systems:Satellite propulsion and UAV manifolds demand material traceability, NDT documentation, and weight-optimized designs. German precision engineering clusters around Munich supply micrometer-tolerance components for European space programs.
- Heavy Machinery:Construction and mining equipment integrate high-pressure hydraulic manifolds with documented ISO 4406 cleanliness levels. Japanese and German OEMs specify integrated manifold-valve assemblies to reduce warranty claims from connection failures.
- Power Generation Equipment:Stationary diesel and gas engines require exhaust manifolds with thermal fatigue resistance for continuous-duty cycles.
- Agricultural Equipment:Tractor and harvester programs absorb Stage V compliance costs with redesigned exhaust manifold architectures.
- Marine Engines:Saltwater corrosion resistance dictates stainless or bronze manifold specifications for commercial vessel propulsion.
Highest specification intensity: Aerospace Systems. Steepest volume expansion: Heavy Machinery.
End User:
Procurement patterns diverge between OEMs with captive design engineering and aftermarket buyers sourcing replacement catalogs.
- Vehicle Manufacturers:Automotive and commercial truck OEMs specify intake and exhaust manifolds with platform-common architectures across model ranges. German automotive automation supply chains demand supplier quality documentation that directly determines platform eligibility.
- Aircraft OEMs:Airframe and engine manufacturers impose material certification packages and process approvals that extend qualification cycles. EASA oversight of additive manufacturing pathways shapes supplier selection for next-generation manifold designs.
- Construction Equipment Producers:Mobile machinery OEMs consolidate fluid power architectures around integrated manifold-valve terminals with documented cleanliness levels.
- Marine Vessel Builders:Shipyards source classification-society-approved manifolds for propulsion and auxiliary systems.
- Mining Companies:Fleet operators specify hardened hydraulic manifolds for extreme-duty excavators and haul trucks with field-replaceable cartridge valves.
Commanding premium pricing: Aircraft OEMs. Driving standardization pressure: Vehicle Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manifold machining for aerospace and automotive programs, with Munich's engineering corridor sustaining demand for micrometer-tolerance fluid systems.
Germany
Baden-Württemberg and Bavaria concentrate exhaust manifold redesigns for Stage V compliance in agricultural equipment. The KBA enforces emissions alignment that forces casting geometry changes. Stuttgart's precision engineering cluster supplies satellite propulsion manifolds for European space programs with documented NDT certification.
United States
Construction equipment fleets in the Midwest and Southeast specify integrated hydraulic manifold-valve assemblies. The EPA Tier 4 Final mandates exhaust manifold architectures accommodating EGR and aftertreatment hardware. Houston's energy corridor sources high-pressure hydraulic blocks for oilfield service applications.
Japan
Factory automation OEMs in Aichi and Kanagawa prefectures drive pneumatic manifold-valve terminal demand. METI industrial standards shape cleanliness documentation requirements for hydraulic suppliers. Nagoya's precision manufacturing belt sustains five-axis CNC capacity for complex port geometries.
China
Mobile machinery producers in Jiangsu and Shandong provinces absorb commodity hydraulic manifold volume. MIIT equipment standards accelerate domestic casting capacity expansion for construction equipment supply chains. Suzhou's industrial zone hosts machining operations serving semiconductor fluid system demand.
India
Mining fleet operators in Jharkhand and Odisha specify hardened hydraulic manifolds for extreme-duty excavators. BIS certification requirements extend qualification timelines for suppliers entering mobile OEM supply chains. Pune's automotive corridor develops casting capabilities for commercial vehicle intake programs.
Manifold Assembly Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with aerospace-grade documentation commanding outsized returns compared to catalog hydraulic blocks. The vendor base stratifies into three tiers: integrated fluid power conglomerates with captive forging, precision specialists with surface-finish differentiation, and regional fabricators competing on port-count economics. Dominant competitive moves include backward integration into aluminum billet supply and strategic partnerships with additive manufacturing qualification bodies.
Among diversified industrial conglomerates, Parker Hannifin and Emerson exemplify scale-driven positions spanning hydraulic and pneumatic architectures. Bosch Rexroth anchors European demand through integrated manifold-valve assemblies that reduce plumbing complexity. These three entities represent distinct archetypes: captive forging capacity, multi-industry portfolio breadth, and European automation anchoring respectively.
| Leading Market Players |
|---|
| Parker Hannifin |
| Swagelok |
| Emerson |
| Bosch Rexroth |
| HydraForce |
| Oliver Valves |
| Hy-Lok |
| DK-LOK |
| FITOK |
| Others |
Pricing and Supply Chain Analysis
Aerospace-grade certification tiers create a three-tier pricing structure across premium, standard, and economy levels that simultaneously fragments supplier bases and concentrates procurement power among documented cleanliness specialists. This divergence forces commodity hydraulic block producers to absorb aluminum billet volatility while precision machinists in Stuttgart and Nagoya capture margin premiums through ISO 4406 compliance packages.
Pricing Analysis
Value-based pricing anchors on documented uptime and warranty claim reduction for integrated manifold-valve assemblies in mobile machinery fleets. Price differentiation rests on certification grade—ISO 4406 cleanliness tiers versus standard catalog offerings—and customization level for port geometries. Pricing pressure stems from casting capacity concentration in ductile iron foundries serving high-volume automotive programs. Construction equipment OEMs exhibit highest price sensitivity, while semiconductor fluid system buyers prioritize surface-finish documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with ductile iron foundry consolidation in Germany and China, where automotive intake manifold programs face disruption risk from regional capacity constraints. Raw material dependencies draw from aerospace-grade aluminum billet, ductile iron ingot, and titanium powder for additive prototyping. Supply chain risk centers on tariff exposure for precision-machined components crossing between German engineering clusters and Japanese factory automation OEMs. Distribution runs through direct OEM supply agreements for qualified suppliers and industrial distributor networks for catalog hydraulic blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V emissions mandates have erected a cost-of-compliance moat that rewards incumbent players with documented qualification pathways while screening out undercapitalized entrants lacking certification infrastructure.
For Market Incumbents: Deepen backward integration into aluminum billet supply to compress input cost volatility exposure from aerospace-grade material markets. Expand captive forging capacity in Baden-Württemberg to defend against emerging additive manufacturing specialists seeking FAA qualification shortcuts. Prioritize ISO 4406 documentation automation to accelerate qualification cycles for mobile OEM supply chains. For New Entrants and Emerging Players: Semiconductor fluid system OEMs represent the most penetrable buyer archetype given surface-finish specification intensity that outstrips incumbent capacity expansion. Target life-science instrumentation manufacturers requiring electropolished stainless manifolds with traceable material certifications. Pursue strategic partnerships with additive manufacturing qualification bodies to bypass traditional machining barrier-to-entry economics. For Investors and Strategic Acquirers: Re-rating potential sits with precision machining specialists given Stage V compliance-driven exhaust manifold redesign demand across European agricultural equipment. Long-term viability favors suppliers with demonstrated FAA and EASA additive qualification progress. Monitor EASA additive manufacturing pathway resolutions as the critical inflection signal for aerospace manifold production scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive aluminum sourcing insulates margin predictability against aerospace-grade material price swings. |
| ISO 4406 Documentation Automation | Accelerated cleanliness certification reduces qualification cycles for German mobile machinery OEMs. |
| Additive Manufacturing Qualification Partnership | FAA and EASA pathway alignment unlocks topology-optimized aerospace manifold production scale. |
| Semiconductor Fluid System Capacity Expansion | Ultra-high purity surface-finish capabilities capture wafer processing equipment premium pricing. |
| Stage V Compliance Casting Investment | Exhaust manifold geometry redesign demand from KBA enforcement sustains automotive program volumes. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC regulatory disclosures formed the secondary backbone for this analysis. Primary interviews with hydraulic manifold procurement managers at construction equipment OEMs, precision machining program directors in German aerospace clusters, fluid power distribution channel partners, and EPA compliance engineering leads combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis established baseline growth patterns across product type, technology, application, and end-user dimensions over the projection horizon. CAGRs were derived from segment-level volume and value modeling that incorporated equipment fleet replacement cycles, emissions regulation phase-in schedules, and additive manufacturing qualification timeline assumptions. Industry-specific forecast inputs included Stage V compliance-driven exhaust manifold redesign demand and semiconductor capital expenditure patterns for fluid system content.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAA and EASA additive manufacturing qualification resolutions and aluminum ingot price volatility. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and OEM supply chain consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
China and Saudi Arabia Automotive Market