
 Engine Piston Ring Set Market | 2026-2036
Engine Piston Ring Set Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Piston Ring Set Market Insights
Skilled tool-and-die craftsmanship is collapsing across traditional manufacturing bases, forcing ring producers to automate precision grinding or relocate technical talent. MAHLE leverages its captive foundry network to sustain margin control across European OEM supply agreements. Tenneco competes through vertical integration into thermal coating technologies, while Riken Corporation anchors Japanese domestic demand with specialized marine engine specifications. Shriram Pistons & Rings dominates India's aftermarket channel through localized cast-iron forging capacity.
An engine piston ring set comprises multiple circular metallic seals installed within internal combustion engine grooves to regulate cylinder pressure, lubricant distribution, and thermal expansion. Compression rings typically achieve radial wall thickness tolerances of 0.01 mm and operate against cylinder bore surfaces exceeding 200°C, functioning primarily to seal combustion gases and transfer heat from the piston to the cylinder wall. Cast iron and steel alloy material categories occupy the mature volume base, whereas molybdenum coated segments capture expanding share in heavy-duty equipment applications where scuffing resistance determines overhaul intervals. Light-duty vehicle demand for tapered rings faces substitution pressure from electrification, concentrating margin pools in oil control rings serving engine remanufacturers with extended warranty requirements.
EPA emission standards and NHTSA fuel economy mandates in the United States compel tighter ring-to-bore clearances and advanced coating chemistries, while China's MIIT enforces national VI emission tiers that elevate oil control ring performance thresholds. India's BIS material certification framework restricts uncertified cast-iron imports, channeling procurement toward domestic qualified suppliers. Stakeholders must monitor regulatory divergence between Euro VII preparatory standards and China's dual carbon implementation timeline to calibrate coating technology investments and geographic manufacturing allocation.
Market Dynamics
Commercial vehicle fleets in Asia-Pacific are extending engine overhaul cycles from 500,000 to 800,000 kilometers, forcing ring suppliers to recalibrate coating durability specifications and thermal management architectures.
Growth Catalysts
- MIIT National VI Emission Tiers:China's Ministry of Industry and Information Technology mandates elevated oil control ring performance thresholds, accelerating chrome-to-molybdenum coating transitions across heavy-duty diesel engine production lines.
- India's Automotive Remanufacturing Corridor:BIS-certified cast-iron forging capacity concentrates in Pune-Chennai industrial clusters, channeling aftermarket procurement toward domestic qualified suppliers with extended warranty capabilities.
- Marine Engine Specifications:Specialized two-stroke and four-stroke marine applications in Japanese and South Korean shipbuilding demand segmented oil control rings with enhanced corrosion resistance in salt-laden combustion environments.
Market Restraints
- Tool-and-Die Craftsmanship Collapse:Precision grinding expertise is vanishing from traditional European and North American manufacturing bases, forcing automation investments or technical talent relocation to Eastern European and Mexican facilities.
- Electrification Substitution:Battery electric vehicle powertrain proliferation in light-duty passenger segments is compressing demand for tapered compression rings, concentrating volume in commercial vehicle and off-highway equipment categories.
- Chrome Plating Regulatory Friction:REACH restrictions on hexavalent chromium compounds in European coating processes are elevating capital requirements for alternative thermal spray deposition systems.
Strategic Opportunities
- Indonesia Mining Equipment Fleet:Nickel and coal extraction operations are expanding heavy-duty equipment parc size, creating aftermarket demand for scuffing-resistant molybdenum-coated ring sets in tropical humidity conditions.
- Dual Carbon Implementation Timeline:China's national carbon peak and neutrality goals are incentivizing remanufacturing over new engine production, extending ring replacement cycles with premium coating specifications.
- Digital Fleet Management Convergence:Integration of telematics-based oil consumption monitoring with predictive maintenance platforms is enabling condition-based ring replacement scheduling for logistics operators.
Industry Challenges
- Radial Wall Tolerance Maintenance:Achieving consistent 0.01 mm precision in automated grinding systems requires multi-axis CNC retrofitting that strains mid-tier supplier capital allocation.
- BIS Certification Timeline Compression:India's Bureau of Indian Standards material qualification process for cast-iron imports creates 12-18 month approval windows that mismatch with just-in-time OEM supply requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Piston Ring Set Market |
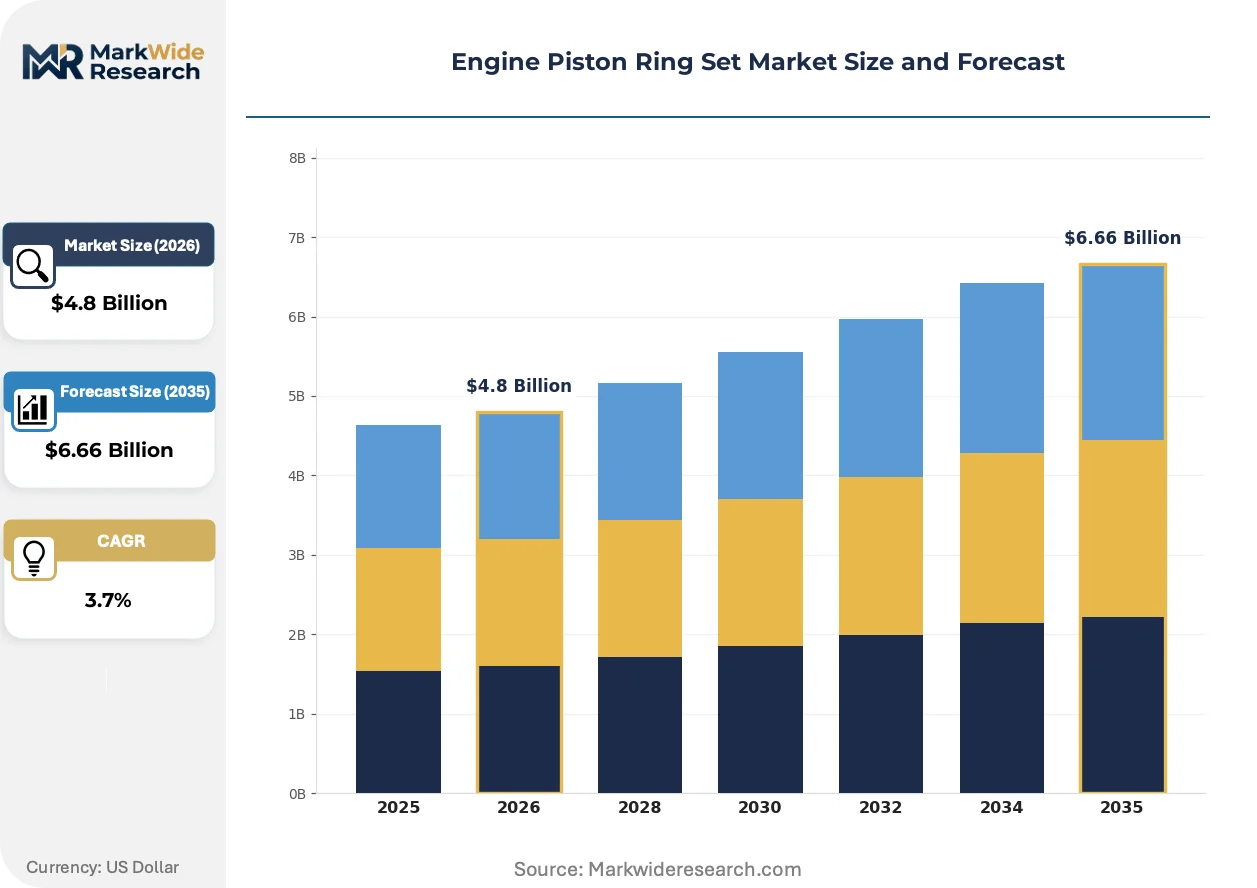
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Rings, Oil Control Rings, Scraper Rings, Tapered Rings Material: Cast Iron, Steel Alloy, Chrome Plated, Molybdenum Coated Application: Light-Duty Vehicles, Heavy-Duty Equipment, Off-Road Vehicles, Marine Engines End User: Vehicle Assemblers, Engine Remanufacturers, Aftermarket Suppliers, Industrial Machinery Makers |
| Companies Covered | Nippon Piston Ring, Tenneco, MAHLE, TPR, Shriram Pistons & Rings, Riken Corporation, Denso, Hastings Manufacturing, Weifu High-Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Piston Ring Set Market Trends and Innovations
Thermal coating chemistries and precision manufacturing automation are converging to redefine durability benchmarks across commercial vehicle engine architectures.
Physical vapor deposition molybdenum coatings achieve 40% superior scuffing resistance compared to traditional chrome plating in high-load diesel applications. Heavy-duty equipment manufacturers in Germany and the United States are specifying these coatings for engines targeting million-kilometer overhaul intervals. Chrome plating is supplanting earlier-generation ferrous coatings in emerging market production, though REACH-compliant alternatives are gaining traction in European supply chains.
EPA emission standards and NHTSA fuel economy mandates compel tighter ring-to-bore clearances below 0.03 mm in US-market engines. These specifications are elevating cylinder bore honing requirements and ring surface finish complexity across Detroit Three supplier networks. Oil control ring designs with increased drain hole density are proliferating to meet particulate matter reduction targets without sacrificing lubricant retention.
Fleet operators are consolidating aftermarket procurement through authorized dealer networks rather than independent distributors. This channel compression is elevating volume concentration among ring suppliers with captive foundry and coating capabilities. India's commercial vehicle aftermarket exhibits the most pronounced consolidation, with organized workshops capturing share from roadside mechanics in major highway corridors.
Engine Piston Ring Set Market Segmentation
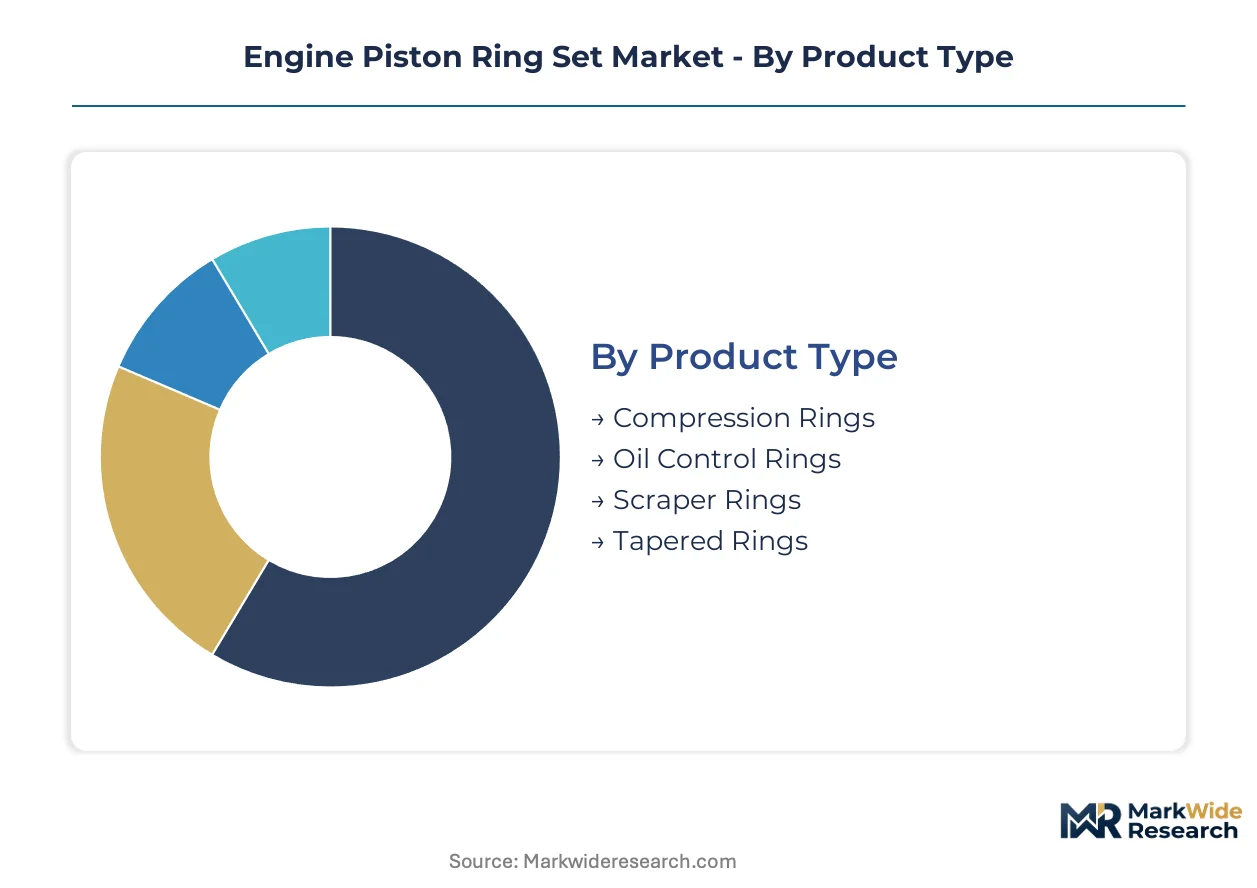
Piston ring set segmentation reveals how coating technologies, material specifications, and duty-cycle requirements fragment procurement patterns across OEM and aftermarket channels. Regulatory thresholds on oil consumption and particulate emissions are redefining which ring configurations command premium positioning versus commodity volume.
Product Type:
EPA and NHTSA mandates in the United States, MIIT National VI tiers in China, and Euro VII preparatory standards each impose distinct oil control and blow-by specifications that favor different ring geometries.
- Compression Rings:These primary sealing elements maintain combustion pressure with radial wall tolerances of 0.01 mm and operate against cylinder surfaces exceeding 200°C. Demand concentrates in heavy-duty diesel engines across Germany and the United States, where million-kilometer overhaul intervals require heat-transfer optimization.
- Oil Control Rings:Multi-piece designs with increased drain hole density regulate lubricant film thickness to meet particulate matter targets. China's commercial vehicle fleets are extending replacement cycles from 500,000 to 800,000 kilometers, elevating specifications for scuffing resistance in molybdenum-coated variants.
- Scraper Rings:Secondary sealing elements remove excess oil from cylinder walls in two-stroke marine applications.
- Tapered Rings:Face-profile geometries for light-duty gasoline engines face substitution pressure from battery electric vehicle proliferation.
Established volume favors compression rings; emerging adoption favors oil control rings.
Material:
Cost tier differentiation separates foundry-cast volume production from thermal-spray premium coating investments.
- Cast Iron:Gray and ductile iron alloys dominate aftermarket replacement volumes through established forging networks. India's BIS certification framework channels procurement toward domestic qualified suppliers in Pune-Chennai industrial clusters with extended warranty capabilities.
- Steel Alloy:Higher-strength substrates enable reduced radial wall thickness for tighter ring-to-bore clearances below 0.03 mm. Detroit Three supplier networks specify these for EPA-compliant fuel economy architectures.
- Chrome Plated:Traditional electrolytic coatings face REACH restriction pressures across European coating processes.
- Molybdenum Coated:Physical vapor deposition achieves 40% superior scuffing resistance in high-load diesel applications.
Cast iron and steel alloys anchor volume economics; molybdenum coatings capture margin expansion in extended-warranty segments.
Application:
Customer type fragmentation separates fleet-operator procurement consolidation from individual owner-operator replacement patterns.
- Heavy-Duty Equipment:Mining, construction, and agricultural machinery operate in abrasive dust and tropical humidity conditions. Indonesia's nickel and coal extraction fleet expansion is creating aftermarket demand for corrosion-resistant ring sets with enhanced drain hole configurations.
- Marine Engines:Two-stroke and four-stroke specifications from Japanese and South Korean shipbuilding demand segmented oil control rings with salt-laden combustion resistance.
- Light-Duty Vehicles:Passenger car and light truck production faces powertrain electrification displacement.
- Off-Road Vehicles:Recreational and utility equipment maintains steady replacement demand through independent distributor channels.
Heavy-duty equipment represents the steepest expansion trajectory; light-duty vehicles face structural compression.
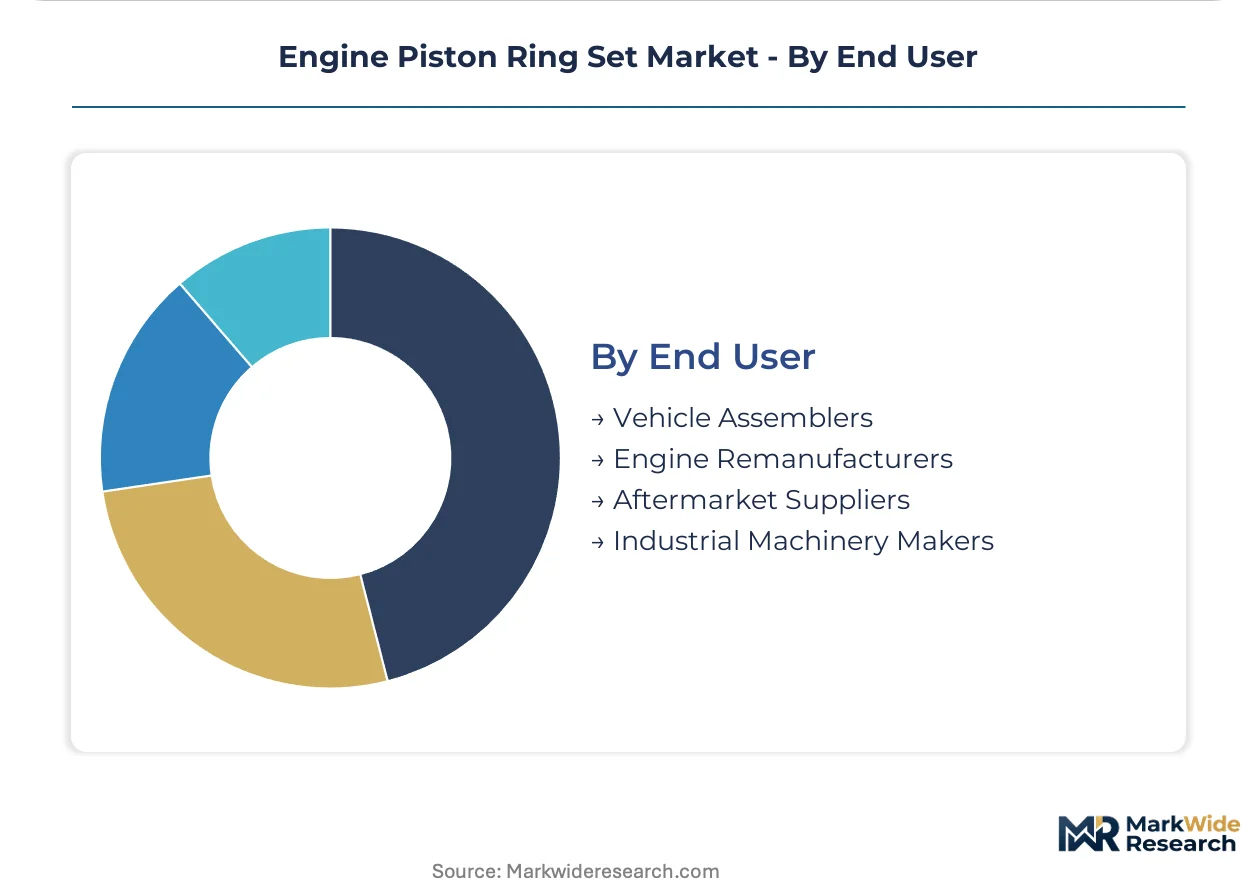
End User:
Supply concentration in captive foundry and coating capabilities determines channel access across consolidated procurement networks.
- Engine Remanufacturers:China's dual carbon implementation timeline incentivizes remanufacturing over new engine production, extending ring replacement cycles with premium coating specifications. These operators require BIS-certified cast-iron forging capacity with 12-18 month qualification windows.
- Vehicle Assemblers:OEM supply agreements demand just-in-time delivery with radial wall tolerance maintenance through automated multi-axis CNC grinding systems.
- Aftermarket Suppliers:India's organized workshop consolidation is capturing share from roadside mechanics in major highway corridors.
- Industrial Machinery Makers:Stationary engine and compressor applications specify standardized ring sets through authorized dealer networks.
Engine remanufacturers are gaining share fastest; vehicle assemblers maintain volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German and US fleets prioritize million-kilometer overhaul intervals with premium coating specifications, while Indian and Indonesian operators emphasize cost-efficient cast-iron replacement cycles in abrasive operating conditions.
United States
Detroit Three supplier networks drive demand for steel alloy compression rings with sub-0.03 mm ring-to-bore clearances. EPA emission standards and NHTSA fuel economy mandates compel advanced coating chemistries and precision surface finishes. Manufacturing concentrates in Michigan-Ohio industrial corridors where automated CNC grinding systems maintain radial wall tolerances.
Germany
Heavy-duty equipment manufacturers specify physical vapor deposition molybdenum coatings for extended-warranty engine architectures. REACH restrictions on hexavalent chromium compounds are elevating capital requirements for alternative thermal spray deposition systems. Production clusters in Baden-Württemberg and North Rhine-Westphalia anchor European coating technology development.
China
Commercial vehicle fleets are extending replacement cycles from 500,000 to 800,000 kilometers, forcing recalibration of oil control ring durability specifications. MIIT National VI emission tiers mandate elevated oil control performance thresholds, accelerating chrome-to-molybdenum transitions. Heavy-duty equipment supply chains concentrate in Yangtze River Delta manufacturing bases serving domestic and export markets.
India
Automotive remanufacturing corridors in Pune-Chennai industrial clusters channel aftermarket procurement toward BIS-certified cast-iron forging capacity. The Bureau of Indian Standards material qualification process creates 12-18 month approval windows that mismatch with just-in-time OEM requirements. Organized workshop networks are capturing share from roadside mechanics in major highway corridors.
Indonesia
Nickel and coal extraction operations are expanding heavy-duty equipment parc size, creating aftermarket demand for corrosion-resistant ring sets. Tropical humidity conditions necessitate enhanced drain hole configurations in oil control ring designs. Mining equipment fleets operate in abrasive dust environments that accelerate ring replacement cycles compared to temperate climate benchmarks.
Engine Piston Ring Set Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry and coating capabilities determining channel access across consolidated procurement networks. The upper tier commands OEM supply agreements through automated precision grinding and thermal spray technology ownership. Mid-tier players compete on BIS-certified cast-iron forging capacity and regional aftermarket distribution density. Dominant competitive moves include backward integration into upstream material processing and geographic relocation of technical talent to Eastern European and Mexican facilities.
Among Japanese specialists, Nippon Piston Ring and Riken Corporation exemplify the marine-engine specification tier, anchoring domestic demand for segmented oil control rings with salt-laden combustion resistance. Tenneco occupies a position within the thermal coating technology vector, representing vertical integration archetypes that compete through in-house deposition system ownership. These three names illustrate how geographic origin and technology specialization stratify competitive positioning across OEM and aftermarket channels.
| Leading Market Players |
|---|
| Nippon Piston Ring |
| Tenneco |
| MAHLE |
| TPR |
| Shriram Pistons & Rings |
| Riken Corporation |
| Denso |
| Hastings Manufacturing |
| Weifu High-Precision |
| Others |
Pricing and Supply Chain Analysis
Chrome-to-molybdenum coating transitions across heavy-duty diesel production lines simultaneously relocate supply gravity toward Yangtze River Delta manufacturing bases and compress pricing premiums for legacy electrolytic coatings. This substitution dynamic concentrates procurement leverage among foundry-integrated suppliers while fragmenting margin pools for coating-dependent specialists.
Pricing Analysis
Long-term offtake agreements dominate OEM supply relationships, with annual volume commitments securing preferential molybdenum deposition capacity allocation. Three-tier pricing structure across premium, standard, and economy levels separates physical vapor deposition specifications from chrome-plated alternatives and uncertified cast-iron volume. Cost compression in standard-tier segments is intensifying because REACH-compliant thermal spray systems elevate European production overhead. Fleet operators exhibit lowest price sensitivity due to warranty-integrated procurement, whereas independent aftermarket distributors face acute margin pressure from organized workshop consolidation.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo trade lanes elevates inbound logistics costs for ferroalloy raw materials sourced from Australian and South African mining operations. Foundry capacity concentrates in China, India, and Germany, with precision grinding equipment dependencies resting on Japanese and Swiss machine tool suppliers. Single-source vulnerability characterizes physical vapor deposition chamber procurement from specialized European equipment manufacturers. Distribution runs through authorized dealer networks rather than independent channels, compressing aftermarket access for non-integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance platforms are transforming ring replacement from interval-based to condition-triggered procurement, creating platform-economics inflection where data interoperability determines supplier lock-in.
For Market Incumbents: Consolidate captive foundry and coating capabilities to defend against emerging thermal spray specialists in Eastern Europe. Prioritize multi-axis CNC grinding automation to offset collapsing tool-and-die craftsmanship in traditional manufacturing bases. Secure BIS certification pathways in India's Pune-Chennai corridor before qualification timeline compression locks out late entrants.
For New Entrants and Emerging Players: BIS fast-track certification for cast-iron forging capacity opens India's organized workshop networks, the most penetrable aftermarket channel. Target Indonesia's nickel extraction fleet expansion with corrosion-resistant oil control ring configurations. Pursue joint development agreements with mining equipment OEMs to bypass established distributor relationships.
For Investors and Strategic Acquirers: The market sits at a coating-technology transition phase that favors foundry-integrated mid-caps with thermal spray deposition ownership. Long-term viability hinges on exposure to commercial vehicle electrification resilience and remanufacturing cycle extension. Monitor MIIT National VII preparatory standards as inflection signal for next-generation oil control ring specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | MAHLE's foundry network sustains margin control across European OEM supply agreements. |
| Thermal Spray Deposition Technology Investment | Tenneco's in-house coating systems compete through REACH-compliant alternative chemistries. |
| Geographic Relocation of Precision Grinding Operations | Eastern European and Mexican facilities capture technical talent fleeing collapsed craftsmanship bases. |
| BIS Certification Fast-Track for Cast-Iron Forging | Shriram Pistons & Rings dominates India's aftermarket through localized qualification advantage. |
| Telematics Platform Integration for Predictive Maintenance | Fleet operator data convergence enables condition-based ring replacement scheduling. |
Research Methodology
A standing panel of Tier 1 supplier procurement managers, aftermarket distributor operations heads, foundry technical directors, and commercial vehicle fleet maintenance officers provided ongoing calibration throughout data collection. Primary interview insights combined with secondary validation from customs trade databases, MIIT emission standard filings, BIS certification registries, and vehicle production statistics. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. Analytical framework segmented by ring type, coating technology, material substrate, application duty cycle, and end-user procurement channel. CAGRs derived from regression analysis of historical replacement patterns and regulatory-driven specification shifts. Industry-specific inputs included commercial vehicle parc expansion rates and marine engine order backlogs from Japanese and South Korean shipbuilders.
Decision-makers should treat outputs as directional under assumptions of sustained commercial vehicle utilization intensity and stable regulatory implementation timelines; material deviation would warrant model refresh. Specific risk factors include accelerated battery electric vehicle penetration in light-duty segments and REACH restriction expansion beyond hexavalent chromium compounds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Drum Brake Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Automotive Engine Cooling Fan Market