
 Autocatalyst Market | 2026-2036
Autocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Autocatalyst Market Intelligence
Emission-compliance subscription services is pivoting how catalyst suppliers monetize their hardware, shifting from one-time component sales to ongoing performance-guarantee contracts. BASF SE leverages its precious-metal trading desk to hedge platinum-group-metal volatility for fleet operators. Johnson Matthey anchors European supply through its Royston manufacturing complex, while Umicore competes on closed-loop recycling economics that recover palladium from spent substrates.
An autocatalyst is a ceramic or metallic substrate coated with platinum-group metals and rare-earth oxide promoters, engineered to convert carbon monoxide, hydrocarbons, and nitrogen oxides into benign exhaust constituents at operating temperatures between 200°C and 600°C. Three-way catalysts dominate passenger-car applications where stoichiometric engine control enables simultaneous NOx, CO, and HC reduction. Selective catalytic reduction systems for heavy-duty vehicles command premium pricing due to urea-dosing complexity and durability requirements under sustained high-load operation.
The US EPA and California Air Resources Board enforce Tier 3 and LEV III standards that mandate near-zero tailpipe emissions, directly dictating catalyst volume and PGM loading per vehicle. Europe's EMA coordinates Euro 7 technical discussions that will extend cold-start emission controls, while China's MEE implements China VI-b standards requiring onboard emissions monitoring. Stakeholders must track regulatory divergence between these jurisdictions to optimize single-platform catalyst architectures against compliance fragmentation.
Market Dynamics
Platinum-group metal price volatility and tightening emission ceilings are compressing catalyst economics, forcing suppliers to reengineer substrate geometries and metal loadings simultaneously.
Growth Catalysts
- China VI-b enforcement:China's MEE mandates onboard emissions diagnostics, expanding catalyst replacement cycles and hardware complexity for domestic OEMs.
- Heavy-duty fleet electrification lag:Diesel commercial vehicles retain internal combustion architectures longer than passenger segments, sustaining demand for SCR and DOC systems.
- Closed-loop recycling infrastructure:Urban mining of palladium from spent autocatalysts in Germany's industrial corridor reduces virgin metal dependency.
Market Restraints
- PGM supply concentration:South African platinum and Russian palladium dominate mined output, exposing fabricators to geopolitical supply shocks.
- Euro 7 cold-start requirements:Extended emission controls below 200°C demand additional catalyst volume and electrically heated substrates, raising per-unit costs.
- Electric vehicle substitution:Battery-electric powertrains eliminate exhaust systems entirely, eroding addressable market in premium passenger segments.
Strategic Opportunities
- India BS-VI Phase 2:Tighter particulate limits for commercial vehicles create first-mover advantage for suppliers establishing local coating capacity.
- Hydrogen combustion engines:NOx aftertreatment for H2-ICE prototypes requires modified catalyst formulations with reduced oxygen storage components.
- Performance-guarantee contracting:Fleet operators in Japan's logistics sector now prefer emissions-compliance subscriptions over component purchases.
Industry Challenges
- PGM trading desk expertise:Catalyst manufacturers lack in-house precious metal hedging capabilities, exposing margins to spot market swings.
- Platform engineering timelines:OEM powertrain redesign cycles compress from 72 to 48 months, accelerating catalyst validation schedules.
- Substrate thermal durability:Next-generation gasoline particulate filters must survive 1,050°C regeneration events without structural degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autocatalyst Market |
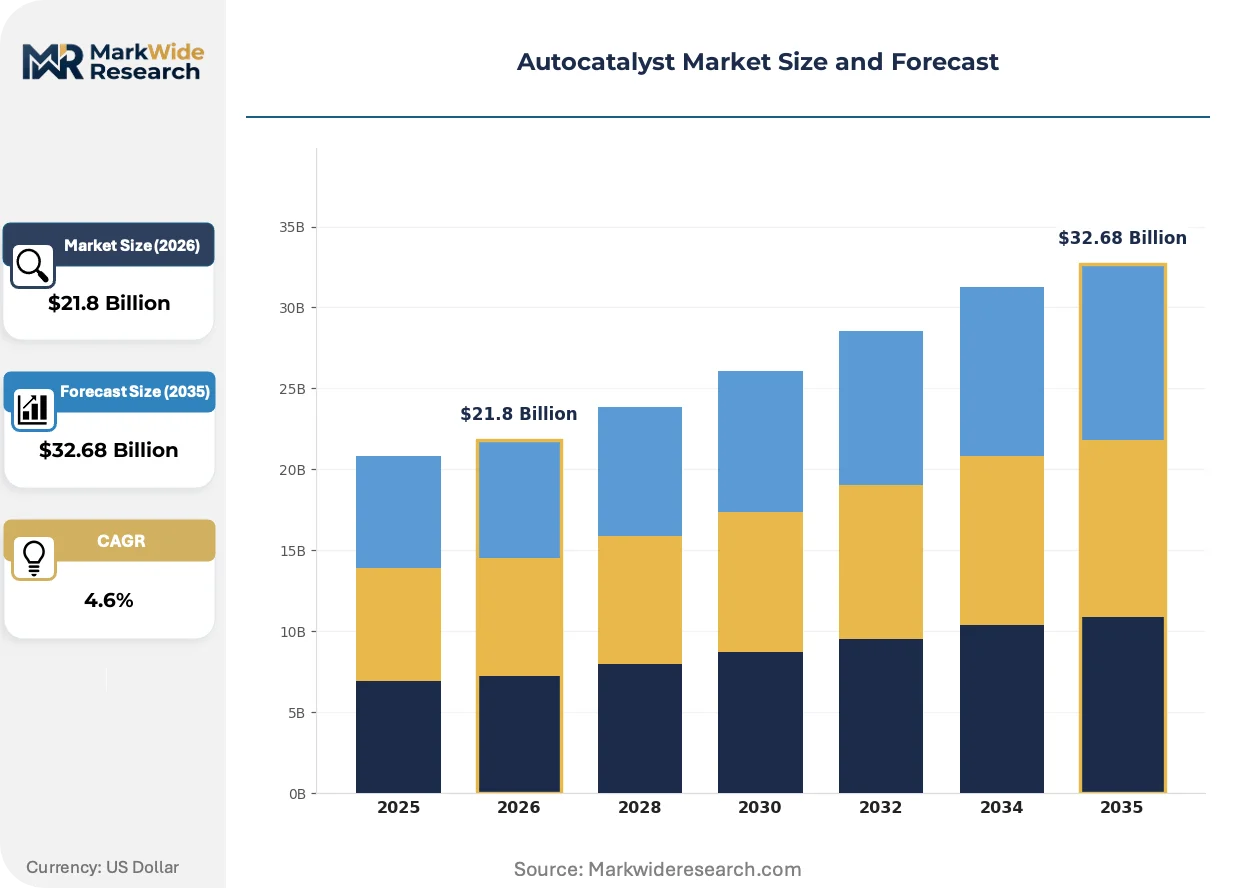
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Palladium, Platinum, Rhodium, Others End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy Machinery Technology: Selective Catalytic Reduction, Lean NOx Trap, Three-Way Catalysts, Oxidation Catalysts Application: Light-Duty Vehicles, Heavy-Duty Vehicles, Off-Road Equipment, Marine Applications |
| Companies Covered | Cataler Corporation, Tenneco Inc., BASF SE, Denso Corporation, Eberspächer Gruppe GmbH & Co. KG, Johnson Matthey, Forvia SE, Clariant, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autocatalyst Market Strategic Shifts & Innovations
Substrate architecture and coating chemistry are converging to deliver higher conversion efficiency at lower metal loadings, reshaping competitive advantage around materials science rather than scale.
Advanced ceramic wall-flow substrates with asymmetric channel geometries are consolidating technical leadership in gasoline particulate filter applications. European OEMs adopting these designs for Euro 7 compliance are reducing backpressure penalties while maintaining soot capture efficiency. The technology is consolidating supplier hierarchies around firms with in-house extrusion and coating integration.
California's Air Resources Board LEV IV proposal extends zero-emission vehicle mandates while tightening remaining combustion fleet allowances. This dual pressure accelerates catalyst obsolescence risk for products not designed for sub-100 mg/mile NOx performance. Heavy-duty engine manufacturers are responding with dual-dosing SCR architectures and ammonia slip catalyst additions.
Fleet procurement departments now bundle catalyst replacement with telematics-based emissions monitoring, unbundling hardware from compliance verification. Logistics operators in Germany's Rhine-Ruhr corridor prefer suppliers offering guaranteed uptime rather than component warranties. This reconfiguration shifts margin capture toward service layers and away from manufacturing scale.
Autocatalyst Market Segmentation
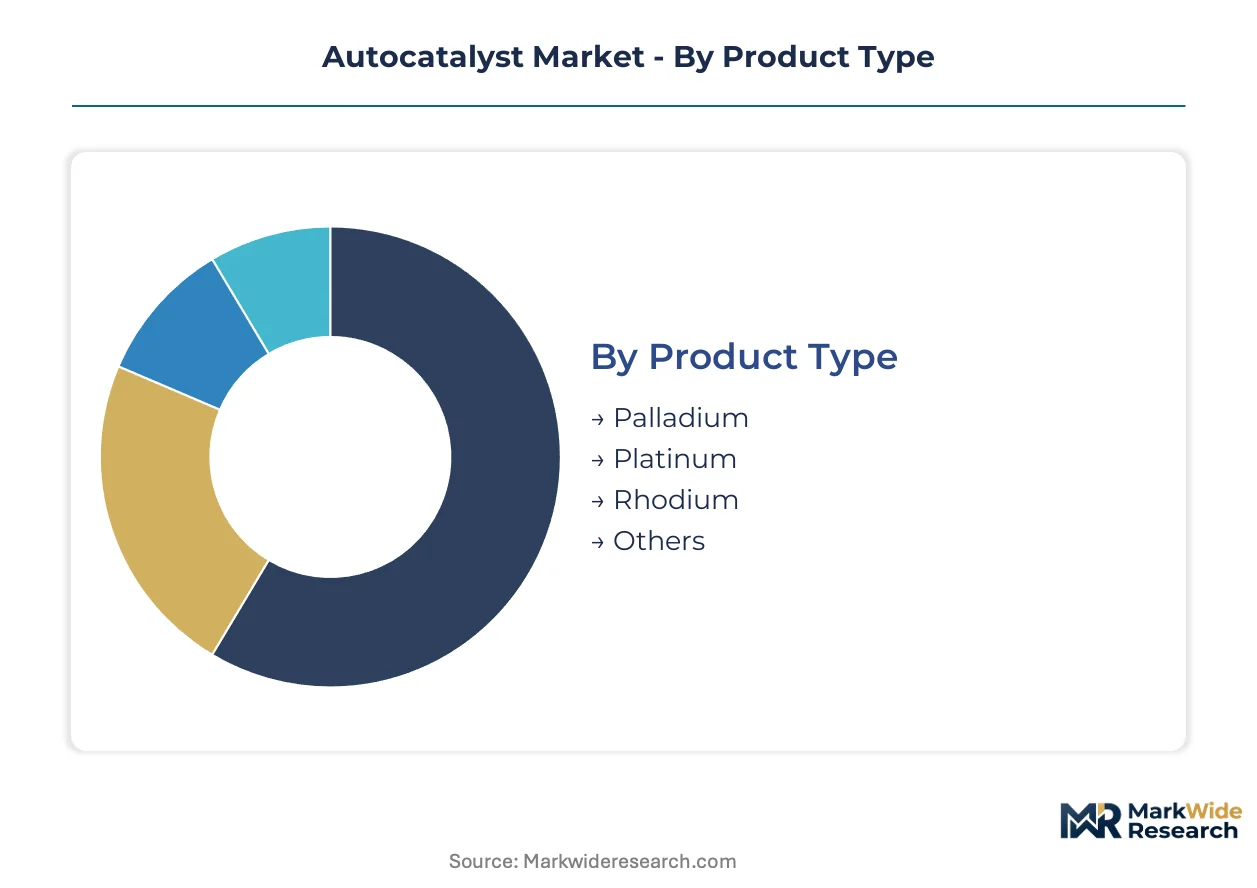
Autocatalyst procurement cycles vary sharply across metal types and vehicle applications, with emission standard upgrades forcing hardware refresh timelines that differ by geography and fleet composition. Suppliers must align coating capacity and PGM inventory positions against these divergent replacement rhythms.
Product Type:
Upgrade cycles for emission hardware correlate directly with platinum-group metal price volatility and loading recalibration mandates from regulators.
- Palladium:Dominates gasoline three-way catalyst formulations due to superior hydrocarbon oxidation activity at stoichiometric conditions. German passenger car OEMs in Stuttgart and Munich have locked in multi-year palladium supply contracts ahead of Euro 7 loading increases. Diesel substitution and gasoline hybrid expansion sustain procurement intensity.
- Platinum:Commands diesel oxidation catalyst and selective catalytic reduction applications where thermal durability exceeds palladium thresholds. Japanese commercial vehicle manufacturers in Aichi Prefecture specify platinum-rich formulations for sustained high-load operation. Hydrogen combustion engine prototypes are testing platinum-based formulations with modified oxygen storage.
- Rhodium:Specialized NOx reduction promoter used in small quantities but irreplaceable for three-way catalyst efficiency.
- Others:Includes ruthenium and iridium experimental loadings for next-generation gasoline particulate filters.
Palladium sits at the top of the volume ranking, with platinum climbing the fastest on diesel commercial vehicle demand and hydrogen powertrain development.
End User:
Cost tier stratification separates premium OEM specifications from aftermarket replacement economics across vehicle categories.
- Passenger Cars:Stoichiometric gasoline engines deploy compact three-way catalyst architectures with precise PGM loading optimized for cold-start performance. Euro 7 proposals mandate electrically heated substrates for sub-200°C operation, raising per-unit metal content. European luxury manufacturers in Bavaria and Baden-Württemberg specify coated substrates with guaranteed 160,000-kilometer durability.
- Commercial Vehicles:Diesel engines require combined diesel oxidation catalyst and selective catalytic reduction systems with urea dosing hardware. China's MIIT China VI-b standard mandates onboard diagnostics for heavy-duty fleets, expanding catalyst replacement frequency. Freight operators along Germany's Rhine corridor prefer performance-guarantee contracts over component purchases.
- Two-Wheelers:Compact single-catalyst designs for small-displacement engines with minimal PGM loading.
- Heavy Machinery:Severe-duty applications requiring thermal shock-resistant substrates for intermittent high-load operation.
Passenger cars capture the largest revenue base, with commercial vehicles gaining share fastest on regulatory tightening and fleet telematics integration.
Technology:
Application-specific chemistry determines margin structure, with complexity premiums commanding differentiated pricing.
- Selective Catalytic Reduction:Urea-based NOx reduction for lean-burn diesel engines with ammonia slip catalyst additions. Heavy-duty manufacturers in Japan's Kanto region specify dual-dosing architectures for sustained compliance under variable load. California Air Resources Board LEV III standards drive adoption across US long-haul fleets.
- Three-Way Catalysts:Simultaneous CO, HC, and NOx reduction requiring precise stoichiometric engine control. European gasoline hybrid proliferation sustains demand despite battery-electric substitution in pure-electric segments. German automotive suppliers optimize washcoat formulations for 1,050°C regeneration survival.
- Lean NOx Trap:Periodic regeneration strategy for lean gasoline engines with sulfur sensitivity constraints.
- Oxidation Catalysts:Diesel particulate and CO reduction with simpler chemistry but thermal durability requirements.
Three-way catalysts lead by installed base, with selective catalytic reduction expanding most quickly on commercial vehicle fleet retention of diesel architectures.
Application:
Volume concentration and margin potential diverge between on-road compliance mandates and off-road equipment durability specifications.
- Light-Duty Vehicles:Passenger car and light commercial applications with standardized catalyst canister dimensions. China's MEE enforcement of China VI-b onboard diagnostics expands hardware complexity for domestic OEMs. Urban mining infrastructure in Germany's industrial corridor recovers palladium from spent substrates at scale.
- Heavy-Duty Vehicles:Long-haul trucking and bus applications with sustained high-temperature operation demanding thermal shock resistance. Japan's logistics sector procurement departments bundle catalyst replacement with telematics-based emissions monitoring. Euro 7 cold-start requirements extend electrically heated substrate adoption.
- Off-Road Equipment:Construction and agricultural machinery with intermittent duty cycles and severe thermal transients.
- Marine Applications:International Maritime Organization Tier III compliance for coastal and inland waterways.
Light-duty vehicles dominate unit volume, with heavy-duty vehicles showing the steepest expansion trajectory on fleet electrification lag and regulatory durability extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor generates denser catalyst procurement per capita than China's sprawling domestic market, yet Beijing's regulatory velocity now outpaces Brussels in forcing hardware refresh cycles.
United States
California's freight corridors sustain diesel oxidation catalyst demand as long-haul fleets delay electrification timelines. The EPA enforces Tier 3 standards that mandate near-zero tailpipe emissions, directly dictating catalyst volume per vehicle. Detroit's powertrain engineering clusters coordinate with catalyst suppliers on 48-month platform validation schedules.
Germany
Bavarian luxury OEMs specify coated substrates with guaranteed 160,000-kilometer durability for premium passenger segments. The KBA coordinates Euro 7 technical discussions that will extend cold-start emission controls below 200°C. The Rhine-Ruhr logistics corridor prefers performance-guarantee contracts over component purchases for commercial vehicle fleets.
China
Domestic OEMs expand catalyst replacement cycles as MIIT mandates onboard emissions diagnostics under China VI-b standards. The MEE enforces hardware complexity requirements that exceed Euro 6b equivalents in certain durability metrics. Shanghai's automotive supplier parks cluster coating capacity near vehicle assembly plants.
Japan
Aichi Prefecture's commercial vehicle manufacturers specify platinum-rich formulations for sustained high-load diesel operation. METI coordinates hydrogen combustion engine development programs that test modified catalyst formulations with reduced oxygen storage. Kanto region logistics procurement departments bundle catalyst replacement with telematics-based emissions monitoring.
India
Commercial vehicle fleets accelerate hardware procurement ahead of BS-VI Phase 2 particulate limit tightening. The country's national automotive regulator mandates onboard diagnostics adoption patterns modeled on European precedents. Maharashtra's emerging automotive corridors attract first-mover coating capacity from multinational suppliers.
Autocatalyst Market Key Industry Players
Top-tier vendors anchor integrated precious-metal trading and coating operations, while mid-tier fabricators compete on regional logistics proximity and specialized substrate geometries. The market structure concentrates around three strategic archetypes: diversified chemical conglomerates with captive PGM desks, dedicated emissions technology specialists with closed-loop recycling infrastructure, and automotive-tier suppliers with exhaust system integration capabilities. Dominant competitive moves include backward integration into precious-metal trading operations and geographic expansion of coating capacity near high-growth OEM clusters.
Within the diversified chemical tier, BASF SE and Clariant exemplify conglomerate-scale fabricators that occupy positions spanning multiple industrial verticals. Among dedicated emissions specialists, Johnson Matthey and Umicore anchor European supply through manufacturing complexes with integrated recycling economics. Tenneco Inc. represents the automotive-tier integration archetype, sitting within exhaust system supply chains that bundle catalyst hardware with aftertreatment packaging.
| Leading Market Players |
|---|
| Cataler Corporation |
| Tenneco Inc. |
| BASF SE |
| Denso Corporation |
| Eberspächer Gruppe GmbH & Co. KG |
| Johnson Matthey |
| Forvia SE |
| Clariant |
| Umicore |
| Others |
Cost & Logistics Intelligence
London Metal Exchange palladium price volatility cascades through autocatalyst supply chains into three-tier pricing structures across premium, standard, and economy levels, with South African mining concentration amplifying spot-market exposure for fabricators lacking captive hedging operations.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for coated substrates, compressing margins for European incumbents. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and volume scale, with Euro 7-compliant formulations commanding substantial premiums over China VI-b equivalents. Cost compression in standard-tier gasoline catalysts is intensifying because OEMs are consolidating procurement volumes across platform families. Fleet operators in Japan's logistics sector exhibit lowest price sensitivity due to performance-guarantee contracting preferences, while Indian aftermarket distributors remain most exposed to spot PGM fluctuations.
Supply Chain Analysis
Automotive-grade substrate certification gates entry through Germany's TÜV and China's CATARC approval pathways, creating 18-24 month qualification timelines for new coating facilities. Geographic supply concentrates in South Africa for platinum mining, Russia for palladium extraction, and China for rare-earth oxide promoter processing. Raw material dependencies rest on ceramic substrate extrusion from Japan's Ibiden and NGK Insulators, PGM sponge from Anglo American Platinum and Norilsk Nickel, and zeolite washcoat precursors from BASF's Ludwigshafen complex. Single-source vulnerability concentrates in South African platinum corridor labor disruptions. Distribution runs through Tier 1 exhaust system integrators bundling catalyst hardware with aftertreatment packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autocatalyst margin expansion hinges on closed-loop recycling economics displacing virgin PGM purchases, with premium-tier shifts toward subscription-based compliance contracts capturing service-layer value.
For Market Incumbents: Acquire urban mining and PGM refining assets to secure backward integration into spent catalyst recovery. Johnson Matthey's Royston complex demonstrates how captive recycling infrastructure insulates against Russian palladium supply disruptions. BASF's precious-metal trading desk provides template for hedging operations that stabilize margins during LME price spikes. Prioritize coating capacity additions in Maharashtra and Thailand to defend position against regional procurement localization mandates. For New Entrants and Emerging Players: Begin with hydrogen combustion engine catalyst formulations, where modified oxygen storage requirements and absence of incumbent patent thickets create accessible entry point. India's BS-VI Phase 2 commercial vehicle segment offers most penetrable geography due to first-mover coating capacity shortages. Target performance-guarantee contracting for Japan's Kanto region logistics fleets, where telematics bundling preferences favor service-native entrants over hardware specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fabricators possessing ceramic extrusion capabilities but lacking integrated PGM trading operations. Five-to-ten year viability favors suppliers with demonstrated Euro 7 cold-start substrate qualification and China VI-b onboard diagnostics integration. Watch for inflection in hydrogen ICE prototype volume commitments from Aichi Prefecture manufacturers as signal for modified formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Recycling | Urban mining infrastructure in Germany's industrial corridor reduces virgin metal dependency and margin volatility. |
| Coating Capacity Expansion in India | Maharashtra automotive corridors attract first-mover suppliers ahead of BS-VI Phase 2 enforcement. |
| Hydrogen ICE Catalyst Development | Modified oxygen storage formulations for METI-coordinated prototypes open premium tier beyond gasoline applications. |
| Performance-Guarantee Contracting | Rhine-Ruhr logistics operators prefer emissions-compliance subscriptions over component warranties. |
| Dual-Dosing SCR Architecture | California CARB LEV IV standards drive adoption across US long-haul fleets requiring ammonia slip catalyst additions. |
Research Approach
Bottom-up vehicle production modeling reconciled against top-down PGM consumption tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 exhaust system procurement leads, catalyst coating plant managers, and fleet telematics operators informed demand assumptions. Secondary validation drew from EPA Tier 3 enforcement databases, China MIIT vehicle-type approval records, European Automobile Manufacturers Association production statistics, and LME precious-metal warehouse flow reports. Cross-referencing coated substrate shipments against vehicle registration data triangulates market sizing.
Historical trendline analysis of catalyst content per vehicle across Euro 5 through Euro 6b transitions established elasticity baselines for PGM loading responses to regulatory tightening. Segmentation modeling spans metal type, vehicle application, technology chemistry, and regional production cluster dimensions. CAGRs derive from regression-weighted scenario analysis incorporating regulatory phase-in schedules and fleet electrification lag assumptions. Forecast inputs include MIIT China VI-b onboard diagnostics penetration curves and KBA Euro 7 technical discussion timelines.
Caveats apply where South African mining labor actions or Russian palladium export restrictions could materially shift the outlook. Assumptions underlying PGM price trajectories and OEM platform electrification rates carry revision risk. A model refresh is warranted upon material change in hydrogen ICE commercialization commitments from Japan's METI-coordinated development programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Drum Brake Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market