
 Blood Pressure Monitors Market | 2026-2036
Blood Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Pressure Monitors Market Intelligence
The European Union's Restriction of Hazardous Substances (RoHS) directive, which limits specific materials in electronic equipment, is restructuring component sourcing for medical device manufacturers. Omron Healthcare leverages its strong brand recognition and extensive distribution network in the home-use segment. Medtronic differentiates through its integration of monitoring devices with broader cardiac care ecosystems. Shenzhen Mindray Bio-Medical Electronics competes on manufacturing scale and cost-efficiency, particularly in markets across Asia and Latin America.
Blood pressure monitors are medical devices that measure arterial pressure using an inflatable cuff and a processing unit. Most modern devices employ the oscillometric method, detecting blood flow oscillations to calculate systolic and diastolic pressures for hypertension management. The home use application segment commands significant volume, while automatic arm monitors lead product categories due to their accuracy and ease of use. Wrist monitors are gaining share based on enhanced portability for active users.
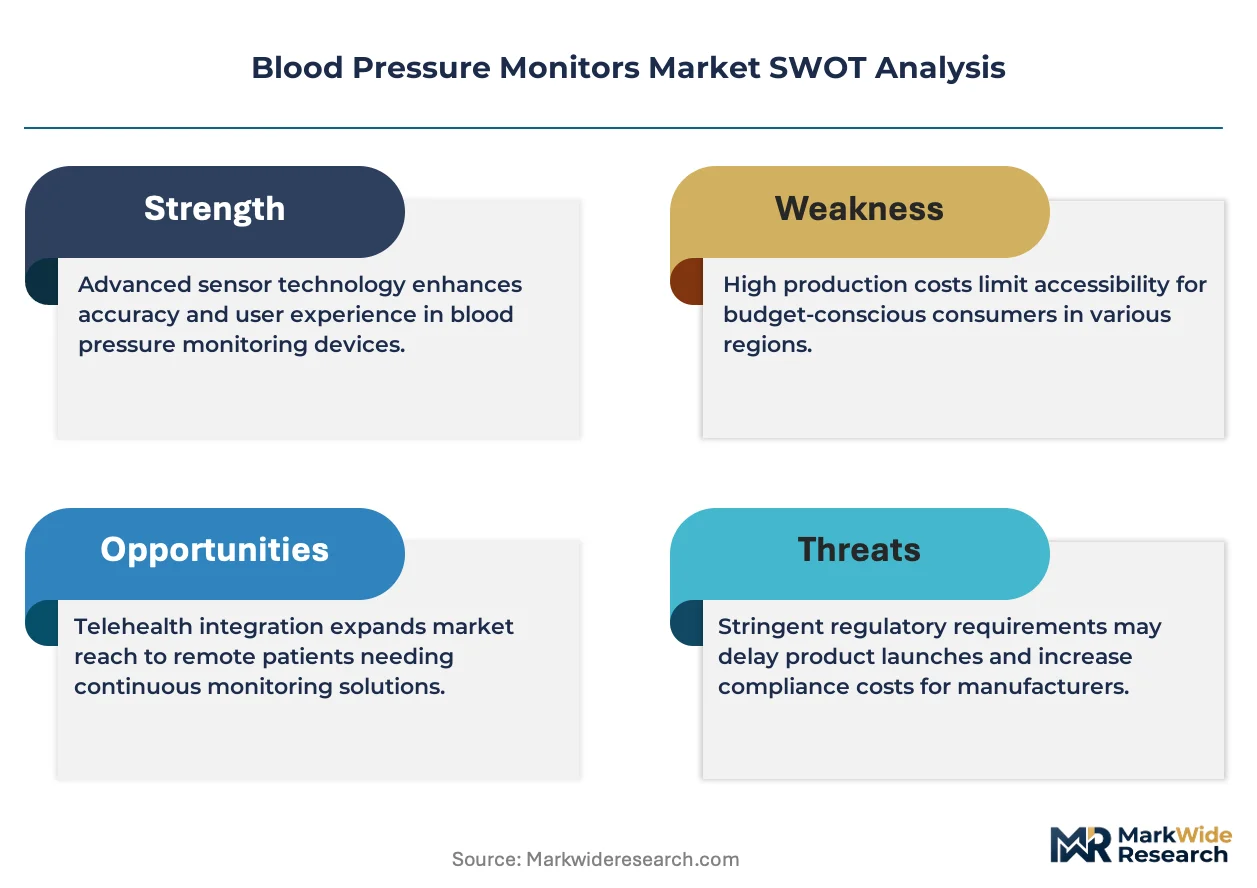
Regulatory oversight from bodies like the US FDA and China's NMPA mandates stringent validation protocols to ensure clinical accuracy. In Europe, the Medical Device Regulation (MDR) imposes stricter post-market surveillance and clinical evidence requirements, raising the bar for market entry. Stakeholder decisions will center on balancing the cost of regulatory compliance with the need for innovation in sensor technology and data connectivity.
Market Dynamics
The convergence of telehealth infrastructure with consumer-grade medical devices is the central force shaping the blood pressure monitor market. This trend accelerates as healthcare systems globally prioritize preventative care and remote management of chronic conditions like hypertension, turning standalone devices into integrated health data points.
Growth Catalysts
- Regulatory Harmonization:The US FDA's streamlined clearance pathways for home-use devices and the EU's Medical Device Regulation (MDR) create clearer market access routes, encouraging investment in new monitoring technologies.
- Aging Demographics:Nations with significant aging populations, such as Japan and Germany, exhibit heightened demand for user-friendly home blood pressure monitors for routine hypertension management.
- Telehealth Integration:The expansion of remote patient monitoring platforms is driving demand for connected devices that can automatically transmit readings to healthcare providers, improving chronic disease management.
Market Restraints
- Component Sourcing Constraints:The EU's Restriction of Hazardous Substances (RoHS) directive complicates supply chains, forcing manufacturers to re-engineer products and find compliant, often more expensive, electronic components.
- Wearable Technology Substitution:The proliferation of smartwatches with integrated, albeit less clinically validated, blood pressure sensing features presents a substitution threat to dedicated medical devices for general wellness tracking.
- Clinical Validation Hurdles:Stricter clinical evidence and post-market surveillance requirements under Europe's MDR and similar mandates from China's NMPA increase the cost and time-to-market for new devices.
Strategic Opportunities
- Emerging Market Penetration:There is significant opportunity in expanding access to affordable, validated devices in markets across Latin America and Southeast Asia, where hypertension prevalence and awareness are rising.
- AI-Powered Predictive Analytics:Integrating artificial intelligence algorithms to analyze long-term blood pressure data can enable predictive alerts for cardiovascular events, creating a new value proposition for users and clinicians.
- Specialized Clinical Applications:Developing monitors for niche applications, such as ambulatory blood pressure monitoring (ABPM) for complex diagnostics or devices tailored for pediatric patients, opens new segments.
Industry Challenges
- Data Security and Privacy Compliance:Ensuring HIPAA compliance in the US and GDPR compliance in Europe for connected devices presents a significant operational challenge, requiring constant investment in cybersecurity infrastructure.
- System Interoperability:Achieving seamless data integration between various brands of monitors and different electronic health record (EHR) systems remains a major hurdle, limiting the effectiveness of remote monitoring programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Pressure Monitors Market |
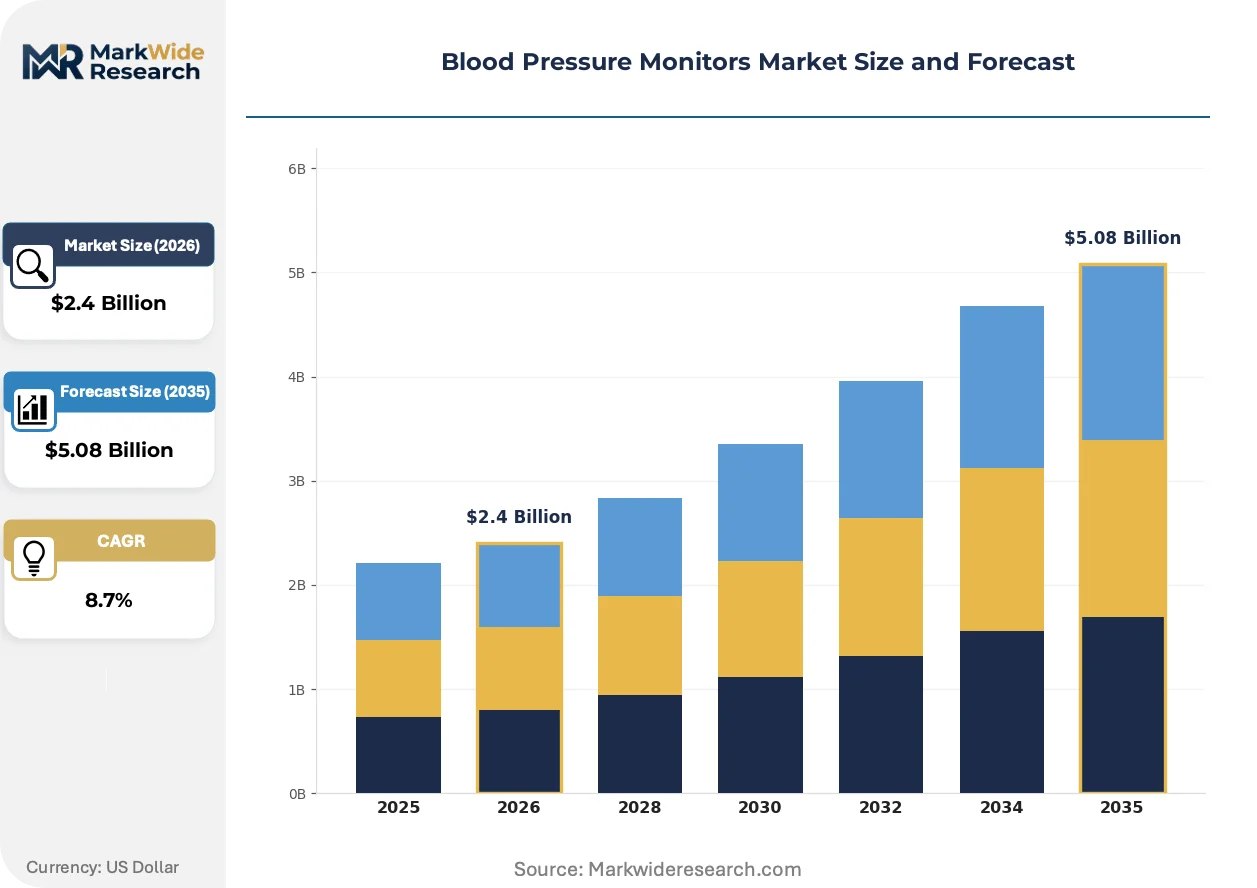
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
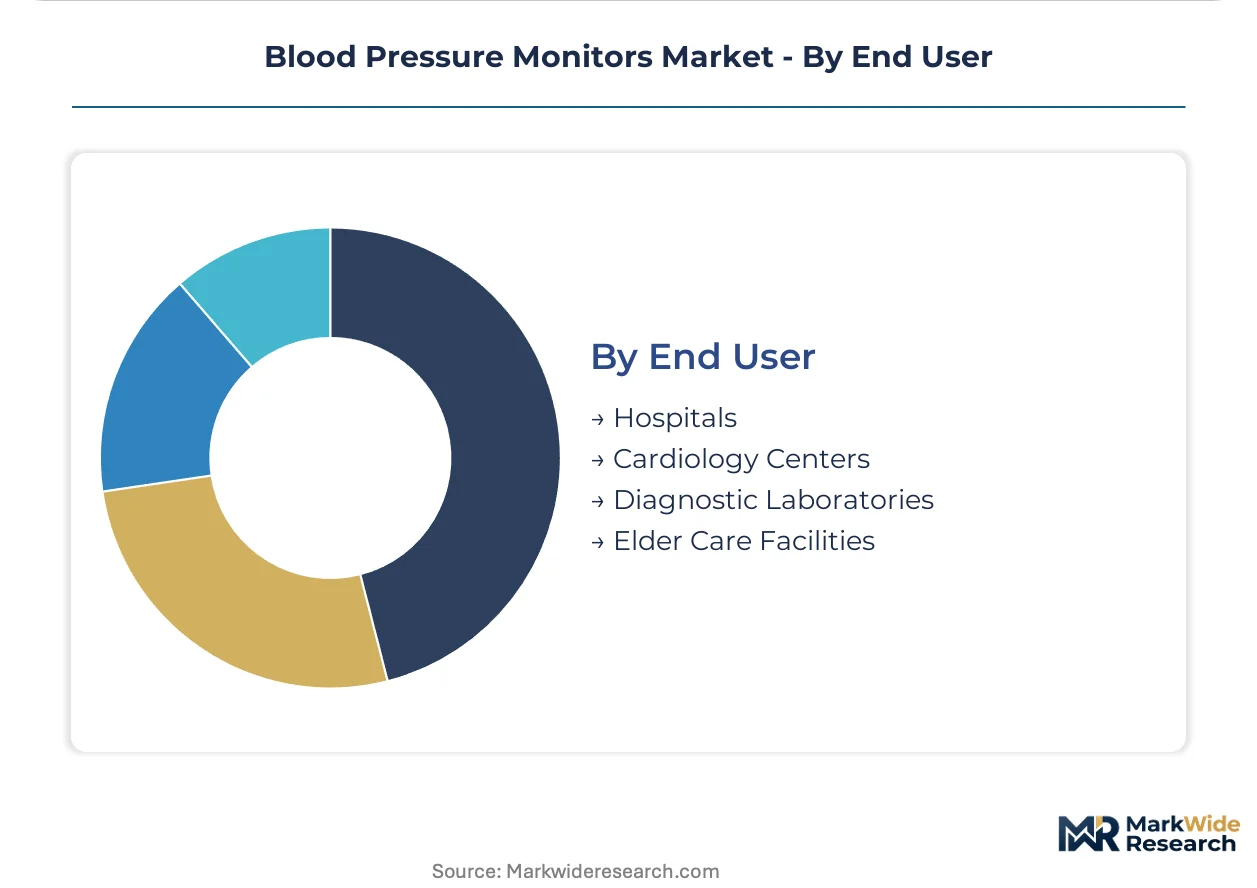
| Segmentation | Product Type: Automatic, Manual, Wrist, Arm, Ambulatory Technology: Oscillometric, Auscultatory, Tonometric, Volume Clamp Application: Home Use, Clinical Diagnostics, Remote Monitoring, Sports Science End User: Hospitals, Cardiology Centers, Diagnostic Laboratories, Elder Care Facilities |
| Companies Covered | GE Healthcare, Medtronic, Omron Healthcare, Shenzhen Mindray Bio-Medical Electronics, Nihon Kohden Corporation, A&D Medical, Panasonic Corporation, Hill-Rom, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Pressure Monitors Market Strategic Shifts & Innovations
The evolution from standalone measurement devices to connected data nodes within digital health ecosystems is the defining trend. This transition is driven by the need for continuous, actionable data for chronic disease management, not just periodic snapshots of arterial pressure.
Cuffless monitoring technology, using optical sensors and photoplethysmography (PPG), enables blood pressure estimation without an inflatable cuff. Consumer tech firms and medical device startups are targeting active users who value convenience. This innovation is unifying previously separate biometric measurements into a cohesive, longitudinal health record accessible from a single wearable platform.
Reimbursement policy expansion for remote patient monitoring (RPM) in the United States and Germany is creating new revenue for healthcare providers. These policies incentivize prescribing connected blood pressure monitors for patients with chronic hypertension. Consequently, cardiology and primary care clinics are adopting turnkey RPM solutions that bundle devices, software, and clinical support.
Direct-to-consumer (DTC) sales channels are gaining traction, bypassing traditional pharmacy and medical supply distributors. This shift is driven by consumers seeking specific features and competitive pricing available through online marketplaces and brand websites. The trend is most visible in the United States and Western Europe, where e-commerce infrastructure supports digital marketing for medical devices.
Blood Pressure Monitors Market Segmentation
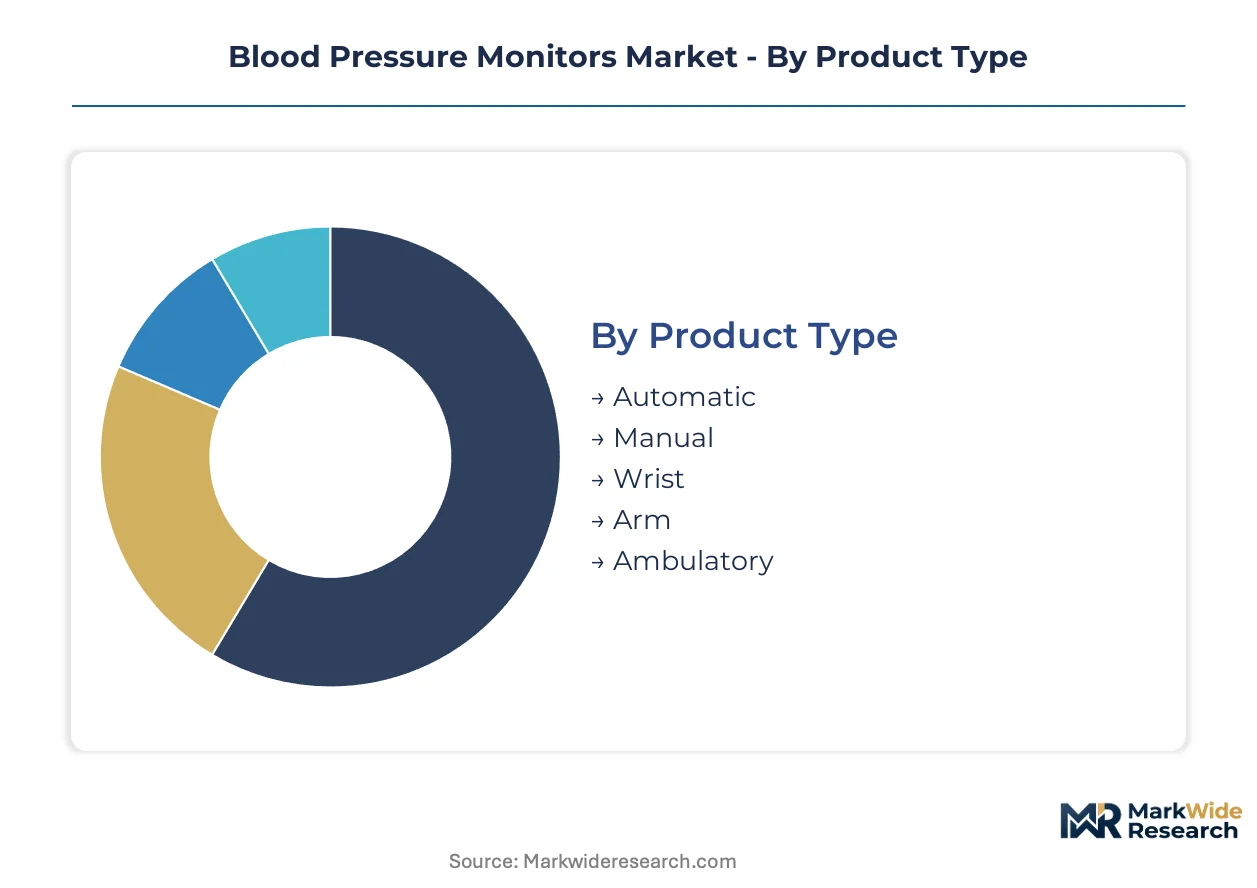
The blood pressure monitors market dissects into distinct segments, reflecting diverse user needs and technological advancements. Understanding these classifications is critical for manufacturers to align product development with market demand and for healthcare providers to optimize device selection. Each segment presents unique opportunities for innovation and market penetration.
Product Type:
The upgrade and replacement cycles for blood pressure monitors are significantly influenced by evolving product types, which offer enhanced convenience and accuracy features.
- Automatic:These devices provide single-button operation, automatically inflating and deflating the cuff to measure blood pressure. Demand for automatic monitors is high in home-use settings across Germany due to their ease of use and consistent readings.
- Wrist:Compact and highly portable, wrist monitors are designed for active users who prioritize convenience over traditional arm-cuff models. Their smaller form factor drives adoption among individuals in Japan seeking discreet, on-the-go monitoring.
- Manual:Requiring a stethoscope and bulb for inflation, manual monitors are common in clinical settings for trained professionals.
- Arm:These traditional cuff-based devices are widely recognized for clinical accuracy, making them a staple in primary care clinics globally.
- Ambulatory:Ambulatory monitors provide 24-hour blood pressure tracking, crucial for diagnosing 'white coat hypertension' and assessing treatment efficacy.
Volume placements concentrate in Arm monitors; the faster expansion belongs to Wrist monitors.
Technology:
The core technology underpinning blood pressure monitors dictates their functional capabilities and suitability for various clinical and home environments.
- Oscillometric:This method detects blood flow oscillations in the artery as the cuff deflates, widely employed in modern automatic digital devices. Its prevalence in home-use monitors across the United States is driven by user-friendliness and reliable performance.
- Tonometric:Tonometric devices measure blood pressure by applanating an artery against a bone, often used in cuffless or continuous monitoring solutions. Innovation in this technology targets wearable integration for continuous data collection in Europe.
- Auscultatory:Utilizing a stethoscope to listen for Korotkoff sounds, this traditional method remains a standard for clinical validation.
- Volume Clamp:This non-invasive technique continuously measures blood pressure by maintaining a constant volume in a finger cuff.
The Oscillometric method is critical for broad market adoption; Tonometric technology offers advanced continuous monitoring capabilities.
Application:
Different application segments reflect distinct user behaviors and health management priorities, influencing device design and feature sets.
- Home Use:Devices for home use empower individuals to self-monitor hypertension, facilitating proactive health management and doctor-patient communication. Demand for these personal devices is strong in Japan, supporting an aging population's health.
- Remote Monitoring:This application integrates connected devices with telehealth platforms, allowing healthcare providers to track patient data remotely. The expansion of remote patient monitoring programs in the US drives significant uptake of these connected solutions.
- Clinical Diagnostics:These applications involve professional use in hospitals and clinics for accurate diagnosis and treatment planning.
- Sports Science:Blood pressure monitoring in sports science helps optimize athletic performance and assess cardiovascular response during training.
Home Use applications demonstrate broad market penetration; Remote Monitoring applications are experiencing rapid integration into healthcare systems.
End User:
The end-user landscape for blood pressure monitors varies, driven by care settings, patient populations, and reimbursement structures.
- Hospitals:Hospitals utilize a range of blood pressure monitors for inpatient care, emergency services, and surgical procedures. Their procurement decisions often prioritize clinical accuracy and seamless integration with existing electronic health records in Europe.
- Elder Care Facilities:These facilities require user-friendly and reliable monitors for routine health checks and chronic disease management for their residents. The increasing elderly population in countries like Germany fuels consistent demand for these devices.
- Cardiology Centers:Specialized cardiology centers employ advanced monitors for detailed cardiovascular assessments and patient follow-ups.
- Diagnostic Laboratories:Laboratories use blood pressure monitoring as part of broader diagnostic panels and health screenings.
Hospitals are primary purchasers for acute care; Elder Care Facilities represent a growing segment for routine monitoring services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's manufacturing capabilities support global blood pressure monitor supply. This Chinese city drives cost-efficiency and volume production. Its industrial clusters serve diverse markets across Asia and Latin America.
United States
Telehealth integration and remote patient monitoring expansion drive demand for connected devices. The US FDA's streamlined clearance pathways encourage new monitoring technologies. Reimbursement policy expansion further incentivizes adoption. The Boston-Cambridge biotechnology cluster sees innovation in sensor technology.
Germany
An aging demographic generates heightened demand for user-friendly home blood pressure monitors. Europe's Medical Device Regulation (MDR) imposes strict post-market surveillance. The RoHS directive influences component sourcing. The MedTech cluster in Tuttlingen focuses on precision manufacturing.
Japan
A significant aging population fuels strong demand for personal health devices. Japan's PMDA ensures stringent validation protocols for clinical accuracy. METI supports innovation in medical device manufacturing. Tokyo's health technology firms develop advanced optical sensors for cuffless monitoring.
China
Rising hypertension prevalence and increasing health awareness drive market expansion. China's NMPA mandates stringent validation protocols for market entry. GB standards ensure product quality and safety. Shenzhen's industrial parks specialize in high-volume production of digital health devices.
Brazil
Emerging market penetration for affordable, validated devices is a key opportunity. ANVISA oversees medical device registration and post-market surveillance. Local policies aim to improve access to preventative care. São Paulo's medical technology sector focuses on distribution networks.
Blood Pressure Monitors Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological innovation and stringent regulatory compliance. The market exhibits a tiered structure, with established medical device manufacturers alongside high-volume electronics producers and specialized startups. Strategic archetypes include specialized clinical solution providers focusing on complex diagnostics and broad consumer health device manufacturers emphasizing user-friendliness and connectivity. Companies actively pursue geographic expansion into emerging markets and portfolio diversification to capture market share and enhance competitive positioning.
Within the consumer health device archetype, Omron Healthcare exemplifies strong brand recognition and extensive distribution networks, particularly in the home-use segment. Medtronic, a US-based medical technology company, anchors the specialized clinical solution segment through its integration of monitoring devices with broader cardiac care ecosystems. Shenzhen Mindray Bio-Medical Electronics Co., Ltd., a prominent Chinese manufacturer, occupies a position focused on manufacturing scale and cost-efficiency, particularly in markets across Asia and Latin America. These companies represent distinct approaches to market penetration and value creation. Their diverse strategies highlight the varied competitive pressures and opportunities within the blood pressure monitor market.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic |
| Omron Healthcare |
| Shenzhen Mindray Bio-Medical Electronics |
| Nihon Kohden Corporation |
| A&D Medical |
| Panasonic Corporation |
| Hill-Rom |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) mandates stringent validation protocols, forcing manufacturers to re-engineer products. This regulatory pressure directly shapes supply chain investments and influences final product pricing across European markets.
Pricing Analysis
Value-based pricing anchors the premium segment, reflecting improved patient outcomes and reduced healthcare costs from early hypertension management. Price differentiation stems from clinical accuracy validated by bodies like the US FDA and strong brand recognition, alongside bundled after-sales services for connected devices. Pricing softness affects high-volume, basic models from Asian manufacturers, while specialized clinical applications maintain stronger margins. Home-use consumers in emerging markets exhibit the highest price sensitivity, contrasting with hospitals prioritizing validated accuracy and integration.
Supply Chain Analysis
Reverse logistics for medical devices, including returns and refurbishment, must comply with strict health and safety standards. Geographic supply concentration centers heavily on China, particularly Shenzhen, for cost-efficient manufacturing, with precision components also sourced from Germany and Japan. Key dependencies include specialized electronic sensors and medical-grade plastics, creating a structural risk due to regulatory restrictions like the EU's RoHS directive complicating sourcing. Distribution runs through online marketplaces and direct-to-consumer channels for home-use devices, complementing traditional medical distributors for clinical settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood pressure monitors market is increasingly defined by the cost of compliance, with the European Union's Medical Device Regulation (MDR) creating a significant barrier to entry. This regulation establishes a robust moat for established players capable of meeting stringent post-market surveillance and clinical evidence requirements.
For Market Incumbents: Acquire specialized AI analytics startups to enhance predictive capabilities for cardiovascular events. This move counters the threat of wearable technology substitution by offering superior clinical insights. Consolidate distribution networks in Latin America and Southeast Asia to leverage existing brand recognition and scale. Invest in advanced sensor technology R&D to maintain a competitive edge against cost-efficient manufacturers.
For New Entrants and Emerging Players: Pediatric patients represent an underserved buyer archetype, requiring specialized device design and clinical validation. Target niche clinical applications like ambulatory blood pressure monitoring for complex diagnostics, emphasizing superior accuracy. Penetrate emerging markets such as Brazil and Southeast Asia with affordable, validated devices tailored to local healthcare infrastructure. A direct-to-consumer go-to-market strategy can capture early adopters valuing convenience and specific features.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated digital health platform providers given the accelerating telehealth integration trend. The market offers long-term viability driven by aging demographics and the global push for preventative care. Identify acquisition targets possessing robust intellectual property in cuffless monitoring or established, interoperable remote patient monitoring platforms. Watch for expanded reimbursement policies for connected devices in major healthcare systems as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Devices | Accelerates market access for advanced diagnostic tools in the US. |
| Telehealth Integration Partnership | Expands reach and utility of connected devices within healthcare ecosystems. |
| Cuffless Monitoring R&D | Targets active users and enhances convenience for continuous data collection. |
| Emerging Market Localization | Tailors devices and services to address specific needs in Latin America. |
| RoHS Compliance Upgrade | Ensures continued market access in Europe and streamlines component sourcing. |
Research Approach
US FDA regulatory documents, EU MDR guidelines, and China NMPA mandates formed the secondary backbone for this study. This was combined with primary interviews involving clinicians, hospital purchasing committees, medical device engineers, and regulatory affairs specialists. A bottom-up and top-down triangulation approach ensured data consistency.
Historical trendline analysis established the foundation for market sizing and competitive landscape evaluation. The analytical framework modeled segments by product type, technology, application, end-user, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived from market drivers, restraints, and competitive strategies. Key forecast inputs included aging population growth rates and remote patient monitoring platform adoption.
Revisions become necessary when significant regulatory shifts, rapid technological advancements in sensor technology, or unforeseen global supply chain disruptions materialize. Forecasts reflect assumptions documented at the time of publication. Practitioners should monitor new reimbursement policies and major regulatory updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market