
 Americas Wearable Medical Device Market | 2026-2036
Americas Wearable Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Wearable Medical Device Market Analysis
Mexico's medical device manufacturing corridor is tilting toward wearable assembly as maquiladora operators expand cleanroom capacity for biosensor production. Dexcom sustains leadership in continuous glucose monitoring through captive manufacturing of enzyme-based sensor filaments. Abbott leverages vertical integration into semiconductor packaging for its Libre platform's radio-frequency chips.
Americas wearable medical devices encompass body-worn instruments that capture physiological parameters through electrochemical, optical, or mechanical transduction, typically operating at sampling frequencies between 1 Hz and 250 Hz for cardiac and metabolic signals. These devices transmit encrypted data to clinical decision support systems, enabling ambulatory care models that reduce hospital readmission exposure. Smartwatches dominate unit economics through consumer-channel scale, while glucose monitors command premium pricing via prescription-reimbursement pathways. ECG monitors represent the fastest-growing clinical segment as atrial fibrillation screening expands from cardiology into primary care workflows.
FDA's Software as a Medical Device framework and HIPAA security rule enforcement shape product architecture decisions for any manufacturer targeting US reimbursement channels. Brazil's ANVISA has accelerated equivalence review timelines for wearable devices already cleared by FDA or Health Canada, redirecting South American market entry strategies toward parallel regulatory filing. Stakeholders must monitor how Medicare Advantage plans restructure capitation contracts to incorporate continuous biometric data from member-worn devices.
Market Dynamics
Medicare Advantage capitation contracts are restructuring to incorporate continuous biometric streams from member-worn devices, forcing manufacturers to architect products around HIPAA-compliant data pipelines and FDA Software as a Medical Device clearance pathways rather than consumer electronics standards.
Growth Catalysts
- FDA SaMD Framework:Compressed premarket review timelines for algorithm-driven diagnostics accelerate commercialization of arrhythmia detection patches and nocturnal glucose alerts.
- Cardiology RPM Expansion:Hospital systems across the United States deploy ambulatory ECG monitors to reduce 30-day heart failure readmission penalties under CMS quality programs.
- Enzyme Biosensor Advances:Extended filament longevity in continuous glucose monitoring drives replacement cycle economics and patient adherence metrics.
Market Restraints
- Semiconductor Packaging Concentration:Radio-frequency chip assembly for Libre-style platforms depends on concentrated Asian substrate suppliers, exposing margin stability to geopolitical friction.
- Cleanroom Capacity Constraints:Mexico's maquiladora corridor faces qualified technician shortages for biosensor laminate production, capping near-term assembly expansion.
- Reimbursement Code Lag:CPT code updates for remote therapeutic monitoring trail device capability releases, compressing initial commercial traction for novel physiological endpoints.
Strategic Opportunities
- Brazil ANVISA Equivalence Pathway:Parallel FDA-ANVISA filing strategies unlock South American market entry with compressed regulatory overhead for wearable cardiac monitors.
- Primary Care AFib Screening:Optical PPG sensors penetrate family medicine workflows previously served by 12-lead ECG, expanding addressable prescriber base beyond cardiologists.
- Silicon Photonics Convergence:Integration of optical coherence tomography principles into wrist-worn form factors enables noninvasive metabolic monitoring without enzymatic consumables.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 skin-sensitivity testing for novel adhesive materials extends product development cycles by 8-14 months.
- Legacy EHR Integration Complexity:HL7 FHIR interoperability gaps force custom API development for each hospital system deployment, inflating implementation costs.
- Signal Processing Talent Scarcity:Competition for firmware engineers with expertise in motion artifact rejection algorithms outpaces academic pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Wearable Medical Device Market |
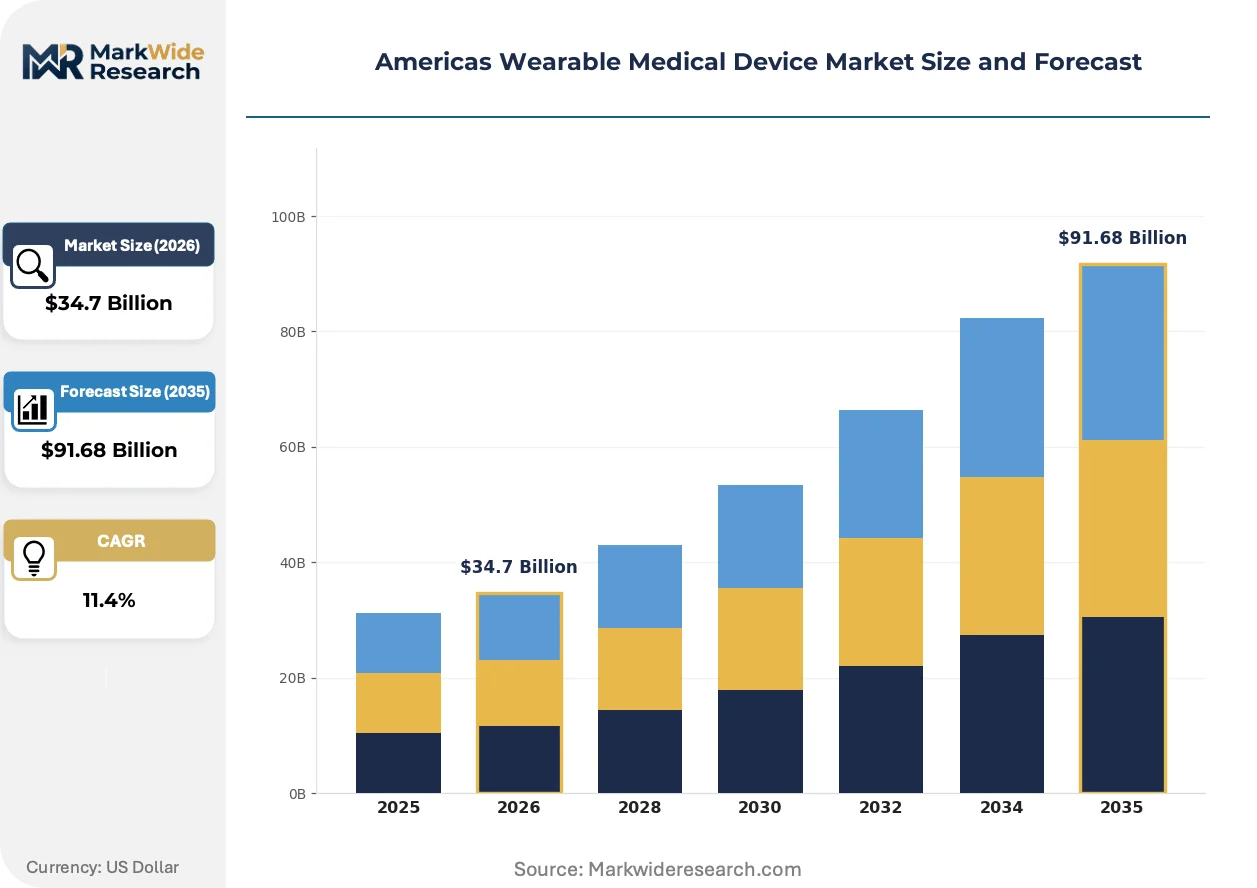
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, ECG Monitors, Glucose Monitors End User: Patients, Healthcare Providers, Caregivers, Fitness Enthusiasts Technology: Bluetooth, NFC, RFID, Wi-Fi Application: Chronic Disease Management, Remote Monitoring, Fitness Tracking, Rehabilitation |
| Companies Covered | Koninklijke Philips NV, Dexcom, Inc., Fitbit, Medtronic, Abbott, Apple Inc., Samsung Electronics Co Ltd, OMRON Healthcare, Inc., Garmin Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Wearable Medical Device Market Emerging Trajectories
Photoplethysmography signal processing advances are collapsing the clinical-grade boundary between prescription cardiac monitors and consumer smartwatches, while regulatory frameworks race to classify algorithm outputs rather than hardware inputs.
Multi-wavelength optical stacks with machine-learned motion compensation are rendering obsolete single-LED PPG modules that require static contact protocols. Cardiology departments at integrated delivery networks in Texas and Florida pilot these sensors for post-ablation monitoring, compressing the telemetry gap between hospital discharge and arrhythmia recurrence detection from weeks to hours.
ANVISA's 2023 equivalence decree for FDA-cleared wearables eliminates redundant in-country clinical trials for glucose and cardiac monitors already holding US clearance. Brazilian private insurers accelerate coverage decisions for continuous monitoring devices, redirecting manufacturer South American market entry capital toward São Paulo-based distribution partnerships rather than regulatory consulting.
Employer-sponsored wellness programs are unbundling device subsidies from health plan premiums, creating direct-to-consumer channels for metabolic monitoring hardware. Large self-insured employers in the US Mountain West states now procure continuous glucose monitors through occupational health vendors, bypassing traditional pharmacy benefit managers and capturing biometric data for population health analytics contracts with third-party administrators.
Americas Wearable Medical Device Market Segmentation
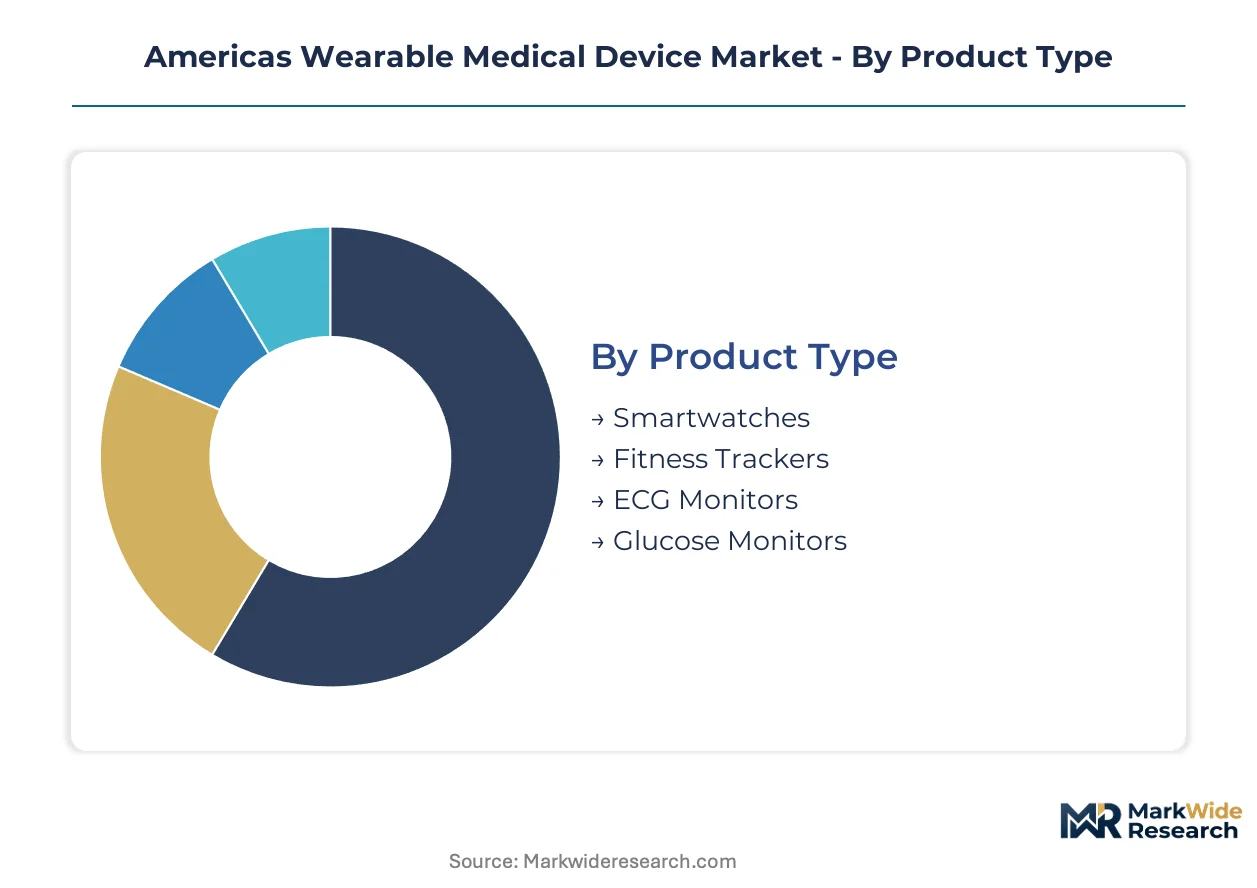
Segmentation across product architecture, connectivity standards, and clinical versus consumer use cases determines reimbursement pathway eligibility and manufacturing scale economics for wearable medical devices across the Americas. Manufacturers must align form factor decisions with FDA Software as a Medical Device classification tiers and Medicare Advantage data integration requirements.
Product Type:
Mature enzymatic sensing platforms coexist with emerging optical cardiac technologies, creating divergent margin profiles and regulatory timelines across the hardware spectrum.
- Smartwatches:Multi-sensor wrist-worn platforms integrate photoplethysmography, accelerometry, and temperature sensing for ambulatory arrhythmia screening. Demand concentrates among Medicare Advantage plans in Florida and Texas integrating Apple Watch and Samsung Galaxy Watch data into risk-adjusted capitation models. FDA 510(k) clearances for atrial fibrillation detection algorithms compress time-to-clinical-deployment versus prescription-only alternatives.
- Glucose Monitors:Enzyme-based continuous glucose monitoring systems with factory-calibrated sensor filaments dominate prescription reimbursement channels. Dexcom and Abbott capture concentrated demand from endocrinology practices in California and New York seeking to reduce HbA1c variability through real-time alerts. Extended sensor longevity drives replacement cycle economics and patient adherence benchmarks.
- ECG Monitors:Patch-based ambulatory electrocardiography systems with single-lead or multi-lead configurations serve post-ablation monitoring workflows.
- Fitness Trackers:Consumer-grade accelerometry devices with basic heart rate monitoring target employer wellness programs and direct-to-consumer channels.
Smartwatches retain volume leadership; ECG monitors hold the steepest expansion curve.
End User:
Reimbursement channel structure fragments demand across institutional procurement, prescription fulfillment, and consumer direct purchase.
- Patients:Individuals with chronic conditions—diabetes, heart failure, atrial fibrillation—operate devices under clinician-prescribed monitoring protocols. Demand clusters among Medicare beneficiaries in Arizona and Colorado enrolled in remote patient monitoring programs billing CPT 99453-99458 codes.
- Healthcare Providers:Cardiology departments and primary care networks deploy wearable fleets for population-scale screening. Integrated delivery networks in North Carolina and Georgia purchase ambulatory ECG patches under group purchasing organization contracts to reduce 30-day heart failure readmission penalties.
- Caregivers:Family members and home health aides utilize fall detection and location tracking features for elderly monitoring.
- Fitness Enthusiasts:Performance-oriented consumers purchase advanced biometric wearables through specialty retail and direct-to-consumer channels.
Healthcare Providers dominate procurement value; Patients represent the fastest-growing user base.
Technology:
Connectivity protocol selection shapes HIPAA compliance architecture and battery life tradeoffs in ambulatory form factors.
- Bluetooth:Low-energy 2.4 GHz protocols enable continuous smartphone-tethered data streaming for cardiac and metabolic monitors. Demand concentrates in US hospital systems requiring encrypted transmission to Epic and Cerner EHR platforms via HL7 FHIR interfaces.
- NFC:Near-field communication supports tap-to-transfer glucose readings from Abbott Libre readers to smartphones without battery drain. Pharmacy benefit managers in Illinois and Ohio favor NFC-enabled devices for Medicaid population adherence tracking.
- RFID:Passive radio-frequency identification enables inventory tracking and patient identification in institutional settings.
- Wi-Fi:Higher-bandwidth protocols support firmware updates and bulk data uploads for sleep apnea and nocturnal glucose monitoring.
Bluetooth commands installed base dominance; NFC gains share fastest in glucose monitoring replacement cycles.
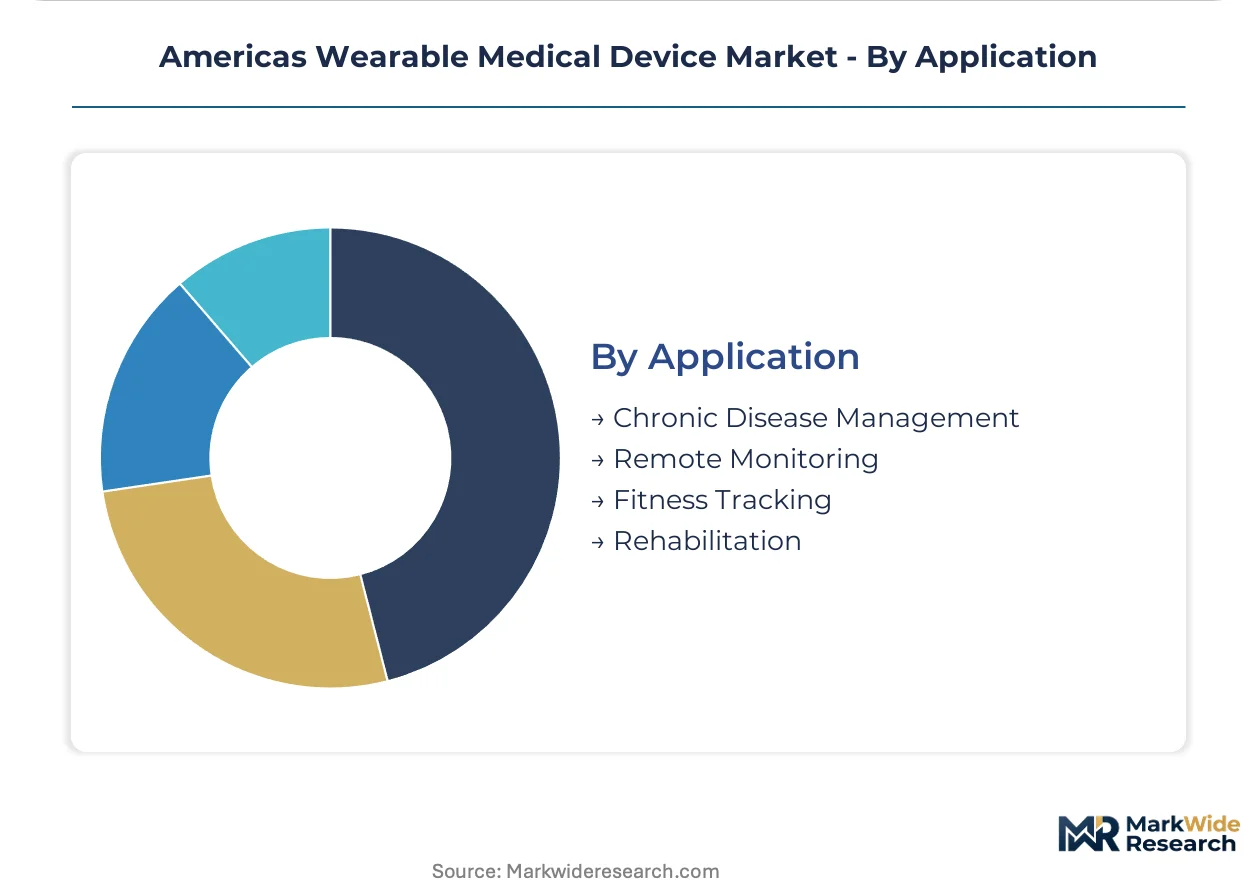
Application:
Clinical indication breadth determines regulatory classification burden and pricing tier access across the Americas.
- Chronic Disease Management:Diabetes, hypertension, and heart failure monitoring through continuous biometric capture. Demand concentrates among Medicare Advantage plans in Pennsylvania and Michigan restructuring capitation contracts around HEDIS quality metrics for glycemic control.
- Remote Monitoring:Post-acute surveillance reducing hospital readmission exposure through automated alert escalation. Hospital systems in Massachusetts and Washington deploy cardiac patch monitors for 30-day post-discharge telemetry.
- Fitness Tracking:Consumer wellness applications including step counting, sleep staging, and caloric expenditure estimation.
- Rehabilitation:Physical therapy and orthopedic recovery monitoring through range-of-motion and activity tolerance metrics.
Chronic Disease Management anchors revenue concentration; Remote Monitoring climbs the fastest on CMS quality program incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Software as a Medical Device framework and HIPAA enforcement anchor commercialization pathways for wearable medical devices across the Americas, with demand concentrating in Medicare Advantage networks and hospital systems integrating biometric data into capitated care contracts.
United States
Medicare Advantage plans in Florida and Texas restructure capitation contracts around continuous biometric streams from member-worn devices. FDA 510(k) clearances for atrial fibrillation detection algorithms compress deployment timelines versus prescription-only alternatives. Integrated delivery networks in North Carolina and Georgia purchase ambulatory ECG patches under group purchasing organization contracts to reduce CMS heart failure readmission penalties.
Brazil
ANVISA's 2023 equivalence decree eliminates redundant in-country clinical trials for glucose and cardiac monitors already holding FDA clearance. Brazilian private insurers accelerate coverage decisions for continuous monitoring devices. São Paulo-based distribution partnerships redirect manufacturer market entry capital toward commercial expansion rather than regulatory consulting overhead.
Mexico
Maquiladora operators expand cleanroom capacity for biosensor laminate production along the medical device manufacturing corridor. The country faces qualified technician shortages for enzyme-based sensor filament assembly, capping near-term expansion. Tijuana and Mexicali clusters concentrate wearable assembly operations serving US reimbursement channels.
Canada
Health Canada clearance pathways enable parallel filing strategies with FDA submissions for cardiac monitoring platforms. Provincial health systems in Ontario and British Columbia pilot remote patient monitoring programs for chronic disease management. Toronto and Montreal clusters concentrate digital health infrastructure integration expertise for HL7 FHIR-compliant data pipelines.
Americas Wearable Medical Device Market Vendor Landscape
Vertically integrated medical technology conglomerates and consumer electronics specialists split the market through divergent channel strategies and regulatory postures. The vendor base concentrates around three archetypes: enzyme biosensor captives, optical cardiac platform developers, and multi-sensor consumer device manufacturers. Dominant competitive moves include backward integration into semiconductor packaging and strategic partnerships with Medicare Advantage plans for data integration contracts.
Among enzyme biosensor specialists, Dexcom and Abbott exemplify captive manufacturing approaches that control sensor filament production and radio-frequency chip assembly. Apple and Samsung anchor the consumer-electronics tier, representing platform-scale distribution through retail channels that bypass traditional prescription fulfillment. These archetypes occupy distinct reimbursement positions: prescription-cleared devices command premium pricing via pharmacy benefit managers, while consumer smartwatches penetrate through direct-to-employer wellness program procurement.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Dexcom, Inc. |
| Fitbit |
| Medtronic |
| Abbott |
| Apple Inc. |
| Samsung Electronics Co Ltd |
| OMRON Healthcare, Inc. |
| Garmin Ltd |
| Others |
Supply Flow & Price Mechanics
Panama Canal transit cost volatility for Asian semiconductor substrates directly shapes margin compression timelines for US-bound glucose monitor manufacturers and reinforces price stratification between prescription-cleared and consumer-grade wearable tiers.
Pricing Analysis
US-Mexico price spreads for comparable cardiac patch monitors now exceed thirty percent, reflecting divergent reimbursement density and FDA clearance premiums. Three-tier pricing structure across prescription-cleared, wellness-grade, and direct-to-consumer levels anchors the market, with FDA 510(k) certification and Medicare Advantage contract eligibility serving as the primary differentiation drivers. Cost compression in the consumer tier is intensifying because employer wellness programs are consolidating procurement around single-vendor contracts. Pharmacy benefit managers exhibit the highest price sensitivity, while integrated delivery networks prioritize clinical validation over unit cost.
Supply Chain Analysis
Contract manufacturing for radio-frequency chip assembly concentrates among Tijuana and Mexicali maquiladora operators, with limited secondary capacity in Costa Rica and Colombia. Enzyme-based sensor filaments, lithium-polymer batteries, and medical-grade adhesive laminates constitute critical input dependencies. Single-source vulnerability for substrate suppliers in East Asia exposes margin stability to tariff friction and logistics chokepoints. Distribution runs through group purchasing organization contracts for hospital systems, direct-to-consumer e-commerce for wellness devices, and pharmacy benefit manager formularies for prescription monitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Software as a Medical Device clearance pathways create formidable regulatory entrenchment, with algorithm validation requirements and HIPAA-compliant data architecture acting as structural moats against consumer electronics crossover.
For Market Incumbents: Pre-empt optical cardiac sensor commoditization by accelerating silicon photonics R&D and securing exclusive Medicare Advantage data integration contracts. Captive manufacturing of biosensor filaments and backward integration into semiconductor packaging defend margin position against Asian substrate cost volatility. Lock in multi-year GPO agreements with integrated delivery networks in Texas and Florida before CPT code expansion democratizes remote monitoring reimbursement. For New Entrants and Emerging Players: Brazilian private insurance channels represent underpenetrated whitespace, with ANVISA equivalence pathways eliminating redundant clinical trial overhead for FDA-cleared devices. Target employer-sponsored wellness programs in US Mountain West states procuring metabolic monitors outside traditional pharmacy benefit structures. Lead with direct-to-occupational-health-vendor sales models that bypass established reimbursement gatekeepers. For Investors and Strategic Acquirers: Optical signal processing specialists with motion artifact rejection IP command scarcity premiums in a talent-constrained firmware engineering market. Long-term viability hinges on algorithm-driven diagnostic differentiation rather than hardware scale. Watch for Medicare Advantage capitation contract restructuring announcements as the inflection signal for biometric data monetization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission | Algorithm-driven diagnostic clearances compress time-to-reimbursement versus hardware-centric pathways. |
| Hospital System Partnership | GPO contracts with integrated delivery networks in North Carolina and Georgia secure recurring telemetry procurement. |
| Software Companion Development | HL7 FHIR-compliant data pipelines enable Epic and Cerner EHR integration for cardiology workflows. |
| Reimbursement Strategy | CPT 99453-99458 code optimization aligns device capability with remote patient monitoring billing. |
| CE Marking Pathway | Parallel Health Canada filings unlock Canadian provincial health system pilot programs. |
Methodological Framework
Desk research of FDA 510(k) filings, CMS Medicare reimbursement databases, and ANVISA regulatory decrees preceded structured interviews with cardiology department heads, hospital GPO contract managers, biomedical engineers, and Medicare Advantage plan actuaries. Primary fieldwork with maquiladora operations managers and enzyme biosensor R&D directors validated secondary trade flow data and capacity expansion timelines. Bottom-up unit economics modeling and top-down reimbursement channel sizing were triangulated against hospital procurement database extracts.
Assumptions held fixed across the projection horizon include FDA Software as a Medical Device framework stability, HIPAA enforcement continuity, and Medicare Advantage capitation contract prevalence. Segmentation dimensions modeled encompass product architecture, connectivity protocol, clinical versus consumer use case, and regional regulatory cluster. CAGRs were derived from replacement cycle economics, patient adherence benchmarks, and reimbursement code expansion trajectories. Enzyme sensor longevity improvements and optical PPG motion compensation advances served as key technology input variables.
Practitioners should monitor CPT code updates for novel physiological endpoints, ANVISA equivalence decree expansion to additional device categories, and Medicare Advantage medical loss ratio filings for early signals of biometric data integration acceleration. Quarterly review of FDA SaMD clearance timelines, maquiladora cleanroom capacity utilization, and employer wellness program procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Bone Power Tools Market
Medical Devices
EMG Biosensors Market
Medical Devices
Feeding Tubes Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Medical Machine Battery Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Global Suture Anchor Devices Market