
 Wearable Heart Monitoring Devices Market | 2026-2036
Wearable Heart Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Heart Monitoring Devices Market Intelligence
The bundling of continuous ECG and sleep analysis features into single consumer devices is consolidating buyer choice around multi-function platforms. This trend benefits ecosystem players like Apple, which leverages its established user base and software integration. Meanwhile, specialized device makers such as Oura differentiate through unique form factors like the smart ring, focusing on specific wellness metrics. Samsung also competes by integrating advanced health sensors into its smartwatch and smartphone lines.
Wearable heart monitoring devices are non-invasive electronic sensors for continuous tracking of cardiac activity. Many utilize photoplethysmography (PPG), employing LEDs to detect blood volume changes in tissue. While smartwatches dominate the device type category, ECG-capable patches see rapid uptake in clinical settings for arrhythmia detection. Fitness tracking remains a primary volume driver, but early cardiac event alerts are emerging as a critical, high-value function.
Regulatory clearance is a critical barrier, with the US FDA, the European Union's CE marking under MDR, and China's NMPA setting standards for medical-grade devices. These bodies require rigorous clinical validation for features making diagnostic claims, such as atrial fibrillation detection. The central challenge for manufacturers is balancing the rapid innovation cycles of consumer electronics with the stringent validation timelines of medical device approval.
Market Dynamics
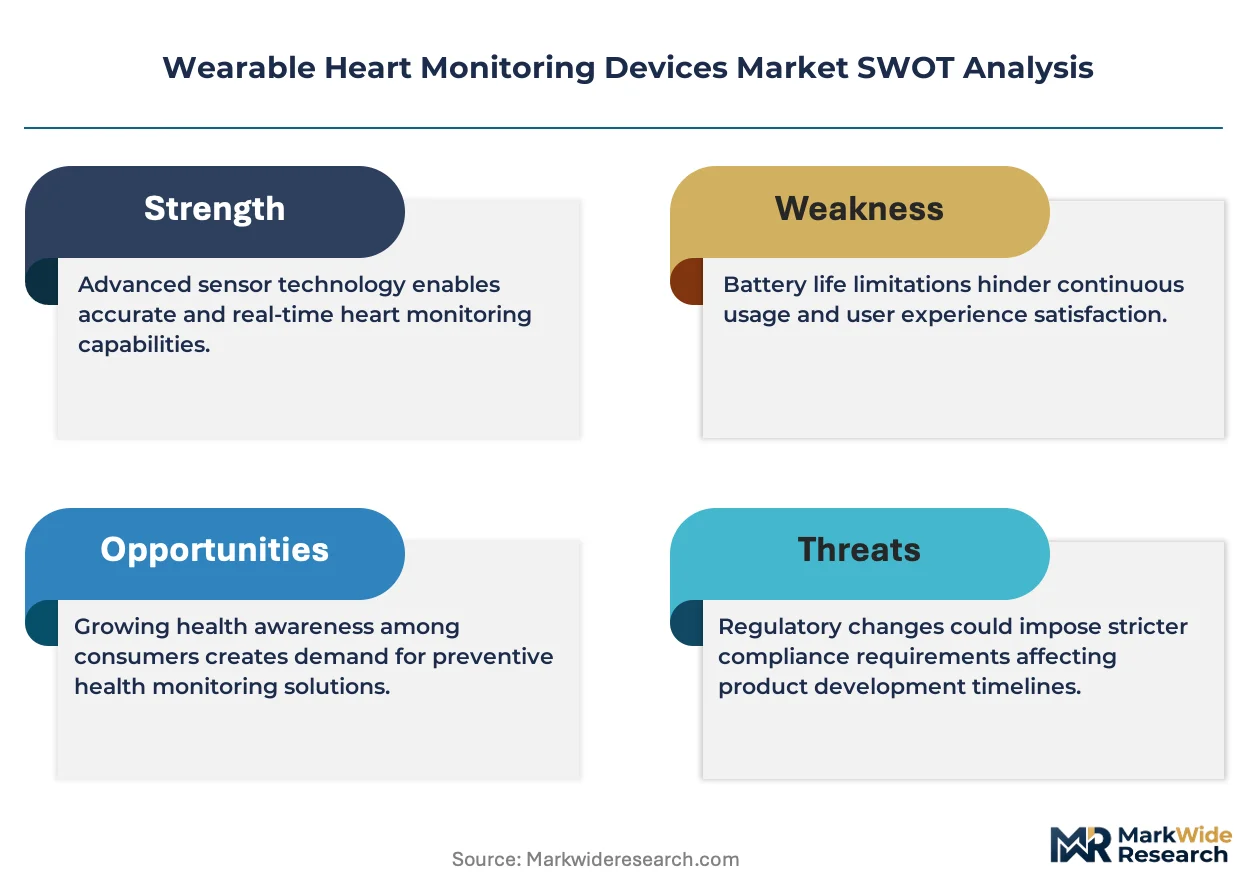
The central dynamic shaping the wearable heart monitoring device market is the structural tension between the rapid innovation cycles of consumer electronics and the stringent, multi-year validation timelines required by medical device regulators like the FDA and for CE marking.
Growth Catalysts
- Remote Patient Monitoring:The expansion of telehealth and remote patient monitoring (RPM) service reimbursement policies in countries like the United States creates direct financial incentives for healthcare providers to adopt continuous monitoring devices for chronic disease management.
- Preventative Healthcare Focus:A growing consumer focus on preventative health and wellness, particularly in developed economies, drives demand for devices that offer early detection capabilities for conditions like hypertension and arrhythmia, moving beyond simple fitness tracking.
- Clinical Adoption in China:Increased investment in hospital infrastructure and a push for domestic medical technology innovation under China's NMPA guidelines are accelerating the uptake of ECG patches and medical-grade smartwatches in clinical settings for post-operative and arrhythmia monitoring.
Market Restraints
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes significantly stricter clinical evidence and post-market surveillance requirements, increasing the time and cost for manufacturers to achieve and maintain CE marking for diagnostic features.
- Sensor Accuracy Limitations:While convenient, photoplethysmography (PPG) sensors used in most consumer wearables are susceptible to motion artifacts and skin tone variations, limiting their diagnostic reliability compared to the gold-standard electrocardiogram (ECG) used in clinical practice.
- Data Privacy Concerns:The collection of sensitive, continuous health data raises significant user privacy and data security concerns, governed by regulations like GDPR in Europe and HIPAA in the US, which can create friction in user adoption and data sharing with providers.
Strategic Opportunities
- Underserved Geographies:Markets in Latin America and Southeast Asia, where smartphone penetration is high but dedicated wearable adoption is lower, present significant growth opportunities for mid-range devices as telehealth infrastructure develops.
- Mental Health Integration:Expanding device capabilities to correlate heart rate variability (HRV) and resting heart rate with stress, sleep quality, and mental well-being opens a new high-value application beyond purely cardiac-focused metrics.
- Diabetes Management Convergence:The technological convergence of continuous glucose monitoring (CGM) sensors with heart rate monitors on a single platform offers a powerful opportunity to create a comprehensive metabolic health monitoring solution for the large and growing diabetic population.
Industry Challenges
- Data Interoperability:A primary operational challenge is the lack of standardization for integrating data from a diverse ecosystem of consumer wearables into professional Electronic Health Record (EHR) systems, creating data silos for clinicians.
- Algorithm Validation Timelines:The lengthy process of conducting clinical trials to validate the accuracy of diagnostic algorithms, such as those for atrial fibrillation detection, creates a bottleneck that delays the market entry of new, innovative features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Heart Monitoring Devices Market |
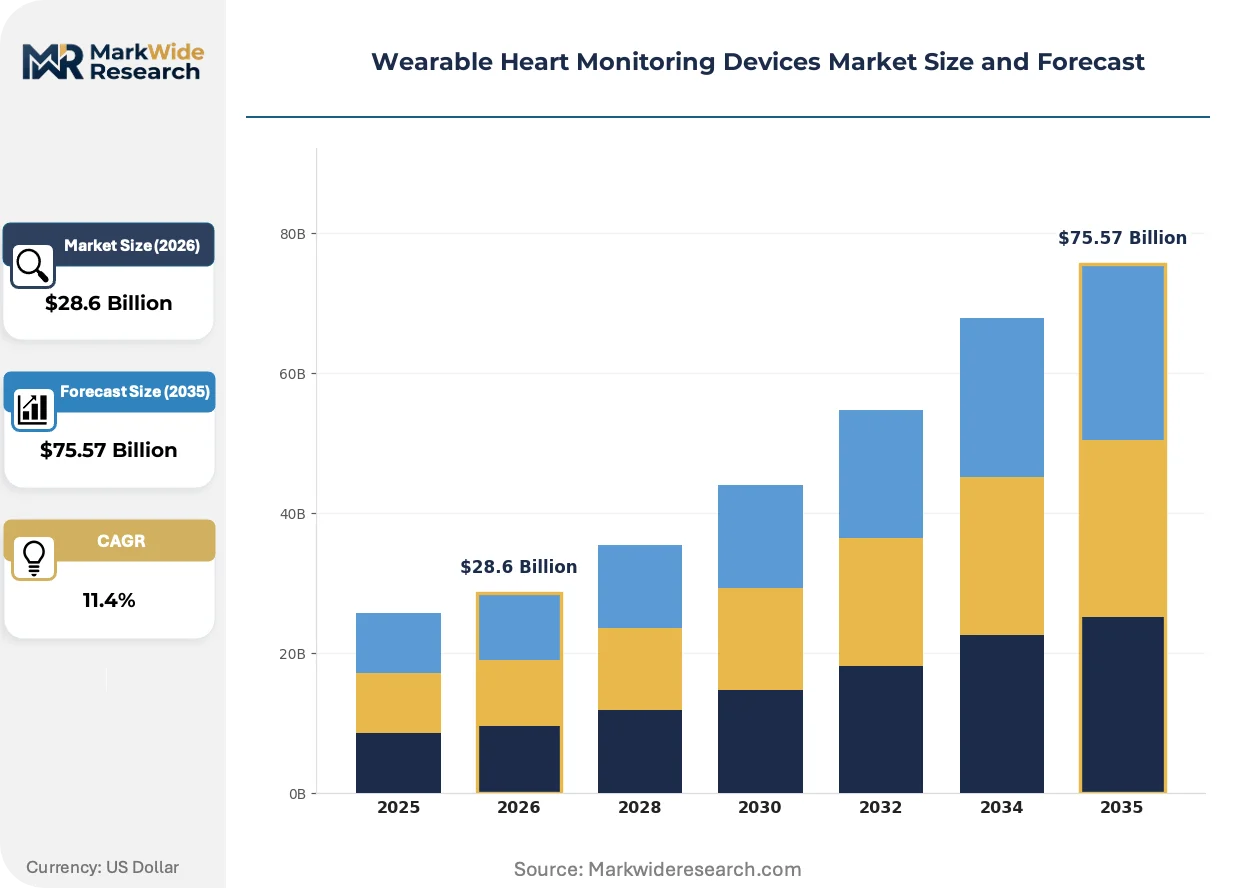
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Chest Straps, Patches, Rings, Clothing Sensors, Headbands Technology: ECG, Photoplethysmography, Ballistocardiography, Piezoelectric Sensors, Bioimpedance, Ultrasonic Application: Arrhythmia Detection, Blood Pressure Monitoring, Fitness Tracking, Stress Management, Sleep Analysis, Early Cardiac Event Alert End User: Cardiac Clinics, Sports Professionals, Remote Patient Monitoring Services, Wellness Centers, Elderly Care Facilities, Research Institutions |
| Companies Covered | Garmin, OMRON, Apple, Oura, Google, Fitbit, Samsung, Whoop, Withings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Heart Monitoring Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of raw biometric data into medically relevant, actionable insights. This shift is driven by advancements in on-device processing, sensor fusion, and the application of machine learning to detect subtle patterns in cardiovascular function.
Multi-modal sensing combines data from photoplethysmography, electrocardiogram, and accelerometer sensors within a single device. Both consumer and clinical user segments are adopting these integrated platforms to gain a more holistic view of cardiac health. This technology trend is unifying previously distinct functions of wellness tracking and medical screening into a single, continuous data stream from one wearable platform.
The US FDA's evolving framework for Software as a Medical Device (SaMD) creates a more agile regulatory pathway for the algorithms that power diagnostic features. This policy allows manufacturers to iterate and improve software-based analysis, like arrhythmia detection algorithms, independently of the hardware. This shift most affects the high-end smartwatch segment, enabling faster post-market updates to enhance device capabilities and clinical accuracy.
A significant demand-side shift sees consumers gravitating from one-time hardware purchases toward subscription services for advanced health analytics and personalized coaching. This business model disrupts traditional retail channels by creating recurring revenue tied to data interpretation, not just the physical product. The trend is most prominent in the direct-to-consumer wellness sector in North America, where users pay monthly fees for deeper insights into sleep, recovery, and stress management.
Wearable Heart Monitoring Devices Market Segmentation
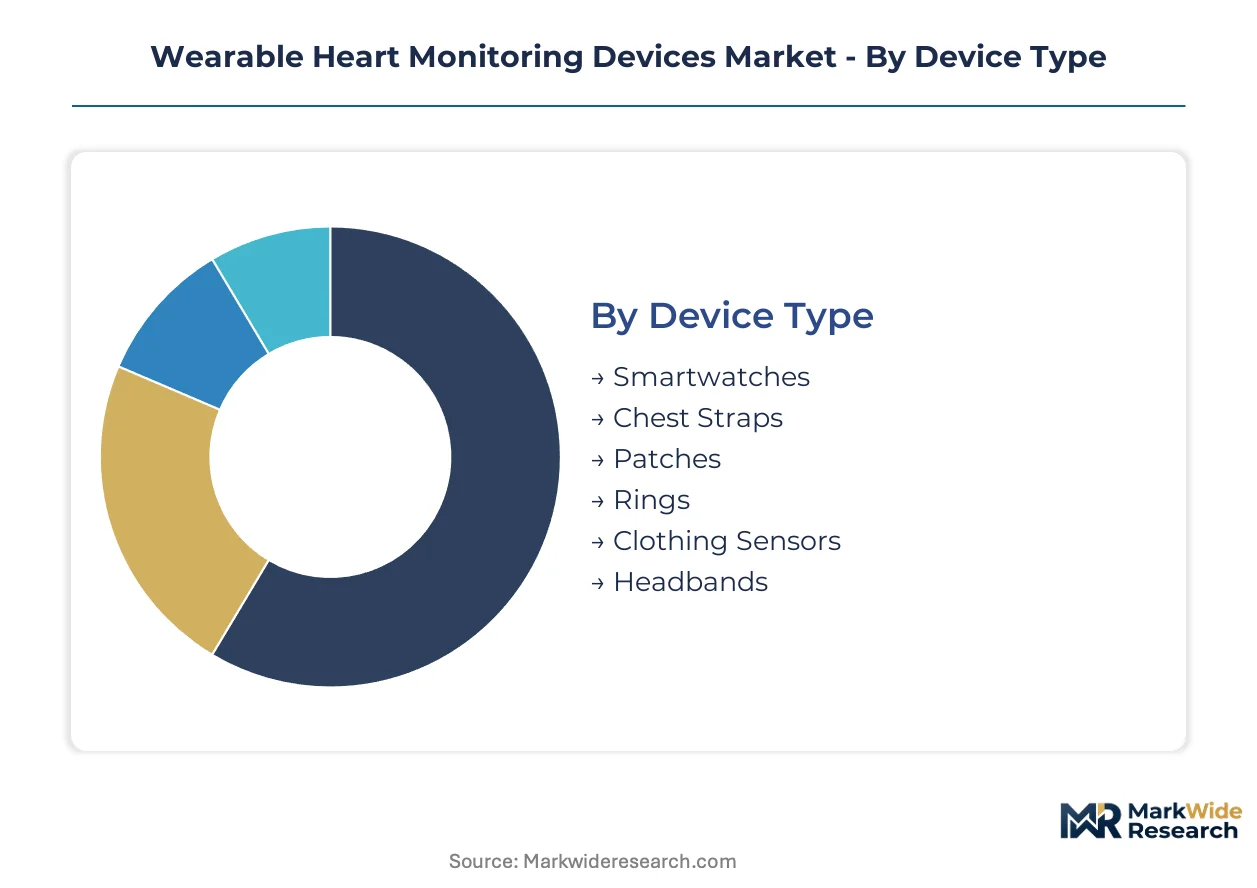
The wearable heart monitoring devices market segments across diverse device types, underlying technologies, specific applications, and distinct end-users. Understanding these categories is essential for manufacturers to tailor product development and market entry strategies effectively, addressing varied consumer and clinical needs.
Device Type:
The form factor and integrated sensor capabilities define how wearable heart monitoring devices interact with users, influencing comfort, data accuracy, and functional utility.
- Smartwatches:These multi-functional wrist-worn devices integrate PPG and often ECG sensors, providing continuous heart rate monitoring, activity tracking, and early arrhythmia detection capabilities. Consumer demand in the United States drives their widespread adoption, leveraging established mobile ecosystems.
- Patches:Adhering directly to the skin, these discreet, often disposable devices offer clinical-grade ECG monitoring for extended periods, making them ideal for arrhythmia diagnosis and post-operative surveillance. European Union's MDR requirements emphasize their clinical validation for diagnostic claims.
- Chest Straps:Primarily used for fitness and sports, these devices offer highly accurate, real-time heart rate data, favored by athletes for performance optimization.
- Rings:Worn on a finger, smart rings provide discreet, continuous monitoring of heart rate, heart rate variability, and sleep patterns, appealing to wellness-focused consumers.
- Clothing Sensors:Integrated directly into garments, these textile-based sensors offer unobtrusive, long-term physiological data collection, suitable for remote patient monitoring.
- Headbands:These devices often focus on sleep tracking and stress management by monitoring heart rate and brain activity, targeting specific wellness applications.
Mature deployment sits with Smartwatches. Newer deployment is concentrated in Patches.
Technology:
Underlying sensor technologies dictate the precision and diagnostic capabilities of heart monitoring wearables, influencing their suitability for clinical versus consumer applications.
- ECG:Electrocardiography is the gold standard for cardiac electrical activity, offering diagnostic-grade data for arrhythmia detection and other cardiac conditions. Regulatory bodies like the US FDA require rigorous clinical validation for ECG features making diagnostic claims.
- Photoplethysmography:PPG uses light to detect blood volume changes in capillaries, commonly found in smartwatches and fitness trackers for continuous heart rate monitoring. Motion artifacts and skin tone variations limit its diagnostic reliability compared to ECG.
- Ballistocardiography:This technology measures micro-vibrations produced by the heart's pumping action, often integrated into smart beds or scales for unobtrusive monitoring.
- Piezoelectric Sensors:These sensors generate an electrical charge in response to mechanical stress, used in some wearables to detect pulse waves or body movement.
- Bioimpedance:Measuring electrical impedance across the body, this technology can assess body composition, hydration levels, and in some cases, cardiac output.
- Ultrasonic:Emerging applications use ultrasonic waves for more advanced, non-invasive imaging and flow measurements within the cardiovascular system.
ECG technology remains critical for diagnostic accuracy. Photoplethysmography drives widespread consumer adoption.
Application:
The diverse applications of wearable heart monitors cater to both wellness and medical diagnostic needs, expanding their utility across various user groups.
- Arrhythmia Detection:This critical application leverages ECG capabilities to identify irregular heart rhythms, such as atrial fibrillation, enabling early intervention and improved patient outcomes. Clinical adoption in China is accelerating for this application.
- Sleep Analysis:Wearables monitor heart rate, HRV, and movement patterns during sleep to assess sleep quality, identify disturbances, and correlate with overall wellness. Consumers in North America increasingly subscribe to services offering deeper insights into sleep data.
- Blood Pressure Monitoring:Emerging wearable technologies are integrating cuff-less blood pressure monitoring, offering continuous data for hypertension management.
- Fitness Tracking:Monitoring heart rate during exercise remains a primary volume driver for consumer wearables, motivating users to maintain activity levels.
- Stress Management:Devices analyze heart rate variability and resting heart rate to provide insights into physiological stress levels, supporting mental well-being initiatives.
- Early Cardiac Event Alert:This high-value function provides timely notifications for potential cardiac issues, moving beyond simple tracking to critical preventative care.
Fitness tracking provides high volume demand. Early cardiac event alerts offer critical, high-value functionality.
End User:
Specific end-user segments drive demand for tailored wearable heart monitoring solutions, from clinical environments to individual wellness management.
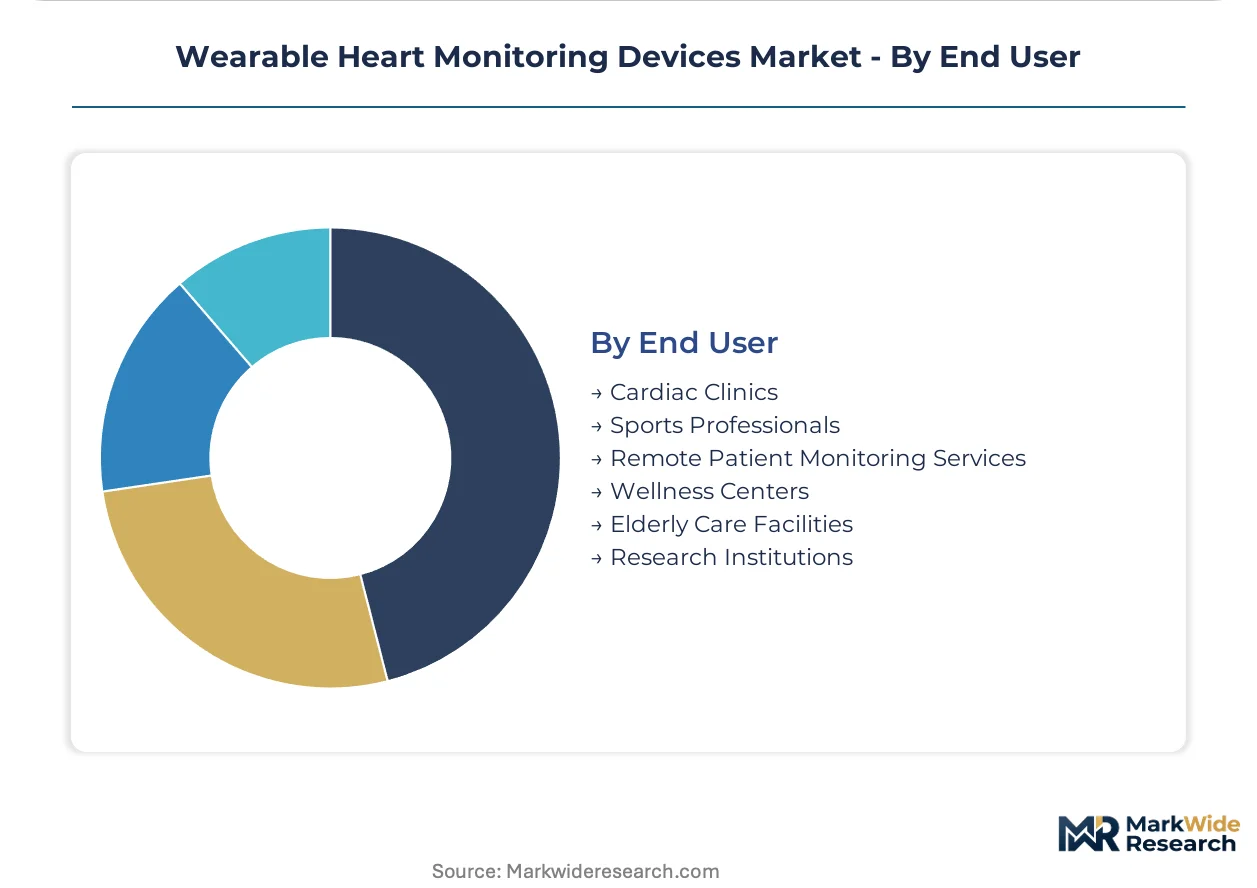
- Remote Patient Monitoring Services:Healthcare providers utilize these devices for continuous oversight of chronic conditions, supported by telehealth reimbursement policies in countries like the United States. This segment represents the fastest-growing trajectory.
- Cardiac Clinics:These medical facilities deploy medical-grade wearable ECG patches and smartwatches for diagnostic confirmation, post-procedure monitoring, and long-term patient management. Stricter clinical evidence requirements under the European Union's MDR directly impact device adoption here.
- Sports Professionals:Athletes and coaches use advanced wearables for performance optimization, recovery tracking, and injury prevention through detailed physiological data.
- Wellness Centers:These facilities integrate wearable data into personalized health programs, focusing on preventative health, stress reduction, and lifestyle improvements.
- Elderly Care Facilities:Wearables provide continuous monitoring for residents, aiding in fall detection, vital sign tracking, and early detection of health deteriorations.
- Research Institutions:Academic and clinical research organizations employ wearables for data collection in studies on cardiovascular health, sleep disorders, and chronic diseases.
Remote Patient Monitoring Services are expanding most quickly. Cardiac Clinics represent a stable, high-value segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global wearable heart monitoring device market exhibits a clear divide between high-consumption regions and emerging manufacturing hubs. Demand for advanced features often originates in developed economies, while production and clinical adoption are expanding in Asia. This dynamic shapes investment and regulatory focus across various geographies.
United States
Consumer demand for preventative health and telehealth drives significant uptake of wearable heart monitoring devices in the United States. The US FDA's evolving framework for Software as a Medical Device (SaMD) streamlines algorithm validation. Boston's MedTech cluster focuses on integrating these devices into comprehensive remote patient monitoring services.
Germany
Germany shows strong demand for medical-grade wearables due to its aging population and robust healthcare system. The European Union's MDR imposes stringent clinical evidence requirements, influencing device design and market entry. Medical technology innovation in the Munich and Stuttgart regions focuses on high-precision diagnostic sensors.
China
China represents a rapidly expanding market for wearable heart monitoring devices, driven by increased investment in hospital infrastructure. China's NMPA guidelines accelerate the uptake of ECG patches and medical-grade smartwatches in clinical settings. Shenzhen's vibrant electronics manufacturing ecosystem supports rapid prototyping and production of new wearable technologies.
Japan
Japan exhibits high demand for sophisticated consumer wearables, reflecting its advanced electronics market and health-conscious population. The PMDA sets rigorous standards for medical device approval, ensuring high quality and safety for diagnostic features. Tokyo and Kyoto research institutions contribute significantly to advancements in multi-modal sensing and miniaturization.
India
India's market for wearable heart monitors is expanding, fueled by a growing middle class and increasing smartphone penetration. The CDSCO is actively developing regulatory frameworks for digital health solutions, including wearable medical devices. Bengaluru and Hyderabad are becoming centers for telehealth infrastructure development and local manufacturing initiatives.
Wearable Heart Monitoring Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the wearable heart monitoring device market. This landscape features a tiered structure, ranging from consumer electronics giants offering multi-functional devices to niche medical device manufacturers providing clinical-grade solutions. Key strategic archetypes include broad ecosystem providers, specialized wellness device makers, and clinical-grade patch developers. Competitive moves center on portfolio diversification to capture wider user segments and strategic partnerships to integrate advanced sensor technologies and improve data interoperability.
Within the broad ecosystem provider archetype, Apple, with its established user base and software integration, exemplifies a strategy of bundling continuous ECG and sleep analysis features. Specialized wellness device makers like Oura differentiate through unique form forms such as the smart ring, focusing on specific wellness metrics and offering subscription services for advanced analytics. Samsung also occupies a position as a diversified electronics manufacturer, integrating advanced health sensors into its smartwatch and smartphone lines, leveraging its extensive consumer electronics distribution. These players collectively drive innovation while navigating stringent regulatory pathways for diagnostic claims.
| Leading Market Players |
|---|
| Garmin |
| OMRON |
| Apple |
| Oura |
| Fitbit |
| Samsung |
| Whoop |
| Withings |
| Others |
Cost & Logistics Intelligence
Shenzhen's electronics manufacturing workforce concentration influences global pricing tiers for wearable heart monitoring devices. Labor-cost differentials between Asian and Western manufacturing hubs contribute to varied product pricing strategies.
Pricing Analysis
Price erosion across consumer-grade smartwatches traces to intense competition and rapid innovation cycles. The market employs a hybrid pricing model, combining per-unit hardware sales with subscription services for advanced health analytics. FDA/CE marking and brand ecosystem integration drive significant price differentiation. While consumers exhibit high price sensitivity for basic fitness trackers, clinical buyers prioritize diagnostic accuracy and regulatory compliance over cost.
Supply Chain Analysis
Regulatory qualification for medical-grade components gates access to critical supply chains for wearable heart monitoring devices. Component manufacturing concentrates in China, Japan, and South Korea, providing essential microcontrollers, advanced sensors, and specialized batteries. Single-source vulnerability for certain high-precision diagnostic electrodes represents a structural risk. Distribution runs through direct-to-consumer channels for wellness devices and specialized medical distributors for clinical-grade patches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable heart monitoring device market is fundamentally a cost-of-compliance story. Stringent regulations like the EU's MDR create significant barriers to entry, forming a competitive moat for established players with validated devices.
For Market Incumbents: Anchor existing user bases through continuous software updates and ecosystem integration. Deepen vertical integration into AI-powered analytics to transform raw data into actionable medical insights. This defends against the threat from emerging niche players offering specialized wellness metrics. Investment in R&D for advanced sensor fusion strengthens diagnostic capabilities and regulatory compliance.
For New Entrants and Emerging Players: Underserved remote patient monitoring services in Latin America present a significant opportunity for mid-range devices. Focus on mental health integration by correlating HRV with stress and sleep quality. Target wellness-focused consumers in Southeast Asia with accessible, multi-functional wearables. A subscription-based model for personalized health analytics offers a compelling go-to-market angle beyond one-time hardware purchases.
For Investors and Strategic Acquirers: Re-rating potential sits with clinical-grade patch developers given the accelerating adoption in hospital settings. The long-term viability centers on the convergence of medical diagnostics with continuous consumer wellness monitoring. Target specialized SaMD companies possessing validated diagnostic algorithms for atrial fibrillation detection. Expansion of telehealth reimbursement policies for remote cardiac monitoring serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Pursue CE Marking under MDR | Securing CE marking enables market access for diagnostic features within the European Union. |
| Develop AI-powered diagnostic algorithms | Advanced algorithms transform raw biometric data into medically actionable insights for clinicians. |
| Establish hospital system partnerships | Collaboration with healthcare providers accelerates clinical validation and adoption of medical-grade wearables. |
| Expand subscription service offerings | Recurring revenue from advanced analytics shifts business models beyond one-time hardware purchases. |
| Invest in cuff-less blood pressure monitoring | Emerging technologies offer continuous, non-invasive blood pressure data for hypertension management. |
Research Approach
Independent corroboration across regulatory body publications, academic research, and industry association reports underwrites the qualitative findings. This study combined primary interviews with medical device engineers, clinical cardiologists, and telehealth providers with extensive secondary validation. Secondary data drew from FDA filings, EU MDR guidance documents, and NMPA announcements. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Rate-of-change decomposition identifies specific drivers influencing market expansion over the projection horizon. The analytical framework modeled segmentation dimensions including device type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical data and projected adoption curves. Telehealth reimbursement rates and regulatory approval timelines served as key industry-specific forecast inputs.
Revisions become necessary when significant shifts in regulatory frameworks or major technological breakthroughs materialize. Forecasts reflect assumptions regarding evolving data privacy regulations and sensor accuracy limitations. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market