
 Global Patient Temperature Monitoring Market | 2026-2036
Global Patient Temperature Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Temperature Monitoring Market Foresight
Subscription-based connectivity for remote patient monitoring platforms is recalibrating how temperature monitoring value gets captured and retained across hospital networks. Cardinal Health leverages its distribution infrastructure to bundle device placement with recurring data-analytics services. Masimo Corporation anchors its competitive stance through advanced signal-processing algorithms that extend monitoring fidelity beyond core temperature to derived hemodynamic indices. Koninklijke Philips N.V. differentiates by integrating thermometry modules within broader patient monitoring ecosystems that sustain multi-parameter contracts.
Patient temperature monitoring encompasses the continuous or intermittent measurement of core and surface body temperature using electronic, infrared, or chemical-based sensor systems, typically achieving clinical accuracy within ±0.1°C for core measurements and ±0.3°C for non-contact surface readings, primarily serving infection detection, perioperative safety, and critical-care surveillance. Digital thermometers retain the largest installed base across hospitals and clinics, though margin pools are migrating toward wireless-enabled platforms that command higher service attach rates. Non-contact thermometry competes aggressively in ambulatory and home care settings where speed and hygiene protocols reshape procurement criteria, while smart devices integrating predictive algorithms represent the fastest-expanding technology tier despite higher upfront validation requirements.
The FDA's Quality System Regulation and 510(k) premarket notification framework govern device safety and software validation for connected thermometry systems entering U.S. clinical settings, while the EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence standards for wireless patient monitors distributed across European member states. ISO 80601-2-56 establishes international performance benchmarks for clinical thermometers that manufacturers must satisfy for broad regulatory acceptance. Stakeholders must weigh the capital intensity of multi-parameter platform integration against the recurring revenue potential of cloud-connected monitoring services as procurement models fragment across fee-for-service and value-based care environments.
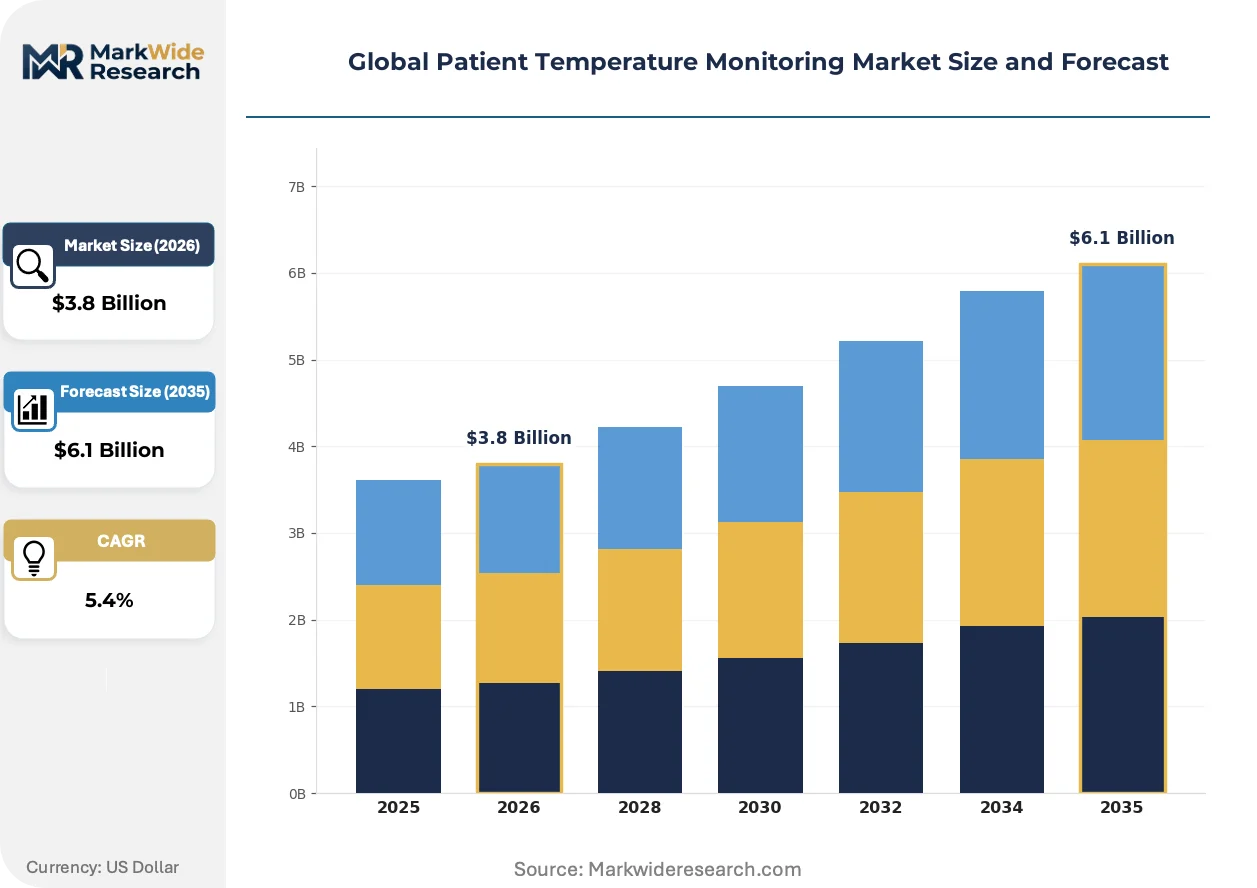
Market Dynamics
Hospital procurement of wireless-enabled continuous monitoring systems is expanding as healthcare systems prioritize early detection of patient deterioration, recalibrating how temperature monitoring value gets captured and retained across acute care networks.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:The FDA's evolving guidance on remote patient monitoring devices is streamlining clearance pathways for connected thermometry platforms entering U.S. clinical settings.
- Electronic Health Record Integration:Integrated EHR compatibility in the United States is driving replacement cycles across acute care networks, forcing upgrades from standalone devices.
- Infrared Sensor Miniaturization:Advances in non-contact infrared thermometry are reshaping hygiene protocols in ambulatory and home care settings where speed dominates procurement criteria.
Market Restraints
- Multi-Parameter Platform Capital Intensity:The capital requirements for integrating thermometry modules within broader patient monitoring ecosystems constrain mid-tier hospital budgets.
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence standards that extend validation timelines for wireless patient monitors.
- Disposable Sensor Input Costs:Volatility in semiconductor and flexible substrate pricing squeezes margins on single-use temperature patches deployed at scale.
Strategic Opportunities
- Home Care Channel Expansion:Retail pharmacy and direct-to-consumer channels for consumer-grade connected thermometers remain underdeveloped relative to institutional sales.
- Predictive Algorithm Convergence:Machine learning integration with core temperature data streams enables derived hemodynamic indices that command premium service attach rates.
- India PLI Scheme Manufacturing:India's production-linked incentive scheme for medical devices offers cost-competitive manufacturing bases for export-oriented thermometry OEMs.
Industry Challenges
- ISO 80601-2-56 Validation Bottlenecks:International performance benchmarking for clinical thermometers requires extensive metrology lab coordination that delays product launches.
- Legacy Device Interoperability:Integration friction with installed base monitoring systems slows wireless platform adoption in budget-constrained regional hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Temperature Monitoring Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Thermistor Sensors, Strip Thermometers End User: Hospitals, Home Care Settings, Clinics, Diagnostic Centers Technology: Contact Thermometry, Non-Contact Thermometry, Wireless Technology, Smart Devices Application: Fever Monitoring, Surgery Recovery, Pediatric Care, Geriatric Care |
| Companies Covered | Cardinal Health, 3M, Koninklijke Philips N.V., Drägerwerk, Hill-Rom Holdings, Masimo Corporation, Omron Healthcare, Becton Dickinson and Company, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Temperature Monitoring Market Shifts & Advancements
Sensor fusion and cloud connectivity are redefining what temperature monitoring hardware captures, how that data flows through clinical workflows, and who retains economic value across the patient journey.
Wireless patch thermometry is modularizing around disposable sensor layers paired with reusable electronic hubs. Acute care networks in Germany and the United States are piloting these platforms for post-surgical wards. This architecture is modularizing procurement decisions, separating capital expenditure on base stations from operational expenditure on single-use patches.
The EU AI Act's risk classification framework is tightening validation requirements for thermometry systems deploying predictive algorithms. Manufacturers must now document training data provenance and clinical performance across demographic subgroups. Class IIa medical devices with embedded AI are experiencing extended notified body review timelines, compressing competitive windows for first movers.
Hospital purchasing consortia are consolidating vendor relationships around multi-parameter monitoring contracts that bundle thermometry with pulse oximetry and capnography. Independent device suppliers face exclusion from integrated tenders unless they demonstrate seamless interoperability with dominant platform ecosystems. This concentration is most visible in United States integrated delivery networks and NHS England procurement frameworks.
Global Patient Temperature Monitoring Market Segmentation
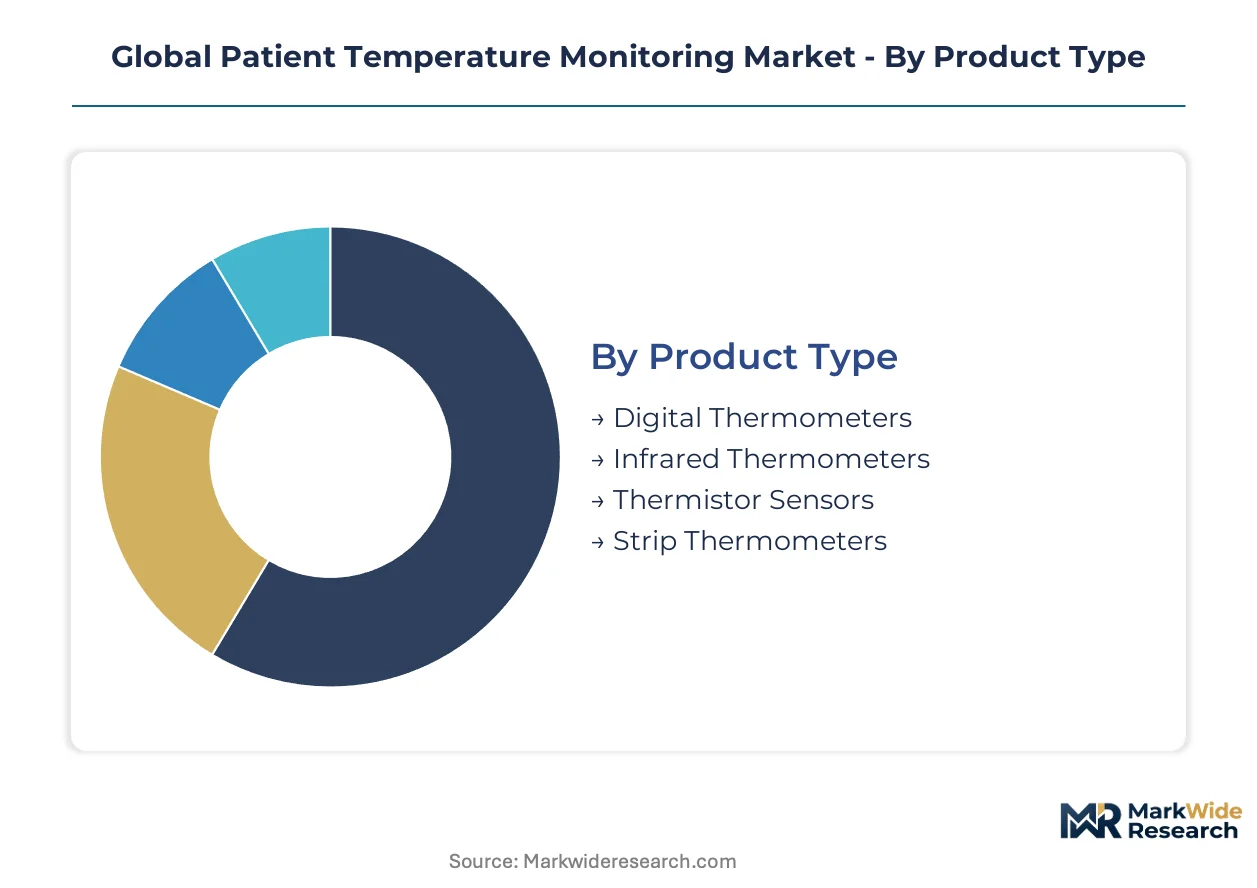
Temperature monitoring procurement splits sharply between institutional buyers seeking integrated platform compatibility and retail channels prioritizing speed and cost. Understanding these fault lines reveals where margin pools concentrate and which technology tiers command premium positioning.
Product Type:
Hospital procurement teams differentiate primarily by calibration stability and wireless integration depth rather than upfront device cost.
- Digital Thermometers:Electronic probe-based systems with thermistor or thermocouple sensors achieving ±0.1°C accuracy in core measurements. Demand concentrates across United States acute care networks where EHR integration mandates drive replacement cycles from standalone units to connected platforms.
- Infrared Thermometers:Non-contact optical sensors detecting thermal radiation from tympanic or temporal arteries, delivering readings within 1-2 seconds. Adoption accelerates in ambulatory clinics and German hospital networks where hygiene protocols and throughput speed reshape procurement criteria.
- Thermistor Sensors:Temperature-sensitive semiconductor elements with negative temperature coefficient characteristics, commonly embedded in multi-parameter patient monitors.
- Strip Thermometers:Single-use chemical-based indicators for surface temperature approximation, deployed in resource-constrained settings and emergency triage.
Digital thermometers lead volumes today; infrared thermometers are gaining share fastest.
End User:
Volume concentration follows reimbursement structure complexity, with integrated delivery networks consolidating purchasing power away from fragmented outpatient settings.
- Hospitals:Acute care networks deploying continuous monitoring across ICU, perioperative, and general ward environments. United States integrated delivery networks and NHS England procurement frameworks bundle thermometry within multi-parameter monitoring contracts that sustain vendor concentration.
- Home Care Settings:Post-discharge and chronic disease management environments where patients or caregivers perform intermittent monitoring. Retail pharmacy channels and direct-to-consumer platforms remain underdeveloped relative to institutional sales, creating whitespace for connected device penetration.
- Clinics:Outpatient facilities prioritizing speed and infection control in high-throughput environments.
- Diagnostic Centers:Specialized facilities integrating temperature screening within broader physiological assessment protocols.
Hospitals capture the dominant revenue share; home care settings show the steepest expansion trajectory.
Technology:
Technology selection hinges on whether workflows prioritize absolute accuracy, hygiene assurance, or predictive capability.
- Contact Thermometry:Probe-based measurement requiring physical patient interface, including oral, rectal, axillary, and bladder catheter methods. Retains installed base dominance in United States surgical suites where core temperature accuracy remains non-negotiable for anesthesia safety protocols.
- Non-Contact Thermometry:Infrared and thermal imaging methods eliminating cross-contamination risk. Deployment accelerates in Japanese outpatient networks and airport screening facilities where throughput speed and hygiene protocols dominate procurement decisions.
- Wireless Technology:Bluetooth and proprietary radio protocols enabling continuous data transmission to central monitoring stations. Cloud-connected platforms command recurring service attach rates that recalibrate vendor economics.
- Smart Devices:Embedded algorithms deriving hemodynamic indices from temperature variability patterns. EU AI Act risk classification extends validation timelines for these systems.
Contact thermometry maintains the largest installed base; smart devices are climbing the fastest.
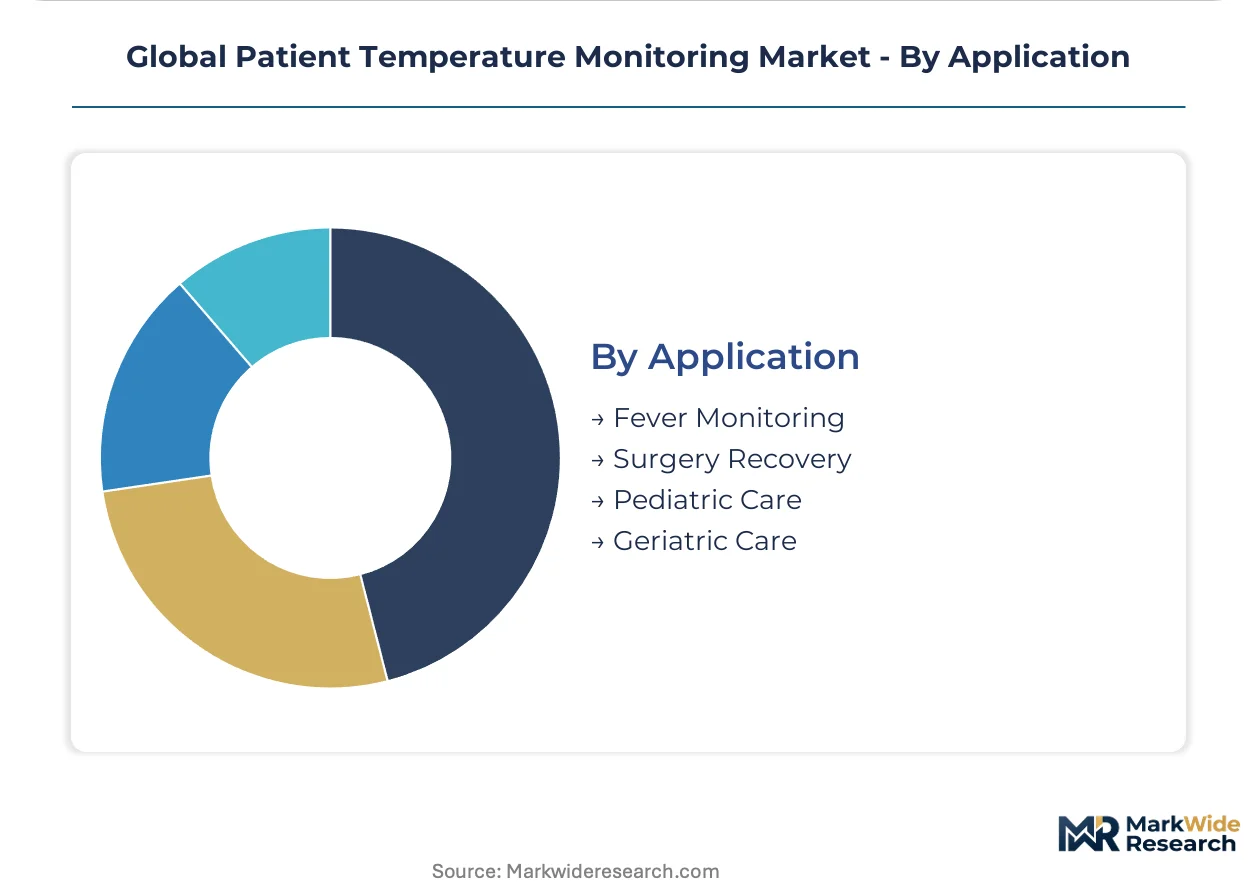
Application:
Application segmentation tracks clinical acuity thresholds and reimbursement intensity across care episodes.
- Fever Monitoring:Infection detection and antibiotic stewardship workflows requiring precise threshold detection. Demand concentrates in emergency departments and infectious disease wards where early sepsis identification drives clinical protocols.
- Surgery Recovery:Perioperative hypothermia prevention and post-anesthesia monitoring. United States hospital networks prioritize continuous core temperature surveillance for surgical patients under enhanced recovery after surgery protocols.
- Pediatric Care:Neonatal and infant monitoring where measurement speed and non-invasive methods reduce distress.
- Geriatric Care:Long-term temperature surveillance for immunocompromised elderly populations with atypical fever presentations.
Fever monitoring leads procedure volumes today; surgery recovery applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with streamlined device approval pathways and production incentives. The cost-of-compliance gap between the EU MDR's clinical evidence burden and the FDA's 510(k) acceleration is reshaping where thermometry OEMs locate final assembly and validation labs.
United States
Integrated delivery networks in Texas and California are consolidating vendor relationships around multi-parameter monitoring contracts that bundle thermometry with pulse oximetry. FDA's evolving guidance on remote patient monitoring streamlines clearance pathways for connected platforms. The Minneapolis medical device cluster anchors wireless-enabled continuous monitoring system development for acute care networks.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia pilot wireless patch thermometry for post-surgical wards under enhanced recovery protocols. EU MDR imposes stricter post-market surveillance standards that extend validation timelines for wireless patient monitors. The Berlin-Brandenburg region concentrates AI-enabled thermometry algorithm development subject to EU AI Act risk classification.
China
Domestic hospital procurement prioritizes cost-competitive infrared thermometry for infection control in high-throughput outpatient settings. NMPA medical device registration pathways accommodate software-as-a-medical-device innovations faster than hardware-heavy submissions. The Yangtze River Delta manufacturing base supplies non-contact sensor modules for export-oriented OEMs.
India
Tier-2 city hospital expansions drive demand for digital thermometers with basic connectivity at price points below wireless patch systems. India's production-linked incentive scheme for medical devices offers cost-competitive manufacturing bases for thermometry exporters. The Karnataka medical technology corridor in Bangalore hosts contract manufacturers serving European and North American markets.
Japan
Aging demographics and home care policy shifts accelerate retail pharmacy distribution of consumer-grade connected thermometers. PMDA streamlined review pathways for Class II devices with predicate approvals in the United States or EU. The Kansai region around Osaka maintains precision sensor fabrication capabilities for thermistor elements deployed in multi-parameter monitors.
Global Patient Temperature Monitoring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement favoring integrated platform vendors while retail channels accommodate private-label suppliers. The vendor base concentrates around three tiers: diversified medical technology conglomerates with multi-parameter ecosystems, pure-play thermometry specialists leveraging distribution scale, and component OEMs supplying sensor modules to third-party device assemblers. Strategic moves center on software validation partnerships for AI-enabled features and manufacturing relocation to capture India's PLI scheme benefits.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Drägerwerk occupy positions anchoring multi-parameter monitoring contracts that sustain vendor concentration across United States integrated delivery networks and NHS England frameworks. Cardinal Health exemplifies the distribution-leveraged archetype, bundling device placement with recurring data-analytics services that recalibrate how temperature monitoring value gets captured across hospital networks.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M |
| Koninklijke Philips N.V. |
| Drägerwerk |
| Hill-Rom Holdings |
| Masimo Corporation |
| Omron Healthcare |
| Becton Dickinson and Company |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Captive sensor fabrication in Japan and Taiwan anchors supply positions for precision thermistor elements while simultaneously constraining pricing power for downstream device assemblers lacking backward integration into semiconductor foundry capacity. This vertical control over negative-temperature-coefficient substrates allows integrated manufacturers to capture margin premiums on multi-parameter monitoring modules while forcing pure-play thermometry vendors into price-competitive procurement of standardized probe assemblies.
Pricing Analysis
Distributor margin layers in United States hospital procurement typically absorb 18-25 points before GPO-negotiated pricing reaches integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless platforms with EHR integration from basic digital probes and single-use chemical strips. Pricing pressure stems from India's PLI scheme attracting cost-competitive manufacturing for export-oriented OEMs serving mid-tier hospital budgets. Home care retail channels exhibit highest price sensitivity due to direct-to-consumer comparison shopping, while perioperative suites in academic medical centers prioritize accuracy certification over unit cost.
Supply Chain Analysis
Thermistor wafer supply rests on Japanese precision ceramics producers and Taiwanese semiconductor foundries with specialized temperature-sensor process lines. Flexible substrate materials for disposable patches draw from South Korean petrochemical complexes and Chinese specialty film manufacturers. Single-source vulnerability concentrates in infrared detector arrays where German and American defense-aerospace suppliers dominate civilian medical allocation. Distribution runs through Cardinal Health and regional medical-surgical distributors serving hospital purchasing consortia, with direct OEM relationships gaining share in wireless platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient temperature monitoring has entered a late-cycle quality phase where hospital procurement committees prioritize FDA-cleared predictive algorithms over basic thermometry accuracy, favoring vendors with validated software companion applications and demonstrated EHR interoperability.
For Market Incumbents: Extend platform stickiness by embedding thermometry modules within broader patient monitoring ecosystems that bundle pulse oximetry and capnography, defending against disintermediation by pure-play AI analytics vendors. Deepen backward integration into thermistor wafer supply through partnerships with Japanese precision ceramics producers, securing input cost stability against semiconductor pricing volatility.
For New Entrants and Emerging Players: Retail pharmacy chains represent the most penetrable channel partner type for consumer-grade connected thermometers, given underdeveloped direct-to-consumer platforms relative to institutional sales concentration. Target post-discharge fever monitoring workflows in German and Japanese home care policy environments where reimbursement shifts accelerate remote patient monitoring adoption. Pursue software-as-a-medical-device regulatory pathways that bypass hardware-heavy validation timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional thermometry specialists with established hospital GPO contracts because procurement consolidation across United States integrated delivery networks favors vendors with multi-site service infrastructure. Focus acquisition screening on Class IIa device manufacturers with predicate 510(k) clearances and demonstrated AI algorithm validation under EU AI Act risk classification. Watch FDA guidance evolution on continuous monitoring software validation as the inflection signal for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined clearance for connected thermometry platforms reduces time-to-revenue for wireless-enabled entrants. |
| Hospital System Partnership | Multi-parameter monitoring contracts with Texas and California IDNs sustain vendor concentration across acute care networks. |
| Software Companion Development | Predictive algorithms deriving hemodynamic indices from temperature variability command premium service attach rates. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend validation timelines but create defensive moats for compliant manufacturers. |
| Reimbursement Strategy | CPT code alignment for remote patient monitoring services recalibrates economic value capture toward recurring revenue models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with hospital biomedical engineers, GPO contracts managers, regulatory affairs specialists at thermometry OEMs, and procurement leads at integrated delivery networks. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement contract disclosures, and ISO 80601-2-56 technical standard documentation. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Historical reference periods anchored the forecast window through installed base analysis of digital thermometer replacement cycles and wireless platform adoption curves in United States acute care networks. Segmentation modeling captured product type, end user environment, technology tier, and clinical application intensity. CAGRs were derived from regression analysis of procurement volume trends against regulatory clearance timelines and EHR integration mandates. Industry-specific inputs included semiconductor pricing indices for thermistor substrates and FDA guidance evolution on software validation requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement patterns and NMPA registration pathway shifts for software-as-a-medical-device innovations. Forecasts reflect documented assumptions regarding hospital capital expenditure recovery trajectories and wireless patch thermometry pilot-to-scale conversion rates. A small set of named triggers warrants ongoing watch: FDA premarket review backlog accumulation, India PLI scheme capacity commissioning timelines, and German hospital network procurement framework renewals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market