
 Blood Temperature Indicator Market | 2026-2036
Blood Temperature Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Temperature Indicator Market Analysis
Aftermarket service revenue for calibration and recertification is narrowing as manufacturers shift toward integrated digital platforms with self-diagnostic capabilities. Thermo Fisher Scientific extends its footprint through laboratory-grade precision systems that command premium positioning in research institutions. Elitech competes on cost-engineered portable devices that dominate clinic and emergency services channels across Asia-Pacific and Latin America.
Blood temperature indicators are electromechanical or chemical devices engineered to monitor and record thermal conditions of blood products during storage, transport, and handling, typically operating within precision ranges of one to ten degrees Celsius with alarm thresholds calibrated to AABB standards. Their primary commercial purpose is to prevent hemolytic degradation and bacterial proliferation that compromise transfusion safety. Infrared technology leads product type segments due to its non-contact measurement speed and elimination of contamination risks in sterile environments, while biochemical sensors represent the fastest-expanding category as pharmaceutical companies adopt single-use indicators for clinical trial logistics. Wireless technologies concentrate margin pools through recurring software licensing and cloud-based compliance documentation that locks in multi-year hospital contracts.
FDA blood storage regulations and AABB accreditation standards shape product design requirements, mandating continuous temperature documentation with audit-trail capabilities for all licensed blood centers. The EU MDR and CE marking frameworks govern device classification and clinical evidence thresholds for indicators marketed across European healthcare systems. Stakeholders must monitor evolving interoperability mandates as health systems consolidate procurement around platforms that integrate directly with electronic medical records and laboratory information management systems.
Market Dynamics
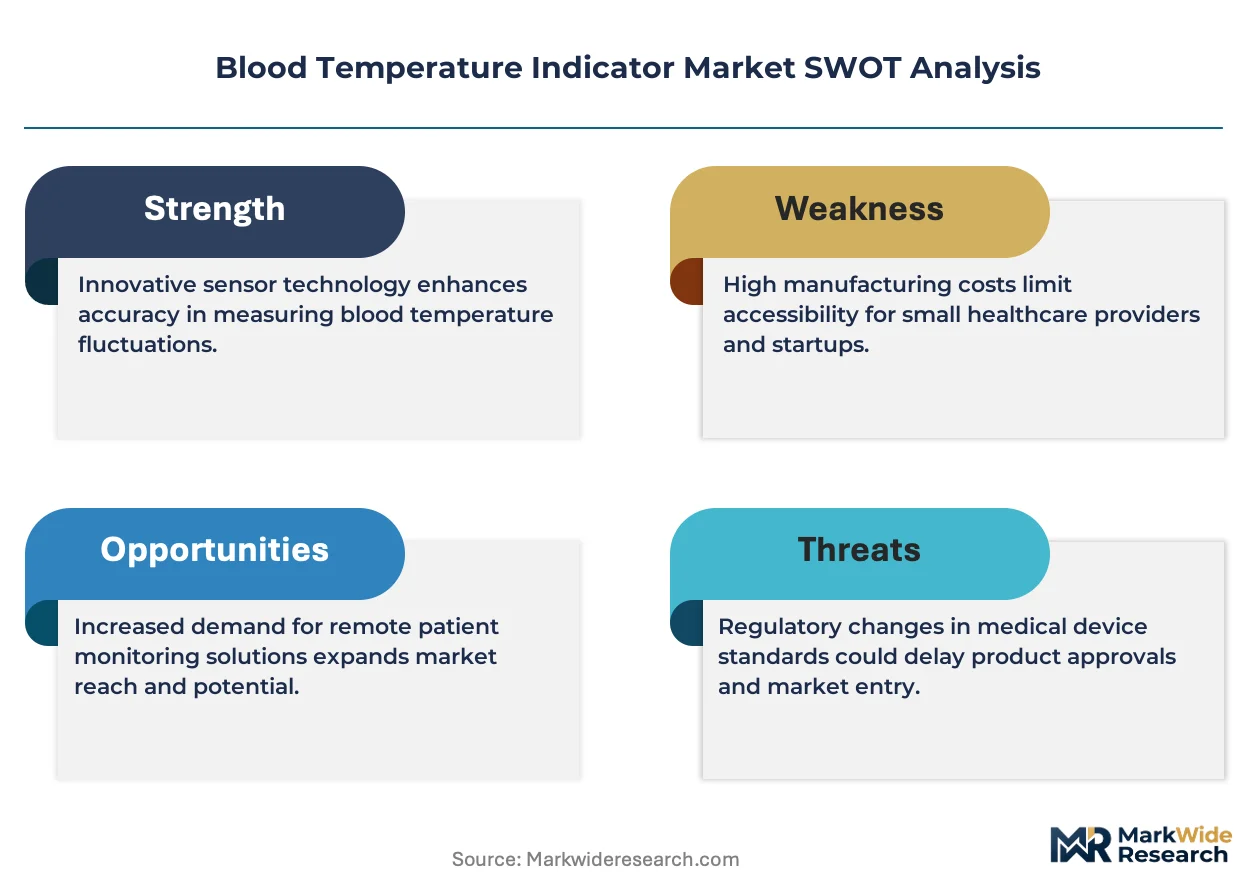
Hospital blood banks are consolidating procurement around integrated digital platforms that bundle continuous temperature monitoring with automated compliance documentation, compressing vendor margins while elevating technical performance requirements.
Growth Catalysts
- FDA Blood Storage Guidelines:Updated mandates for continuous temperature documentation with audit-trail capabilities are accelerating replacement cycles across licensed US blood centers.
- Wireless Cloud Integration:Recurring software licensing models tied to cloud-based compliance platforms are locking hospital networks into multi-year service contracts with predictable revenue streams.
- Asia-Pacific Clinic Expansion:Emergency services and rural clinic networks across India and Southeast Asia are deploying portable indicators for last-mile plasma distribution integrity.
Market Restraints
- Lithium Battery Cost Volatility:Portable indicator supply chains face input pressure from fluctuating battery cell pricing and constrained rare earth processing capacity.
- EU MDR Certification Friction:Elevated clinical evidence thresholds for Class IIa medical devices are extending time-to-market for new indicator submissions by 12-18 months.
- Single-Use Indicator Waste Liability:Biochemical sensor disposal costs are rising as healthcare systems internalize environmental compliance burdens previously externalized to suppliers.
Strategic Opportunities
- Latin America Cold Chain Gaps:Underpenetrated blood bank infrastructure in Brazil and Mexico offers first-mover positioning for cost-engineered portable devices.
- ISO 13485-Aligned Platform Convergence:Integration of temperature indicators with laboratory information management systems creates bundled procurement advantages for vendors with interoperability certifications.
- Clinical Trial Logistics:Pharmaceutical companies are adopting single-use biochemical indicators for cell therapy and biologics transport, opening adjacent revenue pools beyond traditional blood banking.
Industry Challenges
- Embedded Firmware Expertise Scarcity:Vendors struggle to recruit engineers capable of developing self-diagnostic algorithms that meet FDA software validation requirements.
- Legacy LIMS Integration Complexity:Hospital IT departments face protracted API configuration timelines when connecting new wireless indicators to aging laboratory information infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Temperature Indicator Market |
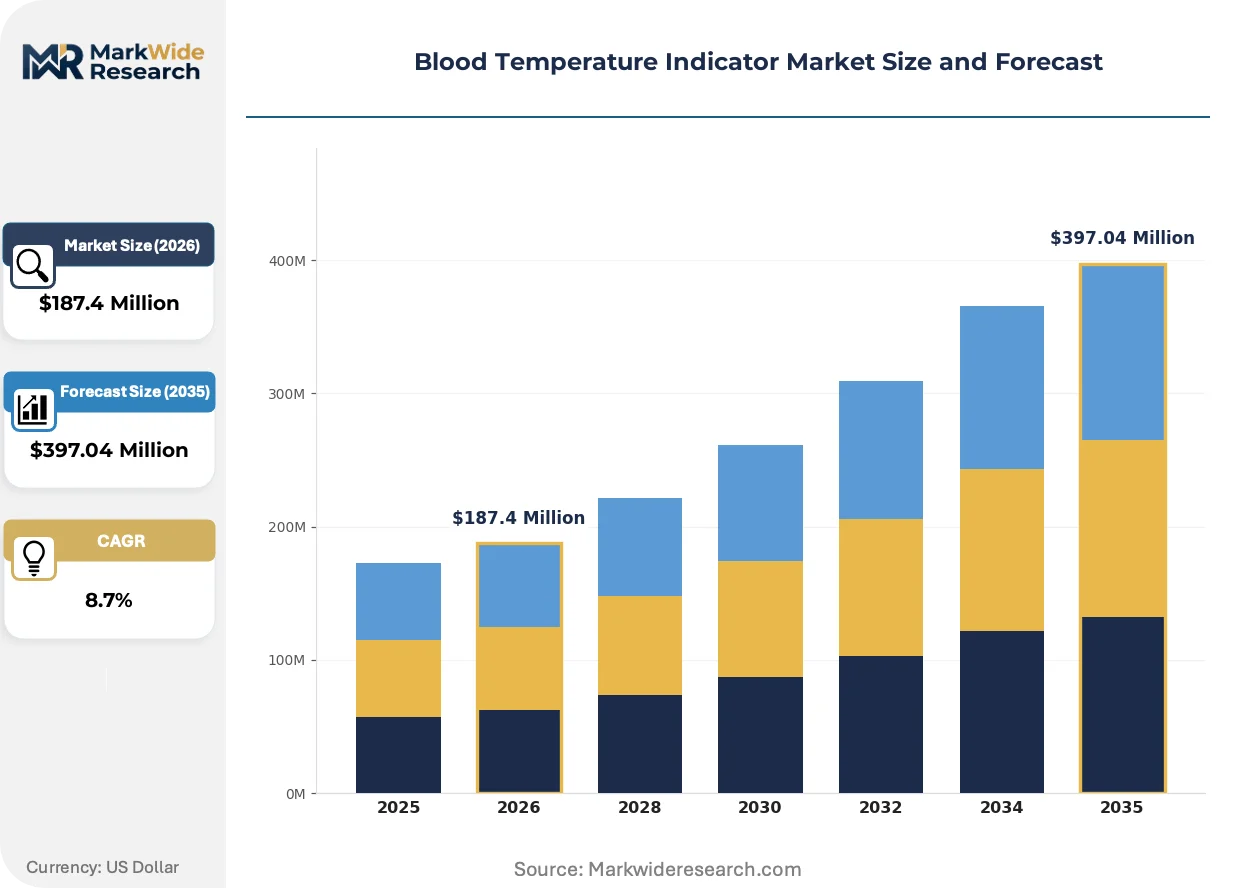
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Thermocouples, Fiber Optic Sensors Application: Hospitals, Home Care, Laboratories, Research Institutions Technology: Infrared Technology, Thermoelectric Sensors, Biochemical Sensors, Wireless Technologies End User: Clinics, Emergency Services, Pharmaceutical Companies, Healthcare Professionals |
| Companies Covered | Elitech, Thermo Fisher Scientific Inc., Sercalia, Ellab Group, Zebra Technologies Corporation, Lisaline Lifesciences Technologies, Stream Peak International PTE Ltd, 3M, DeltaTrak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Temperature Indicator Market Emerging Trajectories
Electrochemical sensing architectures and cloud-native compliance platforms are converging to redefine performance benchmarks and procurement economics across blood temperature monitoring.
Infrared non-contact measurement systems are collapsing the performance gap between laboratory-grade precision and field-deployable portability. Regional hospital networks in Germany and Japan are adopting these hybrid platforms for both centralized blood bank operations and mobile collection units. The technology is collapsing traditional tier boundaries that previously separated research institutions from clinical deployment channels.
EU MDR device classification rules are tightening clinical evidence requirements for temperature indicators marketed across European healthcare systems. Manufacturers must now submit prospective performance data rather than predicate device equivalency for CE marking renewals. Blood centers in France and Italy are delaying procurement decisions until vendors demonstrate compliance with the elevated MDR technical documentation standards.
Subscription-based service contracts are displacing capital equipment purchases across consolidated US hospital networks. Banner Health and Kaiser Permanente are bundling indicator hardware, calibration, and compliance software into per-unit-per-month pricing. This shift concentrates purchasing authority with procurement departments rather than laboratory managers, compressing vendor sales cycles and elevating price transparency requirements.
Blood Temperature Indicator Market Segmentation
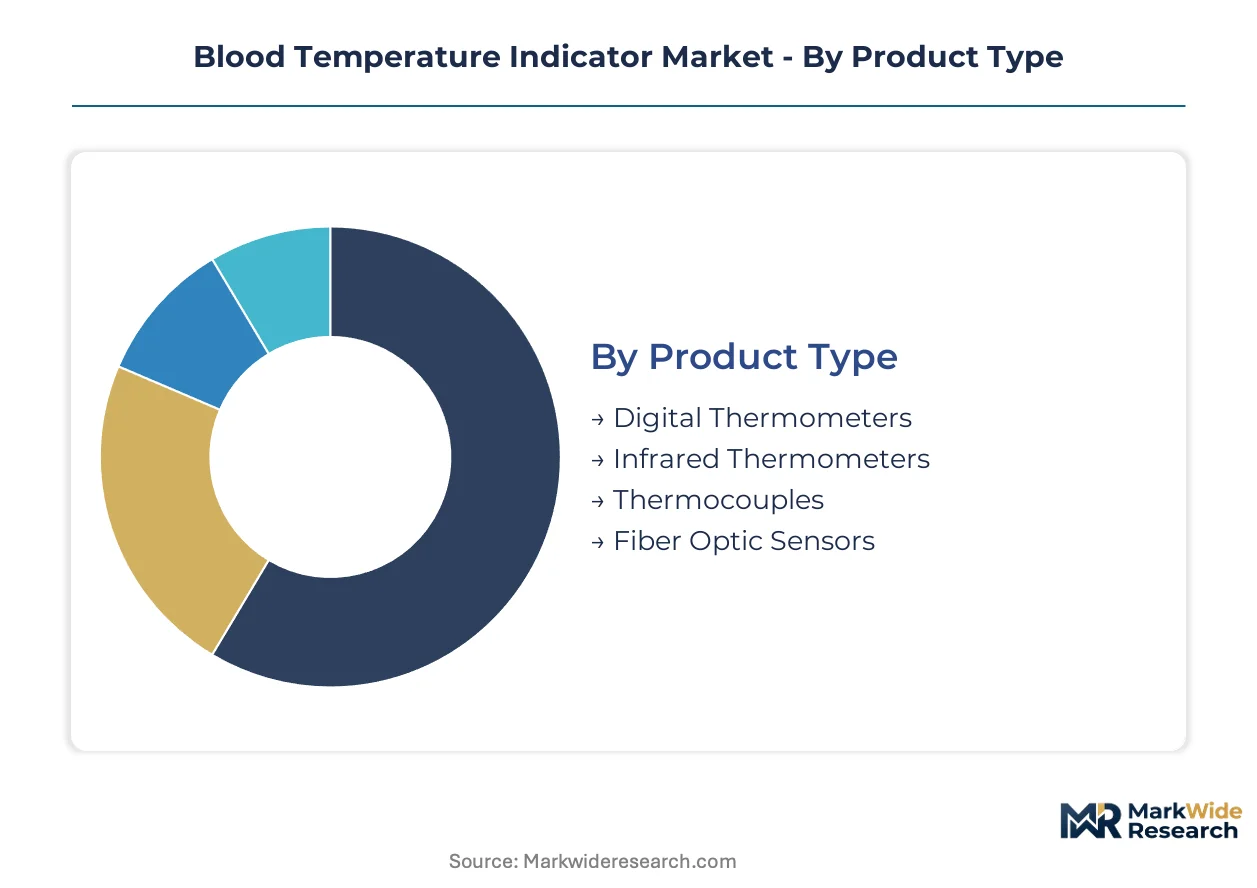
Blood temperature indicators serve divergent operational environments ranging from sterile laboratory calibration to field-deployable emergency response. Segment boundaries reflect fundamental trade-offs between measurement precision, portability requirements, and regulatory documentation burdens.
Product Type:
Use-case spectrum spans laboratory-grade calibration systems through disposable single-use chemical indicators, with cost-per-test and reusability driving procurement decisions.
- Digital Thermometers:Solid-state electronic devices with LCD readouts and programmable alarm thresholds calibrated to AABB standards. Hospital blood banks in the United States prioritize these for plasma inventory management under FDA continuous documentation mandates.
- Infrared Thermometers:Non-contact optical systems measuring thermal radiation without breaching sterile packaging integrity. Demand concentrates in Japanese and German hospital networks adopting hybrid platforms for both centralized blood bank operations and mobile collection units.
- Thermocouples:Junction-based temperature probes offering millisecond response times for research protocols requiring high-frequency sampling.
- Fiber Optic Sensors:Immune to electromagnetic interference, these suit MRI-adjacent blood storage facilities and specialized research environments.
The dominant share belongs to Infrared Thermometers, while Biochemical Sensors (addressed under Technology) is closing the gap fastest.
Application:
Volume concentration tracks regulatory stringency, with facilities under FDA or EMA jurisdiction commanding higher equipment specification tiers than unregulated settings.
- Hospitals:Integrated digital platforms bundling continuous monitoring with automated compliance documentation. Banner Health and Kaiser Permanente in the United States are standardizing per-unit-per-month subscription contracts across their networks.
- Laboratories:Thermo Fisher Scientific commands premium positioning here through precision systems serving research institutions with ISO 17025 calibration requirements.
- Home Care:Simplified indicators for patient-managed coagulation therapy, with cost sensitivity limiting feature sets.
- Research Institutions:Custom-configured multi-channel logging systems for transfusion medicine studies.
Hospitals capture the largest installed base, though Laboratories maintain the highest average selling prices per unit.
Technology:
Margin pools concentrate where recurring revenue attaches to hardware through software licensing and cloud compliance platforms.
- Infrared Technology:Collapsing performance boundaries between laboratory precision and field portability through solid-state detector advances. Regional networks in Germany and Japan are adopting these hybrid platforms for dual-use deployment.
- Wireless Technologies:Cloud-native platforms generating multi-year service contracts through automated audit-trail documentation. FDA mandates for continuous temperature logging with electronic record integrity are accelerating hospital procurement.
- Thermoelectric Sensors:Solid-state devices without moving parts, favored for extreme temperature cycling durability.
- Biochemical Sensors:Single-use color-change or electronic indicators eliminating calibration overhead. Pharmaceutical companies are adopting these for cell therapy clinical trial logistics, opening adjacent revenue pools.
Infrared Technology holds established share leadership, yet Wireless Technologies is climbing the fastest as subscription models displace capital purchases.
End User:
Customer procurement authority is shifting from laboratory managers to centralized supply chain departments as subscription models standardize.
- Clinics:Cost-engineered portable devices dominating Asia-Pacific and Latin America expansion. Elitech competes aggressively here with simplified indicators for rural plasma distribution.
- Emergency Services:Battery-powered units with ruggedized enclosures for ambulance and helicopter transport. Lithium cell cost volatility constrains margin stability.
- Pharmaceutical Companies:Biochemical single-use indicators for biologics and cell therapy cold chain verification, with disposal liability rising under extended producer responsibility frameworks.
- Healthcare Professionals:Individual practitioners with limited procurement authority, typically served through distributor channels.
Clinics represent the broadest addressable base, while Pharmaceutical Companies deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States deploy continuous monitoring systems for plasma inventory management, while clinics across India and Southeast Asia rely on portable battery-powered units for last-mile distribution integrity.
United States
The American Red Cross and Banner Health are standardizing temperature verification protocols across collection networks. FDA updated blood storage guidelines mandate continuous documentation with audit-trail capabilities for all licensed centers. Kaiser Permanente in California is bundling indicator hardware into per-unit-per-month subscription contracts.
Germany
Regional hospital networks are adopting hybrid infrared platforms for both centralized blood bank operations and mobile collection units. EU MDR device classification rules now require prospective performance data rather than predicate device equivalency for CE marking renewals. The Rhine-Ruhr metropolitan cluster is delaying procurement decisions until vendors demonstrate compliance with elevated technical documentation standards.
Japan
Metropolitan hospital systems in Tokyo and Osaka are deploying non-contact optical systems measuring thermal radiation without breaching sterile packaging integrity. METI standards govern medical device quality management systems for temperature monitoring equipment. The Kansai region is consolidating procurement around integrated digital platforms that bundle continuous monitoring with automated compliance documentation.
India
Emergency services and rural clinic networks across Maharashtra and Karnataka are deploying cost-engineered portable indicators for plasma distribution integrity. CDSCO medical device regulations are tightening registration requirements for imported temperature monitoring equipment. The Delhi-NCR corridor is witnessing expansion of cold chain infrastructure for blood component storage in tertiary care facilities.
Brazil
Underpenetrated blood bank infrastructure in São Paulo and Rio de Janeiro is creating first-mover positioning for portable device manufacturers. ANVISA medical device regulations govern market access for temperature indicators used in healthcare settings. The Southeast region is investing in cold chain modernization for platelet and plasma storage networks.
Blood Temperature Indicator Market Vendor Landscape
Capability concentration sits with laboratory-grade precision specialists; scale advantage sits with cost-engineered portable device manufacturers. The market structures around three tiers: premium precision systems for research institutions, mid-range integrated platforms for hospital networks, and economy portable units for clinic and emergency channels. Strategic archetypes include technology licensors with recurring software revenue models, regional fabricators competing on landed cost, and diversified life science conglomerates leveraging distribution scale. Dominant competitive moves encompass M&A to acquire wireless platform capabilities and strategic partnerships with laboratory information management system vendors.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and 3M occupy positions spanning precision instrumentation through disposable indicators. Elitech represents the cost-engineered portable device archetype competing across Asia-Pacific and Latin America expansion markets. Zebra Technologies Corporation sits within the wireless platform tier where cloud-native compliance documentation generates multi-year service contract lock-in.
| Leading Market Players |
|---|
| Elitech |
| Thermo Fisher Scientific Inc. |
| Sercalia |
| Ellab Group |
| Zebra Technologies Corporation |
| Lisaline Lifesciences Technologies |
| Stream Peak International PTE Ltd |
| 3M |
| DeltaTrak Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam freight corridors transmit lithium cell cost volatility directly into portable indicator manufacturing economics, compressing margins for cost-engineered units while amplifying price differentiation between subscription-based hospital platforms and disposable clinic devices.
Pricing Analysis
Long-term service contracts with multi-year software licensing dominate hospital procurement in the United States, displacing capital equipment purchases. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification status, with premium positioning commanding three-to-five-fold multiples over uncertified alternatives. Cost compression in the portable segment intensifies as Elitech and regional fabricators compete on landed cost in Asia-Pacific expansion markets. Emergency services and rural clinics exhibit highest price sensitivity, while research institutions and consolidated hospital networks prioritize technical performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn and Jabil Electronics for sensor assembly and firmware integration, with final calibration and certification retained by brand owners. Component sourcing draws from China for lithium battery cells, Taiwan for infrared detector modules, and Germany for precision thermocouple wire. Single-source vulnerability in rare earth processing for battery cathodes exposes supply continuity to export restriction risk. Distribution runs through GPO contracts and laboratory equipment distributors serving hospital networks, with direct-to-clinic channels expanding in underpenetrated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers creates niche positioning opportunities as FDA, EU MDR, and CDSCO standards diverge in evidence requirements and audit protocols.
For Market Incumbents: Harden subscription platform stickiness by embedding self-diagnostic firmware that automates FDA software validation documentation, reducing hospital IT integration friction. Deepen backward integration into infrared detector module production to offset Taiwan supply concentration and defend margin position against cost-engineered portable entrants. Prioritize ISO 13485-aligned LIMS interoperability certifications that lock in multi-year hospital network contracts. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical clinical trial logistics where single-use biochemical sensor demand outpaces established blood banking channels. Target underpenetrated blood bank infrastructure in Brazil and Mexico with cost-engineered portable devices certified to ANVISA Class IIa standards. Deploy distributor partnerships with regional laboratory equipment channels rather than direct hospital sales to accelerate market access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core temperature monitoring divisions lacking wireless platform integration. Long-term viability favors vendors with recurring software revenue attaching to hardware through cloud compliance documentation. Monitor FDA software validation requirement expansion as inflection signal for acquisition premium compression in legacy electromechanical indicator portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Platform Integration | Cloud-native compliance documentation locks hospital networks into multi-year service contracts with predictable recurring revenue. |
| EU MDR Technical Documentation Investment | Prospective clinical evidence submissions extend time-to-market but create regulatory moats against predicate-device competitors. |
| Biochemical Sensor Portfolio Expansion | Single-use indicators for cell therapy logistics open adjacent revenue pools beyond traditional plasma and platelet monitoring. |
| LIMS Interoperability Certification | ISO 13485-aligned API integration creates bundled procurement advantages in consolidated US hospital networks. |
| Latin America Distribution Partnership | ANVISA-registered portable devices capture first-mover positioning in São Paulo and Rio de Janeiro cold chain modernization. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and hospital GPO contract records preceded structured interviews with biomedical engineers, blood bank operations directors, laboratory information system managers, and pharmaceutical supply chain executives. Secondary validation drew from AABB accreditation standards, CDSCO medical device registration data, and customs import records for temperature monitoring equipment. Bottom-up unit economics modeling triangulated against top-down hospital procurement spend estimates.
Assumption sets held wireless cloud adoption rates and FDA software validation requirement stringency fixed at baseline levels, with lithium battery cost trajectories and EU MDR certification friction varied across sensitivity scenarios. Segmentation dimensions spanned product precision tier, end-use regulatory environment, technology architecture, and geographic procurement authority concentration. CAGRs derived from logistic diffusion curves fitted to hospital network standardization timelines and pharmaceutical clinical trial expansion patterns.
Stress conditions across rare earth export restrictions, lithium cell price volatility bands, and EU MDR renewal timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline regulatory trajectories. Quarterly review of FDA guidance document releases and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market