
 Pneumology Digital Stethoscope Market | 2026-2036
Pneumology Digital Stethoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumology Digital Stethoscope Market Analytics
A shift from single-source acoustic component supply toward multi-source sensor procurement is hardening across the pneumology digital stethoscope value chain. Eko Health, Inc. leverages its FDA-cleared AI algorithms to anchor premium positioning in cardiopulmonary analysis. 3M sustains manufacturing scale across its Littmann digital portfolio, while Thinklabs specializes in high-fidelity electronic stethoscope engineering for research-intensive medical centers.
A pneumology digital stethoscope converts acoustic chest sounds into digital signals via piezoelectric or MEMS sensors, enabling spectral analysis, noise reduction, and cloud-based transmission at sampling rates typically exceeding 4,000 Hz for diagnostic fidelity. Wireless stethoscopes lead product type expansion as clinicians prioritize untethered examination workflows in isolation settings and telehealth consultations. AI Integration commands the fastest growth within technology segments, though acoustic transmission platforms still occupy the largest installed base due to lower unit costs and simpler regulatory pathways.
FDA 510(k) requirements govern premarket notification for digital auscultation devices, while HIPAA mandates encrypt patient audio data transmitted through Bluetooth or cloud platforms. The EU MDR and CE marking framework impose clinical evidence standards on smartphone-compatible stethoscopes sold in European markets. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostic software and determine whether to pursue parallel regulatory submissions or sequential market entry strategies.
Market Dynamics
The pneumology digital stethoscope market is compressing around regulatory acceleration for AI-enabled diagnostics and the migration of auscultation workflows toward cloud-integrated telehealth platforms. FDA clearance timelines for software-as-medical-device submissions are shortening as predicate device libraries expand, while pulmonology departments hardwire remote monitoring into standard care protocols.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Medicare coverage expansion for remote physiological monitoring in the United States is pulling digital stethoscope procurement into hospital capital budgets. Pulmonology departments are prioritizing connected devices that transmit lung sound data directly to electronic health records.
- FDA 510(k) Predicate Pathway:The FDA's accumulation of cleared digital auscultation predicates is compressing premarket notification timelines for new entrants. Manufacturers are leveraging substantial equivalence claims to accelerate product launches.
- MEMS Sensor Cost Curves:Microelectromechanical systems fabrication scaling is reducing bill-of-materials costs for high-fidelity acoustic sensors. Asian foundry capacity expansion is feeding component supply into device assembly operations.
Market Restraints
- Piezoelectric Ceramic Supply Concentration:High-sensitivity piezoelectric material production clusters in East Asian specialty ceramics manufacturers. Single-source dependencies for medical-grade formulations create input volatility risk.
- HIPAA Encryption Overhead:HIPAA-mandated end-to-end encryption for patient audio data transmission imposes computational and certification burdens on Bluetooth-enabled device architectures. Engineering teams must allocate resources to security validation rather than acoustic algorithm development.
- Acoustic Stethoscope Substitution:Conventional mechanical stethoscopes retain cost and reliability advantages in resource-constrained clinical settings. Price-sensitive procurement committees in developing health systems defer digital upgrades.
Strategic Opportunities
- Home-Based COPD Monitoring:Underpenetrated patient populations with chronic obstructive pulmonary disease in Germany and Japan represent deployable demand for prescription-grade digital stethoscopes. Reimbursement frameworks for home respiratory monitoring are crystallizing in both markets.
- AI-Enhanced Spectral Analysis:Machine learning convergence with time-frequency decomposition algorithms is opening diagnostic white space beyond basic waveform capture. Developers are training models on specific adventitious lung sound classification.
- Direct-to-Consumer Telehealth Channels:Subscription-based virtual pulmonology platforms are creating new device distribution vectors outside traditional hospital procurement. Digital health startups are bundling stethoscope hardware with clinician access fees.
Industry Challenges
- FDA Software-as-Medical-Device Expertise Gap:Engineering teams lack regulatory affairs specialists fluent in FDA guidance documents for AI-enabled diagnostic algorithms. Hiring timelines for qualified personnel are extending product development schedules.
- Legacy EHR Integration Complexity:Hospital information systems require custom API development for seamless audio data ingestion. IT departments are prioritizing integration projects based on vendor scale, disadvantaging smaller device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumology Digital Stethoscope Market |
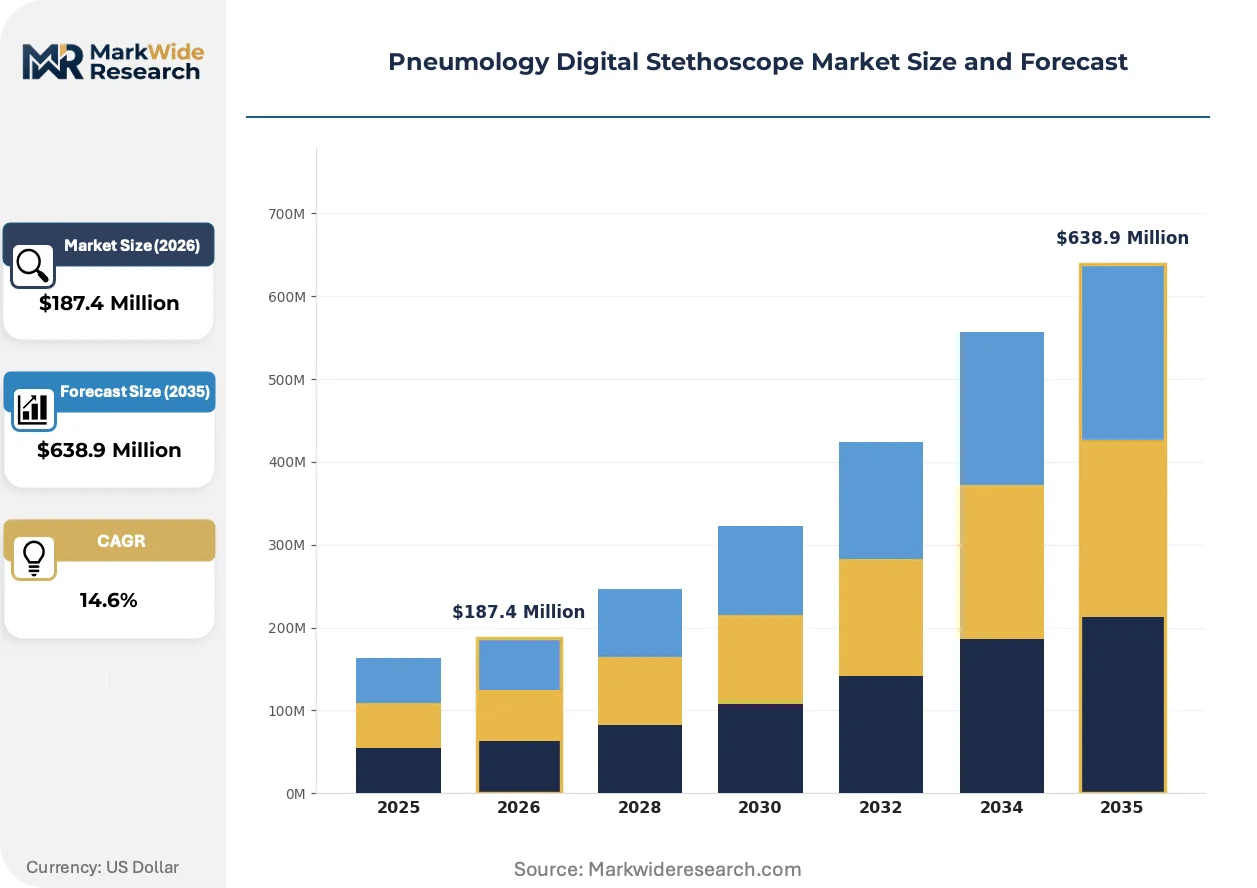
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Stethoscopes, Digital Stethoscopes, Wireless Stethoscopes, Smartphone-Compatible Stethoscopes End User: Hospitals, Private Clinics, Telehealth Providers, Home Healthcare Technology: Acoustic Transmission, Digital Signal Processing, Bluetooth Connectivity, AI Integration Distribution Channel: Online Retail, Medical Equipment Suppliers, Direct Sales, Distributors |
| Companies Covered | HD Medical, Inc., American Diagnostic Corporation, Eko Health, Inc., AMD Global Telemedicine, Contec Medical Systems, Solventum, 3M, eKuore Medical, Thinklabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumology Digital Stethoscope Market Evolving Landscape
Three active transformations are reshaping competitive positioning in pneumology digital stethoscopes: hardware architecture is fragmenting into modular subsystems, regulatory frameworks are hardening around software validation, and procurement authority is migrating from clinical departments to centralized digital health committees.
Digital stethoscope hardware is modularizing around swappable sensor heads and detachable wireless transmission modules. Pulmonology departments in academic medical centers are piloting component-upgrade programs rather than full-device replacement cycles. This architecture is modularizing supply chains, enabling third-party sensor manufacturers to bypass integrated device vendors and sell directly to hospital biomedical engineering teams.
The EU MDR clinical evidence requirements for smartphone-connected stethoscopes are tightening post-market surveillance obligations. Manufacturers must now generate real-world performance data for CE-marked devices sold in European markets. Class IIa diagnostic software modules face expanded notified body scrutiny, compressing development timelines for AI-enhanced products targeting EU hospital systems.
Hospital value analysis committees are consolidating purchasing authority over digital auscultation devices previously bought at department discretion. Pulmonology, cardiology, and primary care divisions must now coordinate procurement through centralized digital health governance structures in United States health systems. This behavioral shift is visible most acutely in integrated delivery networks with standardized telehealth platform mandates across multiple states.
Pneumology Digital Stethoscope Market Segmentation
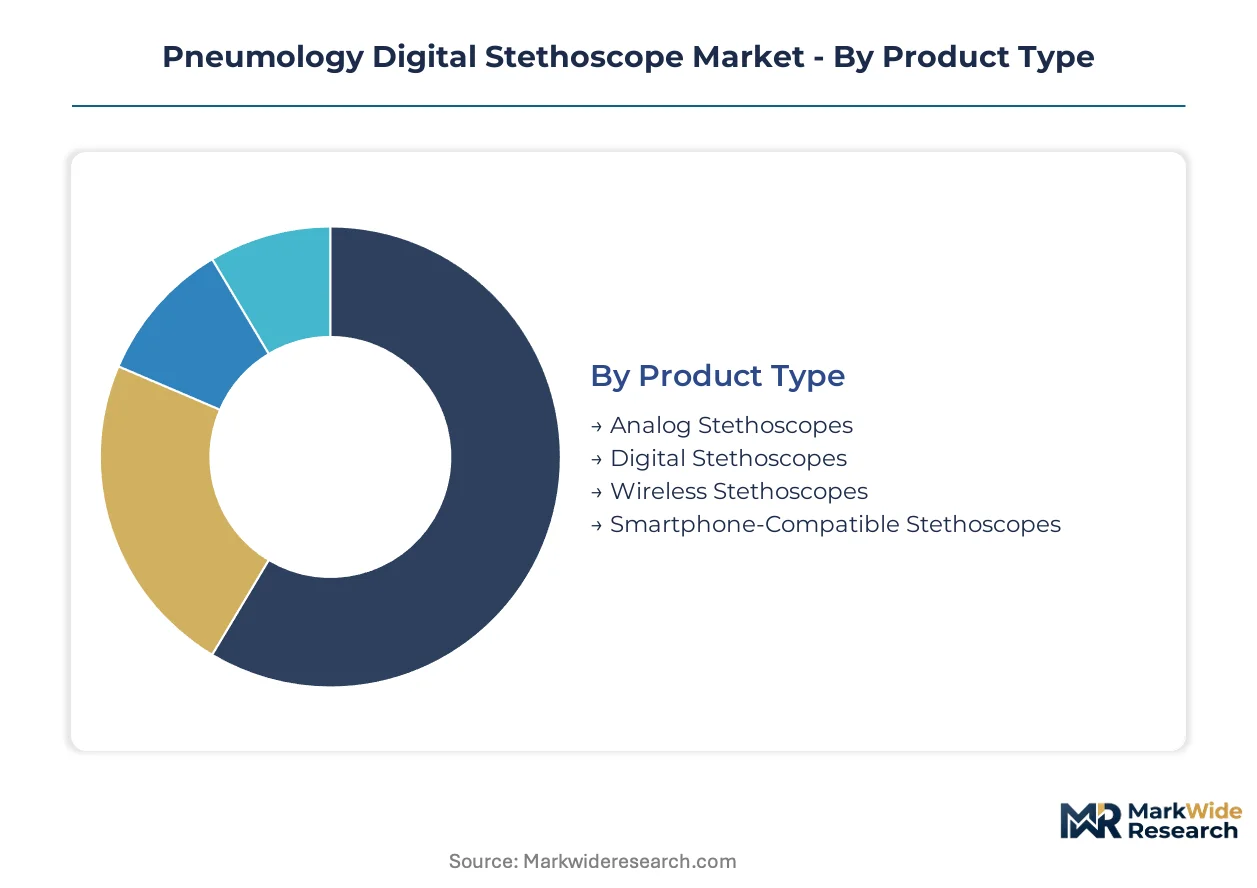
Pneumology digital stethoscope segmentation reveals divergent capital requirements across hardware architectures and customer workflows. Procurement committees evaluate segments based on integration complexity, regulatory pathway costs, and reimbursement eligibility rather than acoustic performance alone.
Product Type:
Wireless stethoscopes demand the heaviest upfront engineering investment due to RF certification, battery subsystem development, and HIPAA-compliant encryption modules. Smartphone-compatible variants require lower hardware capex but incur substantial software validation costs for FDA 510(k) clearance.
- Wireless Stethoscopes:Untethered examination architectures incorporate Bluetooth Low Energy chipsets, rechargeable lithium-polymer cells, and noise-canceling MEMS microphone arrays. Hospital systems in the United States prioritize these units for isolation ward protocols and telehealth cart deployments where cable contamination risks dominate procurement criteria.
- Smartphone-Compatible Stethoscopes:These devices offload signal processing to iOS or Android host applications, reducing onboard computational requirements. Direct-to-consumer telehealth platforms bundle these with subscription-based pulmonology consultations, compressing customer acquisition costs.
- Digital Stethoscopes:Integrated electronic units with onboard amplification and local storage serve academic medical centers conducting longitudinal respiratory sound research.
- Analog Stethoscopes:Conventional mechanical designs persist in resource-constrained clinical settings where procurement committees prioritize unit cost over connectivity features.
Wireless stethoscopes absorb the bulk of installed capacity; smartphone-compatible variants are expanding most quickly.
End User:
Customer-type segmentation tracks reimbursement infrastructure maturity and purchasing authority concentration across care delivery settings.
- Hospitals:Integrated delivery networks command centralized procurement authority over pulmonology, cardiology, and emergency departments. Value analysis committees in United States health systems mandate interoperability with Epic or Cerner EHR architectures as a threshold qualification.
- Telehealth Providers:Virtual-first pulmonology platforms purchase devices in bulk for patient home-deployment models. These customers prioritize plug-and-play onboarding workflows over acoustic fidelity specifications.
- Private Clinics:Independent pulmonology practices select mid-tier digital units with basic cloud connectivity to avoid IT support overhead.
- Home Healthcare:Prescription-grade monitoring for COPD patients in Germany and Japan drives demand for FDA-cleared or CE-marked devices with simplified patient interfaces.
Hospitals dominate current procurement volume; telehealth providers are climbing the fastest.
Technology:
Technology segments stratify by regulatory pathway complexity and algorithmic development intensity.
- AI Integration:Machine learning modules for adventitious lung sound classification require substantial training data acquisition and FDA software-as-medical-device validation. Eko Health, Inc. anchors this segment with FDA-cleared algorithms for cardiopulmonary analysis deployed across United States hospital systems.
- Bluetooth Connectivity:Wireless transmission protocols enable real-time audio streaming to remote clinicians. HIPAA-mandated end-to-end encryption imposes computational overhead on device architectures, extending engineering timelines.
- Digital Signal Processing:Onboard spectral analysis and noise reduction algorithms differentiate mid-tier products from basic electronic amplification units.
- Acoustic Transmission:Conventional electronic stethoscopes without wireless capabilities occupy the largest installed base due to lower unit costs and simpler regulatory pathways.
Acoustic transmission platforms retain the largest installed base; AI integration is gaining share fastest.
Distribution Channel:
Channel segmentation reflects customer purchasing authority migration and digital procurement platform penetration.
- Medical Equipment Suppliers:Specialized distributors with biomedical engineering support staff dominate hospital procurement in the United States. These intermediaries manage FDA compliance documentation and warranty servicing for capital equipment committees.
- Direct Sales:Manufacturers bypass intermediaries for large integrated delivery network contracts, capturing margin and controlling implementation timelines.
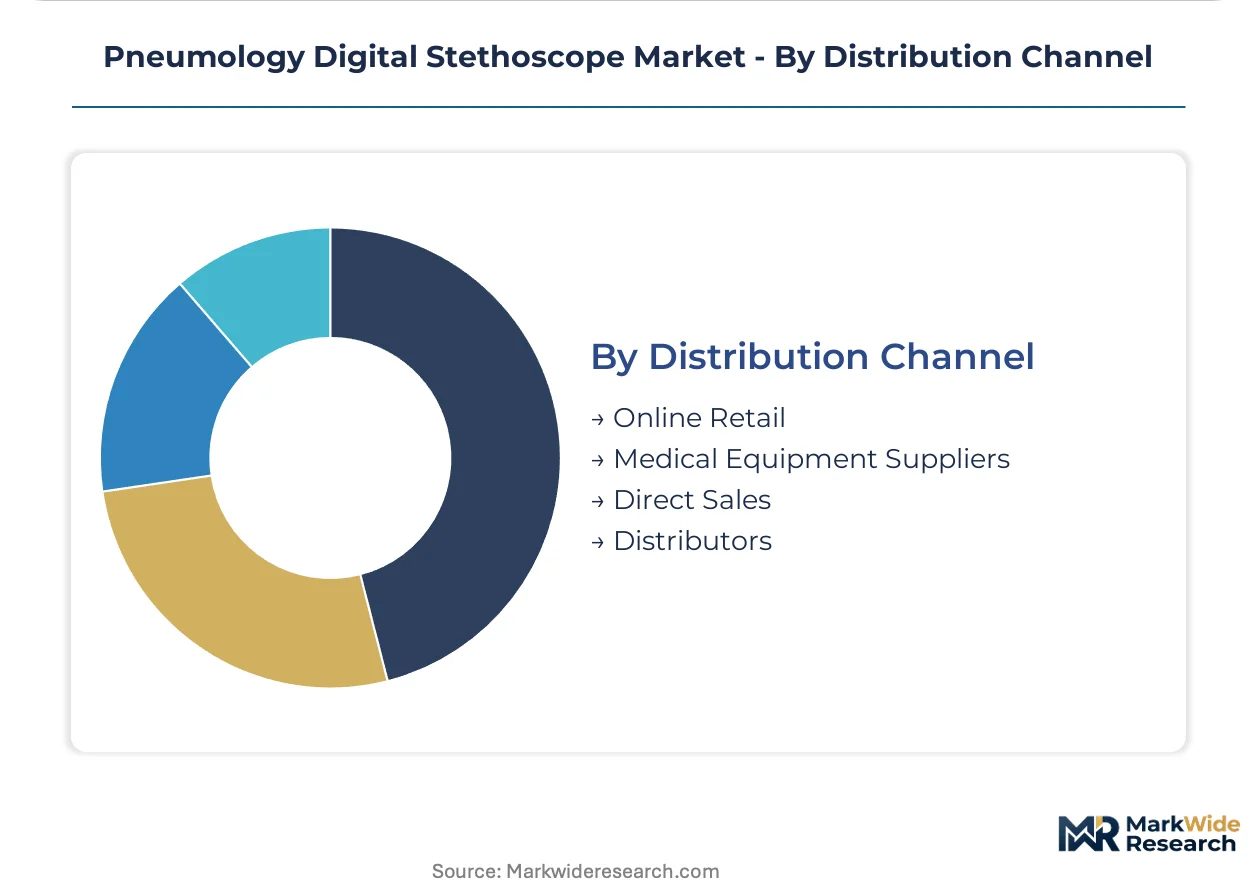
- Online Retail:Amazon Business and medical supply marketplaces serve private clinics and telehealth startups with standardized SKUs and rapid fulfillment.
- Distributors:Regional medical device wholesalers stock inventory for same-day replacement scenarios in acute care settings.
Medical equipment suppliers handle the bulk of hospital procurement; direct sales channels are expanding most quickly among integrated delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric ceramic feedstock from East Asian specialty manufacturers anchors the pneumology digital stethoscope supply base. Finished device assembly clusters in the United States, Germany, and Japan where hospital procurement budgets concentrate. Regulatory clearance pathways in these markets determine commercialization sequencing for new entrants.
United States
Medicare reimbursement expansion for remote physiological monitoring pulls digital stethoscope procurement into hospital capital budgets. FDA 510(k) predicate pathways for digital auscultation devices compress premarket notification timelines through substantial equivalence claims. Boston and Minneapolis medical device clusters host engineering operations for connected diagnostic platforms targeting integrated delivery networks.
Germany
Reimbursement frameworks for home respiratory monitoring crystallize demand for prescription-grade digital stethoscopes among COPD patient populations. EU MDR clinical evidence requirements tighten post-market surveillance obligations for smartphone-connected stethoscopes. Baden-Württemberg precision engineering clusters supply MEMS sensor components to device manufacturers.
Japan
PMDA consultation pathways for AI-enabled diagnostic software accelerate regulatory submissions from domestic and foreign manufacturers. METI funding for digital health infrastructure supports telehealth platform deployment in rural prefectures. Tokyo and Osaka metropolitan areas concentrate pulmonology department procurement authority within academic medical centers.
China
NMPA medical device registration requirements for electronic stethoscopes mandate domestic clinical trials for market authorization. Provincial hospital procurement reforms consolidate purchasing authority under centralized health commissions. Shenzhen and Shanghai hardware engineering clusters manufacture Bluetooth transmission modules for export-oriented device vendors.
United Kingdom
NHS England digital transformation budgets allocate capital for connected auscultation devices in respiratory specialty services. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines for software-as-medical-device submissions. London and Cambridge health technology clusters pilot AI-enhanced diagnostic tools within integrated care systems.
Pneumology Digital Stethoscope Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities and hospital procurement relationships. The vendor base stratifies into three tiers: diversified conglomerates with medical device divisions, digital health specialists with FDA-cleared AI platforms, and component-focused engineering houses. Consolidation pressure intensifies as value analysis committees centralize purchasing authority. Dominant competitive moves include strategic partnerships with telehealth platforms and technology licensing for MEMS sensor integration.
Within the AI-enabled diagnostic tier, Eko Health, Inc. and Thinklabs exemplify contrasting strategic positions. Eko Health, Inc. anchors the algorithm-validation segment through FDA-cleared cardiopulmonary analysis software deployed across United States hospital systems. Thinklabs occupies a specialist position in high-fidelity electronic stethoscope engineering for research-intensive medical centers. 3M represents the diversified conglomerate archetype, sustaining manufacturing scale across its Littmann digital portfolio through established distribution relationships with medical equipment suppliers.
| Leading Market Players |
|---|
| HD Medical, Inc. |
| American Diagnostic Corporation |
| Eko Health, Inc. |
| AMD Global Telemedicine |
| Contec Medical Systems |
| Solventum |
| 3M |
| eKuore Medical |
| Thinklabs |
| Others |
Value Network & Pricing Analysis
MEMS sensor engineering talent concentration in Baden-Württemberg and Boston anchors labor-cost differentials that widen pricing-tier spreads between research-grade and clinical-standard digital stethoscopes. Procurement committees exploit these geographic skill premiums to negotiate volume discounts against warranty-bundled service contracts.
Pricing Analysis
Warranty and calibration service bundling separates premium AI-enabled units from unbundled economy-tier acoustic transmission devices. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status and Bluetooth encryption certification tiers. Cost compression in the smartphone-compatible segment intensifies as Asian foundry output scales MEMS microphone arrays. Telehealth providers exhibit the highest price sensitivity due to thin hardware margins on patient-deployment models, while academic medical centers prioritize acoustic fidelity over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for piezoelectric ceramics now govern procurement contracts with East Asian specialty manufacturers. Component supply draws from China, Japan, and South Korea for MEMS sensors, lithium-polymer cells, and Bluetooth chipsets. Single-source vulnerability concentrates in medical-grade piezoelectric formulations where specialty ceramics production rests on concentrated East Asian capacity. Distribution runs through medical equipment suppliers with biomedical engineering support staff for hospital capital equipment committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumology digital stethoscope market sits in a technology-transition phase where AI-enhanced spectral analysis displaces conventional acoustic transmission platforms in reimbursed care settings.
For Market Incumbents: Deploy algorithm-validation investments to anchor premium positioning against software-as-medical-device entrants. Consolidate hospital system relationships through Epic and Cerner EHR integration certification. MEMS sensor cost curves threaten acoustic transmission margins; backward integration into sensor procurement secures supply continuity. For New Entrants and Emerging Players: Enter via direct-to-consumer telehealth channels bundling smartphone-compatible hardware with subscription clinician access. Home-based COPD monitoring in Germany and Japan offers the most penetrable white space given crystallizing reimbursement frameworks. Target GPO contracts with simplified onboarding workflows over acoustic performance specifications. For Investors and Strategic Acquirers: Re-rating potential sits with FDA-cleared AI algorithm developers given Medicare reimbursement acceleration for remote physiological monitoring. Long-term viability favors platforms with installed base density in integrated delivery networks. Watch FDA guidance evolution on AI-enabled diagnostic software as the inflection signal for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Substantial equivalence claims compress premarket timelines for digital auscultation predicates. |
| Hospital System Partnership | Epic and Cerner EHR integration mandates anchor procurement qualification thresholds. |
| Software Companion Development | AI-enhanced spectral analysis modules differentiate premium tiers from basic amplification. |
| CE Marking Pathway | EU MDR clinical evidence requirements tighten post-market surveillance for smartphone-connected devices. |
| Reimbursement Strategy | Medicare remote physiological monitoring coverage pulls device procurement into capital budgets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pulmonology department heads, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with FDA 510(k) databases, EU MDR notified body submissions, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling and top-down healthcare IT spending analysis triangulated market sizing across the projection horizon.
Granularity-level modeling tracked wireless, smartphone-compatible, digital, and analog product types against hospital, telehealth, clinic, and home healthcare end users. Technology segments including AI integration, Bluetooth connectivity, digital signal processing, and acoustic transmission were projected across the analysis window with CAGRs derived from reimbursement elasticity and regulatory pathway velocity. MEMS sensor cost curves and FDA predicate accumulation rates fed industry-specific forecast inputs.
Revisions become necessary when FDA software-as-medical-device guidance shifts, EU MDR notified body capacity constraints intensify, or Medicare reimbursement codes for remote physiological monitoring contract. Deviation in HIPAA encryption standards or Bluetooth protocol certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Surgical Mesh Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Self-Injections Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Spherical IOL Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market