
 Asia-Pacific Autoimmune Disease Diagnostics Market | 2026-2036
Asia-Pacific Autoimmune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Autoimmune Disease Diagnostics Market Outlook
Hospital-based rheumatology departments is realigning procurement priorities toward multiplex immunoassay platforms. Abbott Laboratories leverages its installed base of automated analyzers across Southeast Asian reference labs. Siemens Healthineers anchors its position through integrated workflow solutions spanning pre-analytical to result reporting. Thermo Fisher Scientific competes on specialty reagent breadth for lupus and multiple sclerosis panels.
Autoimmune disease diagnostics comprise laboratory and point-of-care testing systems that detect autoantibodies, immune complexes, and inflammatory markers through fluorescence-based, enzymatic, or molecular amplification methods, typically requiring sensitivity thresholds below nanograms per milliliter for clinical relevance. These systems serve to stratify patients for biologic therapy selection and monitor disease progression in chronic conditions. Immunoassay technology dominates current throughput requirements in high-volume hospital labs, while mass spectrometry segments are gaining traction for novel biomarker discovery in research institutions. ELISA kits retain cost advantages in clinical laboratories with moderate test volumes, whereas lateral flow tests address decentralization pressures at diagnostic centers in rural catchments.
Japan's PMDA maintains stringent analytical validation standards for autoimmune IVDs, elevating barriers for non-domestic manufacturers. Australia's TGA aligns with EU MDR transition timelines, creating parallel compliance obligations for Asia-Pacific suppliers. China's NMPA accelerates innovative device pathways for companion diagnostics linked to biologic therapies. Stakeholders must calibrate regulatory submission sequencing across these three frameworks to avoid portfolio launch delays.
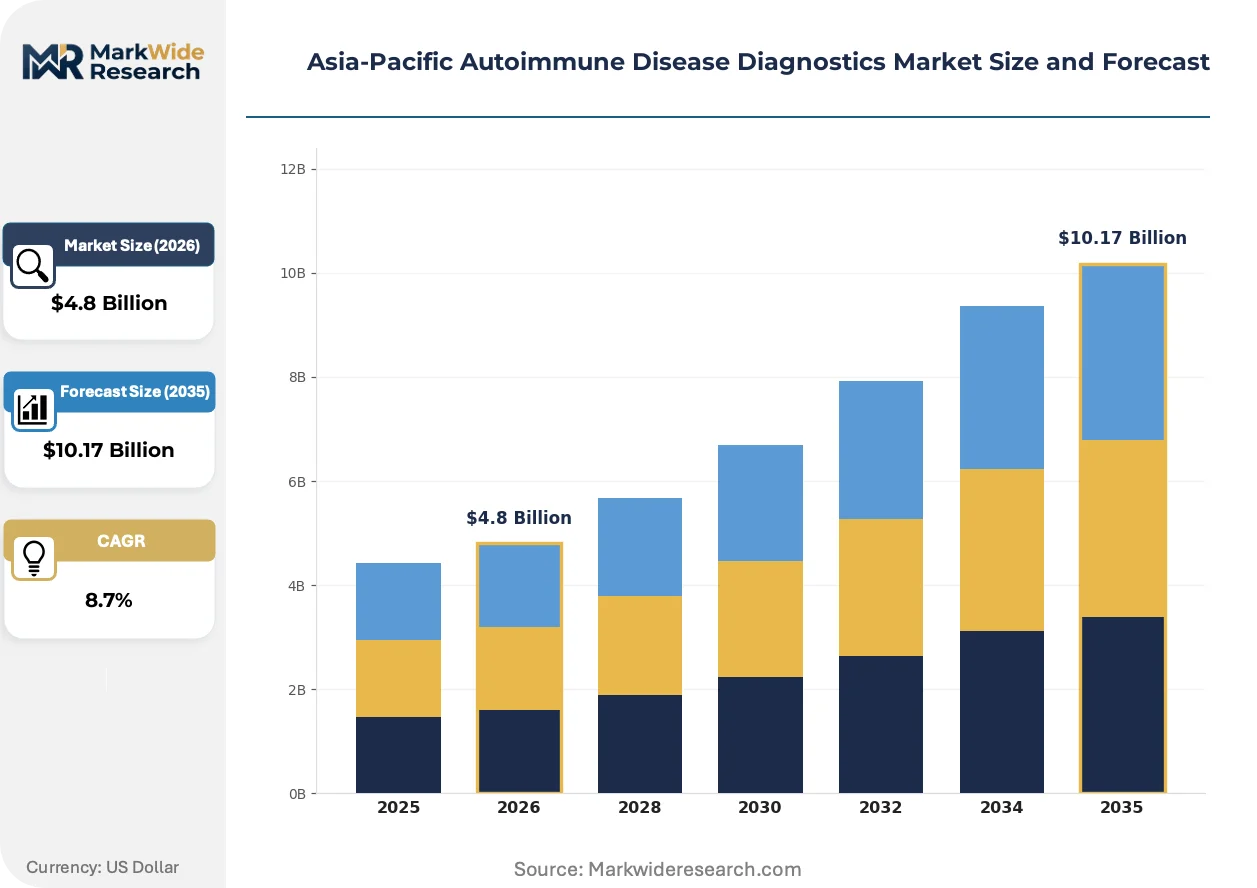
Market Dynamics
Centralized hospital laboratory networks across China's tier-one cities are consolidating procurement authority, compressing vendor negotiation cycles and favoring integrated platform suppliers over standalone reagent manufacturers.
Growth Catalysts
- CDSCO pathway acceleration:India's tightened IVD registration timelines compress product entry cycles from 18 to 12 months, enabling faster commercialization for multinational diagnostic manufacturers.
- Biologic therapy expansion:Rheumatology departments require companion diagnostic panels to stratify patients for TNF-alpha inhibitor and IL-6 blocker selection, expanding test menu demand.
- Multiplex immunoassay platforms:Automated analyzers processing 100-plus autoantibody profiles per run displace manual ELISA workflows in high-volume reference laboratories.
Market Restraints
- Reagent import dependency:Specialty antibodies and fluorophores concentrate in US and European suppliers, exposing Asia-Pacific manufacturers to currency volatility and shipping disruptions.
- PMDA validation burden:Japan's requirement for analytical sensitivity documentation below nanograms per milliliter demands 18-month local clinical studies for non-domestic IVD submissions.
- Fluorescence microscopy saturation:Indirect immunofluorescence remains the gold standard for ANA screening despite labor intensity, slowing chemiluminescence displacement.
Strategic Opportunities
- Rural diagnostic center networks:India's tier-three cities and district hospitals lack autoimmune testing access, creating white space for lateral flow and cartridge-based platforms.
- NMPA innovative device pathway:China's accelerated review for companion diagnostics linked to biologic therapies reduces regulatory timelines for novel biomarker panels.
- Mass spectrometry convergence:LC-MS/MS platforms combining proteomic depth with clinical throughput enable novel autoantigen discovery in research-to-clinic translation.
Industry Challenges
- Clinical immunologist scarcity:Interpretation of complex autoantibody patterns requires specialized training that outpaces workforce expansion in Southeast Asian markets.
- Legacy analyzer integration:Hospital IT systems require middleware customization to connect new multiplex platforms with existing LIS infrastructure, extending deployment timelines.
- Harmonization delays:Lack of standardized international reference materials for lupus and vasculitis panels produces inter-laboratory variability that complicates multi-site clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Autoimmune Disease Diagnostics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Immunoassays, Western Blot, Lateral Flow Tests Technology: Fluorescence Immunoassay, Enzyme-linked Immunosorbent Assay, PCR, Mass Spectrometry End User: Hospitals, Clinical Laboratories, Diagnostic Centers, Research Institutions Application: Rheumatoid Arthritis, Lupus, Multiple Sclerosis, Hashimoto's Thyroiditis |
| Companies Covered | Abbott Laboratories, bioMérieux, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Siemens Healthineers, PerkinElmer, Trinity Biotech, Beckman Coulter, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Autoimmune Disease Diagnostics Market Strategic Shifts
Automation architectures and regulatory convergence are compressing the gap between biomarker discovery and clinical deployment across Asia-Pacific diagnostic networks.
Point-of-care chemiluminescence analyzers are decentralizing autoimmune testing from centralized hospital labs to provincial diagnostic centers. China's county-level hospital networks adopt compact platforms processing 30-plus autoantibody profiles per hour. This capability migration is decentralizing patient access and reducing specialist referral bottlenecks in rural catchments.
TGA alignment with EU MDR transition timelines creates parallel compliance obligations for Australia-based suppliers. Manufacturers must maintain dual technical documentation systems to satisfy both frameworks simultaneously. Asia-Pacific IVD exporters with Australian subsidiaries face compressed certification cycles as they synchronize quality management system updates.
Hospital procurement committees now bundle reagent contracts with analyzer placement agreements, displacing standalone equipment purchases. Rheumatology departments in South Korea negotiate five-year total-cost-of-ownership contracts covering consumables, maintenance, and software updates. This purchasing pattern concentrates vendor relationships and raises switching costs for alternative platform suppliers.
Asia-Pacific Autoimmune Disease Diagnostics Market Segmentation
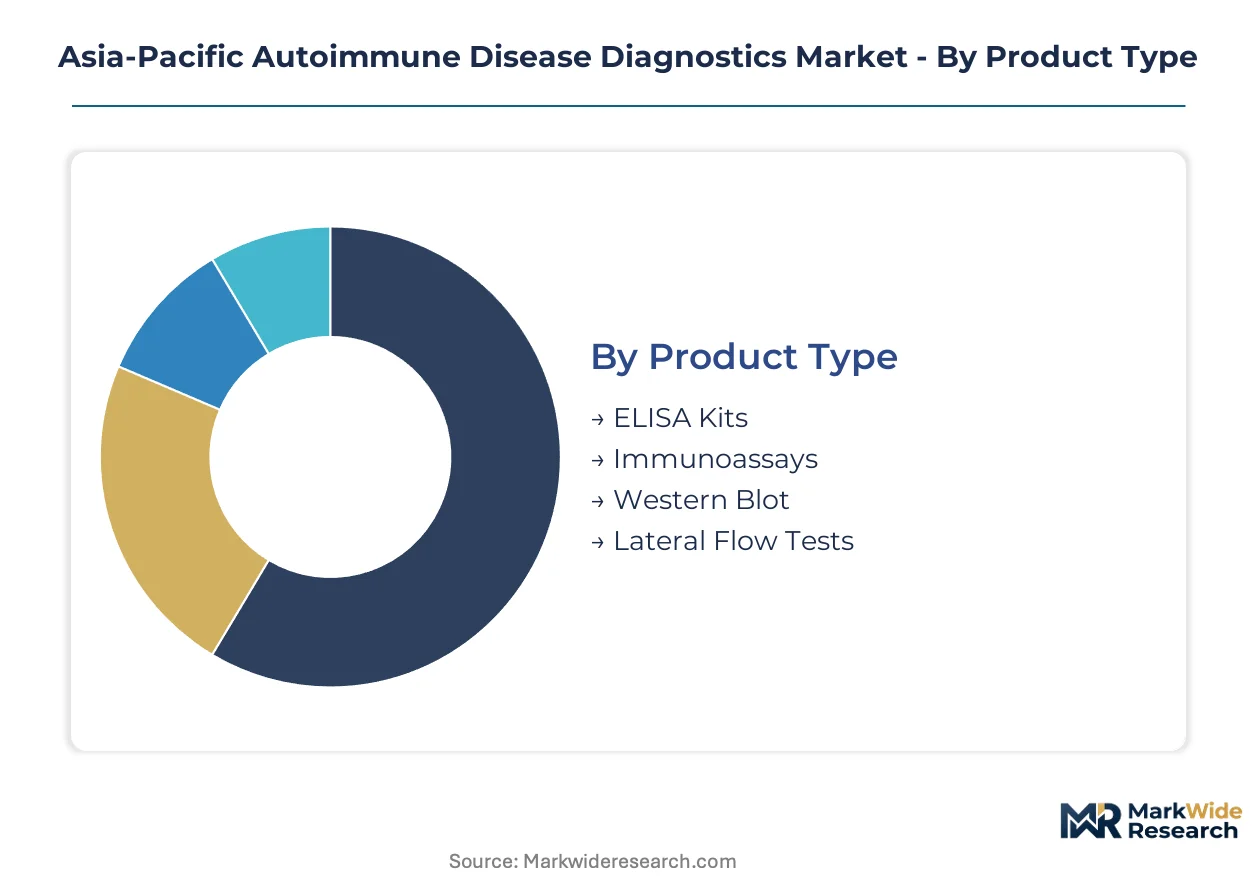
Autoimmune disease diagnostics fragment across multiple technical and commercial axes. Each segmentation layer reveals distinct procurement patterns, regulatory exposure, and margin structures that shape vendor positioning across Asia-Pacific healthcare networks.
Product Type:
Technology sophistication and throughput requirements define product category selection in hospital procurement cycles.
- Immunoassays:Automated analyzers processing multiplex autoantibody panels dominate high-volume reference laboratories. China's tier-one hospital networks prioritize these platforms for rheumatology department consolidation.
- ELISA Kits:Cost-efficient manual workflows retain share in clinical laboratories with moderate test volumes. India's district hospitals and tier-two cities favor these for budget-constrained autoimmune screening programs.
- Lateral Flow Tests:Point-of-care cartridges address decentralization pressures in rural diagnostic centers.
- Western Blot:Confirmatory testing for antibody specificity follows positive screening results.
Immunoassays lead on scale; lateral flow tests lead on momentum.
Technology:
Detection methodology determines sensitivity thresholds, capital requirements, and regulatory validation burden.
- Fluorescence Immunoassay:Indirect immunofluorescence remains the gold standard for ANA screening despite labor intensity. Japanese clinical guidelines maintain this as the reference method, slowing chemiluminescence displacement in East Asian markets.
- Enzyme-linked Immunosorbent Assay:Colorimetric detection platforms balance analytical sensitivity with reagent stability. Southeast Asian reference laboratories standardize on ELISA for lupus and vasculitis panel harmonization.
- PCR:Molecular amplification targets specific autoimmune-associated genetic markers.
- Mass Spectrometry:LC-MS/MS platforms enable novel autoantigen discovery in research-to-clinic translation.
Fluorescence immunoassay anchors current volume; mass spectrometry is climbing the fastest.
End User:
Customer type shapes contract structure, service expectations, and platform integration complexity.
- Hospitals:Centralized laboratory networks across China's tier-one cities consolidate procurement authority. Rheumatology departments bundle reagent contracts with analyzer placement agreements, raising switching costs for alternative suppliers.
- Diagnostic Centers:India's tier-three cities and district hospitals lack autoimmune testing access. Lateral flow and cartridge-based platforms create white space for decentralized service expansion.
- Clinical Laboratories:Independent testing facilities process outsourced hospital referrals.
- Research Institutions:Academic medical centers drive novel biomarker discovery and companion diagnostic development.
Hospitals capture the largest contract value; diagnostic centers offer the steepest expansion trajectory.
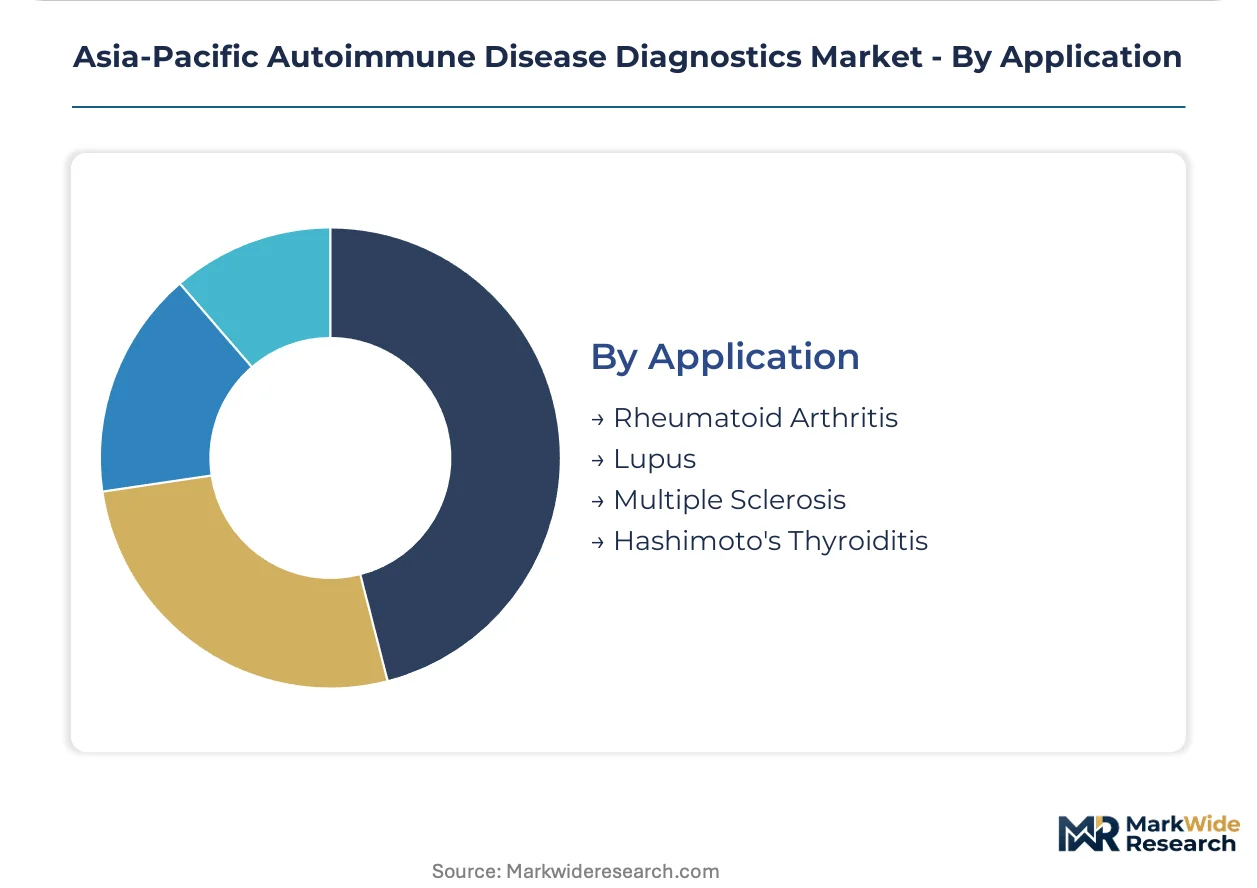
Application:
Disease-specific test menus align with biologic therapy availability and specialist physician density.
- Rheumatoid Arthritis:Anti-CCP and rheumatoid factor panels stratify patients for TNF-alpha inhibitor selection. South Korean rheumatology departments negotiate five-year total-cost-of-ownership contracts covering these assays.
- Lupus:Multi-parameter ANA and anti-dsDNA testing monitors disease activity and organ involvement. Australia's TGA alignment with EU MDR creates parallel compliance obligations for lupus panel suppliers.
- Multiple Sclerosis:Cerebrospinal fluid oligoclonal banding and neuromyelitis optica antibody testing supports neuroimmunology subspecialization.
- Hashimoto's Thyroiditis:Anti-TPO and anti-thyroglobulin antibodies screen for autoimmune thyroid dysfunction in endocrinology clinics.
Rheumatoid arthritis leads on test volume; lupus is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one hospital networks concentrate the region's diagnostic infrastructure investment, with centralized laboratory automation driving procurement consolidation across Beijing, Shanghai, and Guangzhou metropolitan clusters.
China
NMPA's innovative device pathway accelerates companion diagnostic approvals for biologic therapy stratification. County-level hospital networks in Sichuan-Chongqing and Shandong Peninsula deploy compact chemiluminescence platforms processing 30-plus autoantibody profiles hourly. Yangtze River Delta reference laboratories bundle five-year reagent contracts with analyzer placements.
Japan
PMDA mandates 18-month local clinical studies for analytical sensitivity documentation below nanograms per milliliter. Kanto region rheumatology departments maintain indirect immunofluorescence as the gold standard ANA screening method. Tokyo academic medical centers drive novel biomarker discovery through LC-MS/MS research platforms.
India
CDSCO compressed IVD registration timelines from 18 to 12 months, enabling faster multinational product entry. Maharashtra and Gujarat diagnostic centers expand test menus to capture rheumatology referrals from tier-three cities. District hospitals in Karnataka and Tamil Nadu lack autoimmune testing access, creating lateral flow platform opportunities.
South Korea
MFDS aligns with international harmonization standards for lupus and vasculitis panel validation. Seoul Capital Area rheumatology departments negotiate total-cost-of-ownership contracts covering TNF-alpha inhibitor companion diagnostics. Busan-Ulsan reference laboratories standardize on multiplex immunoassay automation for high-volume screening.
Australia
TGA alignment with EU MDR transition timelines creates parallel compliance obligations for domestic suppliers. New South Wales and Victoria hospital networks consolidate procurement authority toward integrated platform vendors. Sydney and Melbourne research institutions pioneer mass spectrometry convergence for proteomic autoantigen discovery.
Asia-Pacific Autoimmune Disease Diagnostics Market Competitive Environment
Platform bundling dominates the current landscape, with procurement committees favoring total-cost-of-ownership contracts over standalone equipment purchases. The vendor base stratifies across three tiers: multinational conglomerates with installed analyzer bases, mid-scale specialty reagent suppliers, and emerging point-of-care platform developers. Strategic archetypes include integrated workflow solution providers, multiplex immunoassay specialists, and decentralized testing innovators. M&A activity and reagent contract lock-ins represent the dominant competitive moves compressing vendor switching opportunities.
Within the multinational tier, Abbott Laboratories, Siemens Healthineers, and Thermo Fisher Scientific occupy positions anchored by automated analyzer installed bases across Southeast Asian reference laboratories. Abbott exemplifies the integrated platform archetype leveraging existing infrastructure. Siemens represents workflow solution providers spanning pre-analytical through result reporting. Thermo Fisher sits within the specialty reagent breadth category for disease-specific panel development. These three entities collectively illustrate how procurement consolidation favors vendors with existing automation footprints and companion diagnostic portfolios.
| Leading Market Players |
|---|
| Abbott Laboratories |
| bioMérieux |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| PerkinElmer |
| Trinity Biotech |
| Beckman Coulter |
| Others |
Value Chain & Pricing Dynamics
Multinational conglomerates with installed analyzer bases across Southeast Asian reference laboratories anchor pricing discipline through bundled reagent contracts, compressing margin flexibility for standalone manufacturers while consolidating procurement leverage in tier-one hospital networks.
Pricing Analysis
Distributor margins on specialty antibodies and fluorophores concentrate pricing power among US and European suppliers, exposing Asia-Pacific manufacturers to currency volatility. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-approved companion diagnostics from CE-marked panels and unregistered research-use-only reagents. Cost compression in economy-tier lateral flow tests intensifies because CDSCO pathway acceleration draws low-cost Indian manufacturers into district hospital procurement. Diagnostic centers in India's tier-three cities exhibit highest price sensitivity; China's Yangtze River Delta reference laboratories show least sensitivity due to total-cost-of-ownership contract lock-ins.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong feed hub-and-spoke patterns across Southeast Asian diagnostic networks. Specialty antibodies and fluorophores draw from US, Germany, and Japan; chemiluminescence substrates and cartridge plastics source from China and South Korea. Single-source vulnerability concentrates in European fluorophore suppliers, exposing reagent manufacturers to shipping disruptions. Distribution runs through hospital procurement committees bundling analyzer placements with five-year consumable commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive moats, with NMPA's innovative device pathway for companion diagnostics accelerating approval timelines and compressing commercialization windows for biologic-linked panels.
For Market Incumbents: Extend reagent contract durations to five-year total-cost-of-ownership agreements, locking out multiplex immunoassay challengers in China's tier-one hospital networks. Deepen backward integration into chemiluminescence substrate production to offset European fluorophore supply vulnerability. Prioritize PMDA pre-submission meetings to front-load analytical validation documentation for Japan's 18-month clinical study requirement.
For New Entrants and Emerging Players: Diagnostic center procurement managers in India's tier-three cities present the most penetrable channel partner type for lateral flow platform introduction. Target Karnataka and Tamil Nadu district hospitals lacking autoimmune testing access. Pursue white-label manufacturing partnerships with established CDSCO-registered distributors to bypass compressed 12-month registration timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among point-of-care platform developers with NMPA innovative pathway submissions pending but no installed analyzer base. Long-term viability across the analysis window hinges on successful research-to-clinic translation of mass spectrometry biomarker discovery. Watch MFDS harmonization alignment with international lupus panel standards as the inflection signal for South Korean rheumatology contract consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovative Device Pathway Submission | Accelerates companion diagnostic approval for biologic therapy stratification in China. |
| CDSCO Registration Acceleration | Compresses product entry cycles from 18 to 12 months for Indian market access. |
| Multiplex Immunoassay Platform Launch | Displaces manual ELISA workflows in high-volume reference laboratories. |
| Point-of-Care Chemiluminescence Deployment | Decentralizes testing to county-level hospital networks in Sichuan-Chongqing clusters. |
| Mass Spectrometry Biomarker Discovery | Enables novel autoantigen translation from Tokyo academic medical centers to clinical panels. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rheumatology department heads, hospital procurement committee members, CDSCO regulatory consultants, and IVD distribution channel managers with secondary validation against NMPA approval databases, PMDA submission records, CDSCO registration filings, and Asia-Pacific hospital procurement contract registries. Bottom-up test volume modeling triangulated against top-down market sizing across immunoassay, ELISA, and lateral flow product categories.
Segment-weighting applied technology type, end-user facility tier, and disease application as primary dimensions across the projection horizon. CAGRs derived from installed base expansion rates, test menu adoption curves, and biologic therapy penetration in rheumatology departments. Forecast inputs incorporated CDSCO timeline compression effects, NMPA innovative pathway approval velocity, and PMDA clinical study duration requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization delays, clinical immunologist workforce expansion rates, and mass spectrometry platform cost reduction trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Antigen Kit Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
India in-Vitro Diagnostics Market