
 Wearable Blood Pressure Monitor Market | 2026-2036
Wearable Blood Pressure Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Blood Pressure Monitor Market Analytics
Chinese sensor module producers is realigning component supply chains toward medical-grade photoplethysmography chips. OMRON Healthcare anchors Japanese precision manufacturing traditions in oscillometric wrist devices. Samsung Electronics leverages semiconductor integration to embed blood pressure algorithms within Galaxy smartwatch ecosystems. Apple competes through regulatory-first strategies, pursuing FDA validation for its optical sensor arrays.
A wearable blood pressure monitor combines photoplethysmography or oscillometric sensors with microprocessor-controlled algorithms to estimate arterial pressure without traditional cuff inflation, typically achieving accuracy within ±5 mmHg under controlled conditions for ambulatory cardiovascular surveillance. Smartwatch form factors dominate consumer-facing revenue pools due to multipurpose utility, while arm cuff variants sustain clinical-grade margins through physician channel validation. Bluetooth-enabled devices lead connectivity adoption, though ECG-integrated models capture premium positioning among hypertensive patients requiring arrhythmia correlation.
FDA premarket clearance requirements constrain U.S. market entry for cuffless optical systems, compelling manufacturers to generate extensive validation datasets against sphygmomanometer references. The EU MDR and ISO 81060-2 standards shape European conformance pathways, with notified bodies demanding sustained accuracy across skin tone variations. Stakeholders must monitor regulatory divergence between prescriptive clinical thresholds and consumer wellness exemptions as reimbursement policies crystallize for remote monitoring programs.
Market Dynamics
FDA premarket clearance requirements for cuffless optical systems are compressing competitive entry timelines while Chinese sensor module producers accelerate medical-grade photoplethysmography chip output for aging population demand.
Growth Catalysts
- Remote Patient Monitoring Expansion:Medicare reimbursement policies for ambulatory cardiovascular surveillance are pulling hypertensive patients into connected care programs. Physician channel validation requirements sustain clinical-grade device margins.
- ISO 81060-2 Standard Harmonization:European notified bodies are streamlining conformance pathways for wrist-based oscillometric devices. Manufacturers achieve cross-border market access through unified accuracy validation protocols.
- Photoplethysmography Algorithm Maturation:Semiconductor integration advances enable blood pressure estimation within ±5 mmHg under controlled conditions. Smartwatch form factors capture multipurpose utility demand.
Market Restraints
- Medical-Grade Sensor Supply Concentration:Chinese photoplethysmography chip production dominates component supply. Geopolitical friction threatens module availability for non-domestic device assemblers.
- FDA Validation Dataset Burden:Cuffless optical systems require extensive sphygmomanometer reference studies. Premarket clearance timelines extend 18-36 months for algorithm-dependent submissions.
- Skin Tone Variation Accuracy Gaps:Optical sensor arrays demonstrate measurement drift across melanin concentration ranges. Device manufacturers face additional validation costs for inclusive performance claims.
Strategic Opportunities
- Arrhythmia Correlation Integration:ECG-embedded blood pressure monitors capture premium positioning among comorbid cardiac patients. Bluetooth-enabled synchronization with electronic health records enables longitudinal data monetization.
- Japan's Super-Aged Society Demand:METI incentives for preventive health technology adoption accelerate home-based monitoring penetration. Domestic precision manufacturing traditions support high-accuracy wrist device acceptance.
- EU MDR Remote Monitoring Reimbursement Crystallization:National health systems are defining coverage criteria for physician-validated wearable data. Early movers secure preferred supplier status in tender processes.
Industry Challenges
- Algorithm Validation Talent Scarcity:Biomedical signal processing expertise concentrates within semiconductor firms and academic medical centers. Device manufacturers compete for scarce regulatory-statistics professionals.
- Legacy Electronic Health Record Integration Friction:Hospital IT systems require custom API development for wearable data ingestion. Implementation timelines delay enterprise contract closures.
- Dual Certification Cost Compression:Simultaneous FDA and EU MDR pathway navigation strains mid-cap development budgets. Sequential market entry strategies sacrifice first-mover advantage in one geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Blood Pressure Monitor Market |
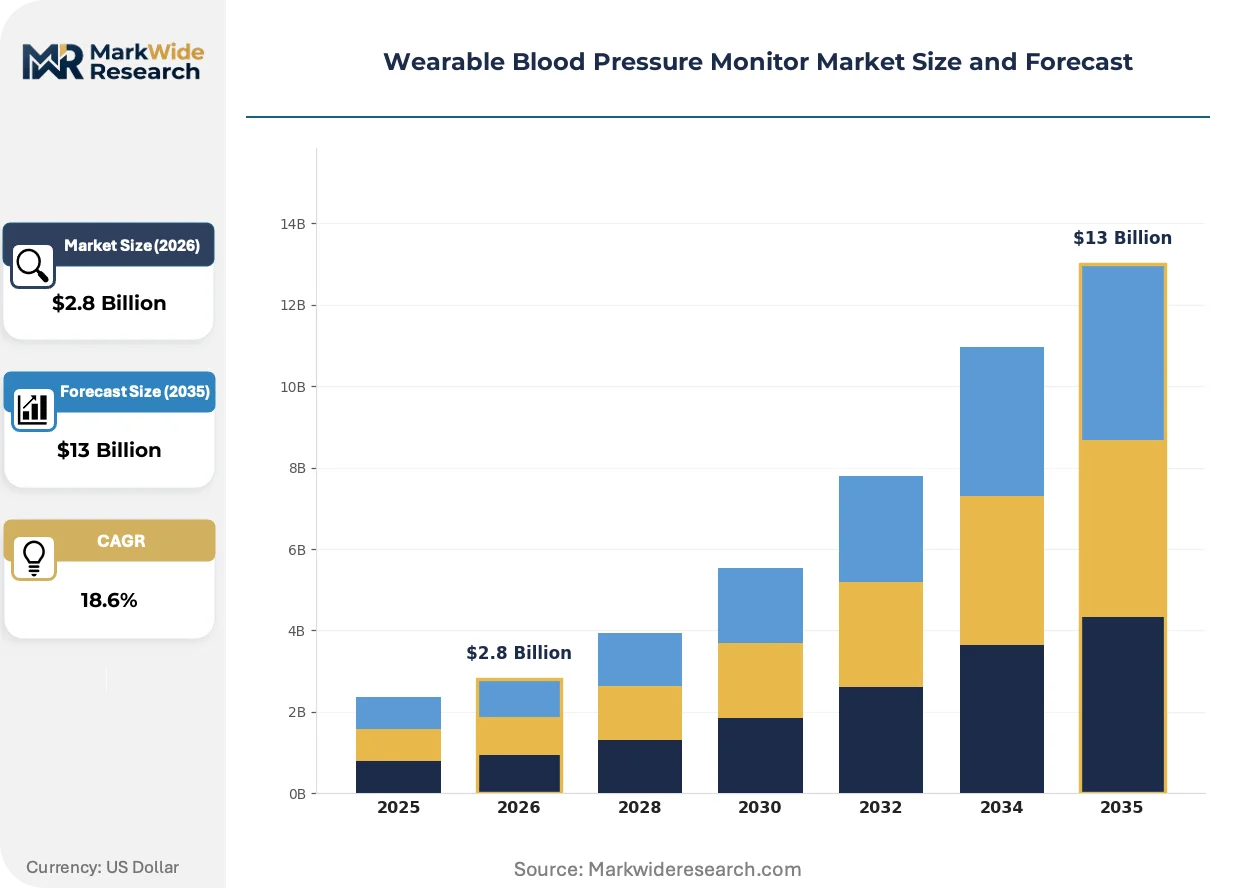
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatch, Fitness Tracker, Arm Cuff, Oximeter Technology: Bluetooth, Wi-Fi, Optical Sensors, ECG End User: Hypertensive Patients, Athletes, General Wellness Users, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Hospitals, Direct Sales |
| Companies Covered | OMRON Healthcare, Samsung Electronics, Fitbit (Google), Apple, Aktiia SA, Withings SA, Biobeat Technologies Ltd, Qardio Inc, iHealth Labs Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Blood Pressure Monitor Market Evolving Landscape
Algorithm-hardware co-design is collapsing the traditional separation between consumer wellness and clinical-grade measurement categories, forcing manufacturers to choose single positioning or dual-track development investments.
Photoplethysmography with multi-wavelength LED arrays is overtaking single-sensor oscillometric methods in wrist-based form factors. Hypertensive patients seeking arrhythmia correlation are adopting ECG-integrated models at triple the rate of standalone blood pressure devices. This convergence is compressing the premium tier definition and blurring physician channel boundaries.
EU MDR Article 117 requirements for clinical evidence are tightening notified body scrutiny of algorithm performance claims. Manufacturers must now submit sustained accuracy data across demographic subgroups including skin tone variations. Wrist-based optical devices face the steepest compliance cost increases as legacy predicate device pathways expire.
Hospital procurement departments are unbundling after-sales service from device acquisition contracts. Third-party calibration and algorithm update subscriptions are displacing manufacturer-captive service agreements in United States health system tenders. This shift is most visible in integrated delivery networks consolidating remote monitoring vendor lists.
Wearable Blood Pressure Monitor Market Segmentation
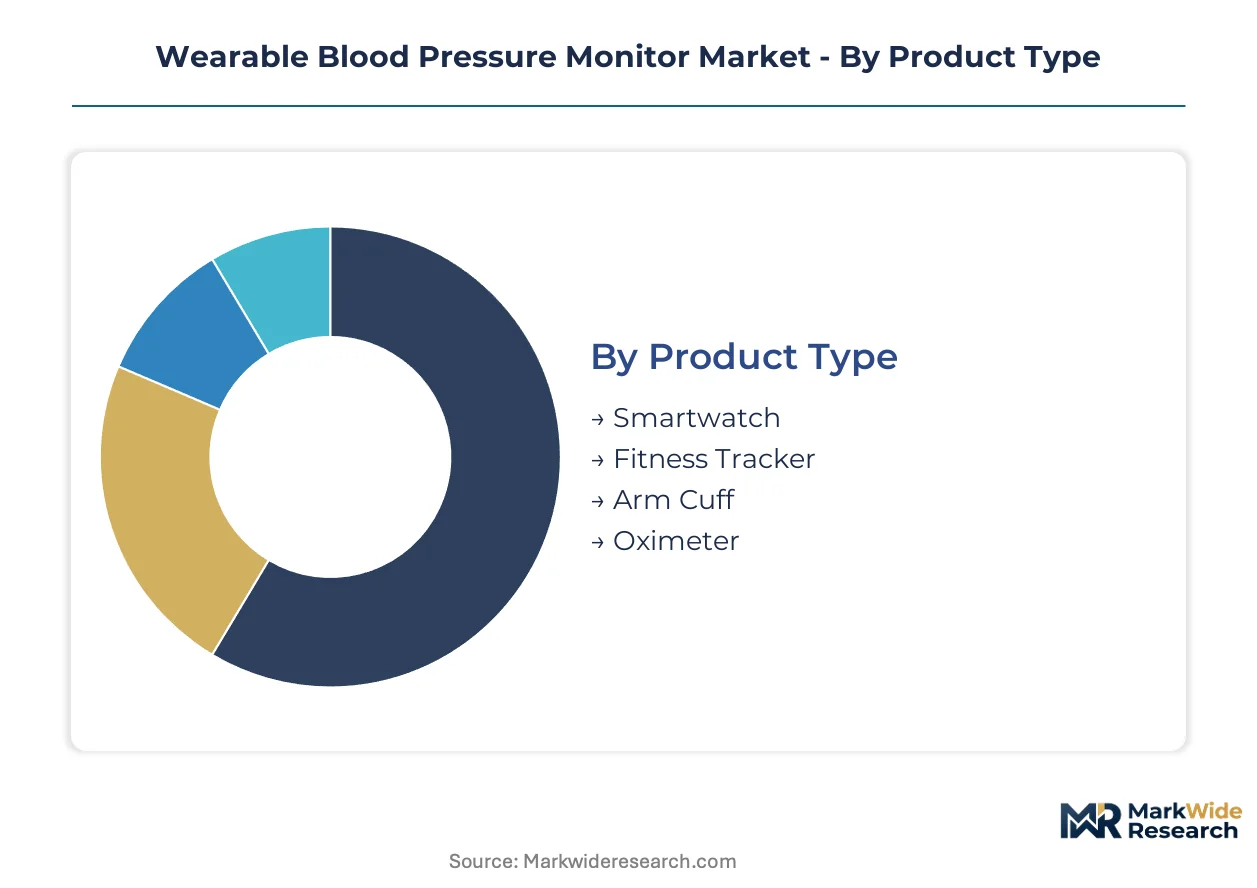
Segmentation in wearable blood pressure monitors reveals how technical specifications, connectivity protocols, and channel economics fragment addressable revenue pools across consumer wellness and clinical surveillance applications. Manufacturers must align sensor accuracy tiers with reimbursement eligibility and distribution margin structures.
Product Type:
Supply concentration in semiconductor-integrated form factors favors multipurpose devices with algorithm-hardware co-design capabilities, while discrete clinical instruments sustain premium positioning through physician channel validation.
- Smartwatch:Combines photoplethysmography arrays with microprocessor-controlled blood pressure estimation within ±5 mmHg under controlled conditions. Demand concentrates among hypertensive patients enrolled in remote monitoring programs seeking arrhythmia correlation alongside cardiovascular surveillance.
- Arm Cuff:Oscillometric wrist devices anchor Japanese precision manufacturing traditions with sustained accuracy across demographic subgroups. Physician channel requirements in Medicare reimbursement jurisdictions sustain clinical-grade margins through FDA-cleared predicate pathways.
- Fitness Tracker:Compact form factors prioritize step-counting utility with secondary blood pressure estimation for general wellness users.
- Oximeter:Single-purpose finger-worn devices target pulse oximetry with limited blood pressure functionality for home-based monitoring.
Today's leader: Smartwatch. Tomorrow's challenger: Arm Cuff.
Technology:
Connectivity and sensing architectures determine reimbursement eligibility and validation burden, with wireless protocols enabling longitudinal data monetization while integrated biometrics capture premium positioning.
- Optical Sensors:Multi-wavelength LED photoplethysmography arrays are overtaking single-sensor methods in wrist-based devices. Chinese sensor module producers dominate medical-grade chip supply for aging population demand in domestic and export markets.
- Bluetooth:Low-energy synchronization with electronic health records enables ambulatory data capture for remote patient monitoring programs. Hospital procurement departments favor Bluetooth-enabled devices for unbundled after-sales service contracts.
- ECG:Embedded electrical signal processing captures arrhythmia correlation for comorbid cardiac patients at triple the adoption rate of standalone blood pressure monitors.
- Wi-Fi:Direct cloud connectivity bypasses smartphone intermediaries for elderly users with limited digital literacy.
Optical Sensors command current volume. ECG integration climbs fastest toward premium tier definition.
End User:
Patient acuity levels stratify accuracy requirements and reimbursement pathways, with diagnosed hypertensive populations pulling clinical-grade specifications into consumer-facing price points.
- Hypertensive Patients:Diagnosed cardiovascular conditions demand sustained accuracy across skin tone variations for inclusive performance claims. Medicare reimbursement policies pull this segment into connected care programs with physician-validated device requirements.
- Healthcare Professionals:Enterprise procurement in integrated delivery networks consolidates vendor lists around devices with custom API development for legacy electronic health record integration.
- Athletes:Post-exercise recovery monitoring drives demand for rapid measurement cycles without cuff inflation.
- General Wellness Users:Preventive health awareness expands addressable market beyond diagnosed populations into consumer wellness exemptions.
Hypertensive Patients anchor revenue concentration. Healthcare Professionals represent the steepest expansion trajectory as remote monitoring reimbursement crystallizes.
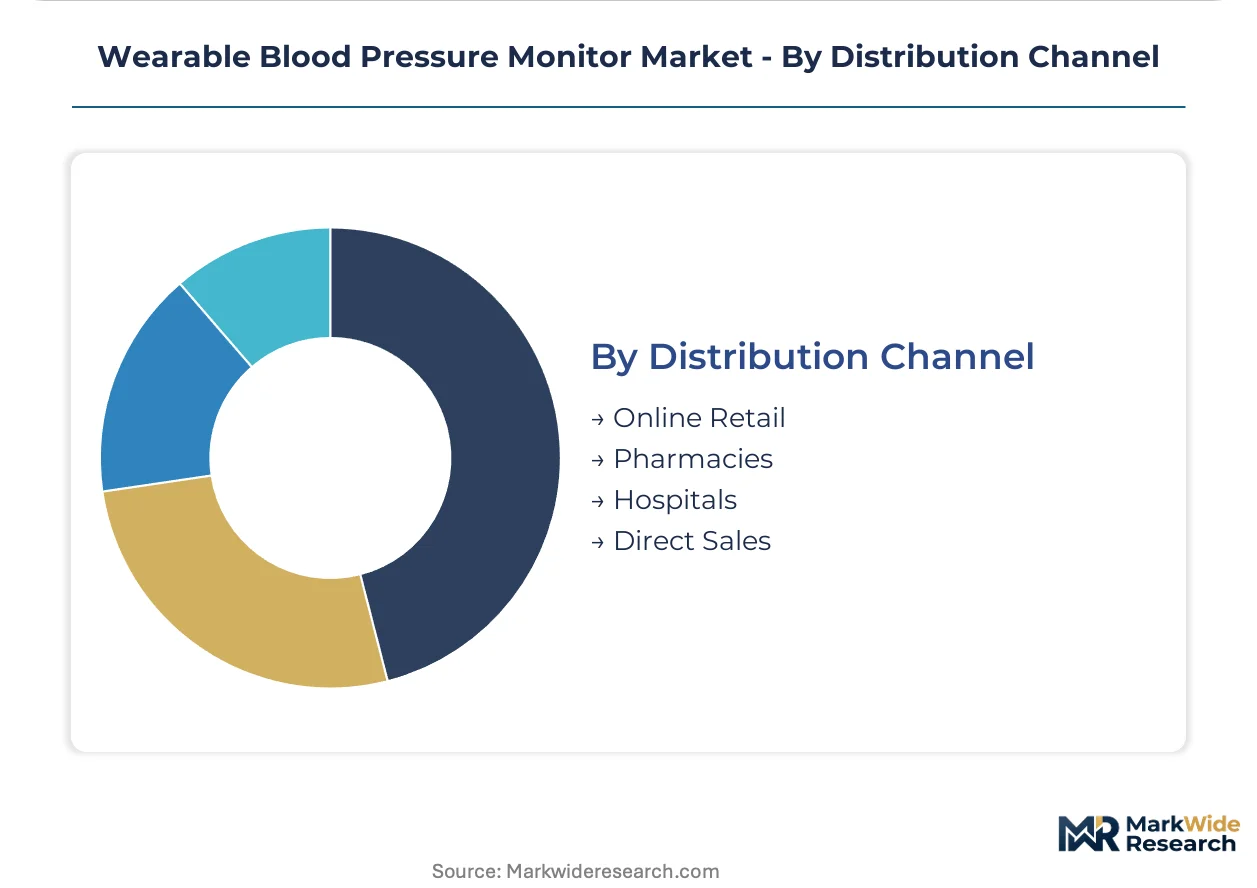
Distribution Channel:
Channel economics fragment between direct-to-consumer digital platforms with algorithm update subscriptions and institutional procurement with captive service agreements.
- Online Retail:E-commerce platforms enable direct algorithm-hardware bundling with third-party calibration subscriptions displacing manufacturer-captive agreements. Consumer-facing revenue pools concentrate here for smartwatch form factors.
- Hospitals:Health system tenders unbundle after-sales service from device acquisition, favoring vendors with sustained accuracy data across demographic subgroups for EU MDR Article 117 compliance.
- Pharmacies:Retail healthcare access points serve aging populations seeking home-based monitoring with pharmacist consultation support.
- Direct Sales:Manufacturer-controlled channels preserve margin for clinical-grade arm cuff variants with predicate device pathways.
Online Retail dominates consumer volume. Hospitals capture premium positioning through reimbursement-validated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as Chinese producers exploit faster domestic medical-device approvals while Western brands absorb extended FDA validation timelines for cuffless optical systems.
United States
Medicare reimbursement expansion for remote patient monitoring pulls hypertensive patients into connected care programs requiring physician-validated devices. FDA premarket clearance pathways for cuffless optical systems compress competitive entry timelines through extensive sphygmomanometer reference studies. Boston's medical technology corridor concentrates algorithm validation expertise alongside academic medical centers.
China
Aging population demand for affordable wrist-based monitors accelerates domestic production scaling by local manufacturers. NMPA regulatory pathways enable faster market entry for photoplethysmography chip-integrated devices compared to Western jurisdictions. Shenzhen's semiconductor ecosystem anchors sensor module supply chain realignment toward medical-grade component output.
Japan
METI incentives for preventive health technology adoption accelerate home-based monitoring penetration among super-aged society demographics. PMDA conformance requirements sustain precision manufacturing traditions for oscillometric wrist devices with cross-border accuracy validation. Tokyo-Osaka industrial corridor maintains high-accuracy device acceptance through domestic channel validation.
Germany
EU MDR Article 117 clinical evidence requirements tighten notified body scrutiny of algorithm performance claims across demographic subgroups. National health systems define coverage criteria for physician-validated wearable data in tender processes. Bavaria's medical device engineering clusters support sustained accuracy validation infrastructure for wrist-based optical systems.
South Korea
Semiconductor integration capabilities enable embedded blood pressure algorithms within smartwatch ecosystems for consumer-facing revenue capture. MFDS regulatory harmonization with international standards facilitates export market access for domestic device manufacturers. Seoul Capital Area's electronics manufacturing base concentrates algorithm-hardware co-design competencies.
Wearable Blood Pressure Monitor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cuffless optical validation and arrhythmia correlation integration. The vendor base stratifies across three tiers: precision manufacturers with predicate device pathways, semiconductor-integrated smartwatch platforms, and algorithm-specialist startups seeking regulatory clearance. Strategic archetypes include oscillometric traditionalists, optical sensor integrators, and ECG-convergence specialists. Dominant competitive moves encompass regulatory-first validation investments and algorithm-hardware co-design partnerships.
Among diversified electronics conglomerates, Samsung Electronics exemplifies semiconductor-integrated platform expansion. Precision device specialists OMRON Healthcare occupy the clinical-grade oscillometric tier. Algorithm-native entrants Aktiia SA represent the cuffless optical validation pathway. Each anchors distinct competitive positioning without overlapping core competency claims.
| Leading Market Players |
|---|
| OMRON Healthcare |
| Samsung Electronics |
| Fitbit (Google) |
| Apple |
| Aktiia SA |
| Withings SA |
| Biobeat Technologies Ltd |
| Qardio Inc |
| iHealth Labs Inc |
| Others |
Value Network & Pricing Analysis
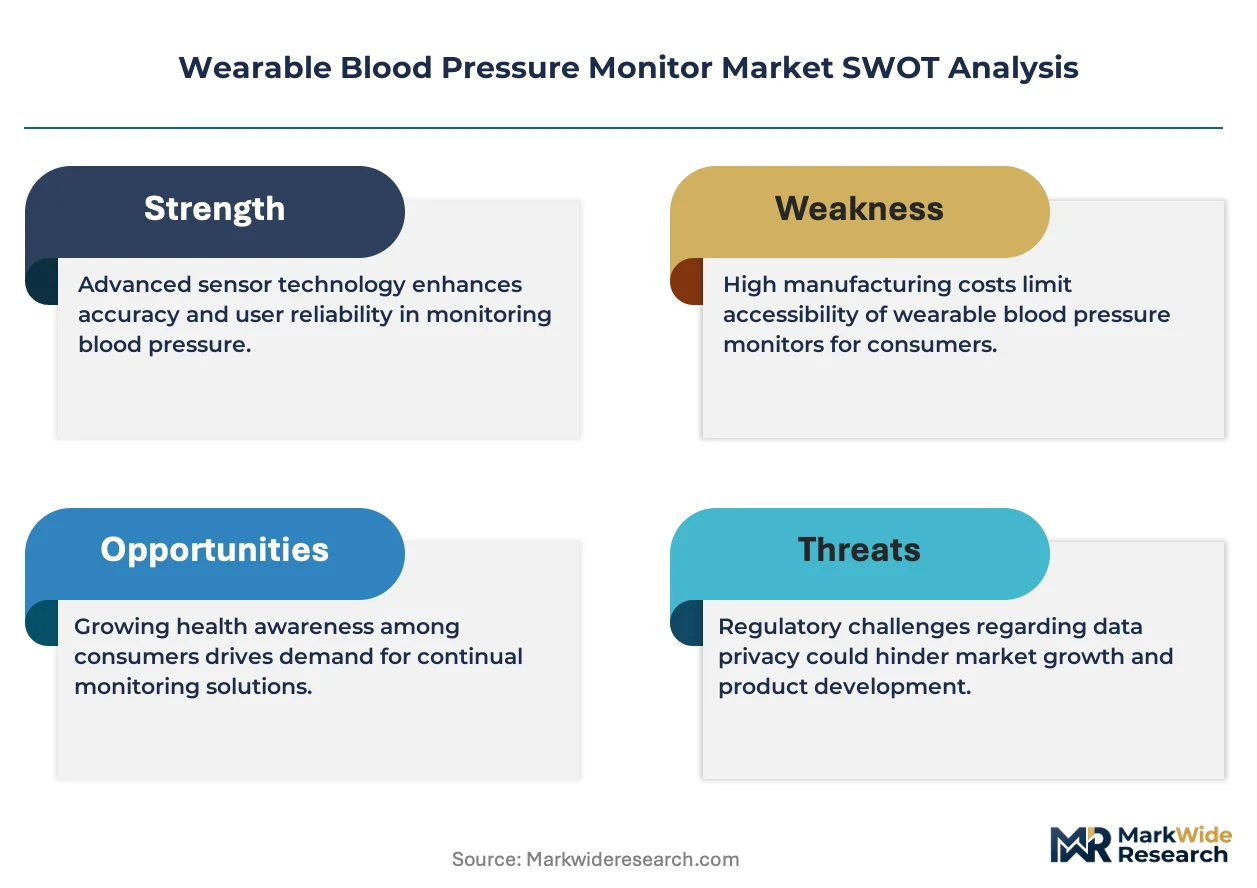
Hospital procurement unbundling of after-sales service from device acquisition is forcing manufacturers to absorb calibration and algorithm update costs into upfront pricing, compressing margins on clinical-grade arm cuff variants while smartwatch form factors escape this pressure through direct-to-consumer channels.
Pricing Analysis
Retailer markup layers in pharmacy and online channels sustain consumer-facing price points for wrist-based optical devices. Three-tier pricing structure across premium, standard, and economy levels separates ECG-integrated models with arrhythmia correlation from basic Bluetooth-enabled units and fitness tracker derivatives. Cost compression in the standard tier is intensifying because Chinese sensor module producers are flooding export markets with medical-grade photoplethysmography chips. Hypertensive patients enrolled in Medicare reimbursement programs exhibit lowest price sensitivity due to coverage validation requirements.
Supply Chain Analysis
Returns and refurbishment flows for clinical-grade arm cuff devices create reverse-logistics complexity that smartwatch manufacturers avoid through disposable component architectures. Component sourcing concentrates in China for photoplethysmography chips, South Korea for semiconductor integration, and Japan for precision oscillometric sensors. Raw material dependencies span medical-grade LEDs, MEMS pressure transducers, and lithium-polymer cells. Single-source vulnerability in Chinese sensor module supply threatens non-domestic device assemblers amid geopolitical friction. Distribution runs through hospital procurement departments, online retail platforms, and pharmacy networks with diverging service bundling expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable blood pressure monitoring functions as a stable compounder anchored by Medicare reimbursement expansion for remote patient monitoring, which locks in recurring demand from diagnosed hypertensive populations regardless of consumer electronics cyclicality.
For Market Incumbents: Deploy algorithm-hardware co-design partnerships to defend against semiconductor-integrated smartwatch platforms eroding the clinical-grade tier. Secure predicate device pathway renewals for oscillometric wrist devices before EU MDR Article 117 expiration eliminates legacy routes. Build captive calibration service networks to offset hospital procurement unbundling. For New Entrants and Emerging Players: The premium-to-economy price-point gap in ECG-integrated models opens white-space opportunity in arrhythmia correlation for comorbid cardiac patients. Target Japan's super-aged society through METI-aligned preventive health technology channels. Pursue software companion development for electronic health record integration as the fastest procurement qualification route. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-native specialists possessing FDA validation datasets for cuffless optical systems. Long-term viability centers on regulatory moats rather than hardware scale. Monitor NMPA approval velocity in China as the inflection signal for global component supply rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Extensive sphygmomanometer reference studies compress competitive entry timelines for cuffless optical entrants. |
| CE Marking Pathway | EU MDR Article 117 compliance costs escalate as notified bodies demand sustained accuracy across skin tone variations. |
| Hospital System Partnership | Integrated delivery network vendor consolidation favors suppliers with custom API development capabilities. |
| Software Companion Development | Algorithm update subscriptions displace manufacturer-captive service agreements in United States health system tenders. |
| Reimbursement Strategy | Medicare coverage crystallization for physician-validated wearable data secures preferred supplier status. |
Research Methodology
Bottom-up hypertensive patient enrollment modeling reconciled against top-down sensor module production tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies were validated against FDA 510(k) filings, NMPA registration databases, EU MDR technical documentation, and CMS Medicare reimbursement policy bulletins.
Input-output matrices connect photoplethysmography chip output volumes to finished device assembly rates across smartwatch, arm cuff, fitness tracker, and oximeter form factors. Segmentation dimensions span product type, technology protocol, end-user acuity, and distribution channel economics. CAGRs were derived from patient population growth curves and reimbursement policy expansion trajectories. Industry-specific forecast inputs include semiconductor integration cost curves and regulatory validation timeline distributions.
Caveats apply where FDA premarket clearance delays or geopolitical friction in Chinese sensor module supply could materially shift the outlook. Practitioners should monitor NMPA approval velocity and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
ADA Substitute Market