
 South America Cardiac Arrhythmia Monitoring Devices Market | 2026-2036
South America Cardiac Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cardiac Arrhythmia Monitoring Devices Market Analytics
Modular device bundles pairing Holter monitors with cloud analytics platforms is expanding choice for cardiology departments across South America. Medtronic leverages its implantable loop recorder portfolio to anchor high-acuity hospital contracts. Abbott Laboratories competes through wireless communication-enabled devices that streamline remote patient workflows. iRhythm Technologies specializes in data analytics-driven screening programs targeting diagnostic centers.
Cardiac arrhythmia monitoring devices encompass electrophysiological recording instruments that detect rhythm abnormalities through surface electrodes, implantable sensors, or wearable patches with sampling rates typically exceeding 250 Hz for diagnostic-grade resolution. These systems serve to reduce stroke risk through early atrial fibrillation detection and enable guideline-directed anticoagulation therapy. Mobile cardiac telemetry represents the fastest-expanding device type as ambulatory surgical centers adopt real-time streaming protocols. Cloud-based solutions command the technology margin pool by minimizing on-premise infrastructure costs for multi-site hospital networks. Postoperative care applications show structural momentum where continuous monitoring replaces intermittent spot-checks in cardiac recovery wards.
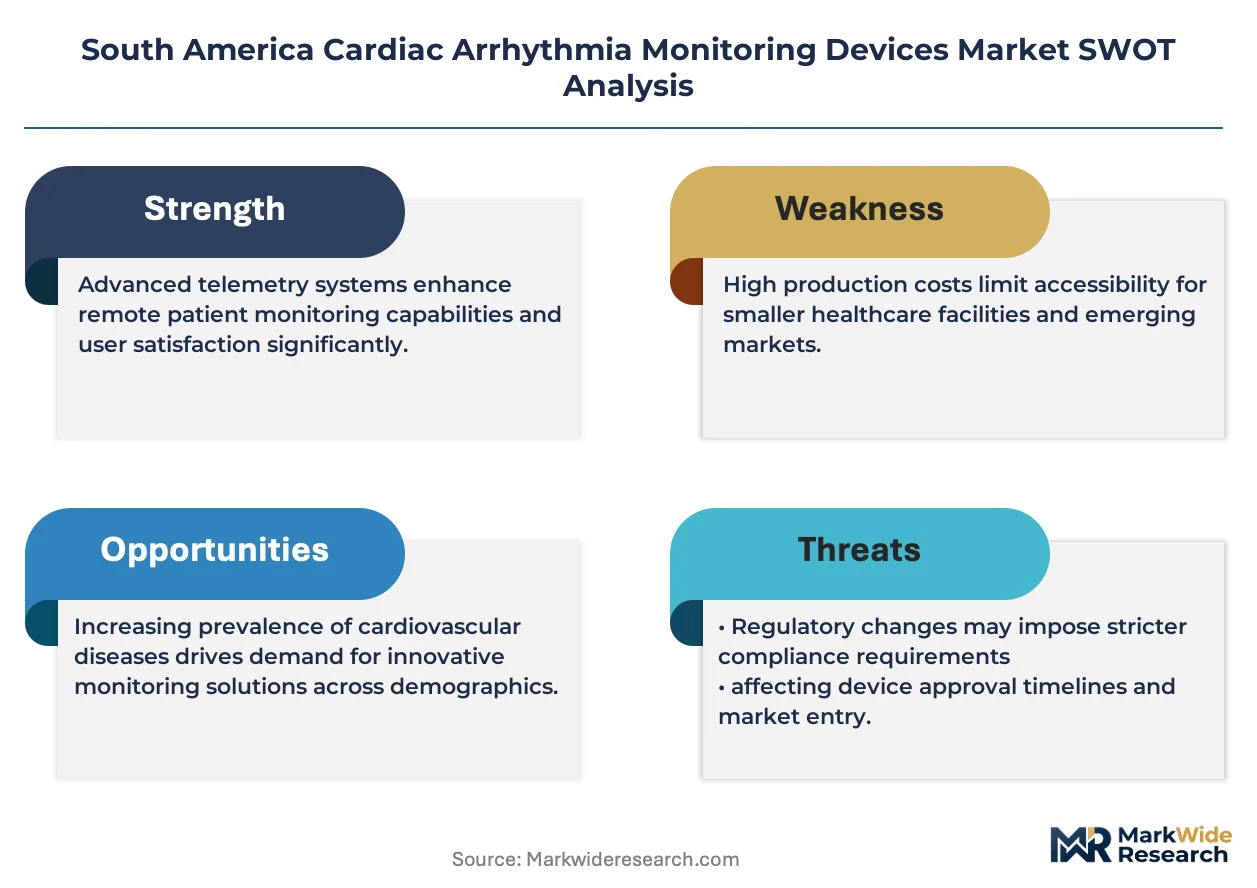
ANVISA governs medical device registration and post-market surveillance in Brazil, requiring clinical evidence submissions that shape product development timelines for manufacturers entering the region. Argentina's national pharmaceutical regulator enforces comparable safety standards, while ISO 13485 certification serves as the baseline quality management framework accepted across South American markets. Stakeholders must monitor reimbursement policy evolution for home healthcare telemetry, as public and private payer decisions will determine whether remote monitoring achieves scalable penetration outside major metropolitan hospital networks.
Market Dynamics
Home healthcare telemetry adoption in Brazil and Argentina is compressing hospital-centric procurement cycles, forcing device manufacturers to reconfigure service delivery models around remote patient workflows and cloud infrastructure.
Growth Catalysts
- ANVISA registration reforms:Streamlined clinical evidence requirements for wearable cardiac monitors are accelerating market entry timelines for international manufacturers targeting Brazilian private hospital networks.
- Mobile cardiac telemetry:Ambulatory surgical centers across São Paulo state are deploying real-time streaming protocols, creating pull for continuous monitoring solutions outside traditional inpatient settings.
- Cloud analytics platforms:Modular device bundles pairing Holter monitors with remote data infrastructure are expanding procurement options for cardiology departments seeking to minimize on-premise capital expenditure.
Market Restraints
- Reimbursement policy uncertainty:Public and private payer decisions on home healthcare telemetry coverage are constraining scalable penetration outside major metropolitan hospital networks in Brazil and Argentina.
- ISO 13485 certification complexity:Quality management framework requirements accepted across South American markets impose extended product development timelines that disadvantage smaller manufacturers.
- Argentina's economic volatility:Currency instability and import restrictions are distorting device pricing and creating working capital constraints for distributors serving provincial diagnostic centers.
Strategic Opportunities
- Postoperative cardiac recovery wards:Continuous monitoring protocols replacing intermittent spot-checks represent underpenetrated demand within Brazil's expanding private hospital infrastructure.
- Argentina's provincial diagnostic centers:Wireless communication-enabled devices can bypass infrastructure limitations in secondary cities where wired telemetry remains impractical.
- Guideline-directed anticoagulation programs:Early atrial fibrillation detection mandates from cardiology societies are creating institutional pull for screening-as-a-service models.
Industry Challenges
- Electrophysiologist workforce scarcity:Interpretation of high-resolution arrhythmia data requires specialized clinical expertise that concentrates in São Paulo and Buenos Aires, limiting service scalability.
- Legacy hospital IT integration:Cloud-based telemetry platforms face interoperability friction with entrenched electronic health record systems in Brazil's established private networks.
- Post-market surveillance compliance:ANVISA's adverse event reporting requirements demand dedicated regulatory affairs capacity that strains mid-sized device importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cardiac Arrhythmia Monitoring Devices Market |
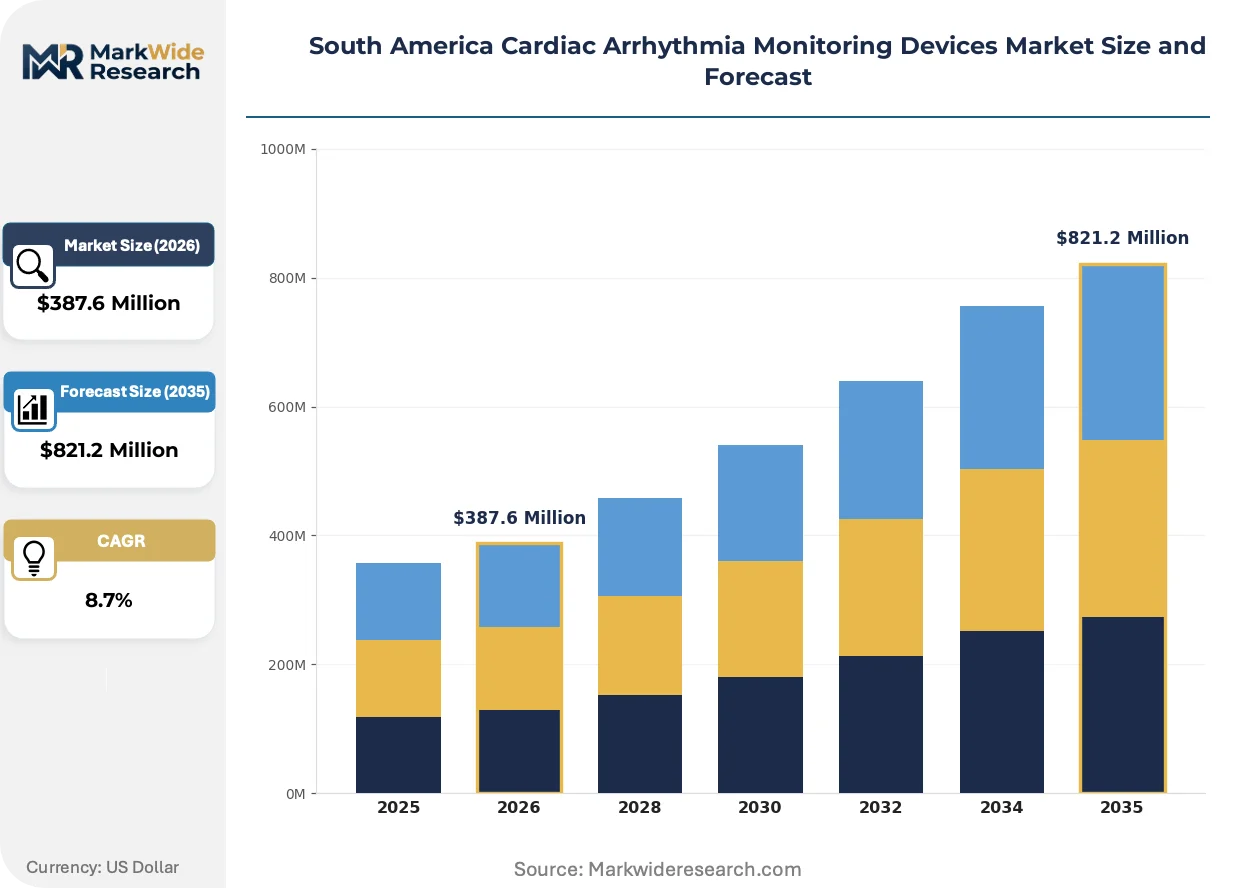
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Holter Monitors, Event Monitors, Implantable Loop Recorders, Mobile Cardiac Telemetry End User: Hospitals, Diagnostic Centers, Home Healthcare, Ambulatory Surgical Centers Technology: Electrocardiography, Wireless Communication, Data Analytics, Cloud-Based Solutions Application: Continuous Monitoring, Postoperative Care, Screening, Telehealth |
| Companies Covered | GE Healthcare, Biotronik, Medtronic, BioTelemetry, AliveCor, Abbott Laboratories, Koninklijke Philips, iRhythm Technologies, Boston Scientific, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cardiac Arrhythmia Monitoring Devices Market Evolving Landscape
Device architecture and service delivery models are restructuring around patient mobility and data liquidity, with hardware commoditization pushing competitive differentiation toward analytics and workflow integration.
Artificial intelligence-enabled arrhythmia classification algorithms are converging with patch-based electrocardiography systems to reduce false-positive burden on clinical readers. Diagnostic centers in Brazil's Southeast region are piloting these tools to accelerate report turnaround times. The technology is converging with cloud infrastructure to enable same-day diagnostic workflows that previously required 48-72 hour Holter analysis cycles.
Argentina's national pharmaceutical regulator is tightening post-market surveillance requirements for Class III cardiac devices, mirroring ANVISA's risk-based classification framework. This regulatory convergence is compelling manufacturers to standardize quality management systems across Mercosur markets rather than maintaining country-specific compliance architectures. Private hospital procurement teams are responding by demanding unified technical documentation packages that satisfy multiple jurisdictions.
Subscription-based remote monitoring services are displacing capital-intensive device ownership models among Brazil's mid-sized cardiology practices. These practices previously deferred telemetry investments due to upfront hardware costs and uncertain utilization rates. The shift is most visible in São Paulo state's satellite municipalities, where physician-entrepreneurs are outsourcing device logistics to specialized service operators.
South America Cardiac Arrhythmia Monitoring Devices Market Segmentation
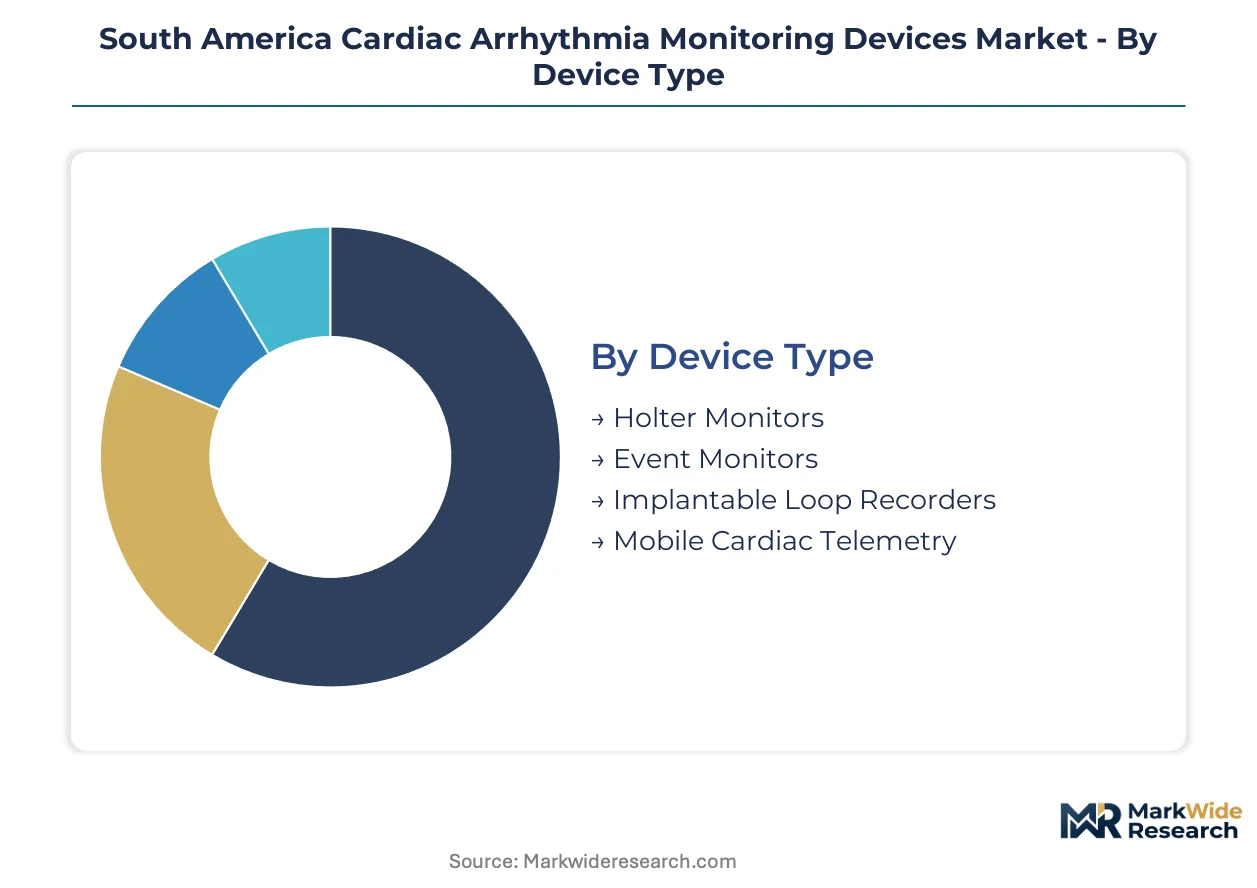
Device architecture and care delivery models across South America stratify around acuity levels, reimbursement pathways, and infrastructure maturity. Procurement patterns diverge sharply between Brazil's private hospital networks and Argentina's provincial diagnostic centers.
Device Type:
Standardization dominates low-acuity ambulatory devices while customization requirements intensify for implantable and real-time streaming systems serving critical care pathways.
- Holter Monitors:These 24-48 hour ambulatory electrocardiography systems record continuous cardiac electrical activity through 3-12 lead surface electrodes. Demand concentrates in São Paulo's diagnostic center chains where high patient throughput justifies dedicated Holter analysis laboratories. ANVISA registration reforms have accelerated import timelines for these established device categories.
- Mobile Cardiac Telemetry:Real-time streaming devices transmit electrophysiological data through cellular networks with automated arrhythmia detection algorithms. Brazil's ambulatory surgical centers in Rio de Janeiro and Belo Horizonte are deploying these systems to enable same-day discharge protocols for cardiac catheterization patients.
- Event Monitors:Patient-activated or auto-triggered devices capturing episodic rhythm disturbances over 30-day wear periods.
- Implantable Loop Recorders:Subcutaneous devices for cryptogenic stroke evaluation and infrequent arrhythmia detection in high-risk populations.
Most installed capacity flows through Holter Monitors. Expansion is steepest in Mobile Cardiac Telemetry.
End User:
Procurement authority is fragmenting as physician-entrepreneurs in Brazil's satellite municipalities bypass hospital purchasing committees through subscription service arrangements.
- Hospitals:Brazil's private hospital networks in São Paulo state anchor capital-intensive telemetry investments, with mobile cardiac telemetry contracts bundled into cardiac service line agreements. IT integration requirements with existing electronic health record systems create switching costs that favor incumbent suppliers.
- Home Healthcare:Remote monitoring services are compressing traditional hospital-centric procurement cycles, with Argentina's Buenos Aires province showing early adoption of physician-supervised home telemetry for postoperative cardiac patients. Reimbursement policy uncertainty remains the primary constraint on scalable penetration.
- Diagnostic Centers:High-throughput electrocardiography interpretation services in Brazil's Southeast region.
- Ambulatory Surgical Centers:Same-day procedure facilities requiring continuous monitoring capabilities without overnight admission infrastructure.
Revenue concentration sits with Hospitals. Home Healthcare is climbing the fastest.
Technology:
Margin capture is shifting from hardware specifications toward data infrastructure and clinical decision support capabilities.
- Cloud-Based Solutions:Remote data infrastructure eliminates on-premise server requirements and enables multi-site hospital network coordination across Brazil's expanding private healthcare systems. ANVISA's data localization requirements for patient health information create compliance architecture decisions for international platform vendors.
- Data Analytics:Artificial intelligence-enabled arrhythmia classification algorithms are reducing false-positive burdens and accelerating report turnaround times in diagnostic centers. These tools are converging with patch-based electrocardiography systems to enable same-day diagnostic workflows.
- Electrocardiography:Surface electrode-based signal acquisition with sampling rates exceeding 250 Hz for diagnostic-grade resolution.
- Wireless Communication:Bluetooth and cellular transmission protocols enabling patient mobility during monitoring periods.
Technology investment prioritizes Cloud-Based Solutions. Data Analytics is gaining share fastest.
Application:
Clinical utility is expanding beyond traditional arrhythmia detection toward workflow optimization and population health screening mandates.
- Continuous Monitoring:Real-time electrophysiological surveillance replaces intermittent spot-checks in Brazil's postoperative cardiac recovery wards, with private hospital networks deploying these protocols to reduce nursing workload and capture reimbursement for intensive monitoring services.
- Screening:Guideline-directed atrial fibrillation detection programs are creating institutional demand for diagnostic-center-based screening-as-a-service models, particularly in Argentina where cardiology society mandates are driving early detection initiatives.
- Postoperative Care:Cardiac surgery and catheterization recovery protocols requiring rhythm surveillance during hemodynamic stabilization periods.
- Telehealth:Remote physician-patient interactions supported by transmitted electrocardiography data.
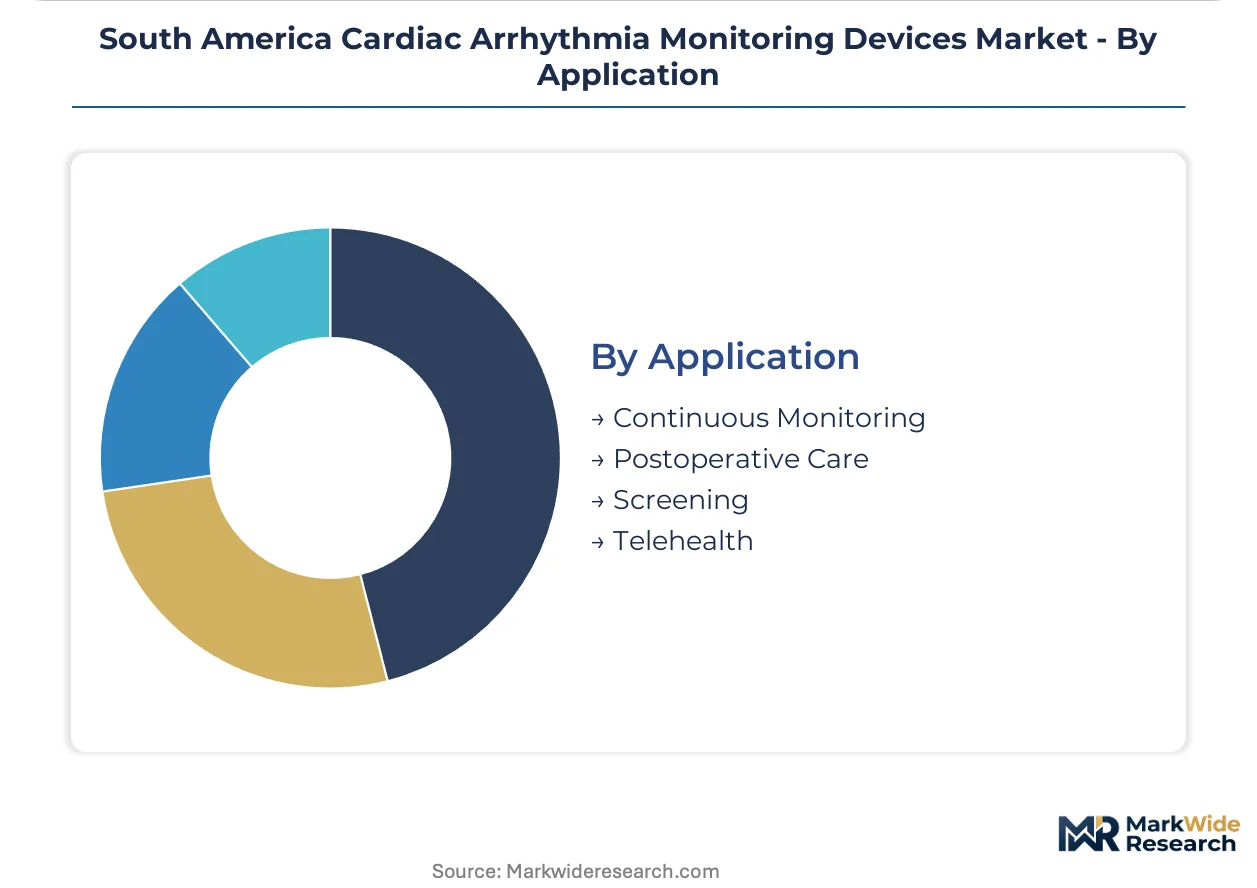
Deployment volume concentrates in Continuous Monitoring. Screening shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac arrhythmia monitoring technology first achieved commercial scale in North American and European hospital systems before expanding into South American markets during the 2000s. Brazil and Argentina now anchor regional demand as private healthcare infrastructure modernizes and regulatory frameworks align with international standards.
Brazil
São Paulo state's private hospital networks drive capital-intensive telemetry investments, with mobile cardiac telemetry contracts bundled into cardiac service line agreements. ANVISA governs medical device registration and post-market surveillance, requiring clinical evidence submissions that shape product development timelines for manufacturers. Rio de Janeiro and Belo Horizonte clusters deploy real-time streaming protocols in ambulatory surgical centers to enable same-day discharge for cardiac catheterization patients.
Argentina
Buenos Aires province shows early adoption of physician-supervised home telemetry for postoperative cardiac patients, compressing traditional hospital-centric procurement cycles. The country's national pharmaceutical regulator enforces safety standards comparable to Brazil's framework, while currency instability distorts device pricing for provincial diagnostic centers. Secondary cities in the interior adopt wireless communication-enabled devices to bypass infrastructure limitations where wired telemetry remains impractical.
Chile
Santiago's private healthcare clusters demonstrate selective adoption of cloud-based telemetry platforms as multi-site hospital networks seek to minimize on-premise capital expenditure. The country's medical device regulatory framework emphasizes ISO 13485 certification as a baseline quality management requirement. Diagnostic centers in the metropolitan region pilot artificial intelligence-enabled arrhythmia classification to accelerate report turnaround times.
Colombia
Bogotá's cardiology departments expand procurement options through modular device bundles pairing Holter monitors with remote data infrastructure. The national health regulator maintains risk-based classification frameworks for cardiac devices that align with regional Mercosur standards. Private hospital networks in Medellín deploy continuous monitoring protocols in postoperative cardiac recovery wards to reduce nursing workload.
Peru
Lima's diagnostic center chains concentrate demand for established Holter monitor categories where high patient throughput justifies dedicated analysis laboratories. The country's pharmaceutical and medical device regulator enforces post-market surveillance requirements that strain mid-sized device importers. Provincial centers face working capital constraints that favor subscription-based remote monitoring services over capital-intensive device ownership.
South America Cardiac Arrhythmia Monitoring Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and data analytics capabilities. The vendor base stratifies between implantable device specialists, wearable monitor manufacturers, and cloud platform operators. Three archetypes dominate: diversified medical technology conglomerates with implantable portfolios, cardiac-focused diagnostics specialists with data analytics capabilities, and emerging wearable device innovators with consumer-health crossover appeal. M&A activity concentrates on acquiring artificial intelligence-enabled arrhythmia classification capabilities, while strategic partnerships between hardware manufacturers and cloud infrastructure providers reshape service delivery models.
Within the diversified medical technology tier, Medtronic and Abbott Laboratories anchor high-acuity hospital contracts through established implantable loop recorder portfolios and wireless communication-enabled device ecosystems. iRhythm Technologies occupies a specialist position exemplifying data analytics-driven screening programs targeting diagnostic centers. These three entities represent distinct competitive vectors: implantable hardware dominance, integrated wireless workflows, and algorithmic diagnostic services.
| Leading Market Players |
|---|
| GE Healthcare |
| Biotronik |
| Medtronic |
| BioTelemetry |
| AliveCor |
| Abbott Laboratories |
| Koninklijke Philips |
| iRhythm Technologies |
| Boston Scientific |
| Others |
Value Network & Pricing Analysis
ANVISA's ISO 13485 certification mandate gates qualified supply access and premium-tier pricing power for cardiac arrhythmia monitoring devices entering Brazilian private hospital networks, compressing margins for uncertified manufacturers while elevating cloud-analytics-integrated bundles.
Pricing Analysis
Subscription-based service models for remote patient monitoring are displacing capital-intensive device ownership across São Paulo's cardiology practices. Pricing stratifies across premium, standard, and economy tiers based on cloud infrastructure integration depth and ANVISA registration tier. Cost compression in economy-tier Holter monitors is intensifying because Argentina's currency instability forces distributors to absorb import cost volatility. Mid-sized diagnostic centers in Brazil's interior provinces exhibit highest price sensitivity, while São Paulo's private hospital networks prioritize workflow integration over unit economics.
Supply Chain Analysis
ISO 13485 certification requirements filter component suppliers, concentrating qualified electrophysiology sensor and telemetry transmission module sourcing in the United States, Germany, and China. Surface electrode arrays, lithium-ion power cells, and cellular transmission chipsets constitute critical input dependencies. Single-source vulnerability in patch-based electrocardiography adhesive substrates creates exposure to medical-grade polymer supply disruptions. Distribution runs through authorized medical device distributors with ANVISA import licenses, bypassing direct hospital procurement in Brazil and Argentina's secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in South American cardiac arrhythmia monitoring hinges on cloud infrastructure cost-down curves and premium-tier AI-enabled diagnostic service adoption, compressing hardware commoditization pressures.
For Market Incumbents: Anticipate subscription-based remote monitoring services eroding capital equipment attach rates by securing multi-year cardiac service line agreements with São Paulo's private hospital networks. Defend against wearable patch entrants through backward integration into cloud analytics platforms and ANVISA-registered manufacturing partnerships that accelerate post-market surveillance compliance. For New Entrants and Emerging Players: Enter via Argentina's provincial diagnostic centers where wireless-enabled devices bypass wired infrastructure gaps and currency-driven pricing distortions disadvantage incumbent distributors. Target physician-entrepreneurs in São Paulo's satellite municipalities with device-as-a-service models that eliminate upfront capital barriers and capture recurring telemetry revenue streams. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap wearable monitor manufacturers lacking AI-enabled arrhythmia classification capabilities, presenting consolidation opportunities before cloud-native diagnostics specialists achieve scale. Monitor ANVISA reimbursement policy determinations for home healthcare telemetry as the inflection signal for scalable penetration outside metropolitan hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Acceleration | Streamlined clinical evidence requirements compress market entry timelines for wearable cardiac monitors targeting Brazilian private networks. |
| Cloud Analytics Platform Integration | Multi-site hospital coordination across Brazil's expanding private healthcare systems eliminates on-premise server capital expenditure. |
| AI-Enabled Arrhythmia Classification Development | Same-day diagnostic workflows in São Paulo diagnostic centers reduce false-positive burden and accelerate report turnaround. |
| Hospital System Partnership Expansion | Cardiac service line agreements in Rio de Janeiro and Belo Horizonte ambulatory surgical centers enable same-day discharge protocols. |
| Reimbursement Strategy Formulation | Public and private payer coverage decisions in Argentina's Buenos Aires province determine home telemetry scalability. |
Research Methodology
Multiple input streams — structured interviews with cardiology department heads, biomedical engineering directors, and GPO contracts managers; regulatory filings with ANVISA and Argentina's national pharmaceutical regulator; and hospital procurement database analysis — were reconciled through bottom-up device shipment tracking and top-down healthcare expenditure modeling.
Historical telemetry adoption patterns in Brazilian private hospital networks were cross-referenced against panel input from cloud platform operators and wearable device manufacturers to construct segmentation-specific growth trajectories across device type, end user, technology, and application dimensions. CAGRs were derived from installed base evolution and replacement cycle analysis, incorporating ANVISA registration reform impacts and Argentina's macroeconomic volatility assumptions.
Inputs from ANVISA adverse event reporting systems and Mercosur trade flow databases were available through the study window; gaps in provincial diagnostic center procurement records introduce uncertainty bands around Argentina's interior market sizing. Forecasts reflect documented assumptions regarding reimbursement policy evolution and electrophysiologist workforce concentration. A model refresh is warranted upon material change in ANVISA home healthcare telemetry coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Australia Patient Monitoring Market