
 Real-Time Location System (RTLS) in Healthcare Market | 2026-2036
Real-Time Location System (RTLS) in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Location System (RTLS) in Healthcare Market Insights
Modular tag-and-software bundling is rebalancing how health systems evaluate total cost of ownership against point-solution flexibility. Zebra Technologies Corporation leverages its hardware-software integration to dominate enterprise-grade deployments. CenTrak, Inc. specializes in clinical-grade location accuracy for operating-room workflows. Impinj, Inc. sustains its position through RAIN RFID silicon supply to third-party healthcare OEMs.
Real-Time Location System in Healthcare denotes infrastructure that computes spatial coordinates of tagged assets, patients, or personnel through radio frequency, infrared, or ultrasonic signaling with sub-room-level precision, typically achieving one- to three-meter accuracy in multipath clinical environments. These systems stream coordinate data into nurse-call platforms, electronic health records, and building-management dashboards to reduce search time, prevent equipment hoarding, and enforce hand-hygiene compliance. RFID technology occupies the largest installed base due to mature tag economics and reader interoperability, though Ultrafine SigFox is gaining traction in European long-range campus tracking where cellular costs prove prohibitive. Cloud-Based delivery mode captures the fastest expansion as hospital IT departments outsource infrastructure maintenance and security patching to vendors with HITRUST certification.
The FDA enforces Unique Device Identification traceability that rewards RFID-enabled asset registries, while HIPAA mandates audit logging for any system processing patient location data, effectively raising the compliance bar for market entry. The EU AI Act and GDPR jointly constrain automated patient-flow algorithms that profile individuals without explicit consent, shaping European product roadmaps. Stakeholders must monitor how emerging cybersecurity disclosure rules from the SEC and analogous EU directives alter liability allocation between RTLS vendors and hospital operators.
Market Dynamics
Hospital procurement committees now weight HITRUST certification and FDA UDI compliance above raw tag pricing, forcing vendors to absorb cybersecurity audit costs into subscription models rather than hardware margins.
Growth Catalysts
- FDA Unique Device Identification mandates:Asset registries must maintain end-to-end traceability for Class II and III medical devices, creating pull-through demand for RFID-enabled location platforms in US acute care networks.
- Operating-room workflow digitization:Surgical suites in Germany and Japan deploy sub-meter accuracy systems to track instrument sterilization cycles and reduce turnover delays between procedures.
- Bluetooth Low Energy mesh networks:These protocols cut infrastructure deployment costs by eliminating dedicated cabling to ceiling-mounted exciters, accelerating adoption in mid-sized community hospitals.
Market Restraints
- Lithium battery supply concentration:Active RFID tags depend on cell production concentrated in East Asian manufacturing hubs, exposing tag economics to raw material volatility and export licensing friction.
- Multipath interference in steel-frame construction:Ultrasonic and infrared signaling suffers accuracy degradation in older hospital buildings with dense metallic infrastructure, limiting retrofit viability.
- GDPR Article 9 constraints on health data:European deployments face explicit consent requirements for patient location tracking that complicate automated flow optimization algorithms.
Strategic Opportunities
- India's hospital modernization wave:The country's PLI scheme for medical electronics creates subsidy pathways for RTLS vendors targeting greenfield tertiary care construction in Delhi and Mumbai corridors.
- Ambulatory surgery center expansion:Outpatient facilities in the United States seek lightweight, cloud-native tracking for mobile equipment fleets without enterprise IT overhead.
- EU AI Act conformity certification:Vendors that pre-validate patient-flow algorithms against prohibited profiling criteria gain procurement preference in French and Dutch health systems.
Industry Challenges
- RF engineering talent scarcity:Hospital IT departments lack in-house expertise to tune antenna placement and multipath mitigation in complex clinical environments, forcing reliance on vendor professional services.
- Legacy nurse-call integration:Proprietary middleware from 1990s-installed systems requires custom API development, extending deployment timelines and inflating professional services burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time Location System (RTLS) in Healthcare Market |
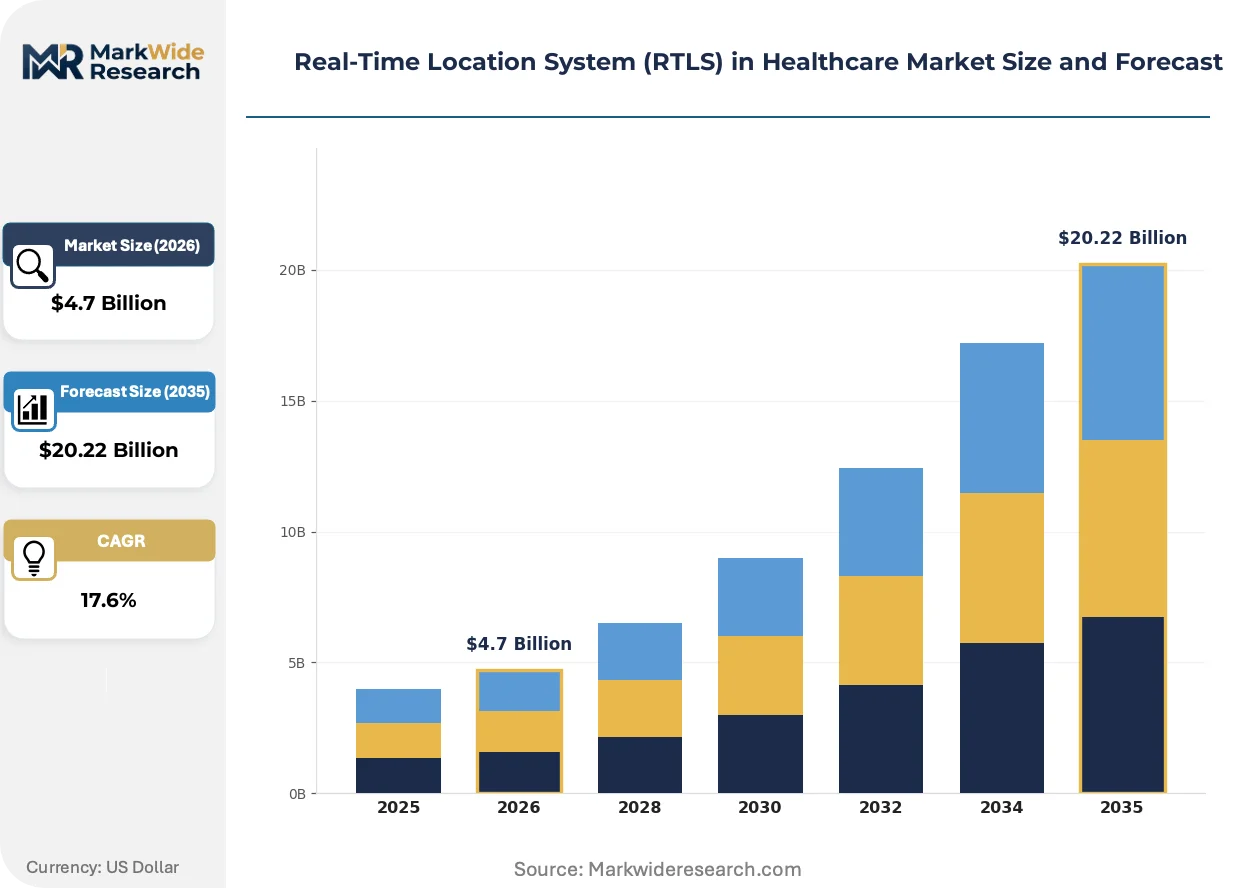
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $20.22 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Infrared, Ultrafine SigFox, GPS Application: Asset Tracking, Patient Management, Staff Coordination, Inventory Control Delivery Mode: Cloud-Based, On-Premises, Hybrid, SaaS End User: Hospitals, Nursing Facilities, Diagnostic Centers, Rehabilitation Clinics |
| Companies Covered | Securitas Healthcare LLC, Zebra Technologies Corporation, HPE Aruba Networking, Impinj, Inc., TeleTracking Technologies, Inc., CenTrak, Inc., Cognosos, Inc., Savi Technology, Inc., GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Location System (RTLS) in Healthcare Market Trends and Innovations
Edge computing architectures are compressing latency budgets for location-aware alerts, while regulatory pressure on data residency forces vendors to regionalize cloud infrastructure. These shifts favor modular, API-first platforms over monolithic enterprise suites.
Ultra-wideband chipsets are decentralizing precision location infrastructure by enabling peer-to-peer ranging between badges and smartphones without fixed anchor density. US health systems pilot these mesh configurations in emergency departments where rapid staff mustering demands sub-second latency. The technology is decentralizing hardware procurement decisions from centralized IT to departmental clinical engineering teams.
The EU AI Act's risk classification framework for biometric inference systems imposes conformity assessment obligations on patient-flow algorithms that predict length-of-stay or deterioration risk. German university hospitals now require vendor documentation of training data provenance and bias auditing before algorithm deployment. French regulators through CNIL coordinate with hospital groups to establish precedent on legitimate interest claims for staff tracking versus patient tracking.
Subscription pricing for location platform access is displacing perpetual license models in US health system procurement. Hospital CFOs facing capital expenditure freezes prefer operational expenditure treatment for infrastructure that requires continuous security patching and firmware updates. This preference concentrates in nonprofit systems with bond covenant constraints on balance-sheet debt.
Real-Time Location System (RTLS) in Healthcare Market Segmentation
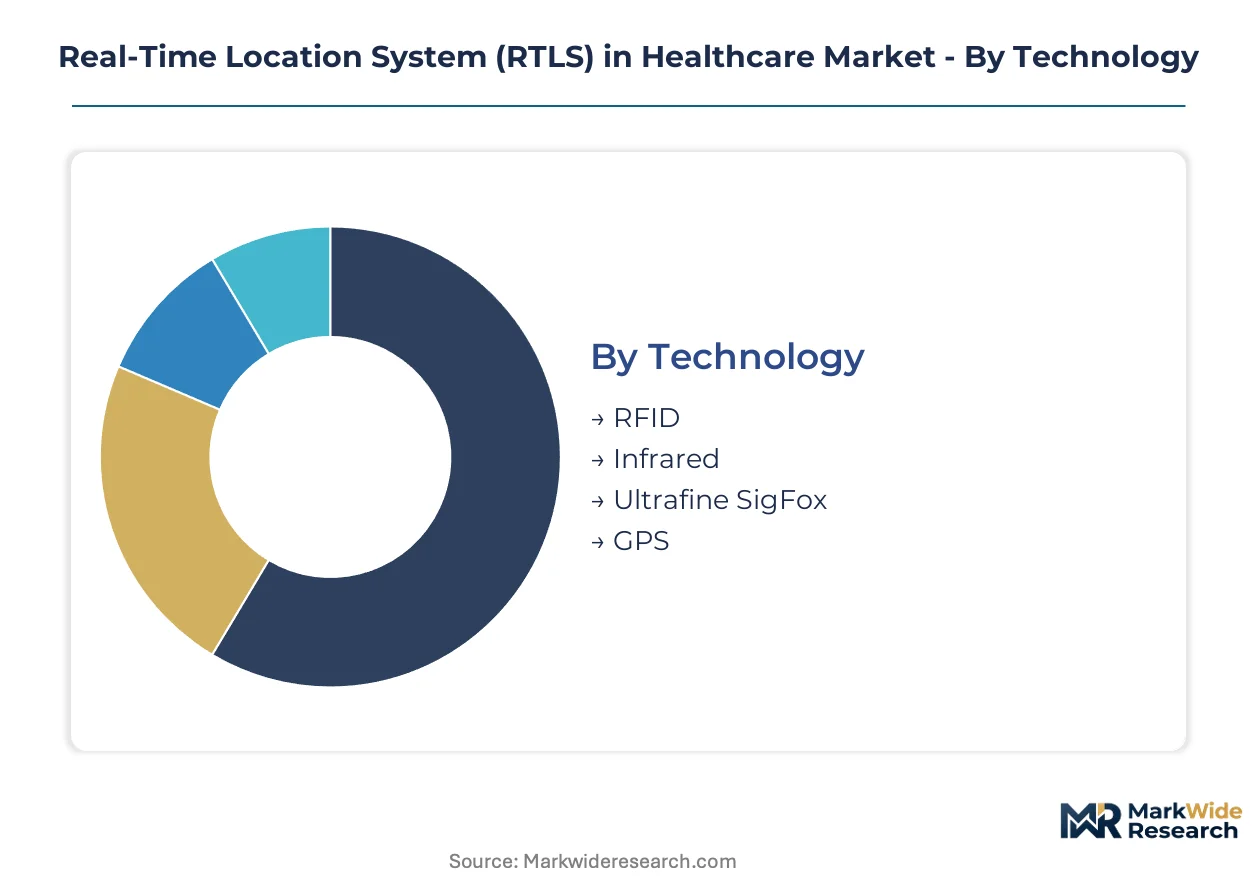
Hospital procurement cycles for RTLS infrastructure vary sharply by technology maturity and integration burden. Replacement timelines stretch from three years for cloud-native SaaS platforms to eight-plus years for hardwired infrared ceiling grids. Understanding segment-level upgrade elasticity helps vendors align subscription pricing with customer capital planning horizons.
Technology:
Upgrade cycles differentiate sharply across signaling protocols, with passive RFID nearing replacement saturation while campus-wide mesh networks drive greenfield investment.
- RFID:Passive and active radio-frequency identification tags dominate installed bases through mature economics and FDA UDI compliance alignment. Acute care networks in the United States prioritize RFID for surgical instrument sterilization tracking and infusion pump registries.
- Infrared:Ceiling-mounted infrared exciters deliver sub-meter accuracy for operating-room workflows but require dedicated cabling infrastructure that complicates retrofit economics. German university hospitals maintain these systems for instrument sterilization cycle verification despite higher maintenance overhead.
- Ultrafine SigFox:Low-power wide-area networking enables long-range campus tracking across European hospital grounds without cellular subscription costs. French and Dutch health systems pilot these configurations for outdoor equipment yards and parking structure coverage.
- GPS:Satellite-based positioning serves inter-facility fleet logistics and home health worker routing where indoor precision is unnecessary. Japanese metropolitan hospital networks deploy GPS for mobile diagnostic unit dispatch across dispersed clinic footprints.
Volume placements concentrate in RFID; the faster expansion belongs to Ultrafine SigFox.
Application:
Workflow digitization priorities reshape segment demand, with surgical suite optimization commanding premium pricing against back-office inventory automation.
- Asset Tracking:Medical equipment location services reduce search time and prevent departmental hoarding through real-time bed availability dashboards. United States acute care networks prioritize infusion pump and wheelchair fleet visibility to optimize capital utilization rates.
- Patient Management:Automated flow algorithms track bed status, transport requests, and emergency department length-of-stay predictions. GDPR Article 9 constraints in Europe limit deployment scope without explicit consent frameworks.
- Staff Coordination:Badge-based mustering and duress alerting improve emergency response times while supporting hand-hygiene compliance monitoring. Cloud-native platforms displace legacy nurse-call integration in mid-sized community hospitals.
- Inventory Control:Pharmaceutical and supply chain visibility targets par-level optimization and expiration date management. Hybrid delivery modes bridge on-premises ERP connectivity with cloud analytics for materials management departments.
Revenue concentration sits with Asset Tracking; Patient Management climbs fastest as AI-act-compliant algorithms mature.
Delivery Mode:
Capital expenditure freezes at nonprofit health systems accelerate operational expenditure treatment for infrastructure requiring continuous security patching.
- Cloud-Based:Vendor-managed infrastructure with HITRUST certification outsources cybersecurity maintenance and firmware updates. United States hospital CFOs facing bond covenant constraints prefer subscription treatment for balance-sheet relief.
- On-Premises:Dedicated server installations persist in defense and government hospital networks with data residency mandates. Higher upfront capital requirements limit adoption to systems with established IT capital budgets.
- Hybrid:Edge computing architectures process location alerts locally while streaming analytics to cloud dashboards. German hospitals deploy hybrid models to satisfy both latency requirements for emergency mustering and GDPR data localization rules.
- SaaS:Software-as-a-service licensing decouples platform access from hardware procurement, enabling departmental clinical engineering teams to pilot without centralized IT approval. Ambulatory surgery centers favor lightweight SaaS for mobile equipment fleet visibility.
Deployment share tilts toward Cloud-Based; SaaS expands most quickly among outpatient facilities.
End User:
Facility type determines accuracy requirements and integration complexity, with tertiary hospitals demanding sub-meter precision against nursing facility cost sensitivity.
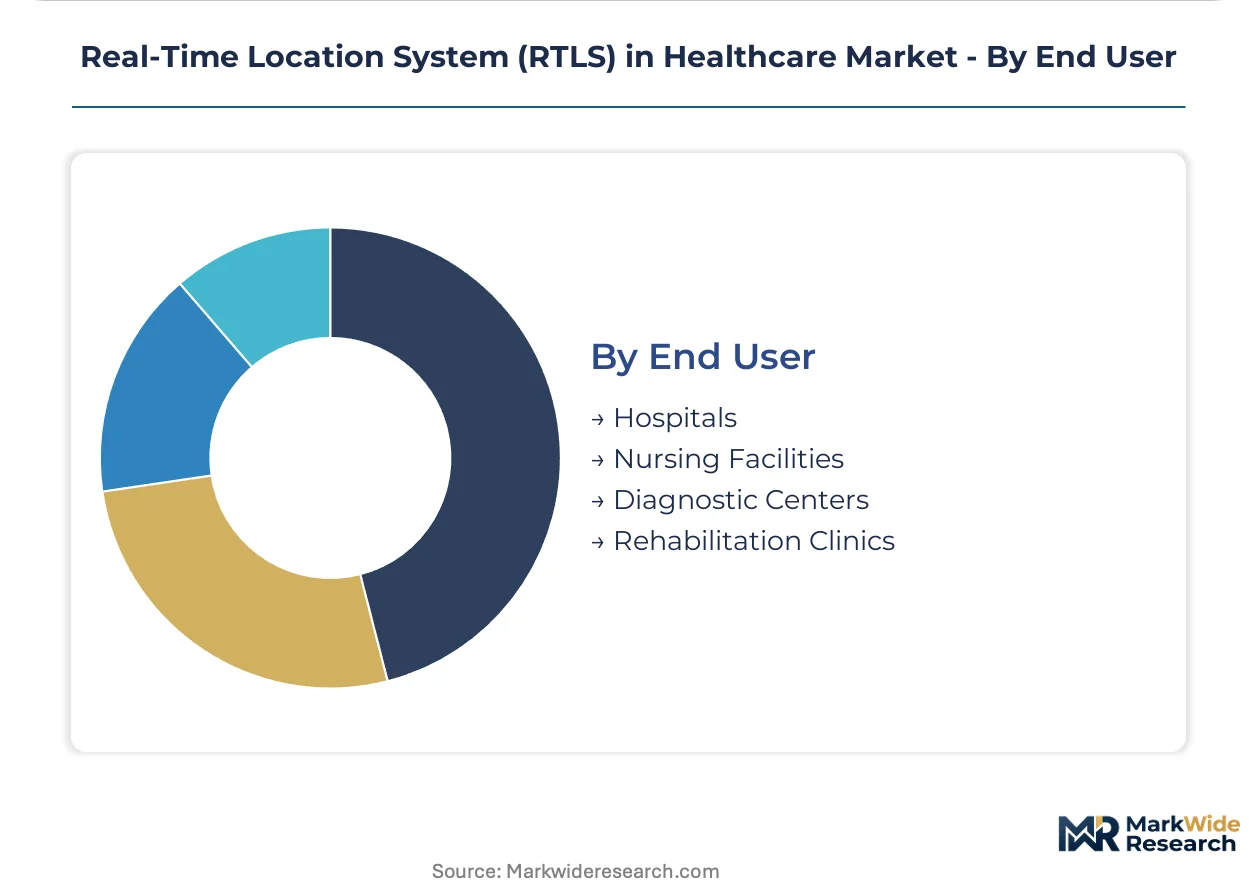
- Hospitals:Acute care networks require room-level and bay-level accuracy for emergency department throughput and operating-room turnover optimization. Japan and Germany lead modernization waves for surgical suite digitization.
- Nursing Facilities:Long-term care operators prioritize wander management and fall detection over asset tracking, accepting corridor-level precision for lower per-bed infrastructure costs. Bluetooth Low Energy mesh networks reduce deployment complexity in older building stock.
- Diagnostic Centers:Imaging and laboratory facilities track mobile equipment fleets and patient flow through high-volume outpatient corridors. Cloud-native platforms minimize IT overhead for standalone operators without enterprise infrastructure.
- Rehabilitation Clinics:Physical therapy and post-acute settings focus on staff safety duress systems and equipment utilization in distributed treatment bays. Lightweight SaaS configurations align with smaller capital budgets and rapid deployment timelines.
Installed base centers on Hospitals; Rehabilitation Clinics gain share fastest as post-acute networks consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware production concentrates in East Asian manufacturing hubs while software development and clinical deployment concentrate in North American and Western European health systems. Consumption patterns diverge sharply between mature acute care networks modernizing legacy infrastructure and emerging markets building greenfield digital capabilities.
United States
FDA Unique Device Identification mandates drive RFID-enabled asset registry procurement across acute care networks. HIPAA audit logging requirements raise compliance barriers for patient location data processing. The Texas Medical Center in Houston deploys sub-meter accuracy systems across fifty-plus hospitals for surgical suite optimization.
Germany
Operating-room workflow digitization commands premium pricing for clinical-grade location accuracy. The EU AI Act imposes conformity assessment obligations on patient-flow algorithms predicting length-of-stay. University hospitals in Bavaria require vendor documentation of training data provenance before algorithm deployment.
Japan
METI hospital modernization subsidies accelerate surgical suite digitization in metropolitan networks. PMDA guidance on connected medical devices shapes procurement criteria for location-aware platforms. The Kanto region around Tokyo leads deployment of mobile diagnostic unit dispatch systems using satellite positioning across dispersed clinic footprints.
France
CNIL coordinates with hospital groups to establish precedent on legitimate interest claims for staff tracking versus patient tracking. GDPR Article 9 explicit consent requirements complicate automated patient-flow optimization. The Île-de-France region pilots Ultrafine SigFox configurations for outdoor equipment yards and parking structure coverage.
India
The PLI scheme for medical electronics creates subsidy pathways for RTLS vendors targeting greenfield tertiary care construction. CDSCO medical device regulations increasingly align with international traceability standards. Hospital construction corridors in Delhi and Mumbai drive demand for cloud-native location platforms without legacy integration burden.
Real-Time Location System (RTLS) in Healthcare Market Competitive Landscape
The competitive structure tilts toward hardware-software integration specialists with enterprise IT relationships. Three tiers separate dominant platform vendors from clinical-grade accuracy specialists and component suppliers. Strategic moves concentrate on HITRUST certification acquisition and cloud infrastructure regionalization to satisfy data residency mandates. Partnerships with nurse-call system incumbents accelerate legacy integration timelines.
Within the enterprise platform tier, Zebra Technologies Corporation and HPE Aruba Networking exemplify hardware-software bundling strategies that dominate US health system procurement. CenTrak, Inc. occupies a distinct position as a clinical-grade accuracy specialist serving operating-room workflow digitization in German and Japanese university hospitals. Impinj, Inc. anchors the component supplier archetype through RAIN RFID silicon supply to third-party healthcare OEMs without direct end-user platform competition.
| Leading Market Players |
|---|
| Securitas Healthcare LLC |
| Zebra Technologies Corporation |
| HPE Aruba Networking |
| Impinj, Inc. |
| TeleTracking Technologies, Inc. |
| CenTrak, Inc. |
| Cognosos, Inc. |
| Savi Technology, Inc. |
| GE HealthCare |
| Others |
Pricing and Supply Chain Analysis
Captive integration into RAIN RFID silicon fabrication anchors supply positioning for component suppliers while licensing-based pricing power flows to platform vendors with HITRUST-certified cloud infrastructure. Hospital procurement committees now weight cybersecurity audit costs above raw tag economics, compressing hardware margins while expanding recurring subscription yields.
Pricing Analysis
Margin tightening in hardware tiers reflects lithium cell cost volatility and East Asian export licensing friction. Three-tier pricing structure across enterprise-grade, clinical-accuracy, and community-hospital levels separates vendors by certification depth and integration burden. Cost-down pressure on active RFID tags accelerates because battery supply concentrates in concentrated manufacturing hubs. Mid-sized community hospitals exhibit highest price sensitivity; German university hospitals show lowest due to operating-room workflow digitization mandates.
Supply Chain Analysis
Freight cost escalation from East Asian manufacturing hubs to North American and European health systems compresses landed margins on ceiling-mounted infrastructure. Hardware production concentrates in China, South Korea, and Taiwan; RAIN RFID silicon draws from specialized foundry capacity. Lithium battery cells, ceramic capacitors, and precision ultrasonic transducers constitute critical input dependencies. Single-source vulnerability in rare earth magnet supply for exciter motors threatens production continuity. Distribution runs through hospital GPO contracts and direct enterprise sales teams with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth Low Energy mesh networks are displacing hardwired infrared infrastructure across mid-sized hospitals, compressing deployment timelines from months to weeks. This technology transition rewards modular, API-first platforms over monolithic enterprise suites.
For Market Incumbents: Anchor cloud-native subscription models with HITRUST certification to defend against SaaS-native entrants targeting ambulatory surgery centers. Deepen backward integration into RAIN RFID silicon supply to offset tag cost volatility. Prioritize nurse-call system partnerships to accelerate legacy middleware integration timelines. For New Entrants and Emerging Players: Enter via India's PLI-subsidized greenfield hospital construction corridors in Delhi and Mumbai, where absence of legacy infrastructure removes integration barriers. Target rehabilitation clinic networks consolidating across post-acute care with lightweight SaaS configurations. Lead with departmental clinical engineering sales bypassing centralized IT procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise IT infrastructure vendors seeking healthcare vertical penetration. Long-term viability hinges on recurring revenue share exceeding perpetual license dependency. Target clinical-grade accuracy specialists with German and Japanese university hospital reference sites. Monitor EU AI Act conformity certification velocity as inflection signal for algorithm-enabled patient-flow platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| HITRUST Certification Acquisition | Cybersecurity credentialing satisfies hospital procurement committee requirements above raw tag pricing. |
| Cloud Infrastructure Regionalization | GDPR data residency mandates force vendor edge computing deployment across German and French health systems. |
| Nurse-Call System Partnership | Legacy middleware integration accelerates deployment timelines for proprietary 1990s-installed systems. |
| RAIN RFID Silicon Supply Agreement | Captive component sourcing insulates tag economics from East Asian battery supply volatility. |
| EU AI Act Conformity Pre-Validation | Algorithm bias documentation gains procurement preference in French and Dutch hospital networks. |
Research Methodology
Document review covered FDA UDI guidance documents, HIPAA security rule amendments, EU AI Act implementation texts, and GPO contract databases, complemented by interviews with hospital biomedical engineers, health system procurement committee members, RTLS vendor product managers, and HITRUST certification auditors. Secondary sources included CMS Medicare cost report data, hospital capital expenditure disclosures, and medical device regulatory filings. Bottom-up triangulation across technology segment deployments reconciled with top-down health system IT spending estimates.
Segment-level revenue outputs reflect modeling across signaling protocol, application workflow, delivery mode, and facility type dimensions throughout the forecast period. CAGRs derive from elasticity-adjusted adoption curves calibrated to procurement cycle data and replacement timeline benchmarks. Forecast inputs incorporated surgical suite digitization spend patterns, bond covenant constraints on nonprofit system capital budgets, and lithium battery raw material price indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden export licensing restrictions for East Asian battery cells or accelerated EU AI Act enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Digital Patient Monitoring Systems Market