
 Online Patient Observation Market | 2026-2036
Online Patient Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Online Patient Observation Market Analytics
Modular service bundling is recalibrating how healthcare systems procure online patient observation capabilities. Teladoc Health anchors its position through extensive provider network density across integrated delivery networks. Amwell differentiates by embedding its platform directly into payer and employer workflows. MDLive sustains competitive relevance through specialized behavioral health observation modules that complement general medical offerings.
Online patient observation encompasses continuous or intermittent digital monitoring of patient physiological and behavioral data through connected devices, cloud infrastructure, and clinical decision support algorithms, typically transmitting biometric readings at intervals ranging from real-time streaming to scheduled batch uploads for remote clinical assessment. The primary commercial purpose centers on reducing acute care utilization while maintaining clinical oversight outside traditional facility boundaries. Telehealth Platforms capture the broadest deployment footprint as health systems consolidate point solutions into unified virtual care environments. Wearable Devices represent the fastest-expanding hardware category as FDA-cleared biosensors proliferate for cardiac, respiratory, and metabolic monitoring. Remote Monitoring Systems concentrate margin pools through recurring SaaS fees and data analytics subscriptions that extend beyond initial device provisioning.
The FDA regulates software-as-medical-device classifications for diagnostic algorithms, while CMS reimbursement frameworks determine which observation modalities qualify for provider payment under remote physiologic monitoring codes. HIPAA compliance requirements shape data architecture investments and vendor selection criteria for covered entities handling protected health information across state lines. Stakeholders must monitor evolving state-level telehealth licensure compacts and interstate practice regulations that could either expand or constrain platform addressable markets.
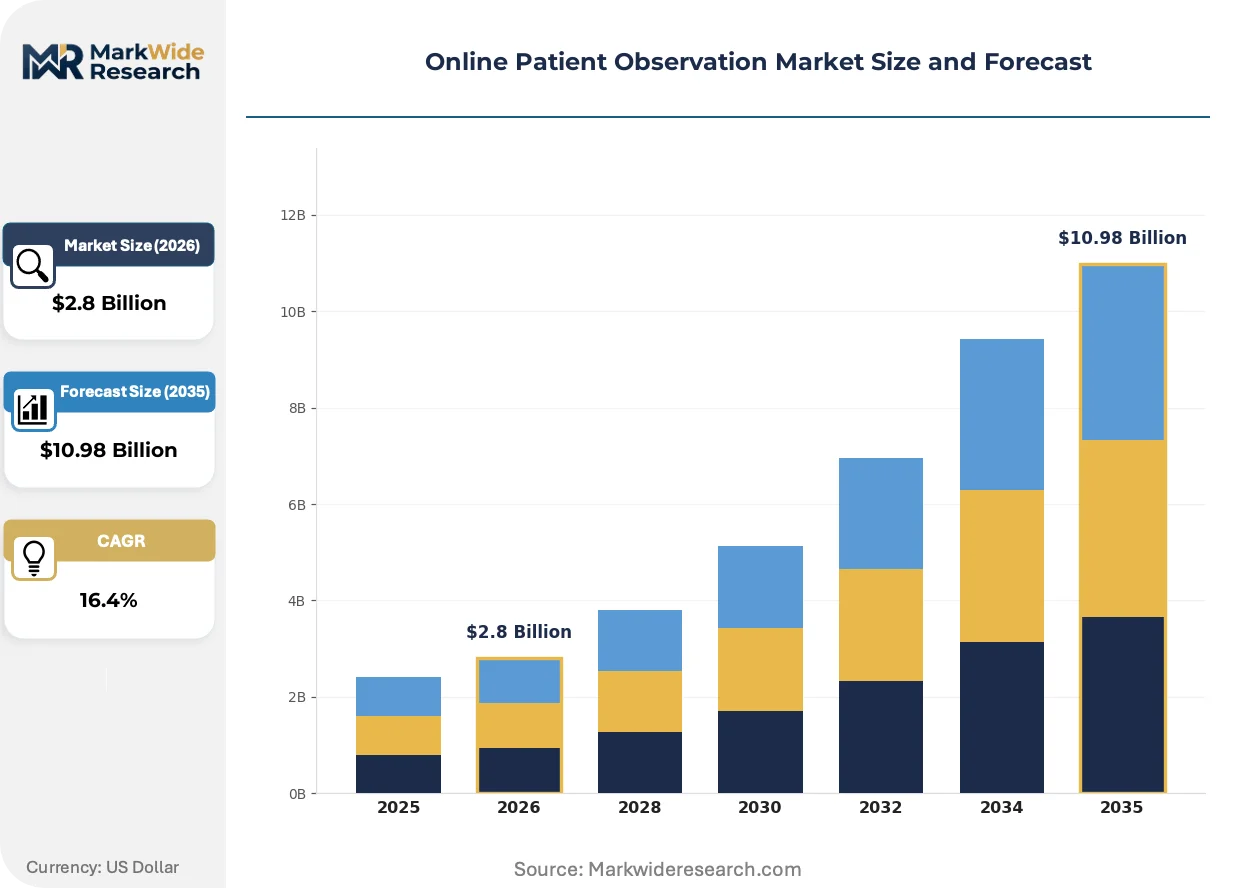
Market Dynamics
CMS reimbursement expansion for remote physiologic monitoring codes is restructuring provider procurement priorities, forcing health systems to consolidate fragmented point solutions into unified virtual care platforms rather than maintaining siloed vendor relationships.
Growth Catalysts
- CMS RPM Reimbursement Expansion:Medicare coverage for continuous glucose monitors and blood pressure cuffs incentivizes hospital systems to deploy connected device fleets for chronic disease cohorts.
- FDA Software-as-Medical-Device Pathway:Streamlined 510(k) clearances for diagnostic algorithms accelerate commercialization timelines for AI-enabled arrhythmia detection and respiratory pattern analysis tools.
- Integrated Delivery Network Consolidation:Hospital mergers across Texas, Florida, and California create captive demand bases requiring standardized remote monitoring infrastructure across multi-state footprints.
Market Restraints
- Interstate Licensure Fragmentation:Absence of universal telehealth compacts forces platforms to maintain redundant clinician credentialing systems across state medical boards, elevating operational overhead.
- Biometric Sensor Supply Concentration:FDA-cleared photoplethysmography modules depend heavily on Taiwanese semiconductor foundries, exposing hardware vendors to geopolitical supply disruption risks.
- Cloud Infrastructure Cost Escalation:HIPAA-compliant data architecture requirements mandate dedicated server instances rather than shared public cloud resources, compressing SaaS margins for mid-tier platform providers.
Strategic Opportunities
- Behavioral Health Integration:Unmet demand for remote psychiatric monitoring and medication adherence tracking creates expansion vectors beyond traditional cardiopulmonary applications.
- EU MDR Convergence:Harmonized medical device regulations across Germany, France, and Netherlands lower market entry barriers for platforms seeking CE marking equivalence with FDA clearances.
- Home Health Agency Partnerships:Direct distribution through visiting nurse associations and home care franchises bypasses hospital procurement committees, accelerating patient onboarding velocity.
Industry Challenges
- Clinical Workflow Integration:Alert fatigue from high-sensitivity monitoring algorithms strains nursing staff capacity, requiring platform vendors to embed triage protocols directly into EHR interfaces.
- Data Interoperability Standards:HL7 FHIR implementation gaps between legacy hospital systems and cloud-native monitoring platforms delay real-time data synchronization, degrading clinical decision support accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Patient Observation Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Remote Monitoring Systems, Telehealth Platforms Technology: IoT, AI, Cloud Computing, Big Data Analytics End User: Healthcare Providers, Patients, Insurance Companies, Pharmacies Application: Chronic Disease Management, Post-Surgery Monitoring, Elderly Care, Mental Health Support |
| Companies Covered | Teladoc Health, Amwell, MDLive, Doxy.me, HealthTap, Lemonaid Health, Zocdoc, Doctor on Demand, Maven Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Patient Observation Market Evolving Landscape
Artificial intelligence inference at the network edge is compressing latency windows for critical event detection, while regulatory harmonization efforts across North America and Europe reshape certification strategies for software vendors.
Edge computing architectures are integrating machine learning models directly into wearable biosensors and home hub devices, enabling local arrhythmia classification and fall detection without continuous cloud connectivity. Rural health systems in Montana and Alaska are deploying these capabilities to overcome broadband infrastructure gaps. The shift is integrating clinical-grade diagnostics into consumer form factors, blurring procurement categories between medical devices and wellness electronics.
FDA's evolving guidance on predetermined change control plans permits algorithm updates without supplemental 510(k) submissions, reducing regulatory friction for adaptive AI models. European regulators through MDR Article 120 transitional provisions are synchronizing software qualification thresholds with US predicates. Cardiac monitoring platforms with dual-jurisdiction clearances are capturing disproportionate health system attention as procurement teams prioritize regulatory durability.
Health system purchasing committees are consolidating vendor relationships around platforms offering modular service bundling across telehealth, remote monitoring, and asynchronous messaging. Single-point solutions for diabetes management or hypertension tracking face displacement as integrated delivery networks negotiate enterprise-wide contracts spanning multiple chronic conditions. This concentration is most visible in California and New York, where Kaiser Permanente and Northwell Health have standardized on unified virtual care stacks.
Online Patient Observation Market Segmentation
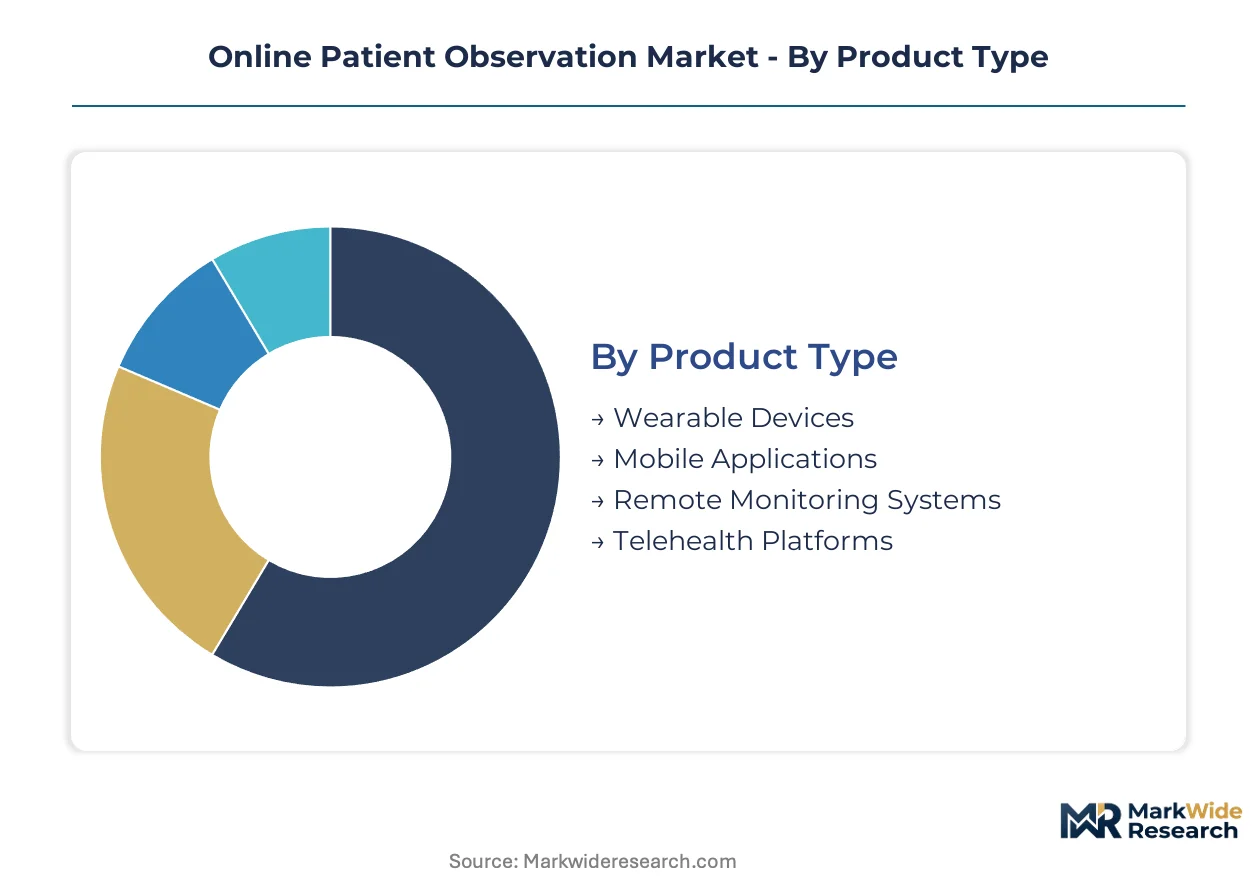
Segmentation in online patient observation reveals distinct certification pathways and procurement economics across hardware, software, and service layers. Hospital purchasing committees evaluate segments through divergent lenses: FDA clearance requirements for devices versus HIPAA compliance burdens for platforms.
Product Type:
FDA 510(k) clearances dominate hardware segments while software categories navigate HIPAA and state-level telehealth licensure. CE marking under EU MDR creates secondary compliance tracks for vendors pursuing dual-jurisdiction strategies.
- Telehealth Platforms:Unified virtual care environments consolidate video consultation, asynchronous messaging, and EHR integration into single-vendor relationships. Kaiser Permanente and Northwell Health have standardized procurement around these stacks, displacing point solutions for diabetes or hypertension management.
- Wearable Devices:FDA-cleared photoplethysmography modules and continuous glucose monitors transmit biometric data at intervals from real-time streaming to scheduled batch uploads. Supply concentration in Taiwanese semiconductor foundries exposes hardware vendors to geopolitical disruption risks.
- Remote Monitoring Systems:Recurring SaaS fees and data analytics subscriptions extend revenue beyond initial device provisioning.
- Mobile Applications:Patient-facing interfaces for medication adherence and symptom tracking require less stringent regulatory pathways than diagnostic hardware.
Telehealth Platforms sit at the top of the volume ranking, with Wearable Devices climbing the fastest.
Technology:
Cost tiers separate infrastructure-heavy deployments from algorithmic layers that leverage existing cloud capacity. Capital intensity varies tenfold between edge hardware and pure software implementations.
- AI:Machine learning models for arrhythmia detection and respiratory pattern analysis now deploy at the network edge, enabling local inference without continuous cloud connectivity. FDA's predetermined change control plans permit algorithm updates without supplemental 510(k) submissions, reducing regulatory friction for adaptive models.
- IoT:Connected biosensors and home hub devices integrate clinical-grade diagnostics into consumer form factors, blurring procurement categories between medical devices and wellness electronics. Rural health systems in Montana and Alaska deploy these capabilities to overcome broadband infrastructure gaps.
- Cloud Computing:HIPAA-compliant data architecture mandates dedicated server instances rather than shared public cloud resources.
- Big Data Analytics:Population health dashboards aggregate cohort-level trends for health system administrators.
Cloud Computing commands the largest installed base, though AI is expanding most quickly as health systems prioritize predictive capabilities.
End User:
Customer type determines pricing structure and contract duration. Institutional buyers negotiate enterprise terms while individual patients drive direct-to-consumer subscription models.
- Healthcare Providers:Hospitals and integrated delivery networks procure through multi-year enterprise agreements spanning telehealth, remote monitoring, and chronic disease management. CMS reimbursement for remote physiologic monitoring codes directly influences procurement priority and scale.
- Patients:Direct-to-consumer channels bypass hospital procurement committees, with visiting nurse associations and home care franchises accelerating onboarding velocity for elderly and post-surgical cohorts.
- Insurance Companies:Payers embed observation platforms into member benefit designs to reduce acute care utilization.
- Pharmacies:Retail health locations deploy observation tools for medication adherence programs and chronic condition screening.
Healthcare Providers represent the dominant revenue concentration, with Patients gaining share fastest through direct-to-consumer channels.
Application:
Maturity levels vary across clinical domains, with cardiopulmonary monitoring achieving standard-of-care status while behavioral health applications remain underpenetrated.
- Chronic Disease Management:Continuous glucose monitors and connected blood pressure cuffs target diabetes and hypertension cohorts with established reimbursement pathways. Medicare coverage expansion incentivizes hospital systems to deploy connected device fleets at scale.
- Mental Health Support:Remote psychiatric monitoring and medication adherence tracking address unmet demand beyond traditional cardiopulmonary applications. MDLive sustains competitive relevance through specialized behavioral health observation modules.
- Post-Surgery Monitoring:Discharge-to-home protocols reduce readmission penalties through remote vital sign surveillance.
- Elderly Care:Fall detection and activity monitoring support aging-in-place initiatives for Medicare Advantage populations.
Chronic Disease Management sits at the top of the volume ranking, with Mental Health Support climbing the fastest as reimbursement frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The online patient observation industry traces its commercial roots to early telemedicine pilots in the United States during the 2010s, where integrated delivery networks first tested remote monitoring for cardiac patients. Medicare reimbursement policies subsequently codified these programs, establishing the regulatory and payment infrastructure that other jurisdictions later adapted.
United States
CMS remote physiologic monitoring codes now cover continuous glucose monitors and blood pressure cuffs, driving hospital procurement at scale. The FDA's predetermined change control plans for AI diagnostic algorithms reduce regulatory friction for adaptive software updates. Kaiser Permanente in California and Northwell Health in New York have standardized enterprise-wide virtual care stacks, consolidating previously fragmented point solutions.
Germany
EU MDR Article 120 transitional provisions synchronize software qualification thresholds with FDA predicates, easing dual-jurisdiction certification for cardiac monitoring platforms. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, actively coordinates with notified bodies on digital health pathways. Berlin-Brandenburg hosts emerging health tech clusters where platforms pursue CE marking equivalence to access reimbursement schemes.
United Kingdom
NHS England's remote monitoring programs for chronic disease management create institutional demand for integrated telehealth infrastructure. The Medicines and Healthcare products Regulatory Agency maintains alignment with FDA software-as-medical-device classifications through mutual recognition workarounds. London's health tech corridor concentrates vendor activity around NHS procurement frameworks and digital health accelerators.
Japan
The Ministry of Health, Labour and Welfare expanded reimbursement for online patient observation in 2023, targeting rural aging populations with limited access to tertiary centers. The Pharmaceuticals and Medical Devices Agency streamlined approval pathways for AI-enabled diagnostic algorithms used in remote cardiac monitoring. Tokyo and Osaka metropolitan areas concentrate platform development partnerships between domestic electronics manufacturers and hospital systems.
India
The Central Drugs Standard Control Organization issued guidance documents for software-as-medical-device classifications in 2022, clarifying regulatory pathways for remote monitoring platforms. Telemedicine practice guidelines from the national medical commission enable interstate consultation frameworks that reduce credentialing overhead. Karnataka and Maharashtra host health tech clusters where platforms target direct-to-consumer channels for diabetes and hypertension management.
Online Patient Observation Market Competitive Landscape
The competitive structure tilts toward platform consolidators with established provider network density. Health systems increasingly favor unified virtual care environments over fragmented point solutions, concentrating procurement decisions around vendors offering modular service bundling. Two strategic archetypes dominate: integrated telehealth platforms spanning multiple chronic conditions, and specialized behavioral health modules complementing general medical offerings. Competitive moves center on enterprise contract negotiations with integrated delivery networks and direct distribution partnerships with home health agencies.
Among the named platform providers, Teladoc Health and Amwell exemplify the integrated consolidator archetype, while MDLive occupies a position within specialized behavioral health observation. These three companies anchor different vectors of competitive differentiation—provider network density, payer workflow embedding, and psychiatric monitoring specialization respectively. The vendor set includes additional telehealth platforms, direct-to-consumer services, and appointment scheduling intermediaries that compete for overlapping patient populations through distinct channel strategies.
| Leading Market Players |
|---|
| Teladoc Health |
| Amwell |
| MDLive |
| Doxy.me |
| HealthTap |
| Lemonaid Health |
| Zocdoc |
| Doctor on Demand |
| Maven Clinic |
| Others |
Value Network & Pricing Analysis
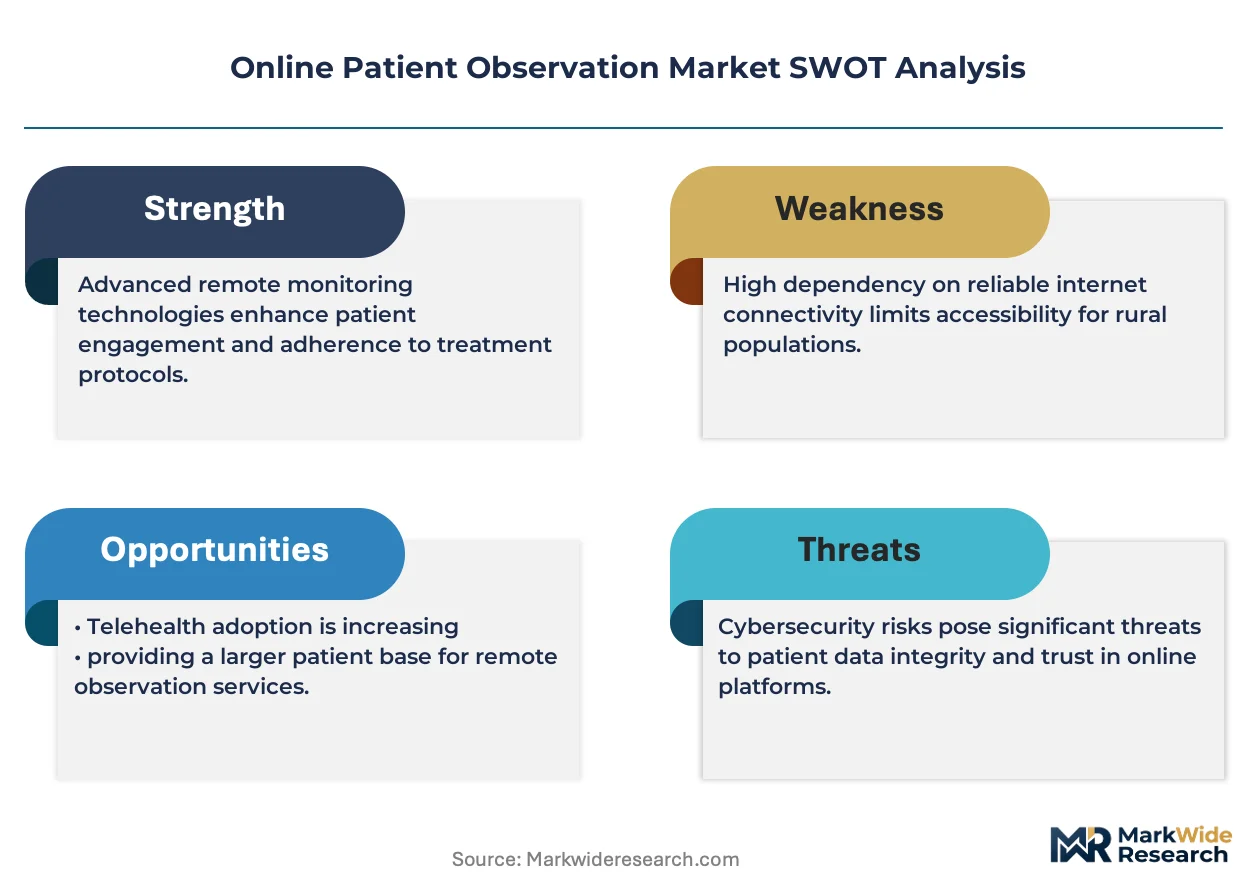
Photoplethysmography sensor module pricing indices from Taiwanese foundries cascade through hardware tiers into three-tier pricing structures across premium FDA-cleared, standard CE-marked, and economy wellness-grade observation devices. Hospital procurement committees leverage volume scale to compress SaaS margins while cloud infrastructure costs for HIPAA-compliant dedicated instances reshape platform provider pricing strategies.
Pricing Analysis
Subscription-based SaaS tiering with per-patient-per-month fees dominates platform revenue models, separating enterprise health system contracts from direct-to-consumer subscriptions. Price differentiation hinges on FDA 510(k) clearance grade and EHR integration depth, with premium tiers commanding substantial markups for algorithmic diagnostic capabilities. Cost compression in mid-tier SaaS offerings is intensifying because cloud infrastructure providers mandate dedicated server instances for HIPAA compliance. Health systems with captive patient populations exhibit lowest price sensitivity, while individual patients through direct-to-consumer channels drive hardest bargain negotiations.
Supply Chain Analysis
FDA-cleared photoplethysmography modules rest on Taiwanese semiconductor foundries, South Korean display panel manufacturers, and Chinese battery cell producers for wearable device assembly. Raw material dependencies span silicon wafers, lithium-ion cells, and medical-grade polymers for biocompatible housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for specialized biosensor chips. Distribution runs through hospital procurement committees for institutional sales and visiting nurse associations for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The online patient observation market functions as a regulatory compounder where CMS reimbursement expansion for remote physiologic monitoring codes directly structures demand trajectories and procurement priorities across health system buyers.
For Market Incumbents: To counter platform consolidation pressure from integrated delivery networks, anchor enterprise contracts through modular service bundling spanning telehealth, remote monitoring, and behavioral health modules. Deepen backward integration into FDA-cleared hardware manufacturing to capture margin pools beyond SaaS fees and reduce exposure to Taiwanese foundry supply concentration. For New Entrants and Emerging Players: Home health agencies offer the most penetrable channel partner type for bypassing hospital procurement committee gatekeeping and accelerating patient onboarding velocity. Target behavioral health observation modules where unmet demand exceeds cardiopulmonary market saturation. Pursue direct-to-consumer subscription models through visiting nurse association partnerships for elderly and post-surgical cohorts. For Investors and Strategic Acquirers: Consolidation pressure builds where health systems standardize on unified virtual care stacks and displace fragmented point solutions. Long-term viability favors platforms with dual-jurisdiction FDA and EU MDR clearances that reduce regulatory friction across North American and European reimbursement schemes. Watch CMS reimbursement code expansion breadth as the critical inflection signal for platform addressable market scaling.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance for AI-enabled arrhythmia algorithms unlocks Medicare reimbursement and hospital procurement eligibility. |
| CE Marking Equivalence Strategy | EU MDR Article 120 alignment with FDA predicates reduces dual-jurisdiction certification costs for cardiac platforms. |
| Hospital System Partnership | Enterprise contracts with Kaiser Permanente or Northwell Health displace fragmented point solutions through standardization. |
| Software Companion Development | FDA predetermined change control plans permit adaptive algorithm updates without supplemental submissions. |
| Reimbursement Strategy | CMS remote physiologic monitoring code coverage directly determines platform procurement priority and deployment scale. |
Research Methodology
Bottom-up health system procurement modeling reconciled against top-down platform deployment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and telehealth platform executives combined with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance filings, and hospital procurement contract disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side capacity disclosures.
Input-output matrices segment volume and value across product type, technology layer, end-user archetype, and clinical application domain throughout the forecast period. CAGRs derive from regression analysis against reimbursement policy trajectories, health system consolidation patterns, and semiconductor supply capacity expansion. Forecast inputs incorporate CMS code coverage expansion schedules and EU MDR transitional provision timelines for software-as-medical-device classifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interstate telehealth licensure compact adoption, Taiwanese foundry supply disruption, and CMS reimbursement code modification. Assumptions underlying projections reflect documented regulatory trajectories and health system consolidation patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
South Korea Patient Monitoring Market