
 Asia-Pacific Syndromic Multiplex Diagnostic Market | 2026-2036
Asia-Pacific Syndromic Multiplex Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Syndromic Multiplex Diagnostic Market Outlook
Hospital-based reference laboratories is redrawing procurement priorities across the Asia-Pacific Syndromic Multiplex Diagnostic Market, displacing smaller clinic buyers as the dominant volume segment. Thermo Fisher Scientific anchors its position through captive supply of PCR thermal cyclers and reagent ecosystems across Chinese provincial hospital networks. QIAGEN differentiates via automated sample-to-answer platforms that reduce technician training burdens in Japan's METI-funded diagnostic modernization programs. Abbott Laboratories competes through point-of-care compatibility, extending its installed base into Southeast Asian district hospitals with limited laboratory infrastructure.
Asia-Pacific syndromic multiplex diagnostics combine nucleic acid amplification with parallel pathogen detection, typically targeting fifteen to thirty genetic or protein biomarkers within a single cartridge or microfluidic chip to deliver differential diagnosis in under two hours. The technology serves infectious disease management by collapsing serial single-target testing into one workflow, reducing empiric antibiotic prescription and isolation bed occupancy in acute care settings. Cartridge-based systems command premium positioning in high-throughput hospital laboratories where workflow integration and contamination control justify higher per-test costs. PCR technology dominates current installed capacity, though NGS-based syndromic panels capture growing interest from Australia's public health reference laboratories for outbreak surveillance and novel pathogen discovery.
Japan's PMDA and Australia's TGA enforce stringent analytical validation requirements for multiplex claims, creating compliance moats that favor established manufacturers with dedicated regulatory affairs teams in Tokyo and Canberra. China's NMPA has streamlined innovative device review channels under revised Class III diagnostic regulations, accelerating market access for validated syndromic platforms while maintaining post-market adverse event surveillance. India's CDSCO aligns with ICMR guidelines to mandate quality control standards for imported multiplex reagents, shaping procurement specifications at AIIMS-affiliated networks and state-level medical college hospitals. Stakeholders must monitor divergent premarket evidence requirements across these three regulatory jurisdictions when prioritizing product registration sequencing and clinical trial site selection.
Market Dynamics
Centralized hospital laboratory procurement is consolidating purchasing authority across Asia-Pacific diagnostic networks, compressing vendor margins while elevating workflow integration and contamination-control specifications as decisive selection criteria.
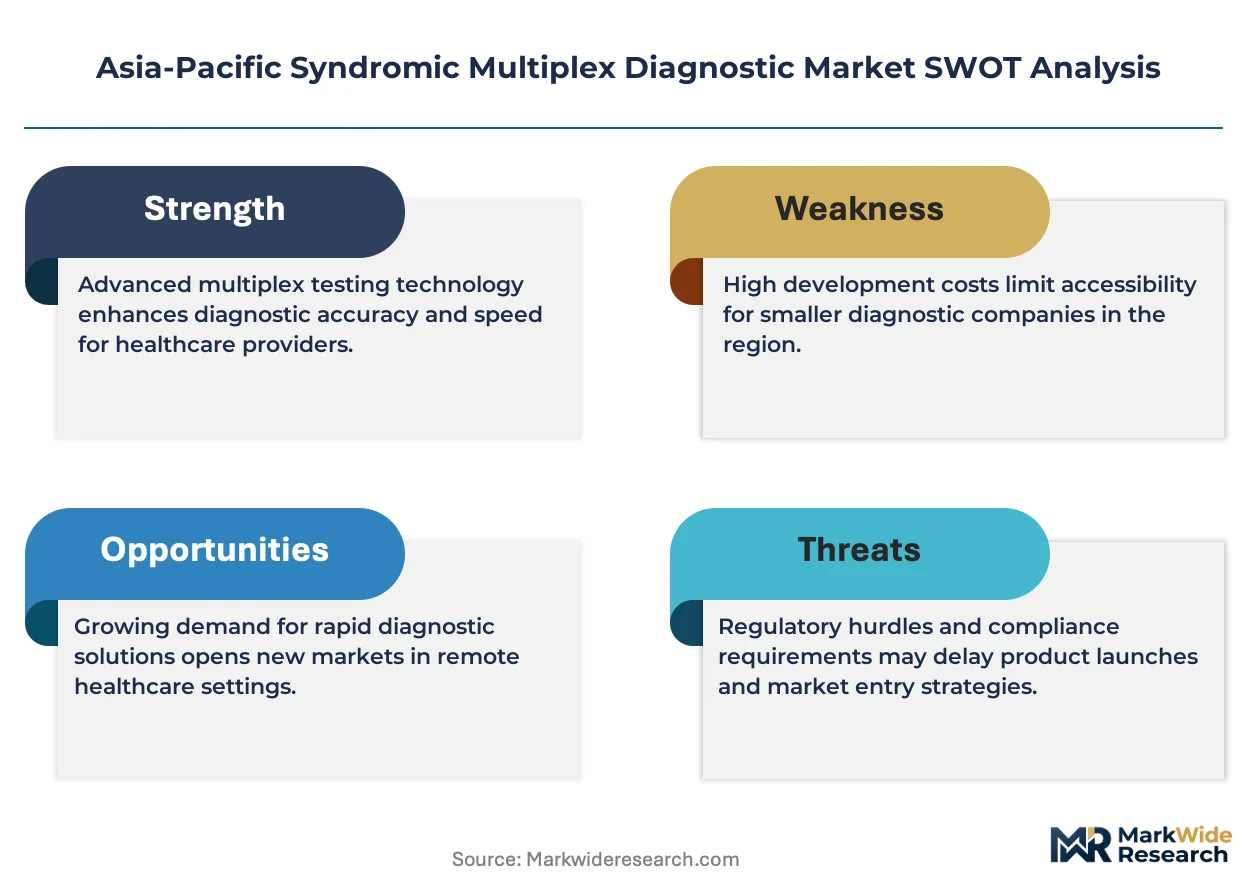
Growth Catalysts
- Japan's METI-funded diagnostic modernization:Government subsidies for automated sample-to-answer platforms accelerate replacement of manual PCR workflows in prefectural hospital networks.
- CDSCO streamlined Class C/D review:India's compressed regulatory timelines for imported multiplex reagents reduce market entry barriers for validated syndromic assays targeting AIIMS-affiliated reference laboratories.
- Cartridge-based microfluidics:Closed-system architectures eliminate cross-contamination risks in high-throughput Chinese provincial hospitals managing respiratory outbreak surges.
Market Restraints
- PCR thermal cycler supply concentration:Dependence on single-source optical component suppliers from South Korean semiconductor fabs creates instrument production bottlenecks.
- PMDA analytical validation burden:Japan's requirement for 300+ specimen clinical studies per syndromic panel claim extends registration timelines and elevates compliance costs for novel biomarker combinations.
- NGS platform substitution threat:Next-generation sequencing systems with metagenomic capabilities capture outbreak surveillance contracts from Australia's public health reference laboratories.
Strategic Opportunities
- Southeast Asian district hospitals:Point-of-care compatible syndromic platforms address infrastructure gaps in Indonesian and Vietnamese provincial health networks lacking centralized laboratory capacity.
- Respiratory-gastrointestinal combined panels:Convergent pathogen detection addresses co-infection complexity in India's pediatric intensive care units and elderly care facilities.
- China's NMPA innovative device channel:Expedited Class III review for breakthrough diagnostic technologies accelerates commercialization timelines for novel host-response biomarker integrations.
Industry Challenges
- Molecular diagnostics technician scarcity:Shortages of trained PCR operators in Australia's regional pathology services constrain instrument utilization rates and extend turnaround times.
- Legacy LIS integration complexity:Proprietary data formats from established hospital information system vendors in Japan complicate middleware development for automated result reporting.
- Reagent cold chain integrity:Temperature excursion risks during last-mile distribution to Indonesian archipelago facilities degrade assay performance and trigger quality control failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Syndromic Multiplex Diagnostic Market |
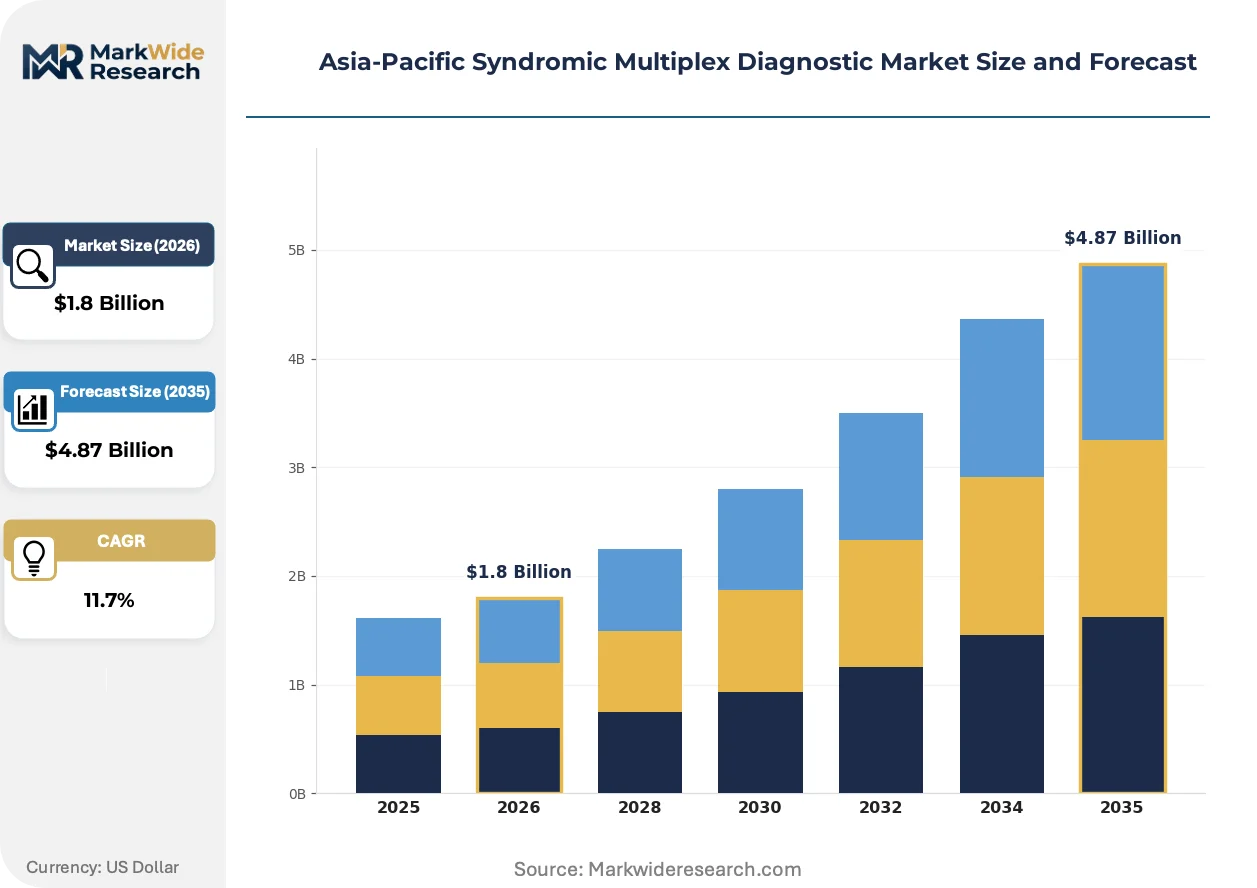
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridge-Based, Microfluidic Chips, Reagents, Software End User: Hospitals, Laboratories, Clinics, Point-of-Care Testing Technology: PCR, NGS, Mass Spectrometry, Lateral Flow Assays Application: Infectious Disease, Respiratory Infections, Gastrointestinal Disorders, Others |
| Companies Covered | bioMérieux, Luminex Corporation, QIAGEN, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, DiaSorin, Becton Dickinson, Applied BioCode, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Syndromic Multiplex Diagnostic Market Strategic Shifts
Multiplex diagnostic architectures are converging with artificial intelligence-enabled result interpretation, compressing the diagnostic pathway from sample acquisition to clinical decision while elevating analytical specificity requirements.
CRISPR-Cas12a-based nucleic acid detection is supplanting conventional qPCR in research-use syndromic panels, offering amplification-free pathogen identification with reduced thermal cycling infrastructure. Australian public health laboratories are piloting these platforms for field-deployable outbreak investigation. The technology is compressing instrument footprint requirements and enabling testing in non-traditional laboratory environments.
China's NMPA revised Class III diagnostic regulations under the 2021 Medical Device Law have established conditional approval pathways for urgently needed infectious disease assays. Manufacturers with established quality management systems in Shanghai and Beijing regulatory consulting networks are exploiting accelerated review channels. Domestic innovators with localized clinical trial sites capture priority review status over foreign competitors.
Reference laboratory procurement committees are consolidating vendor relationships from multi-supplier fragmentation toward single-source ecosystem contracts. Thermo Fisher Scientific and QIAGEN are restructuring sales organizations around annual reagent rental agreements with Chinese tier-one hospital networks. This concentration is most visible in Shanghai and Guangdong provincial health systems where integrated instrument-reagent-service bundles displace transactional cartridge purchasing.
Asia-Pacific Syndromic Multiplex Diagnostic Market Segmentation
Channel architecture dictates how syndromic multiplex diagnostics reach clinical decision-makers across the Asia-Pacific. Procurement pathways bifurcate between centralized hospital laboratory contracts and distributed point-of-care placements, with each channel imposing distinct technical specifications and margin structures on segment performance.
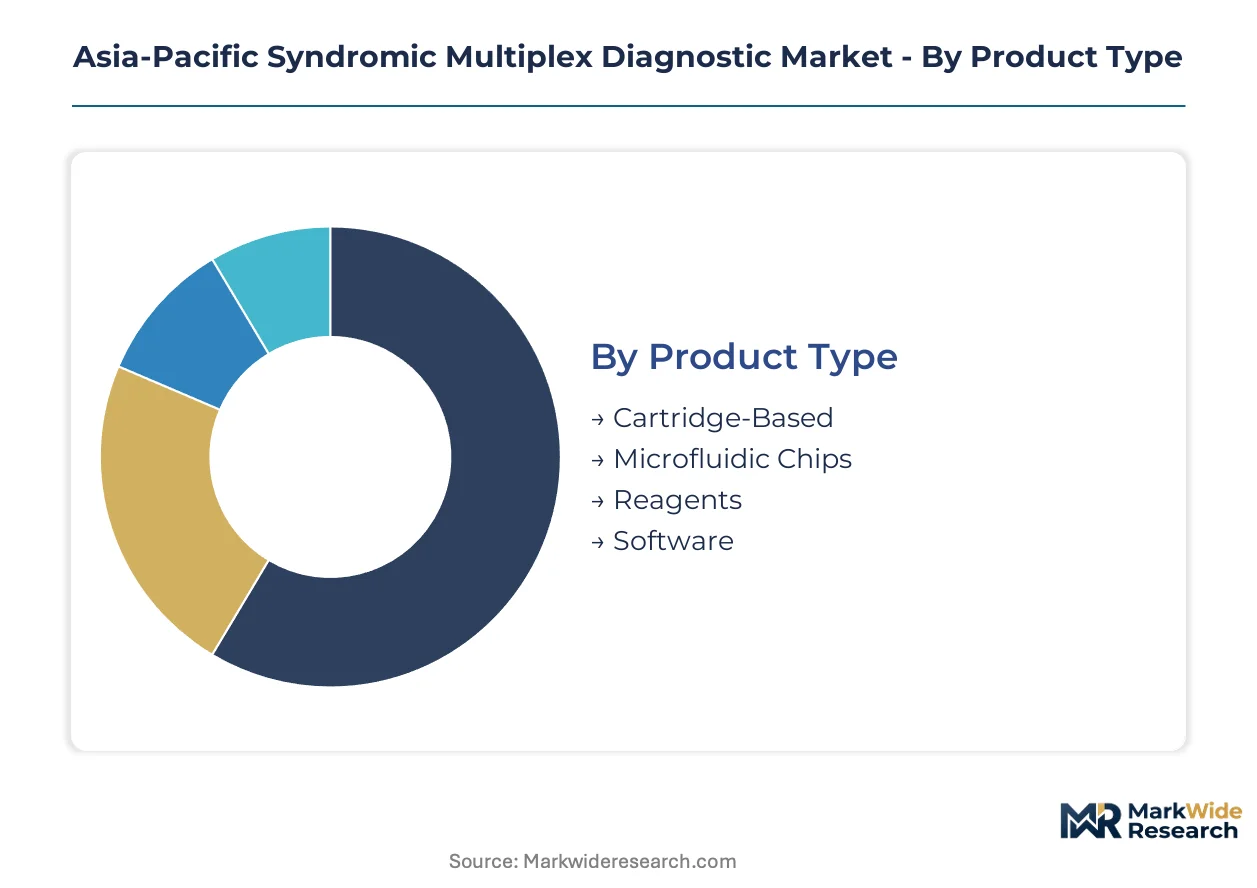
Product Type:
Cartridge-based systems and microfluidic chips flow through divergent distribution channels, with closed-system architectures dominating tier-one hospital tenders while open-platform reagents capture reference laboratory volume.
- Cartridge-Based:Closed-system consumables integrate sample preparation, amplification, and detection within single-use cassettes. Demand concentrates in China's provincial hospital networks and Australia's public reference laboratories, where contamination control and workflow standardization justify premium positioning.
- Microfluidic Chips:Miniaturized fluidic circuits enable parallel pathogen detection on credit-card-sized substrates. Japanese prefectural hospitals under METI modernization programs are adopting these platforms to reduce technician training burdens and instrument footprint requirements.
- Reagents:Bulk amplification chemistries and detection probes serve laboratories with existing thermal cycler infrastructure across India and Southeast Asia.
- Software:Algorithmic result interpretation and laboratory information system middleware address integration complexity in Japan's legacy hospital networks.
By volume, reagents lead due to installed base expansion. By growth pace, cartridge-based systems are climbing the fastest as procurement consolidates around integrated ecosystem contracts.
End User:
Customer-type concentration reveals a structural shift from fragmented clinic purchasing toward consolidated hospital authority, with implications for vendor salesforce deployment and technical support requirements.
- Hospitals:Centralized laboratory procurement committees across Chinese tier-one networks and Australian public health systems now control the majority of syndromic panel volume. These buyers prioritize workflow integration, contamination control, and annual reagent rental agreements over transactional purchasing.
- Laboratories:Reference and pathology services in Japan and Australia drive demand for high-throughput, automated sample-to-answer platforms with sophisticated data management capabilities.
- Clinics:Smaller diagnostic facilities in India and Southeast Asia remain price-sensitive buyers, though their procurement influence is diminishing relative to hospital networks.
- Point-of-Care Testing:District hospitals and emergency departments across Indonesia and Vietnam with limited laboratory infrastructure require instrument-minimal, rapid-turnaround solutions.
By installed base, hospitals dominate. By expansion trajectory, point-of-care testing is gaining share fastest as vendors target infrastructure gaps in Southeast Asian provincial health networks.
Technology:
Technology selection reflects a maturity gradient, with PCR commanding current capacity and NGS capturing surveillance-oriented applications requiring novel pathogen discovery capabilities.
- PCR:Quantitative amplification remains the workhorse technology across Chinese provincial hospitals and Indian reference laboratories, supported by extensive installed bases of thermal cyclers and standardized technician training protocols.
- NGS:Next-generation sequencing platforms with metagenomic capabilities are displacing multiplex PCR for outbreak surveillance contracts in Australia's public health reference laboratories.
- Mass Spectrometry:Matrix-assisted laser desorption platforms enable rapid protein-based pathogen identification in specialized Japanese research hospitals.
- Lateral Flow Assays:Immunochromatographic strip tests address cost-constrained screening applications in rural Indian and Southeast Asian settings.
By deployment scale, PCR leads. By capability expansion, NGS is advancing most quickly as public health agencies prioritize genomic surveillance infrastructure.
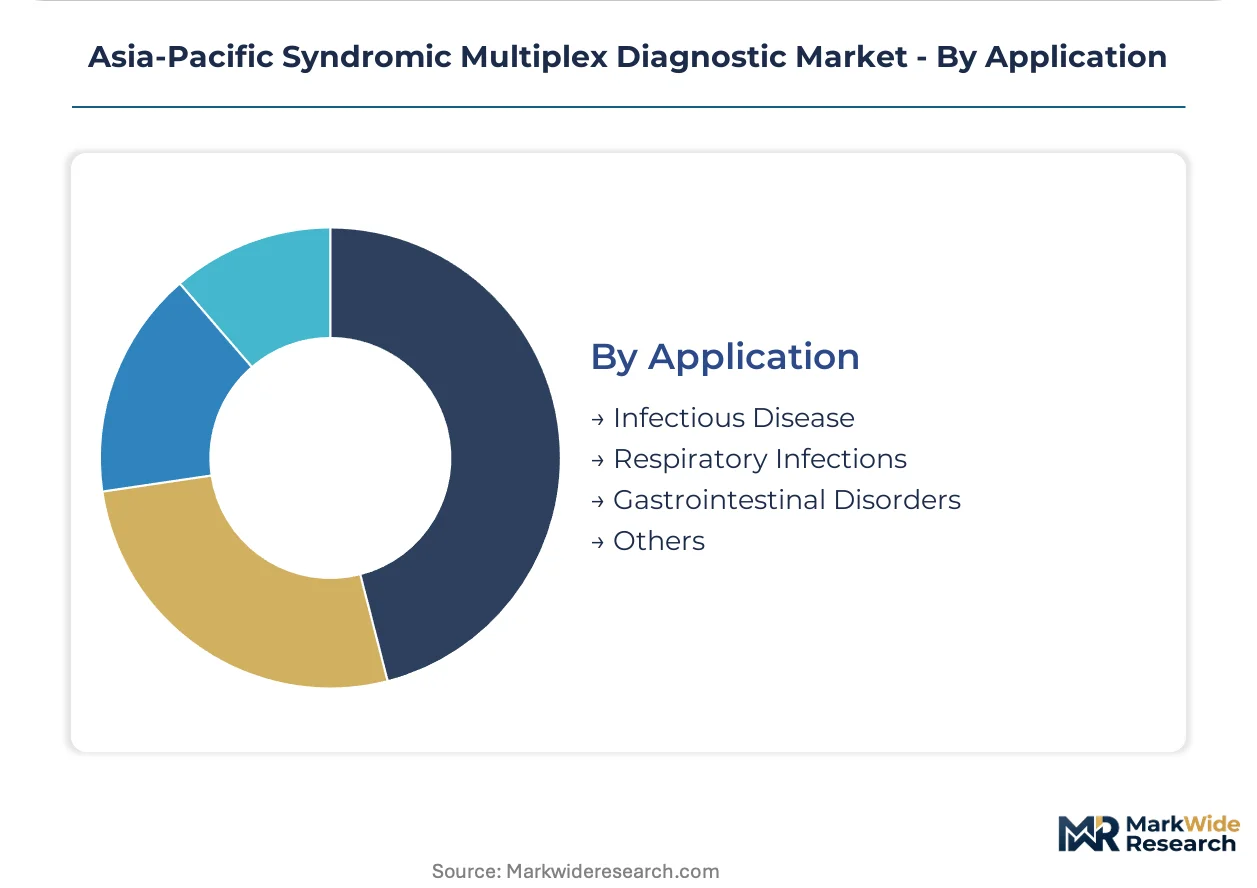
Application:
Application demand patterns track disease burden and reimbursement alignment, with respiratory panels capturing outbreak-responsive volume and gastrointestinal assays addressing endemic pathogen prevalence.
- Infectious Disease:Broad-spectrum syndromic panels targeting fever of unknown origin serve emergency departments and intensive care units across Chinese tier-one hospitals, where rapid differential diagnosis reduces empiric antibiotic prescription.
- Respiratory Infections:Multi-pathogen panels detecting viral and bacterial co-infections concentrate procurement in Australian public reference laboratories and Japanese prefectural hospitals managing seasonal outbreak surges.
- Gastrointestinal Disorders:Enteric pathogen panels address high endemic burden in Indian pediatric intensive care units and elderly care facilities.
- Others:Emerging applications including bloodstream infection and central nervous system pathogen detection remain limited to specialized reference centers.
By test volume, respiratory infections lead. By clinical priority elevation, gastrointestinal disorders are expanding most rapidly as antimicrobial stewardship programs intensify focus on enteric pathogen management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific region's diagnostic supply chains pivot on Shanghai's Yangshan Deep Water Port, which handles temperature-controlled reagent imports for Chinese tier-one hospital networks and redistributes cartridge-based systems across East and Southeast Asian markets.
China
Provincial hospital networks in Shanghai and Guangdong drive cartridge-based system procurement through centralized annual reagent rental agreements. NMPA's 2021 Medical Device Law established conditional approval pathways that accelerate Class III diagnostic registrations for validated syndromic platforms. Beijing-Tianjin-Hebei medical clusters prioritize closed-system architectures that eliminate cross-contamination risks during respiratory outbreak surges.
Japan
Prefectural hospitals under METI-funded diagnostic modernization programs demand automated sample-to-answer platforms that reduce technician training burdens. PMDA enforces stringent analytical validation requirements requiring 300-plus specimen clinical studies per syndromic panel claim, extending registration timelines for novel biomarker combinations. Kansai region medical centers in Osaka anchor high-throughput installations with sophisticated data management capabilities.
India
AIIMS-affiliated reference laboratories and state-level medical college hospitals concentrate procurement of imported multiplex reagents following CDSCO's streamlined Class C/D review timelines. ICMR-mandated quality control standards shape procurement specifications at central government hospital networks. Maharashtra's Mumbai-Pune corridor hosts the densest concentration of molecular diagnostics infrastructure serving pediatric intensive care units.
Australia
Public health reference laboratories in New South Wales and Victoria drive NGS platform adoption for outbreak surveillance and novel pathogen discovery applications. TGA's analytical validation requirements create compliance moats favoring manufacturers with dedicated regulatory affairs teams in Canberra. Sydney's research hospital clusters pilot CRISPR-Cas12a-based detection platforms for field-deployable outbreak investigation.
Southeast Asia
Indonesian and Vietnamese district hospitals with limited laboratory infrastructure require point-of-care compatible syndromic platforms addressing infrastructure gaps in provincial health networks. Reagent cold chain integrity challenges during last-mile distribution to Indonesian archipelago facilities degrade assay performance and trigger quality control failures. Jakarta and Ho Chi Minh City medical centers anchor pilot programs for rapid-turnaround emergency department testing.
Asia-Pacific Syndromic Multiplex Diagnostic Market Competitive Environment
Concentration sits with diversified life science conglomerates and specialized molecular diagnostics firms that control thermal cycler installed bases and reagent ecosystems. The market structure tilts toward consolidated procurement relationships where Chinese tier-one hospital networks and Australian public reference laboratories negotiate multi-year ecosystem contracts. Two strategic archetypes dominate: integrated instrument-reagent-service providers and point-of-care platform specialists. Competitive moves center on backward integration into optical component supply and geographic expansion into Southeast Asian district hospital networks.
Among diversified diagnostics conglomerates, bioMérieux, QIAGEN, and Thermo Fisher Scientific occupy positions that exemplify the integrated ecosystem archetype. bioMérieux represents French multinational presence with established quality management systems. QIAGEN anchors German-origin automated platform specialization. Thermo Fisher Scientific exemplifies American-scale captive supply of PCR thermal cyclers and reagent ecosystems. These three sit within the premium tier where annual reagent rental agreements displace transactional cartridge purchasing across Chinese provincial health systems.
| Leading Market Players |
|---|
| bioMérieux |
| Luminex Corporation |
| QIAGEN |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| DiaSorin |
| Becton Dickinson |
| Applied BioCode |
| Others |
Value Chain & Pricing Dynamics
Annual reagent rental agreements lock in supply access and price visibility for Chinese tier-one hospital networks negotiating multi-year ecosystem contracts with integrated instrument-reagent-service providers. These structures compress transactional flexibility while embedding contamination-control specifications and workflow integration requirements into contracted cost baselines across Shanghai and Guangdong provincial health systems.
Pricing Analysis
Volume-discount tiering separates closed-system cartridge premiums from open-platform reagent economies across procurement committees. Three-tier pricing structure across premium, standard, and economy levels reflects ISO certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian state-level medical college hospitals prioritize lowest per-test costs over workflow integration. Smaller clinics in Southeast Asian district hospitals exhibit highest price sensitivity; Australian public reference laboratories show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate Japanese prefectural hospitals under METI-funded modernization, while just-in-time inventory management prevails in China's tier-one networks with reliable cold chain infrastructure. Optical component supply draws from South Korean semiconductor fabs, Japanese precision manufacturers, and German optical engineering centers. Single-source vulnerability concentrates in South Korean fab capacity for PCR thermal cycler production. Temperature excursion risks during last-mile distribution to Indonesian archipelago facilities degrade reagent integrity. Distribution runs through Shanghai's Yangshan Deep Water Port for temperature-controlled redistribution across East and Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained PCR operator scarcity constrains instrument utilization rates across Australia's regional pathology services and India's state-level medical college hospitals, creating a capability bottleneck that shapes competitive outcomes. This skills gap elevates automated sample-to-answer platforms that reduce technician training burdens.
For Market Incumbents: Consolidate captive supply of thermal cycler optical components through backward integration into South Korean semiconductor fab partnerships or capacity reservation agreements. Deepen annual reagent rental penetration across Chinese provincial hospital networks before NGS platform substitution accelerates in Australian public health reference laboratories. Prioritize middleware development for legacy LIS integration in Japan's hospital information system environments. For New Entrants and Emerging Players: Point-of-care service-layer gaps in Indonesian and Vietnamese district hospitals offer white-space entry where centralized laboratory infrastructure remains underdeveloped. Target respiratory-gastrointestinal combined panels for India's pediatric intensive care units where co-infection complexity exceeds incumbent assay breadth. Pursue CDSCO Class C/D registration for imported multiplex reagents to capture AIIMS-affiliated reference laboratory procurement cycles. For Investors and Strategic Acquirers: Automated platform specialists with established PMDA quality management systems in Tokyo represent priority acquisition targets given Japan's 300-plus specimen clinical study requirements that extend registration timelines for unvalidated entrants. Long-term viability hinges on ecosystem contract density rather than transactional cartridge volume. Watch NGS platform adoption rates in Australian public health laboratories as inflection indicator for PCR displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Quality Management System Establishment | Tokyo-based regulatory affairs teams compress registration timelines for novel syndromic panel claims under stringent validation requirements. |
| NMPA Innovative Device Channel Registration | Shanghai and Beijing consulting networks accelerate Class III diagnostic approvals for urgently needed infectious disease assays. |
| Backward Integration into Optical Component Supply | South Korean semiconductor fab partnerships reduce production bottlenecks for PCR thermal cycler manufacturing. |
| Point-of-Care Platform Deployment | Southeast Asian district hospitals with limited laboratory infrastructure require instrument-minimal rapid-turnaround solutions. |
| NGS Platform Surveillance Contract Capture | Australian public health reference laboratories prioritize metagenomic capabilities for outbreak investigation and novel pathogen discovery. |
Study Parameters
A standing panel of hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles and secondary validation. ClinicalTrials.gov, CDSCO device registration databases, PMDA approval records, and hospital procurement contract filings anchored source triangulation. Bottom-up instrument installation tracking and top-down reagent consumption modeling converged on segment-level estimates.
Consistency checks validated outputs against external benchmarks including thermal cycler shipment disclosures and reference laboratory capital expenditure patterns across the projection horizon. Segmentation dimensions spanned product architecture, end-user procurement authority, technology maturity gradient, and application disease burden. CAGRs derived from logistic diffusion curves fitted to installed base expansion and replacement cycle dynamics. Host-response biomarker integration timelines and CRISPR-Cas12a platform pilot results informed capability evolution assumptions.
Forecasts assume regulatory continuity in Japan's PMDA analytical validation regime, China's NMPA Class III review channels, and India's CDSCO streamlined Class C/D pathways; material policy shifts would require re-modeling. Antimicrobial stewardship program intensification, NGS cost curves, and regional cold chain infrastructure development represent specific revision triggers. Practitioners should keep alternative scenarios live as these conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Influenza Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market