
 Global Hemodynamic Monitoring System Market | 2026-2036
Global Hemodynamic Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemodynamic Monitoring System Market Foresight
Silicon-based pressure transducers is hardening as the dominant sensing element over traditional strain-gauge configurations in modern pulmonary artery catheters. Edwards Lifesciences Corporation leverages proprietary catheter engineering to sustain leadership in invasive hemodynamic measurement. GE HealthCare Technologies anchors its position through integrated monitoring ecosystems that span diagnostic imaging and patient monitoring workflows.
A hemodynamic monitoring system measures cardiovascular performance parameters including cardiac output, blood pressure, vascular resistance, and fluid responsiveness through invasive, minimally invasive, or non-invasive sensor modalities. These systems employ thermodilution, Doppler ultrasound, or pulse contour analysis to generate real-time physiological data that guides therapeutic decisions in critical care and surgical settings. Non-invasive devices represent the fastest-expanding product category as hospitals seek to reduce catheter-associated infection risks while maintaining measurement fidelity. Pulse contour analysis technology commands premium positioning among minimally invasive alternatives due to its calibration-free operational profile and compatibility with existing arterial lines.
The FDA governs device classification and 510(k) clearance pathways for hemodynamic monitors sold in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for invasive cardiovascular devices entering European markets. Japan's PMDA maintains distinct pharmaceutical and medical device agency standards that shape product localization strategies for Asian market entry. Stakeholders must weigh regulatory validation investments against the margin compression inherent in commoditized non-invasive sensor segments.
Market Dynamics
The transition from invasive to non-invasive hemodynamic monitoring modalities is compressing catheter volumes while expanding addressable patient populations across emergency departments and step-down units. Silicon-based pressure transducers and Doppler ultrasound platforms are displacing traditional thermodilution methods in mid-acuity settings.
Growth Catalysts
- EU Medical Device Regulation:Strengthened clinical evidence requirements for invasive cardiovascular devices are accelerating hospital procurement of validated non-invasive alternatives that bypass lengthy regulatory validation cycles.
- Catheter-associated infection protocols:Intensive care units in the United States are mandating reduced pulmonary artery catheter dwell times, creating immediate demand for continuous cardiac output monitoring through arterial line-compatible pulse contour systems.
- Perioperative monitoring infrastructure:Germany and Japan are simultaneously upgrading surgical suites with integrated hemodynamic platforms that bridge diagnostic imaging and patient monitoring workflows.
Market Restraints
- Silicon wafer supply concentration:Pressure transducer manufacturing depends on semiconductor foundry capacity concentrated in East Asian supply nodes, exposing device makers to input volatility and allocation constraints.
- Reimbursement compression:CMS and German statutory health insurers have narrowed coverage differentials between invasive and non-invasive hemodynamic monitoring, eroding price premiums for advanced catheter systems.
- Technical measurement limitations:Non-invasive cardiac output methods exhibit reduced accuracy in patients with severe arrhythmias or valvular dysfunction, restricting addressable populations in cardiac surgery units.
Strategic Opportunities
- Japan's PMDA fast-track pathway:The Sakigake designation system offers accelerated review for breakthrough hemodynamic monitoring devices, enabling earlier market entry than FDA 510(k) timelines.
- Ambulatory surgical center expansion:United States outpatient facilities represent underpenetrated demand for compact, calibration-free pulse contour monitors that support same-day discharge protocols.
- AI-integrated waveform analysis:Machine learning algorithms applied to arterial pressure waveforms are converging with traditional pulse contour mathematics to enable predictive fluid responsiveness alerts.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in cardiovascular physiology signal processing and MEMS fabrication is concentrating among a limited pool of academic and industry researchers.
- Legacy system integration complexity:Hospital information technology departments face protracted validation cycles when connecting next-generation hemodynamic monitors to existing electronic health record architectures.
- Multi-jurisdictional certification timelines:Simultaneous FDA 510(k), EU MDR, and PMDA submissions require duplicative clinical evidence packages that strain regulatory affairs bandwidth at mid-size device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemodynamic Monitoring System Market |
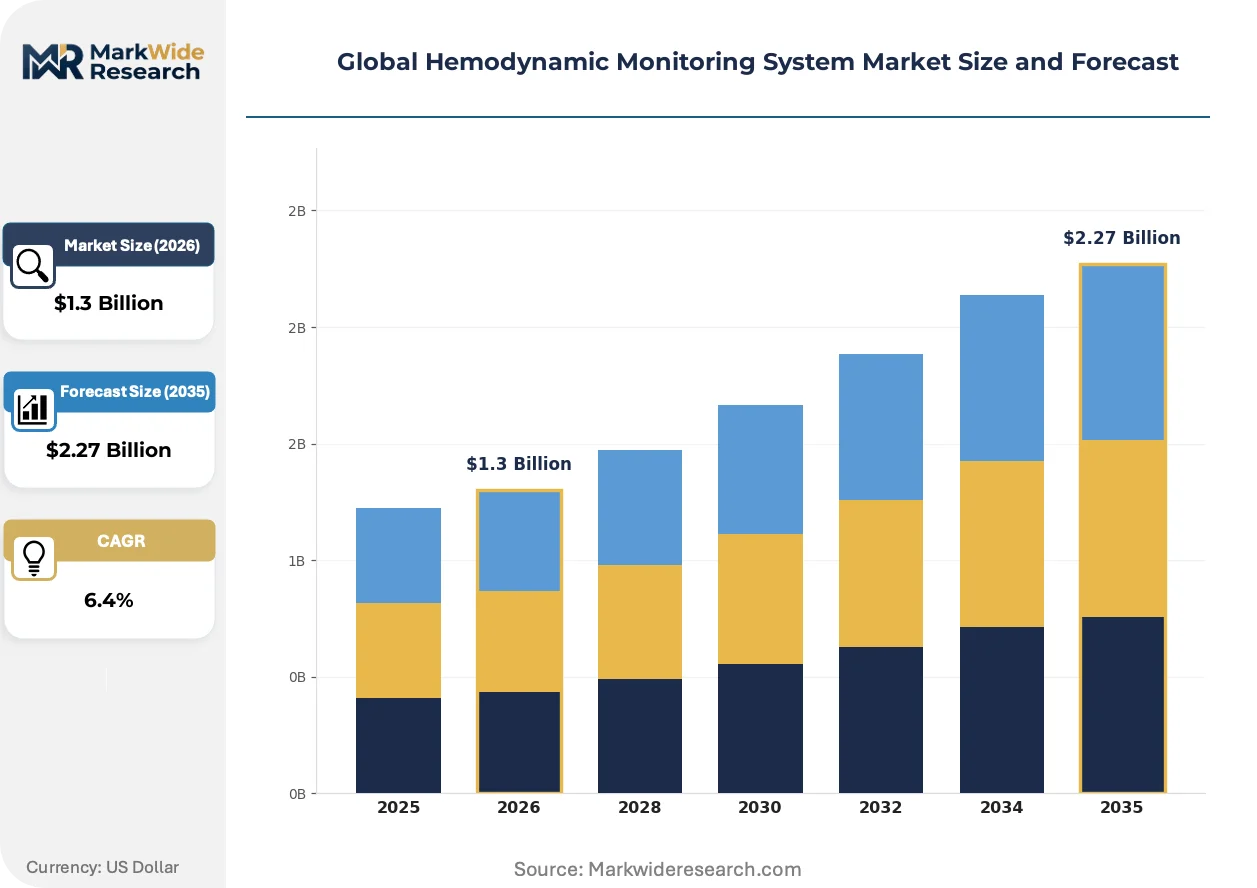
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
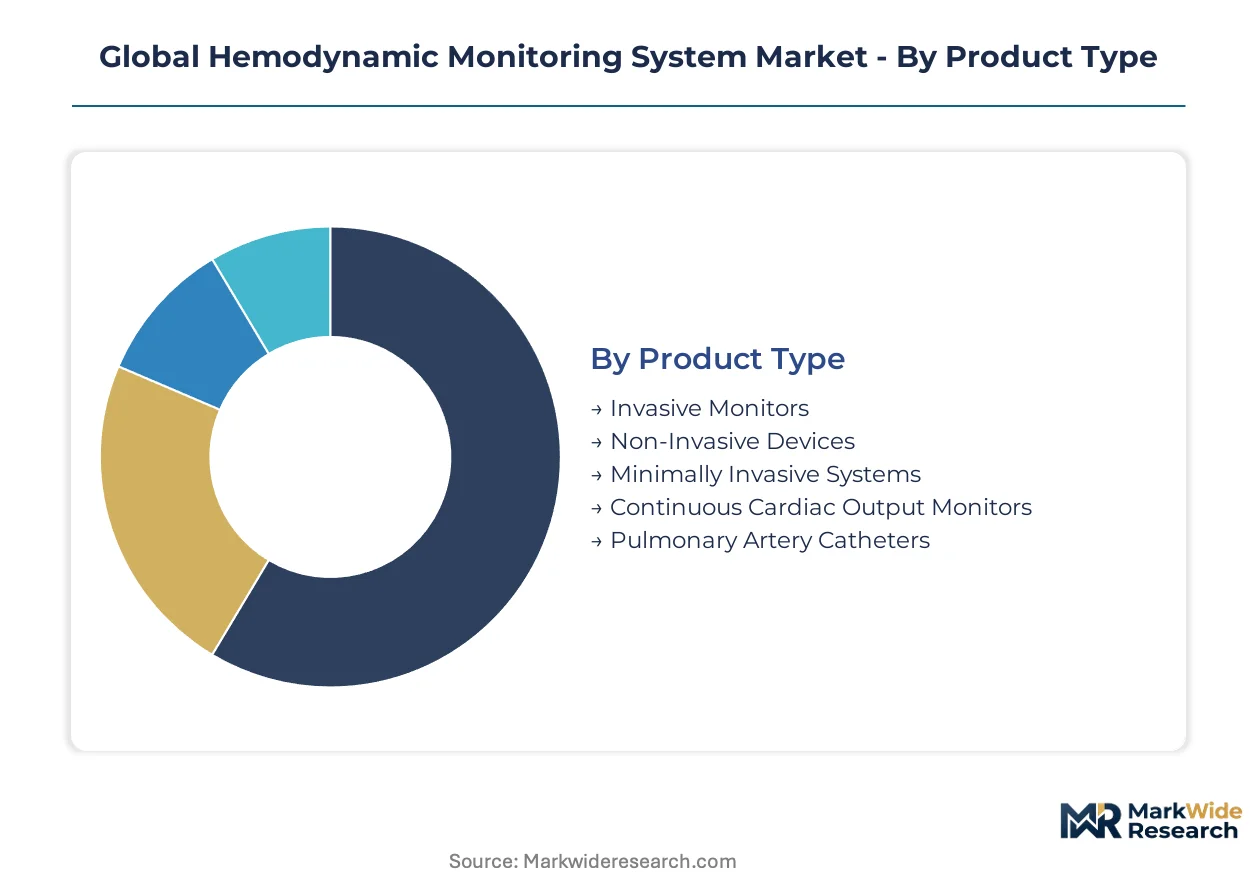
| Segmentation | Product Type: Invasive Monitors, Non-Invasive Devices, Minimally Invasive Systems, Continuous Cardiac Output Monitors, Pulmonary Artery Catheters Application: Critical Care, Perioperative Monitoring, Cardiovascular Surgery, Emergency Medicine, Anesthesia Management End User: Intensive Care Units, Cardiac Centers, Surgical Wards, Trauma Centers, Diagnostic Laboratories Technology: Thermodilution, Doppler Ultrasound, Pulse Contour Analysis, Bioimpedance, Electrical Velocimetry |
| Companies Covered | GE HealthCare Technologies, Getinge, Koninklijke Philips N.V., Siemens Healthineers, ICU Medical, Edwards Lifesciences Corporation, Baxter International, Mindray Medical International Limited, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemodynamic Monitoring System Market Shifts & Advancements
Sensor miniaturization and wireless data transmission are dissolving the physical boundaries between patient, monitor, and clinical decision-maker. These advances are enabling continuous hemodynamic surveillance outside traditional intensive care footprints.
Implantable pulmonary artery pressure sensors are rewriting the chronic heart failure management paradigm by enabling outpatient hemodynamic monitoring that previously required hospital admission. Cardiology practices in the United States are adopting these devices for guideline-directed medical therapy titration. The technology is compressing emergency department utilization for volume overload episodes while creating new reimbursement negotiations with payers.
Japan's PMDA has streamlined software-as-a-medical-device classification for hemodynamic algorithms, reducing premarket review timelines for AI-enhanced monitoring platforms. This regulatory flexibility is attracting algorithm developers to Tokyo's medical device cluster. European manufacturers are responding by establishing Tokyo-based regulatory subsidiaries to access the accelerated pathway.
Hospital procurement committees are consolidating hemodynamic monitor purchasing with broader patient monitoring ecosystem contracts, favoring vendors with integrated platform architectures. This behavioral shift is displacing standalone device purchasing in favor of multi-year enterprise agreements. The pattern is most visible in German university hospital networks and United States integrated delivery networks.
Global Hemodynamic Monitoring System Market Segmentation
Hospital procurement committees evaluate hemodynamic monitoring platforms across multiple technical and operational dimensions. Product architecture, clinical application, and end-user environment each impose distinct performance requirements and budget constraints. Understanding these segment boundaries illuminates where device manufacturers can defend premium positioning versus where commoditization pressures dominate.
Product Type:
Capital allocation decisions separate high-acuity invasive platforms from emerging non-invasive alternatives in contemporary purchasing cycles.
- Invasive Monitors:These systems deploy pulmonary artery catheters with integrated pressure transducers and thermodilution sensors for gold-standard cardiac output measurement. Demand concentrates in United States academic medical centers where CMS reimbursement still recognizes invasive monitoring intensity. Catheter-associated infection protocols are compressing dwell times and forcing manufacturers to demonstrate superior aseptic engineering.
- Non-Invasive Devices:Bioimpedance and Doppler ultrasound platforms eliminate vascular access requirements while maintaining measurement fidelity for hemodynamic surveillance. German university hospital networks are expanding procurement of these systems for step-down units seeking to reduce iatrogenic complication rates. The EU Medical Device Regulation's strengthened clinical evidence requirements favor established non-invasive platforms with existing validation libraries.
- Minimally Invasive Systems:Arterial line-compatible pulse contour monitors balance measurement accuracy with reduced invasiveness.
- Continuous Cardiac Output Monitors:Real-time hemodynamic trending devices support dynamic fluid responsiveness assessment.
- Pulmonary Artery Catheters:Traditional balloon-tipped flow-directed catheters remain embedded in cardiac surgery protocols.
Volume sits with Invasive Monitors; growth tilts toward Non-Invasive Devices.
Application:
Clinical workflow integration determines whether hemodynamic platforms achieve sustained utilization or shelf deployment.
- Critical Care:Multi-parameter invasive monitoring dominates intensive care units managing septic shock and acute respiratory distress syndrome. Japan's PMDA fast-track pathway is accelerating clearance of AI-integrated platforms for Tokyo metropolitan hospital networks facing intensivist staffing constraints.
- Perioperative Monitoring:Integrated hemodynamic surveillance bridges diagnostic imaging and patient monitoring workflows in surgical suites. Germany's statutory health insurers have narrowed coverage differentials here, eroding price premiums for advanced catheter systems.
- Cardiovascular Surgery:High-fidelity cardiac output measurement guides cardiopulmonary bypass management.
- Emergency Medicine:Rapid hemodynamic assessment supports triage and early goal-directed therapy.
- Anesthesia Management:Continuous blood pressure and flow monitoring guides intraoperative fluid administration.
Critical Care captures the largest installed base; Perioperative Monitoring is gaining share fastest through integrated platform contracts.
End User:
Facility acuity level shapes whether procurement prioritizes measurement precision or operational flexibility.
- Intensive Care Units:These environments demand continuous multi-parameter monitoring with alarm integration and electronic health record connectivity. United States integrated delivery networks are consolidating purchasing across ICU, step-down, and emergency department footprints to extract volume discounts from vendors.
- Cardiac Centers:Specialized catheterization laboratories and electrophysiology suites require hemodynamic platforms with high-frequency pressure waveform fidelity. Silicon wafer supply concentration in East Asian foundries exposes these centers to transducer allocation constraints during semiconductor shortage periods.
- Surgical Wards:Post-operative monitoring environments favor compact, calibration-free devices.
- Trauma Centers:Rapid assessment protocols drive demand for portable non-invasive alternatives.
- Diagnostic Laboratories:Hemodynamic stress testing applications require precise exercise-induced measurement capability.
Intensive Care Units anchor current revenue; Cardiac Centers present the steepest expansion trajectory through implantable sensor adoption.
Technology:
Signal processing methodology determines calibration burden, arterial line compatibility, and arrhythmia tolerance.
- Pulse Contour Analysis:This arterial waveform mathematics approach enables cardiac output derivation without external calibration when combined with proprietary algorithms. United States ambulatory surgical centers are expanding procurement of these systems for same-day discharge protocols requiring minimal setup time.
- Doppler Ultrasound:Transcutaneous or transesophageal ultrasound platforms measure blood flow velocity to calculate stroke volume. Japanese PMDA software-as-a-medical-device classification streamlines algorithm updates for Tokyo-based developers enhancing measurement accuracy.
- Thermodilution:Indicator dilution methods remain the reference standard for cardiac output validation.
- Bioimpedance:Thoracic electrical impedance changes track stroke volume through non-invasive skin electrodes.
- Electrical Velocimetry:Signal morphology analysis from electrocardiographic electrodes estimates cardiac output.
Pulse Contour Analysis commands premium positioning; Doppler Ultrasound is climbing the fastest through miniaturization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen concentrate hemodynamic monitor assembly operations serving Asia-Pacific hospital networks. Medical device parks in Germany's Baden-Württemberg region anchor European distribution. Japanese regulatory innovation in Tokyo's Minato medical cluster accelerates algorithm-driven platform approvals.
United States
Academic medical centers in Boston and Houston drive demand for invasive monitoring platforms with AI-integrated alarm systems. FDA 510(k) clearance pathways shape product development timelines for cardiovascular device manufacturers. The Research Triangle Park in North Carolina hosts contract manufacturing facilities producing silicon pressure transducers for catheter systems.
Germany
University hospital networks in Munich and Heidelberg prioritize integrated perioperative monitoring ecosystems spanning imaging and patient surveillance workflows. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for invasive cardiovascular platforms entering European markets. Baden-Württemberg's medical technology corridor concentrates engineering talent for MEMS-based sensor development.
Japan
Tokyo metropolitan hospitals facing intensivist staffing shortages accelerate procurement of automated hemodynamic surveillance systems. PMDA's Sakigake designation offers accelerated review for breakthrough monitoring devices, enabling earlier market entry than FDA timelines. The Kobe biomedical innovation cluster attracts algorithm developers seeking streamlined software-as-a-medical-device classification.
China
Tier-three hospitals in Shanghai and Beijing expand cardiac surgery capacity requiring high-fidelity pulmonary artery catheter systems. NMPA device registration pathways are converging toward international standards, reducing duplication for multinational manufacturers. The Suzhou Industrial Park hosts foreign-invested production facilities serving domestic and export markets.
India
Corporate hospital chains in Mumbai and Delhi-NCR invest in non-invasive cardiac output monitors for step-down units managing post-surgical patients. CDSCO medical device rules impose import licensing requirements that favor localized assembly operations. Hyderabad's medical device manufacturing zone attracts contract electronics producers serving regional OEMs.
Global Hemodynamic Monitoring System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding enterprise contracts while component suppliers capture recurring sensor replacement revenue. The vendor base organizes around three archetypes: diversified medical technology conglomerates with monitoring ecosystems, cardiovascular-focused device specialists with catheter engineering heritage, and Asian electronics manufacturers scaling non-invasive sensor production. Strategic moves center on hospital information technology integration partnerships and regulatory bandwidth expansion through Tokyo and Washington D.C. subsidiary networks.
Among diversified technology conglomerates, GE HealthCare Technologies and Siemens Healthineers occupy positions spanning diagnostic imaging and patient monitoring workflows. Edwards Lifesciences Corporation exemplifies the cardiovascular specialist archetype with concentrated expertise in invasive hemodynamic measurement. Koninklijke Philips N.V. anchors the integrated platform tier, representing the hospital ecosystem contracting model consolidating multiple monitoring modalities under single procurement frameworks.
| Leading Market Players |
|---|
| GE HealthCare Technologies |
| Getinge |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| ICU Medical |
| Edwards Lifesciences Corporation |
| Baxter International |
| Mindray Medical International Limited |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Silicon wafer spot price indices cascade through hemodynamic monitor manufacturing tiers, compressing margins on pressure transducer-dependent invasive systems while amplifying pricing power for calibration-free non-invasive alternatives that bypass semiconductor-intensive catheter engineering.
Pricing Analysis
Lead-time premiums command fifteen-to-twenty percent markups for arterial line-compatible pulse contour monitors deliverable within standard procurement windows, while spot inventory of legacy thermodilution catheters trades at discounted clearance levels. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated platforms with predictive analytics from basic waveform displays and refurbished legacy units. Pricing pressure stems from CMS reimbursement compression narrowing coverage differentials between invasive and non-invasive modalities. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, whereas academic medical centers prioritize measurement fidelity over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States integrated delivery networks and German university hospital networks force transducer manufacturers to qualify secondary semiconductor foundries beyond primary East Asian suppliers. Silicon wafer fabrication concentrates in Taiwan, South Korea, and Japan, while catheter assembly operations cluster in Mexico, Costa Rica, and Malaysia. Raw material dependencies span semiconductor-grade silicon, medical-grade polyurethane, and platinum-iridium electrode alloys. Single-source vulnerability in advanced MEMS pressure sensor foundries exposes device makers to allocation constraints during capacity crunches. Distribution runs through regional medical device distributors holding consignment inventory at major hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors with hospital information technology integration capabilities, as procurement committee consolidation favors enterprise contracting over standalone device purchasing and forces catheter-specialist pure-plays toward acquisition or exit.
For Market Incumbents: Cement ecosystem lock-in through exclusive electronic health record connectivity partnerships with Epic and Cerner installations at tier-one academic medical centers. Deepen backward integration into MEMS pressure transducer fabrication through captive supply agreements with Taiwan-based foundries. Counter emerging AI-algorithm competitors by embedding machine learning waveform analysis directly into hardware platforms rather than standalone software modules. For New Entrants and Emerging Players: Begin with ambulatory surgical center pulse contour monitors targeting same-day discharge protocols in United States outpatient facilities, where incumbent presence remains thin and procurement cycles favor compact calibration-free designs. Exploit Japan's PMDA Sakigake fast-track pathway for algorithm-driven platforms ahead of FDA 510(k) timelines. Position through direct-to-facility sales bypassing traditional distributor markups. For Investors and Strategic Acquirers: The window for entry favors cardiovascular-focused device specialists with catheter engineering heritage and existing FDA 510(k) validation libraries, as regulatory bandwidth scarcity creates defensive moats. Long-term viability hinges on software-as-a-medical-device revenue streams recurring beyond initial hardware placement. Watch PMDA software classification precedents as the inflection signal for algorithm-centric valuation multiples displacing traditional device revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines compress competitive entry barriers for next-generation platforms. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor established players with existing validation libraries. |
| Hospital System Partnership | Enterprise contracting with United States integrated delivery networks locks out standalone competitors. |
| Software Companion Development | AI-integrated waveform analysis enables predictive fluid responsiveness alerts and recurring SaaS revenue. |
| Reimbursement Strategy | CMS coverage differential narrowing forces pricing discipline and cost engineering focus. |
Research Methodology
Multi-period observation of silicon wafer pricing indices, FDA 510(k) clearance timelines, and hospital procurement contract values anchored the trend analysis, supplemented by interviews with biomedical engineering directors at catheter manufacturers, intensivists at academic medical centers, GPO contracts managers, and regulatory affairs leads specializing in cardiovascular devices. Secondary validation drew from FDA 510(k) database filings, EU MDR notified body certificates, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Input-output matrices modeled hemodynamic monitor demand across invasive, non-invasive, and minimally invasive product categories, critical care and perioperative monitoring applications, and intensive care unit versus ambulatory surgical center end-user environments throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated intensivist staffing shortage projections, semiconductor foundry capacity expansion plans, and evolving catheter-associated infection protocol stringency.
Semiconductor supply allocation disruptions, PMDA regulatory pathway reversals, and CMS reimbursement category reclassification are the dominant revision risks to the outlook. Deviation in silicon wafer availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market