
 China ICU Patient Monitor Market | 2026-2036
China ICU Patient Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
China ICU Patient Monitor Market Insights
Aftermarket service revenue is rewriting profit allocation across the China ICU patient monitor landscape. Mindray Medical International Limited leverages its domestic manufacturing footprint to anchor service contracts in tier-one cities. GE Healthcare competes through backward integration into sensor module production, sustaining margin capture on high-acuity installations. Philips differentiates via digital platform licensing, extending recurring revenue streams beyond hardware sales.
An ICU patient monitor is a multi-parameter physiological surveillance instrument that continuously measures, displays, and alarms on vital signs including electrocardiography, invasive and non-invasive blood pressure, pulse oximetry, and respiratory mechanics through modular plug-in architectures. These devices serve as the central nervous system of intensive care workflows, enabling clinicians to detect hemodynamic deterioration before irreversible organ injury occurs. Bedside monitors dominate current hospital procurement volumes, while central monitoring systems command premium pricing through ward-wide integration capabilities. Wireless technology represents the fastest-expanding segment as Chinese tertiary hospitals pursue flexible ICU layouts and remote telemetry during surge events.
NMPA medical device registration rules and GB 9706 electrical safety standards shape product design requirements, lengthening approval timelines for imported systems while accelerating domestic certificate issuance under priority review pathways. The country's dual carbon goals are forcing manufacturers to redesign power architectures and reduce standby consumption across monitor portfolios. Stakeholders must weigh NMPA localization incentives against the R&D burden of hybrid analog-digital signal processing architectures that satisfy both legacy infrastructure and next-generation interoperability demands.
Market Dynamics
NMPA medical device classification rules are compressing approval timelines for domestic manufacturers while extending regulatory scrutiny on imported ICU patient monitor systems, fundamentally restructuring competitive entry costs.
Growth Catalysts
- Dual carbon goals:Beijing's emissions reduction mandates are accelerating hospital fleet replacements with energy-efficient monitor architectures across tertiary facilities in Jiangsu province.
- Modular plug-in architectures:These flexible hardware configurations enable rapid parameter expansion without full device replacement, reducing capital commitment cycles for procurement departments.
- GB 9706 electrical safety standards:Updated technical requirements are creating certification moats that favor established domestic manufacturers with in-house testing infrastructure.
Market Restraints
- Sensor module import dependency:High-acuity photoplethysmography and invasive pressure transducers remain concentrated among German and Japanese component suppliers, exposing assemblers to currency volatility.
- Hybrid analog-digital signal processing complexity:Legacy hospital infrastructure in China's central provinces demands backward-compatible architectures that inflate R&D overhead by 40-60% versus pure digital designs.
- NMPA priority review pathway asymmetry:Domestic certificate issuance acceleration has not extended equivalently to joint ventures, distorting competitive positioning for hybrid ownership structures.
Strategic Opportunities
- Central monitoring system ward-wide integration:Tertiary hospitals in Guangdong and Zhejiang provinces are consolidating fragmented bedside installations into unified telemetry networks.
- Wireless remote telemetry:Surge event protocols developed during respiratory virus waves are institutionalizing flexible ICU layouts that demand untethered patient monitoring.
- MIIT industrial internet platform certification:Medical device interoperability mandates are opening software licensing revenue streams beyond hardware margins for platform-compliant vendors.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-functional expertise spanning clinical workflow design and embedded systems firmware remains concentrated in Shenzhen and Beijing, constraining regional service network expansion.
- Legacy central station integration:Heterogeneous communication protocols across installed monitor fleets complicate ward-wide system upgrades without complete infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China ICU Patient Monitor Market |
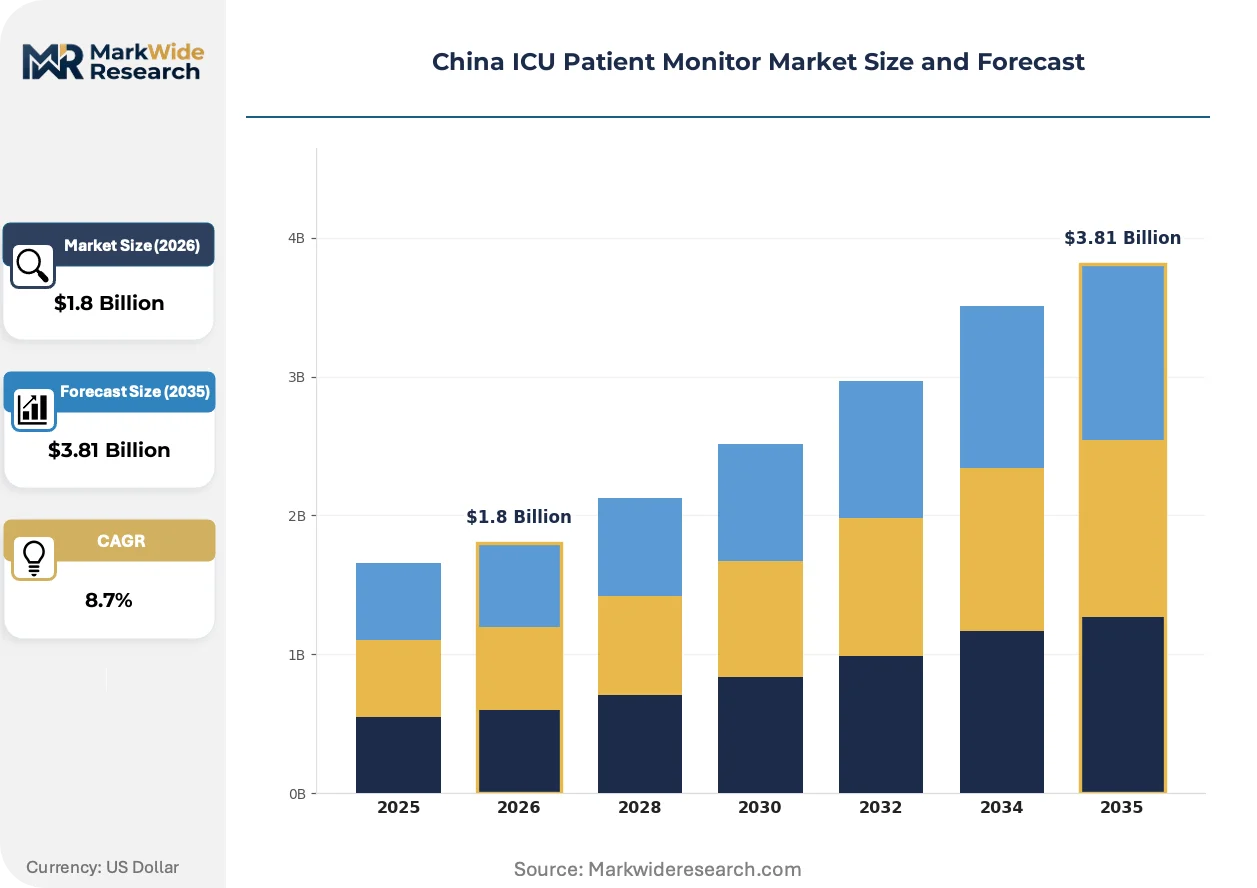
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable Monitors, Bedside Monitors, Central Monitoring Systems, Fetal Monitors End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Home Care Services Technology: Wireless Technology, Analog Technology, Digital Technology, Hybrid Technology Monitoring Parameter: Heart Rate, Blood Pressure, Respiratory Rate, Oxygen Saturation |
| Companies Covered | Mindray Medical International Limited, Zhengzhou Santa Medical Co., Ltd., Shenzhen Comen Medical Instruments, Jiangsu Konsung Bio-Medical Science & Technology Co., Ltd., GE Healthcare, Koninklijke Philips NV, Medtronic PLC, Draegerwerk AG, Nihon Kohden, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China ICU Patient Monitor Market Trends and Innovations
Digital platform licensing is displacing pure hardware transactions as the dominant value capture mechanism, while wireless architectures and AI-enhanced alarm algorithms compress clinical response latency.
Edge computing modules with on-device arrhythmia detection are hybridizing traditional bedside monitors into predictive clinical decision support nodes. Tertiary hospitals in Shanghai and Beijing are piloting these systems at scale. This convergence is compressing differentiation timelines for pure hardware vendors while elevating software development capabilities as primary competitive moats.
NMPA's 2023 medical software classification guidance is mandating standalone registration for AI-enabled diagnostic algorithms previously embedded within hardware certificates. Domestic manufacturers are reorganizing regulatory affairs teams to parallel-track hardware and algorithm submissions. High-acuity installations with predictive analytics are experiencing 8-14 month additional approval delays versus conventional parameter monitoring.
Hospital procurement departments are consolidating vendor relationships through multi-year fleet management contracts that bundle hardware, software updates, and predictive maintenance. Distributor networks in eastern seaboard provinces are losing volume to direct manufacturer service subsidiaries. This consolidation is most visible in Jiangsu province's medical device manufacturing clusters, where tertiary facilities now favor single-source accountability over multi-vendor price arbitrage.
China ICU Patient Monitor Market Segmentation
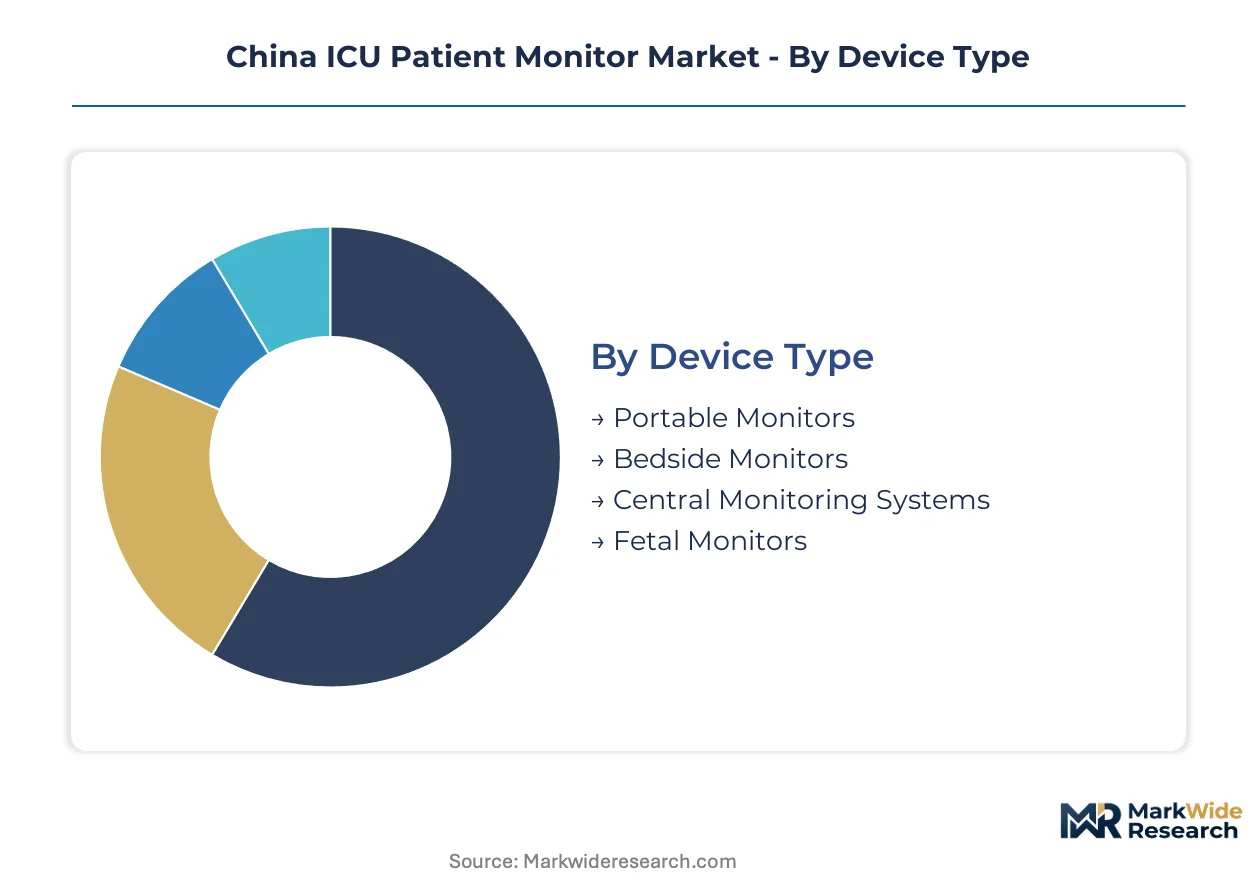
Aftermarket service intensity varies sharply across device configurations in China's ICU patient monitor landscape. Procurement departments in Jiangsu province's tertiary hospitals prioritize segments with embedded calibration and predictive maintenance capabilities.
Device Type:
Service contract profitability concentrates in installations requiring continuous parameter validation and firmware updates across extended operational lifecycles.
- Bedside Monitors:Fixed-location multi-parameter units with modular plug-in architectures dominate current procurement volumes across China's eastern seaboard tertiary facilities. Jiangsu province hospitals are consolidating fleet replacements around these configurations to standardize training protocols and reduce spare parts inventory complexity.
- Central Monitoring Systems:Ward-wide integration platforms aggregate telemetry from multiple bedside units through centralized display architectures. Guangdong and Zhejiang province hospitals are driving demand for these systems as they consolidate fragmented ICU installations into unified networks.
- Portable Monitors:Battery-powered mobile units enable intra-hospital transport and emergency department surge deployment.
- Fetal Monitors:Obstetric-specific parameter tracking for antepartum and intrapartum surveillance in maternity wards.
By volume, Bedside Monitors leads. By growth pace, Central Monitoring Systems is ahead.
End User:
Capital commitment cycles and regulatory compliance burdens create distinct procurement behaviors across care delivery settings.
- Hospitals:Tertiary facilities with NMPA Class III medical device procurement authority drive specification standards that cascade to smaller institutions. These installations demand continuous technical support and calibration services that anchor long-term vendor relationships.
- Specialty Clinics:Cardiovascular and neurological focused outpatient surgical centers require high-acuity monitoring for procedural sedation and recovery.
- Rehabilitation Centers:Post-acute facilities with step-down monitoring needs prioritize cost-efficient parameter coverage.
- Home Care Services:Remote patient monitoring deployments with cellular connectivity for chronic disease management.
By installed base, Hospitals dominates. By expansion trajectory, Home Care Services is climbing the fastest.
Technology:
Signal processing architecture determines NMPA registration pathway complexity and electrical safety certification requirements under GB 9706 standards.
- Wireless Technology:Untethered telemetry architectures with Wi-Fi and proprietary radio protocols enable flexible ICU layouts demanded by surge event protocols. Shanghai and Beijing tertiary hospitals are piloting these systems at scale for remote patient visibility.
- Digital Technology:Pure digital signal processing with embedded edge computing for on-device arrhythmia detection.
- Hybrid Technology:Analog-digital conversion architectures maintaining backward compatibility with legacy central station infrastructure in China's central provinces.
- Analog Technology:Legacy continuous signal architectures with limited interoperability for installed base replacement.
By current penetration, Hybrid Technology leads. By technology transition momentum, Wireless Technology is gaining share fastest.
Monitoring Parameter:
Sensor module import dependency concentrates in specific physiological measurement domains, exposing assemblers to supply chain volatility.
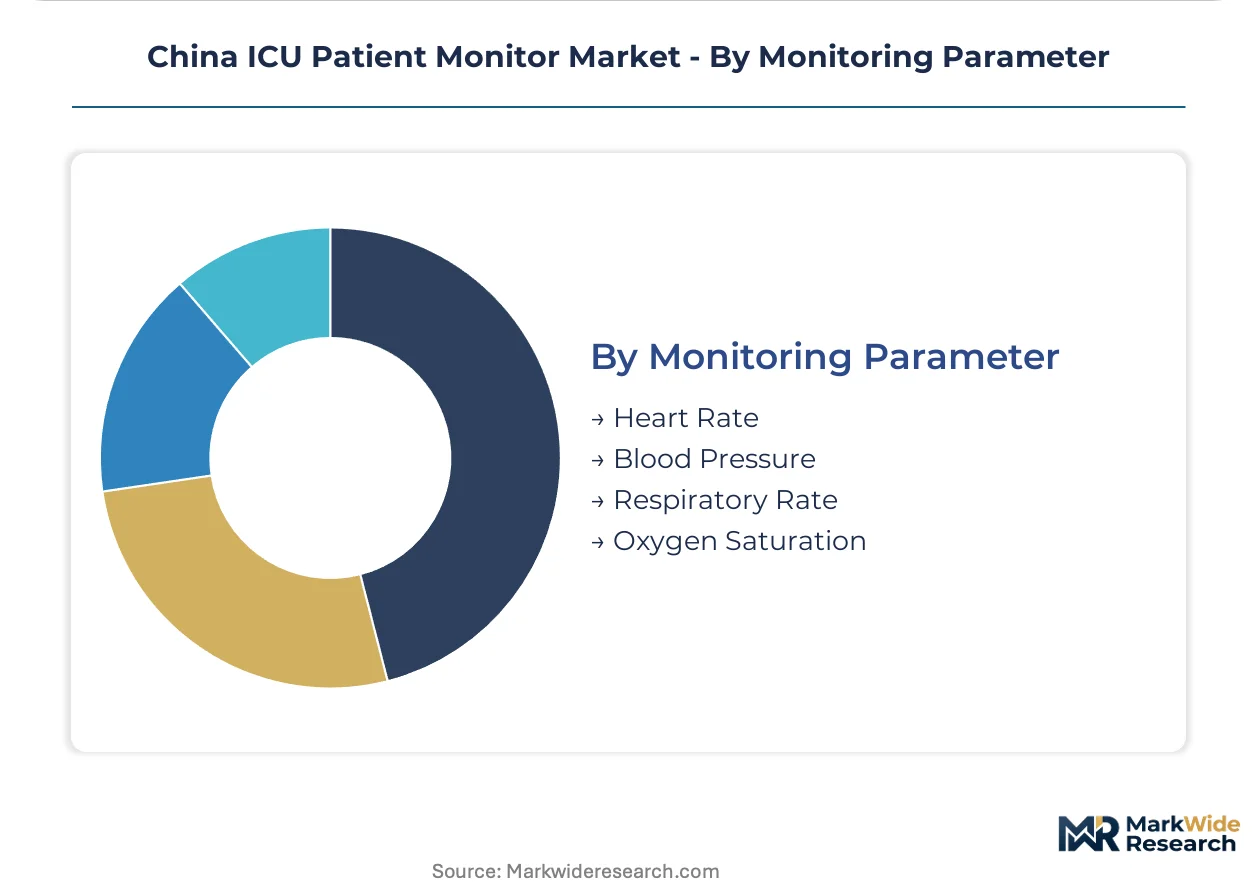
- Oxygen Saturation:Pulse oximetry with photoplethysmography sensors remains concentrated among Japanese component suppliers, creating currency exposure for domestic monitor assemblers. High-acuity installations require calibrated SpO2 accuracy for hypoxemia detection in respiratory failure protocols.
- Blood Pressure:Invasive arterial pressure transduction with disposable pressure tubing and transducer modules.
- Heart Rate:Electrocardiography with multi-lead acquisition and arrhythmia classification algorithms.
- Respiratory Rate:Impedance pneumography and capnography for ventilatory status assessment.
By clinical criticality, Oxygen Saturation leads. By integration complexity, Blood Pressure is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's provincial healthcare systems diverge sharply between eastern seaboard tertiary facilities and central province installations. Jiangsu province hospitals prioritize modular fleet standardization, while Sichuan-Chongqing facilities grapple with legacy infrastructure integration. These geographic disparities shape procurement specifications and vendor selection criteria.
Jiangsu Province
Tertiary hospitals in Nanjing and Suzhou are consolidating monitor fleet replacements around standardized bedside configurations. NMPA priority review pathways accelerate certificate issuance for domestic manufacturers with local testing infrastructure. The province's medical device manufacturing clusters in Suzhou Industrial Park anchor service contract negotiations with direct manufacturer subsidiaries.
Guangdong Province
Shenzhen and Guangzhou tertiary facilities are driving demand for central monitoring system ward-wide integration. MIIT industrial internet platform certification requirements are reshaping software licensing revenue models for platform-compliant vendors. The Pearl River Delta's electronics supply chain concentration reduces lead times for wireless telemetry component sourcing.
Zhejiang Province
Hangzhou and Ningbo hospitals are piloting wireless remote telemetry architectures for flexible ICU surge protocols. GB 9706 electrical safety standard updates are creating certification barriers for imported systems without in-house testing facilities. The province's biomedical engineering talent concentration supports advanced service network deployment.
Sichuan-Chongqing Region
Chengdu and Chongqing tertiary facilities face hybrid analog-digital signal processing complexity from legacy central station infrastructure. Dual carbon goals are accelerating hospital fleet replacements with energy-efficient monitor architectures. The region's medical device distributor networks are losing volume to direct manufacturer service subsidiaries from eastern seaboard vendors.
Beijing-Tianjin-Hebei
Beijing's top-tier hospitals are piloting edge computing modules with on-device arrhythmia detection at scale. NMPA's 2023 medical software classification guidance is mandating standalone registration for AI-enabled diagnostic algorithms. The capital's regulatory affairs talent concentration supports parallel-track hardware and algorithm submission strategies.
China ICU Patient Monitor Market Competitive Landscape
Capability concentration sits with domestic manufacturers possessing in-house NMPA testing infrastructure; scale advantage sits with multinational healthcare conglomerates with established tertiary hospital relationships. The vendor base stratifies across three tiers: domestic specialists with regulatory proximity, global diversified medtech giants with portfolio breadth, and regional assemblers with cost-position flexibility. Dominant competitive moves include backward integration into sensor module production and digital platform licensing for recurring revenue capture.
Among domestic specialists, Mindray Medical International Limited exemplifies the regulatory-proximity archetype with manufacturing footprint advantages in tier-one cities. GE Healthcare and Koninklijke Philips NV occupy positions on the multinational diversified tier, anchoring premium pricing through technology licensing and ward-wide integration capabilities. Jiangsu Konsung Bio-Medical Science & Technology Co., Ltd. represents the regional specialist archetype concentrated in eastern seaboard manufacturing clusters.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Zhengzhou Santa Medical Co., Ltd. |
| Shenzhen Comen Medical Instruments |
| Jiangsu Konsung Bio-Medical Science & Technology Co., Ltd. |
| GE Healthcare |
| Koninklijke Philips NV |
| Medtronic PLC |
| Draegerwerk AG |
| Nihon Kohden |
| Others |
Pricing and Supply Chain Analysis
Japanese photoplethysmography sensor suppliers and German pressure transducer manufacturers anchor margin capture in downstream monitor assembly, concentrating pricing power among component vendors while domestic Chinese assemblers compete on service bundling and NMPA certification speed.
Pricing Analysis
Long-term fleet management contracts with embedded calibration and predictive maintenance clauses dominate tertiary hospital procurement in Jiangsu and Guangdong provinces. Price differentiation rests on NMPA Class III certification tier and after-sales service depth, with premium installations commanding sustained margins through software licensing. Cost compression in economy-tier bedside monitors intensifies as regional assemblers sacrifice hardware margins to secure service contract anchors. Provincial GPOs exhibit highest price sensitivity, while Beijing's top-tier hospitals prioritize predictive analytics capabilities over unit economics.
Supply Chain Analysis
Extended payment terms from Jiangsu province distributor networks to Suzhou Industrial Park manufacturers are compressing working capital cycles across the assembly tier. Component sourcing draws from Japan for pulse oximetry sensors, Germany for invasive pressure transducers, and domestic China for display modules and power supplies. Single-source vulnerability in high-acuity photoplethysmography creates tariff exposure and currency volatility for domestic assemblers. Distribution runs through direct manufacturer service subsidiaries in tier-one cities, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA's 2023 medical software classification guidance is disrupting hardware-centric business models, creating accelerated value capture for vendors with parallel-track regulatory capabilities and AI-enabled diagnostic portfolios.
For Market Incumbents: Insulate installed base relationships through backward integration into sensor module production, reducing import dependency exposure. Deepen software development capabilities to capture recurring revenue from AI-enabled arrhythmia detection algorithms, defending against pure-hardware margin erosion from regional assemblers.
For New Entrants and Emerging Players: Wireless telemetry architectures for flexible ICU surge protocols in Sichuan-Chongqing's legacy infrastructure replacement cycle represent the most penetrable entry point. Target tier-two tertiary hospitals in central provinces with hybrid analog-digital compatibility and localized service networks as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic specialists with in-house NMPA testing infrastructure and established MIIT industrial internet platform certification. Long-term viability hinges on software licensing revenue scalability beyond hardware transaction cycles. Monitor NMPA priority review pathway expansion to joint ventures as the critical inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Parallel-Track Submission | Accelerates market entry for AI-enabled diagnostic algorithms under 2023 software guidance. |
| MIIT Platform Certification | Unlocks software licensing revenue streams beyond hardware margins for compliant vendors. |
| Backward Integration into Sensors | Reduces Japanese and German component dependency exposure for domestic assemblers. |
| Hospital System Partnership | Consolidates vendor relationships through multi-year fleet management contract bundling. |
| Wireless Telemetry Development | Captures flexible ICU layout demand from surge event protocols in Beijing and Shanghai. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committee members, biomedical engineering directors, NMPA regulatory affairs specialists, and GPO contract managers. Secondary validation drew from NMPA medical device registration databases, hospital procurement disclosure records, MIIT industrial internet platform certification filings, and GB standards technical documentation. Bottom-up installation base modeling and top-down healthcare expenditure allocation analysis were triangulated to establish market sizing.
Calibration against historical NMPA certificate issuance timelines and tertiary hospital capital expenditure cycles anchored projection reliability across the analysis window. Segmentation modeling incorporated device type, end-user facility tier, signal processing architecture, and monitoring parameter complexity. CAGRs were derived from weighted regression of procurement volume trends and replacement cycle acceleration patterns under dual carbon mandates.
Practitioners should monitor NMPA software classification guidance enforcement intensity and MIIT platform certification expansion for early signals of business model disruption. Forecasts reflect assumptions regarding regulatory pathway stability and hospital procurement centralization velocity. Macroeconomic deviation, regulatory timeline extension, or AI algorithm validation breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market