
 Europe Remote Patient Monitoring Systems Market | 2026-2036
Europe Remote Patient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Remote Patient Monitoring Systems Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for connected diagnostic platforms. Siemens Healthineers leverages its imaging heritage to anchor hospital-centric RPM deployments across German-speaking markets. Koninklijke Philips N.V. sustains a broad home-monitoring portfolio that competes on interoperability with acute care networks.
Remote patient monitoring systems encompass wearable biosensors, implantable telemetry devices, cloud-native software platforms, and companion mobile applications that capture, transmit, and analyze physiological data outside traditional clinical settings. These systems typically operate through Bluetooth Low Energy, Wi-Fi, or cellular connectivity to relay continuous or episodic patient metrics to centralized care teams for clinical decision support. Wearable devices and software solutions capture divergent margin profiles, with wearable hardware facing component cost pressures while cloud-based platforms and mobile applications accumulate recurring revenue from long-term patient monitoring contracts. Cellular-enabled systems are gaining structural importance as elderly patient segments require connectivity that functions independently of home network infrastructure.
EMA guidance on software-as-a-medical-device, the EU Medical Device Regulation, and GDPR data governance frameworks collectively determine product design, clinical validation requirements, and cross-border data flows for RPM vendors operating in Europe. EMA's evolving stance on algorithm-driven diagnostics is forcing companies to document clinical evidence for AI-enhanced monitoring features before market authorization. Stakeholders must weigh the compliance burden of MDR conformity against the revenue opportunity of scaling chronic disease management programs into home care settings.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product development timelines while forcing vendors to rebuild clinical evidence portfolios for legacy connected devices. This regulatory recertification wave is simultaneously creating barriers for smaller software developers and opening procurement pathways for established medical technology manufacturers with in-house regulatory affairs capabilities.
Growth Catalysts
- Chronic disease management mandates:Germany's structured disease management programs (DMPs) for diabetes and cardiovascular conditions now explicitly reimburse remote monitoring interventions, creating institutional pull for connected glucose meters and blood pressure telemetry.
- GDPR-compliant data architectures:Vendors investing in edge computing and local data processing are unlocking hospital procurement contracts that were previously blocked by cross-border data transfer restrictions.
- Cellular connectivity infrastructure:NB-IoT and LTE-M network rollouts across France, Spain, and Italy are eliminating home Wi-Fi dependency for elderly patient segments.
Market Restraints
- MDR conformity assessment bottlenecks:Notified body capacity constraints in Germany and the Netherlands are extending time-to-market for Class IIa and above software devices by 12-18 months.
- Sensor component supply concentration:MEMS accelerometer and optical PPG module production concentrates in Taiwanese and South Korean foundries, exposing European device manufacturers to geopolitical supply interruptions.
- Interoperability fragmentation:Proprietary data formats from incumbent acute care vendors are blocking seamless integration with third-party RPM platforms, forcing redundant system investments.
Strategic Opportunities
- Post-acute care transitions in Poland and Romania:Hospital capacity constraints in these markets are accelerating public tenders for home-based cardiac rehabilitation monitoring.
- EU AI Act compliance services:Algorithmic risk classification requirements for diagnostic monitoring features are creating adjacent revenue streams in clinical validation documentation.
- Pharmacy channel integration:Community pharmacy networks in France and Belgium are piloting RPM device dispensing alongside chronic medication fulfillment, bypassing traditional hospital procurement.
Industry Challenges
- Clinical evidence generation capacity:MDR recertification demands for real-world performance data are overwhelming regulatory affairs teams at mid-sized software vendors.
- Legacy EHR integration complexity:HL7 FHIR implementation gaps between RPM platforms and hospital information systems in the United Kingdom are requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Remote Patient Monitoring Systems Market |
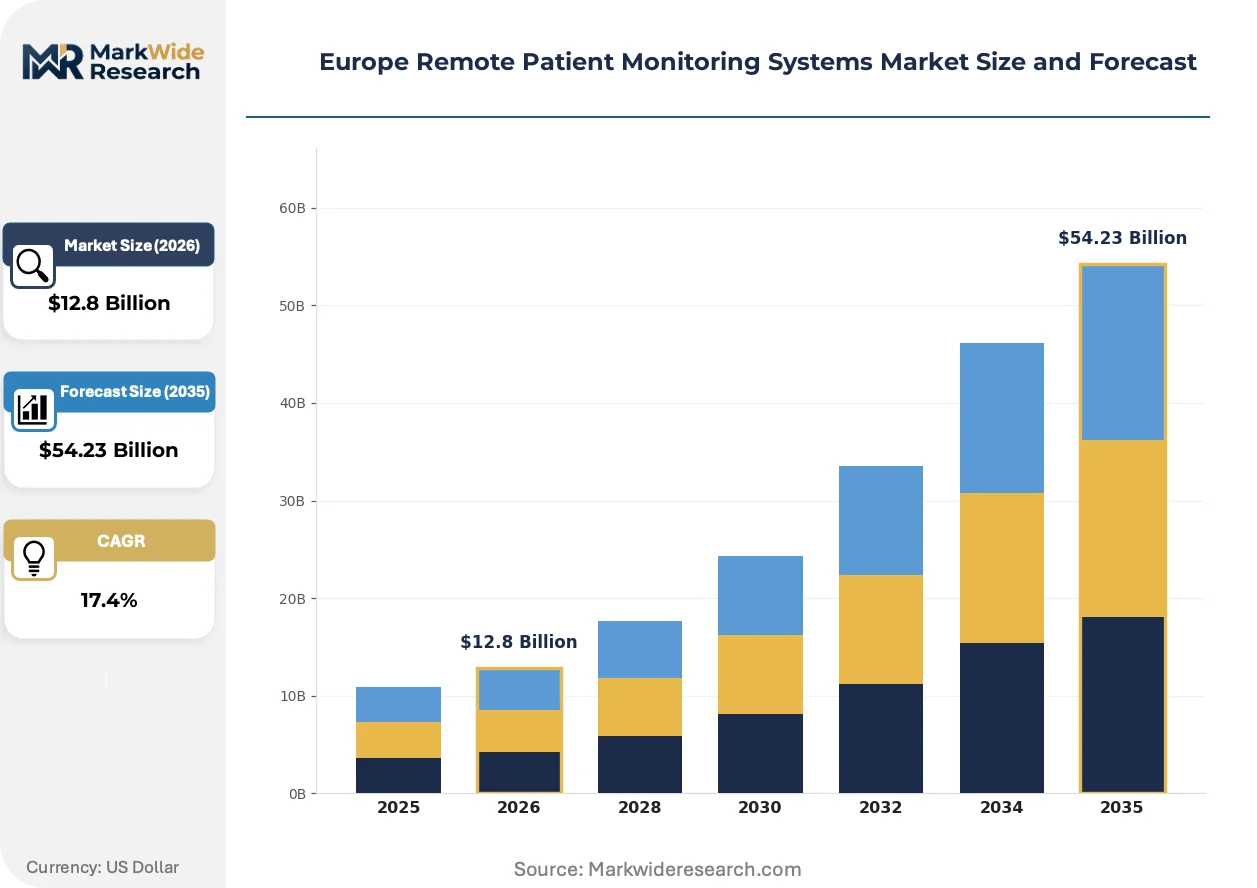
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $54.23 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
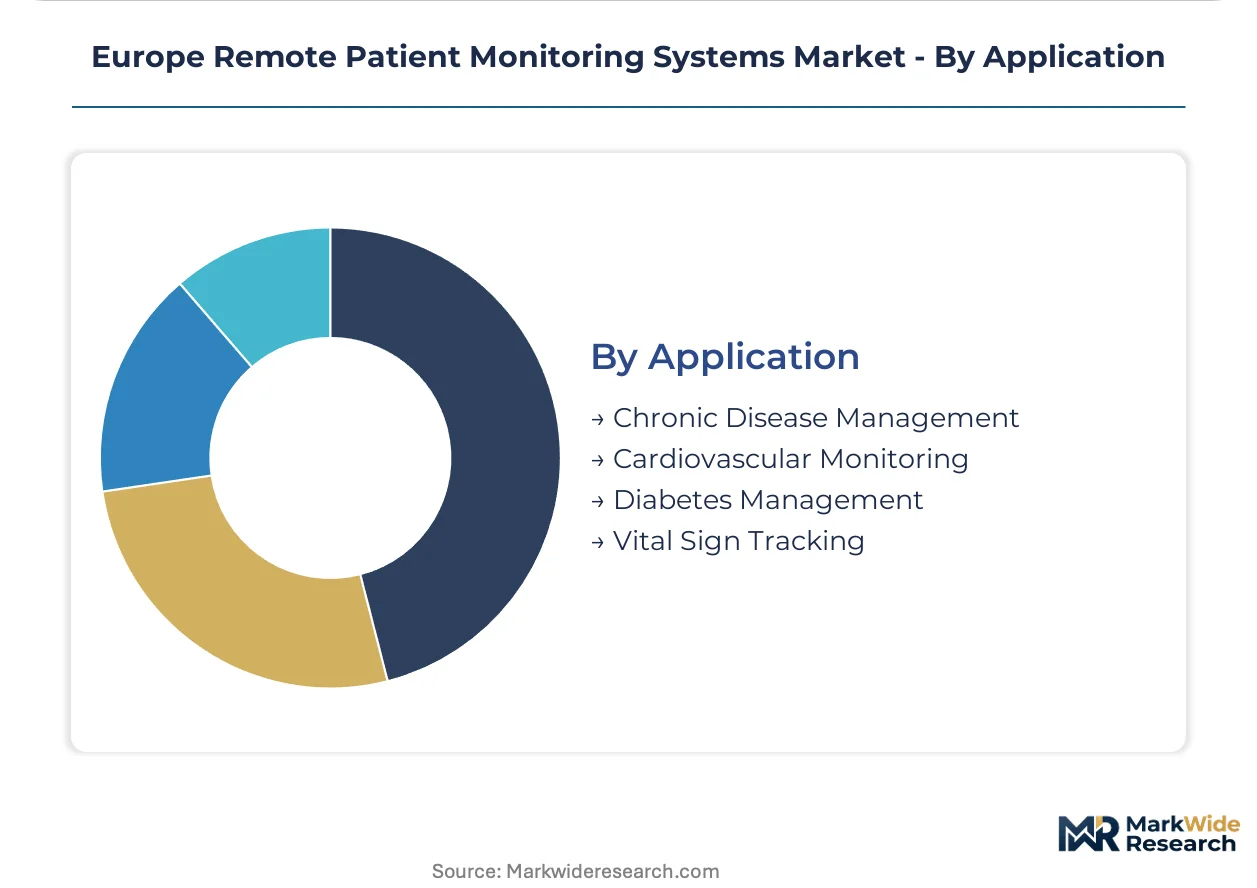
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Software Solutions, Mobile Applications Technology: Bluetooth, Wi-Fi, Cellular, Cloud-Based Systems End User: Hospitals, Home Care Providers, Clinics, Elderly Patients Application: Chronic Disease Management, Cardiovascular Monitoring, Diabetes Management, Vital Sign Tracking |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Koninklijke Philips N.V., Omron Healthcare, Masimo, Medtronic, Boston Scientific, Biotronik, GE Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Remote Patient Monitoring Systems Market Shifts & Advancements
Algorithmic diagnostic capabilities are migrating from cloud servers to device edge, driven by latency requirements for acute event detection and GDPR data localization mandates. This architectural shift is redistributing computational costs and clinical liability across the technology stack.
Continuous glucose monitoring systems with factory-calibrated sensors are supplanting traditional fingerstick glucometers in Type 2 diabetes management protocols. Endocrinology departments at university hospitals in Germany and Denmark are adopting these devices for outpatient titration programs. The elimination of user calibration is compressing training burdens while expanding addressable patient populations beyond insulin-dependent cohorts.
EMA guidance on software-as-a-medical-device is forcing RPM vendors to document clinical validation for algorithm-driven alert thresholds prior to CE marking. This regulatory clarification is diverting R&D expenditure toward prospective clinical trials and away from feature expansion. Cardiovascular monitoring applications face the steepest compliance gradient given the agency's heightened scrutiny of arrhythmia detection algorithms.
Hospital procurement committees are unbundling RPM device supply from data platform subscriptions, reversing earlier integrated contracting preferences. Acute care networks in France and the United Kingdom are now sourcing wearables through medical device tenders while separately negotiating software licenses. This bifurcation is pressuring vendors with captive hardware-software stacks to demonstrate standalone value propositions for each component.
Europe Remote Patient Monitoring Systems Market Segmentation
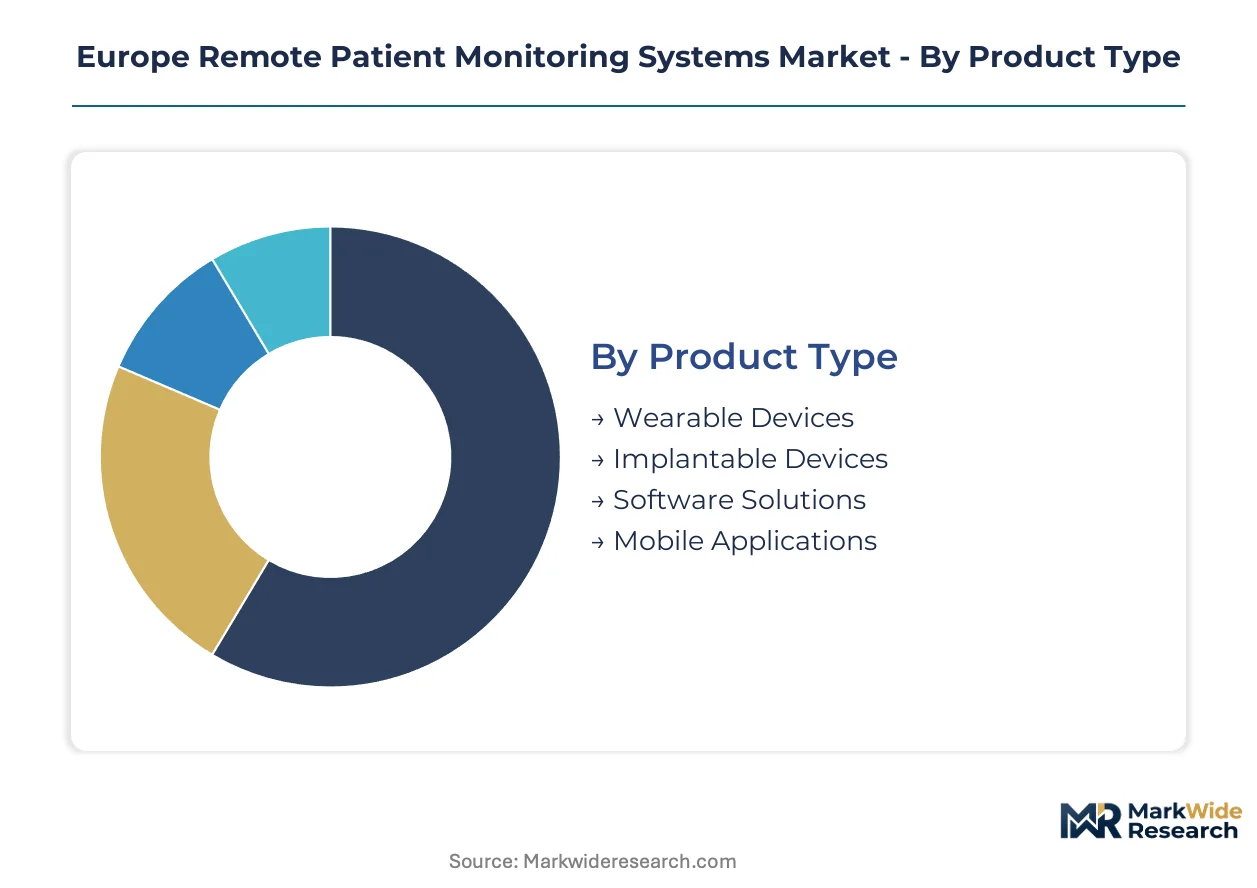
Segmentation in the Europe Remote Patient Monitoring Systems Market reveals distinct channel economics. Hospital procurement committees source hardware and software through separate tenders, while home care providers favor bundled subscription models.
Product Type:
Wearable devices flow through medical device distributors, implantable systems through specialized cardiac centers, and software platforms through direct enterprise sales.
- Wearable Devices:Factory-calibrated biosensors with Bluetooth Low Energy or cellular radios capture continuous glucose, blood pressure, and activity metrics. German disease management programs reimburse connected glucose meters and blood pressure cuffs, pulling volume through pharmacy and hospital outpatient channels.
- Software Solutions:Cloud-native platforms aggregate multi-device data streams and generate clinical alerts for care teams. GDPR-compliant architectures with edge processing are unlocking contracts in France and Belgium where cross-border data restrictions previously blocked procurement.
- Implantable Devices:Cardiac telemetry implants with subcutaneous leads transmit arrhythmia data via cellular networks.
- Mobile Applications:Companion apps for patient engagement and medication adherence run on iOS and Android.
By volume, Wearable Devices leads. By growth pace, Software Solutions is expanding most quickly.
Technology:
Connectivity choice determines addressable patient demographics and infrastructure dependency.
- Cellular:NB-IoT and LTE-M modules eliminate home Wi-Fi dependency for elderly patients in Spain and Italy. Network rollouts by telecom operators are enabling standalone devices that function in rural settings without broadband.
- Cloud-Based Systems:Centralized data aggregation platforms with AI-driven analytics require substantial clinical validation under EMA software-as-a-medical-device guidance. Danish and German university hospitals are piloting these systems for outpatient cardiac rehabilitation.
- Bluetooth:Low-energy radios pair wearables with patient smartphones for episodic data upload.
- Wi-Fi:Continuous streaming to home routers suits urban patients with reliable broadband.
Cellular-enabled systems command premium pricing. Bluetooth retains the largest installed base.
End User:
Customer type dictates purchasing authority, contract duration, and integration complexity.
- Hospitals:Acute care networks in the United Kingdom and France unbundle device procurement from software licensing, sourcing wearables through medical device tenders while negotiating separate platform agreements. HL7 FHIR integration gaps are forcing custom interface development.
- Home Care Providers:Community nursing organizations in Germany manage chronic disease patients through structured DMPs with explicit remote monitoring reimbursement. These providers favor multi-year subscriptions covering devices, connectivity, and clinical monitoring services.
- Clinics:Outpatient cardiology and endocrinology practices prescribe RPM for post-acute follow-up.
- Elderly Patients:Direct-to-patient channels remain limited by MDR conformity requirements and prescription workflows.
Hospitals generate the largest contract values. Home care providers show the steepest adoption curve.
Application:
Clinical use case determines regulatory pathway, evidence requirements, and reimbursement eligibility.
- Diabetes Management:Continuous glucose monitoring with factory-calibrated sensors is supplanting fingerstick glucometers in Type 2 protocols. German and Danish endocrinology departments deploy these for outpatient insulin titration without user calibration burden.
- Cardiovascular Monitoring:Arrhythmia detection algorithms face heightened EMA scrutiny, requiring prospective clinical trials before CE marking. This compliance gradient favors established vendors with in-house regulatory affairs capabilities.
- Chronic Disease Management:Multi-condition platforms address diabetes, hypertension, and heart failure through unified dashboards.
- Vital Sign Tracking:General physiological monitoring supports post-surgical recovery and wellness programs.
Diabetes Management holds the deepest reimbursement penetration. Cardiovascular Monitoring carries the highest regulatory barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
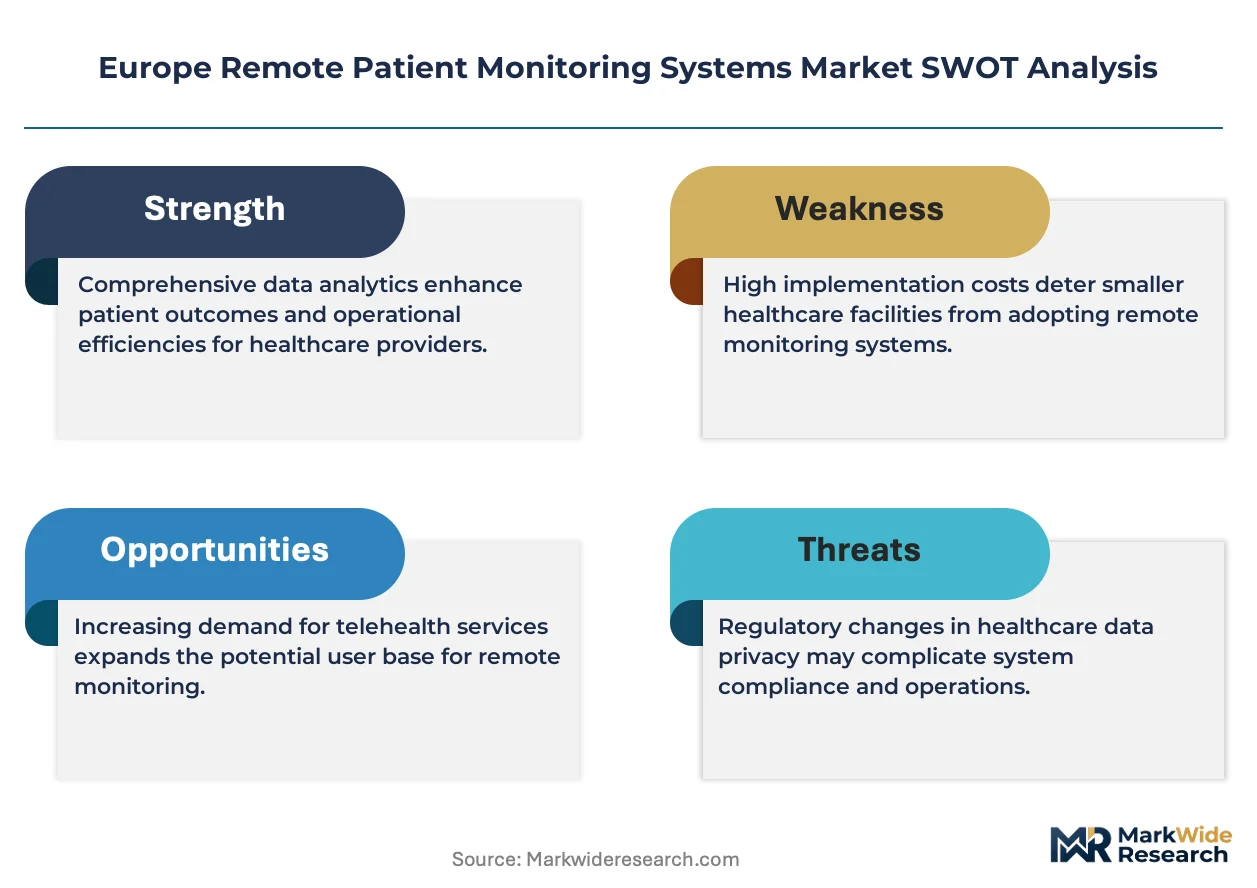
Germany's structured disease management programs and France's hospital procurement reforms are accelerating RPM deployment across Western Europe. The EU Medical Device Regulation is harmonizing compliance requirements while creating divergent adoption timelines across member states.
Germany
Bavarian university hospitals pilot continuous glucose monitoring for outpatient insulin titration without calibration burden. The Federal Joint Committee (G-BA) mandates remote monitoring reimbursement within structured disease management programs for diabetes and cardiovascular conditions. Berlin-Brandenburg hosts Siemens Healthineers' regulatory affairs hub managing MDR conformity assessments for connected diagnostic platforms.
France
Hospital procurement committees in Île-de-France unbundle device tenders from software licensing agreements. ANSM guidance on software-as-a-medical-device requires clinical validation documentation for algorithm-driven alert thresholds. The Lyon-Grenoble corridor concentrates cardiac telemetry manufacturing with specialized production of implantable monitoring devices.
United Kingdom
HL7 FHIR implementation gaps between RPM platforms and hospital information systems force costly custom interface development. NHS England's MedTech Funding Mandate accelerates procurement of digitally enabled care technologies for chronic disease management. The Greater Manchester health innovation cluster tests cellular-enabled monitoring for post-acute cardiac rehabilitation in underserved communities.
Spain
Telefónica's NB-IoT network rollout eliminates home Wi-Fi dependency for elderly patients in rural Castile and Andalusia. The Spanish Agency for Medicines and Health Products (AEMPS) enforces MDR conformity timelines that extend market access for Class IIa software devices. Barcelona's digital health ecosystem hosts pilot programs integrating pharmacy dispensing with remote monitoring device distribution.
Netherlands
Notified body capacity constraints in Utrecht and Amsterdam extend time-to-market for software-enabled monitoring systems by 12-18 months. The Healthcare and Youth Inspectorate (IGJ) coordinates with EMA on software-as-a-medical-device classification for AI-enhanced diagnostic features. Eindhoven's semiconductor cluster supplies edge computing components for GDPR-compliant local data processing architectures.
Europe Remote Patient Monitoring Systems Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with imaging and diagnostic heritage alongside specialized cardiac monitoring firms. The competitive structure tiers across established device manufacturers with in-house regulatory capabilities, software-native platforms seeking hardware partnerships, and implantable specialists with deep clinical evidence portfolios. Strategic moves concentrate on MDR conformity assessment navigation and unbundled procurement positioning to capture hospital tenders.
Within the diversified medical technology tier, Siemens Healthineers and Koninklijke Philips N.V. exemplify contrasting geographic anchoring strategies. Siemens Healthineers occupies a position leveraging German-speaking market proximity for hospital-centric deployments. Koninklijke Philips N.V. represents broad home-monitoring portfolio architecture competing on acute care network interoperability. Abbott Laboratories sits within the specialized monitoring tier, with factory-calibrated sensor technology anchoring diabetes management protocol adoption.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Omron Healthcare |
| Masimo |
| Medtronic |
| Boston Scientific |
| Biotronik |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
CE marking under the EU Medical Device Regulation gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified hardware vendors while rewarding established manufacturers with in-house regulatory affairs capabilities. German hospital procurement committees exploit this bifurcation to extract pricing concessions from software-native platforms lacking MDR conformity infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: CE-marked Class IIa devices with clinical validation documentation command subscription premiums, uncertified wellness trackers compete on per-unit transactional pricing, and mid-tier Bluetooth-enabled sensors occupy hybrid licensing arrangements. Cost compression in cellular-enabled systems is intensifying because NB-IoT module suppliers face foundry capacity constraints. Home care providers show acute price sensitivity compared to hospital procurement committees with centralized tender budgets.
Supply Chain Analysis
Taiwan and South Korea anchor MEMS accelerometer and optical PPG module fabrication for European device manufacturers. Optical sensor arrays and lithium-polymer batteries draw from concentrated Asian foundries, while edge computing components for GDPR-compliant architectures source from Eindhoven's semiconductor cluster. Single-source vulnerability in Taiwanese wafer supply exposes production schedules to geopolitical interruption. Distribution runs through medical device distributors for hardware, direct enterprise sales for software platforms, and pharmacy networks for patient-facing peripherals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among French and German hospital procurement committees as unbundled tendering for devices and software reduces vendor switching costs. This consolidation fragments pricing power across the supply base.
For Market Incumbents: Fortify regulatory affairs capabilities to accelerate MDR recertification timelines for legacy connected devices. Deepen backward integration into edge computing component supply to mitigate Taiwanese foundry concentration risk. Capture pharmacy channel partnerships in France and Belgium before software-native platforms establish dispensing relationships. For New Entrants and Emerging Players: Anchor in post-acute cardiac rehabilitation monitoring for Poland and Romania where hospital capacity constraints accelerate public tender activity. Community nursing organizations in German disease management programs offer the most penetrable entry point. Pursue white-label manufacturing partnerships with established CE-marked hardware suppliers to bypass 12-18 month notified body bottlenecks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across software-as-a-medical-device segments as EMA guidance forces prospective clinical trial expenditure. Long-term viability favors diversified medical technology conglomerates with imaging heritage and in-house regulatory infrastructure over pure-play software platforms. Target acquisition profiles emphasize vendors with completed MDR conformity assessments and existing hospital system integration contracts. The signal to watch is notified body capacity expansion announcements in Germany and the Netherlands as inflection indicators for software device time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment completion unlocks hospital procurement committee eligibility across German-speaking markets. |
| Hospital System Partnership | Integration with NHS England's MedTech Funding Mandate accelerates digitally enabled care technology adoption. |
| Software Companion Development | EMA guidance on algorithm-driven diagnostics demands clinical validation documentation before market authorization. |
| Reimbursement Strategy | G-BA mandates within German disease management programs create institutional pull for connected monitoring interventions. |
| Geographic Expansion | Telefónica's NB-IoT rollout in Spain eliminates home Wi-Fi dependency for elderly rural patient segments. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs directors and secondary validation through EMA guidance documents anchors the qualitative findings. Clinicians at Bavarian university hospitals, biomedical engineers at Berlin-Brandenburg device manufacturers, GPO contracts managers at French hospital procurement committees, and pharmacy network operators in Belgium contributed field perspectives. Bottom-up triangulation against hospital procurement databases and top-down validation through customs records for MEMS component imports shaped segment-level estimates.
Sensitivity analysis around notified body capacity constraints and cellular module supply disruption scenarios stress-tested analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, connectivity technology, end user archetype, and clinical application with regulatory pathway complexity as an industry-specific overlay. CAGRs derived from logistic adoption curves for cellular-enabled systems and linear penetration assumptions for software platforms incorporated Danish and German university hospital pilot program expansion rates as forecast inputs.
Material uncertainties — MDR recertification timeline extensions, geopolitical interruption of Taiwanese foundry supply, and NHS England HL7 FHIR implementation delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory capacity expansion and reimbursement policy continuity. Recalibration cycles align with material shifts in notified body staffing levels and EMA software-as-a-medical-device guidance revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market