
 Wireless Healthcare Market | 2026-2036
Wireless Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Healthcare Market Intelligence
Specialized biomedical engineering talent is bifurcating the competitive landscape, with firms that retain RF-integrated circuit designers pulling ahead of pure-software entrants. Qualcomm Technologies sustains technology leadership in low-power wireless protocols for implantable sensors. GE HealthCare Technologies Inc. anchors hospital-grade telemetry through its dominant position in FDA-cleared patient monitoring hardware. Apple Inc. leverages consumer-scale manufacturing to drive down per-unit sensor costs for wrist-worn health trackers.
Wireless healthcare encompasses medical-grade data transmission between patients, devices, and clinical systems using unlicensed and licensed spectrum bands, typically operating at 2.4 GHz ISM, sub-1 GHz medical body area network frequencies, or cellular LTE-M/NB-IoT channels with latency requirements under 250 milliseconds for critical alarms. Its primary purpose is to enable continuous physiological monitoring outside traditional clinical settings while maintaining HIPAA-compliant data integrity. Wearable devices command the deepest margin pools due to recurring sensor replacement cycles and subscription analytics revenue. Remote monitoring systems dominate hospital procurement budgets as Medicare reimbursement shifts toward episode-based payment models. Telehealth solutions represent the fastest-expanding segment as rural health networks deploy cellular-connected diagnostic carts to extend specialist reach.
FDA premarket cybersecurity guidance and HIPAA Security Rule enforcement shape device design requirements, mandating encrypted over-the-air updates and audit-logged data flows for network-connected diagnostics. The EU MDR and GDPR jointly constrain cross-border patient data routing, forcing manufacturers to architect region-specific cloud instances for European deployments. Stakeholders must monitor spectrum allocation battles between medical device manufacturers and consumer IoT vendors in the sub-6 GHz range, as FCC rulings on coexistence protocols will determine which connectivity standards achieve clinical adoption lock-in.
Market Dynamics
Chronic disease management protocols are compressing care delivery timelines, forcing device manufacturers to engineer continuous glucose monitors and cardiac telemetry systems that transmit clinical-grade data through unlicensed spectrum bands while maintaining sub-250-millisecond alarm latency.
Growth Catalysts
- Medicare episode-based reimbursement:Hospital procurement committees now prioritize remote patient monitoring hardware that reduces 30-day readmission penalties. This payment model accelerates capital deployment into wireless telemetry infrastructure.
- Sub-1 GHz medical body area network adoption:Home care providers deploy wearable sensors operating in protected spectrum allocations to avoid interference from consumer Wi-Fi and Bluetooth traffic in dense residential environments.
- Germany's national digital health infrastructure:The country's statutory health insurance digitization mandate creates institutional demand for interoperable patient monitoring platforms that route encrypted physiological data to electronic health record systems.
Market Restraints
- RF-integrated circuit supply concentration:Foundry capacity for ultra-low-power radio transceivers concentrates among Taiwan-based semiconductor manufacturers, exposing device makers to geopolitical disruption risk and allocation constraints.
- FDA premarket cybersecurity documentation:The agency's 2023 guidance mandates encrypted over-the-air update architectures and software bill of materials submissions, extending design validation cycles by 8-14 months for network-connected diagnostics.
- Legacy hospital IT integration friction:Existing patient data management systems built on proprietary middleware resist seamless API connectivity with cloud-native wireless sensor platforms, forcing expensive gateway hardware purchases.
Strategic Opportunities
- Rural cellular-connected diagnostic carts:Telehealth solution vendors can capture underserved specialist access gaps in Montana, Wyoming, and Alaska by deploying LTE-M-connected examination equipment to primary care clinics lacking fiber infrastructure.
- EU MDR-GDPR convergent compliance services:Manufacturers serving European markets require region-specific cloud instances with audit-logged data flows, creating recurring revenue opportunities for managed security providers.
- AI-enhanced arrhythmia detection at the edge:On-device machine learning inference for cardiac event classification reduces cloud transmission costs and enables real-time clinical decision support without continuous connectivity.
Industry Challenges
- Biomedical RF engineering talent scarcity:Firms compete for hardware designers capable of integrating antenna miniaturization with FCC Part 15 compliance testing, compressing development timelines for implantable sensor programs.
- Multi-jurisdiction certification parallelism:Simultaneous FDA 510(k), EU MDR technical documentation, and PMDA Shonin submissions require dedicated regulatory affairs teams with jurisdiction-specific submission expertise.
- HIPAA Security Rule audit preparation:Business associate agreements with cloud infrastructure providers demand documented encryption key management and access control matrices that strain lean device startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Healthcare Market |
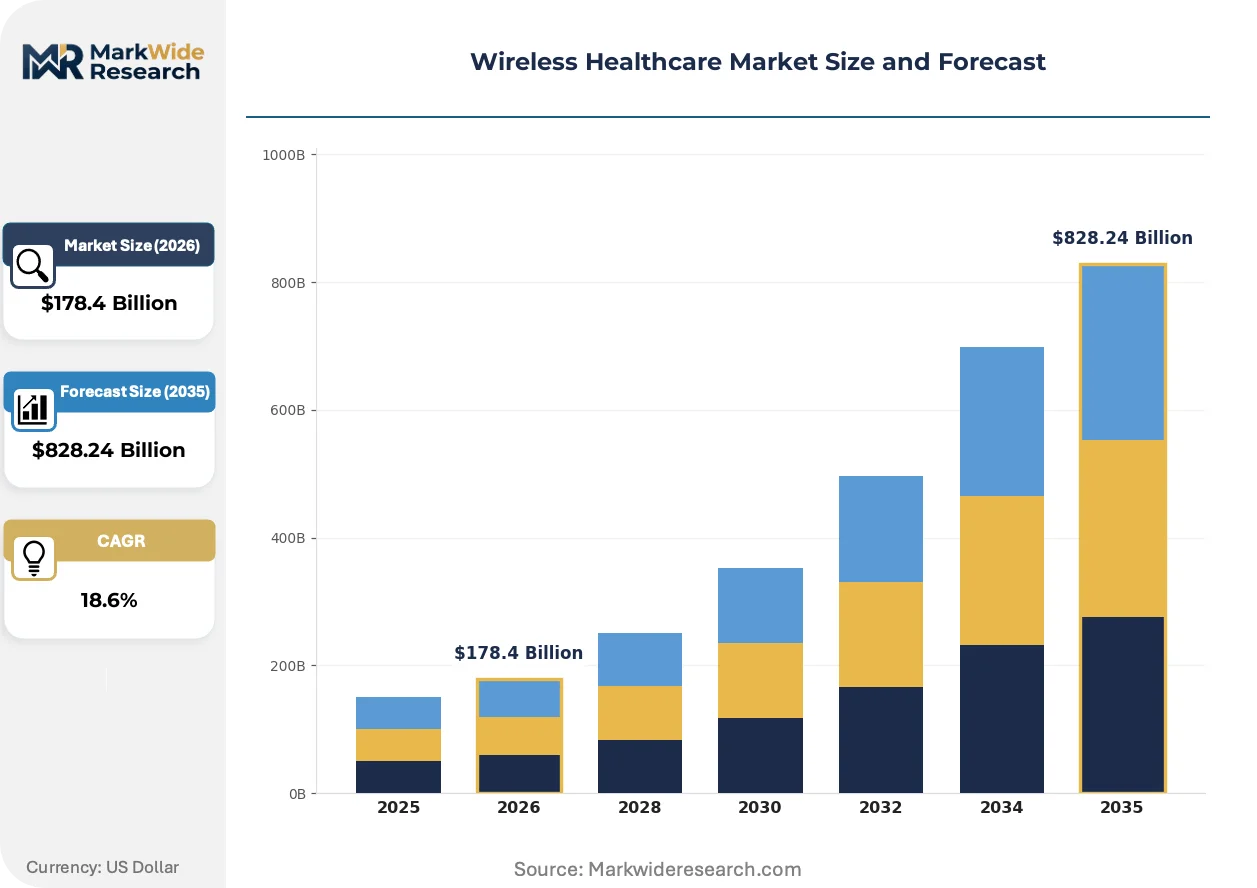
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $828.24 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Systems, Mobile Health Applications, Telehealth Solutions End User: Hospitals, Clinics, Home Care Providers, Rehabilitation Centers Technology: Bluetooth, Wi-Fi, Cellular, NFC Application: Chronic Disease Management, Fitness Tracking, Telemedicine, Emergency Response |
| Companies Covered | GE HealthCare Technologies Inc., Siemens Healthcare GmbH, AT&T Inc., Cisco Systems, Inc., Qualcomm Technologies, Inc., Samsung Electronics Co., Ltd, Verizon Communication Inc., Apple Inc., Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Healthcare Market Strategic Shifts & Innovations
Spectrum allocation politics and edge computing architectures are reconfiguring how physiological data flows between patients, devices, and clinical decision-makers. Three distinct vectors are compressing legacy connectivity models.
Ultra-wideband positioning for indoor patient tracking is fragmenting the real-time location systems market previously dominated by Wi-Fi triangulation. Hospital facilities management teams in Texas and Florida deploy centimeter-accurate wearable tags to automate bed turnover workflows and reduce emergency department boarding times. This precision is compressing capital budgets previously allocated to infrared and ultrasonic alternatives.
FDA's 2023 premarket cybersecurity guidance is mandating encrypted over-the-air update capabilities for all network-connected diagnostic devices. Manufacturers must architect secure bootloaders and cryptographic key provisioning infrastructure that previously existed only in defense and financial hardware. Implantable sensor developers face the steepest compliance burden, as firmware vulnerabilities in cardiac pacemakers and neurostimulators carry irreversible patient safety consequences.
Episode-based payment models are consolidating purchasing authority within hospital value analysis committees. These committees now demand wireless monitoring platforms that demonstrate measurable reductions in 30-day readmission rates for heart failure and COPD populations. Vendors must produce peer-reviewed outcome data from specific health systems to advance past pilot contracts into multi-year enterprise agreements.
Wireless Healthcare Market Segmentation
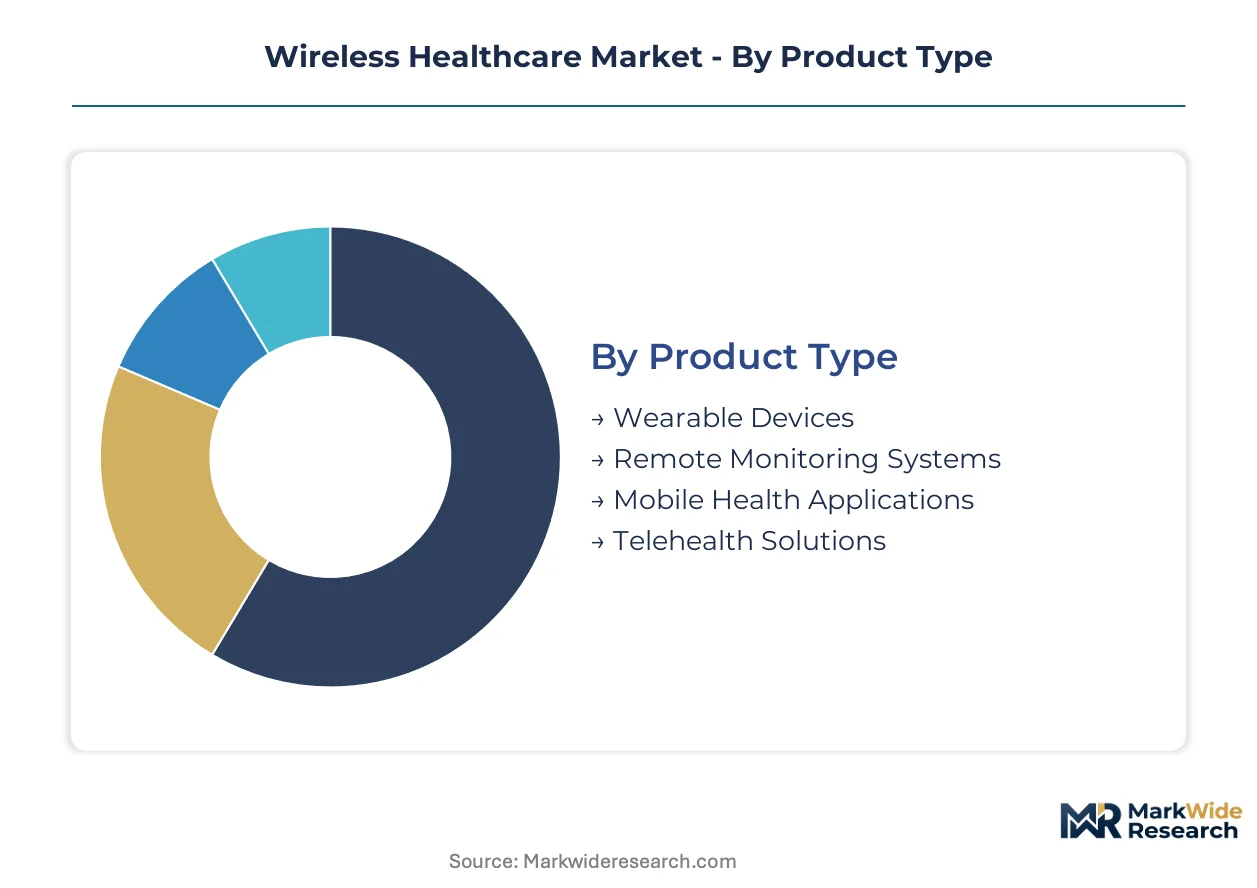
Wireless healthcare vendors engineer distinct hardware-software bundles for each application context, as reimbursement pathways and regulatory scrutiny vary sharply between hospital telemetry and consumer wellness tracking. Segmentation reveals where capital deployment concentrates and which connectivity standards achieve clinical lock-in.
Product Type:
Wearable devices capture the deepest margin pools through recurring sensor replacement cycles and subscription analytics revenue, while remote monitoring systems anchor hospital procurement budgets under episode-based payment models.
- Wearable Devices:Wrist-worn and patch-based sensors integrate accelerometers, optical heart rate monitors, and temperature transducers for continuous ambulatory monitoring. Demand concentrates among home care providers in Germany and Japan as statutory insurance frameworks expand reimbursement for preventive physiological tracking.
- Remote Monitoring Systems:FDA-cleared bedside telemetry and implantable cardiac monitors transmit through dedicated RF channels to cloud-based clinical dashboards. Hospital procurement committees in the United States prioritize these systems for heart failure populations facing Medicare readmission penalties.
- Mobile Health Applications:Smartphone-integrated software platforms aggregate consumer sensor data and deliver medication adherence prompts.
- Telehealth Solutions:Cellular-connected diagnostic carts and video consultation platforms extend specialist reach into infrastructure-constrained regions.
Wearable devices hold installed capacity. Telehealth solutions are rotating up the share rankings.
End User:
Volume concentration tilts toward institutional purchasers with centralized IT budgets, though home care providers are expanding fastest as reimbursement shifts to community-based chronic disease management.
- Hospitals:Acute care facilities deploy enterprise-grade wireless telemetry infrastructure with sub-250-millisecond alarm latency and HIPAA-compliant audit logging. Value analysis committees in Texas and Florida health systems consolidate purchasing authority under episode-based payment mandates.
- Clinics:Outpatient facilities adopt LTE-M-connected diagnostic equipment to extend specialist access without fiber infrastructure. Rural primary care networks in Montana and Wyoming drive procurement of cellular-enabled examination carts.
- Home Care Providers:Medicare-certified agencies deploy wearable sensors and remote patient monitoring platforms for post-acute care transitions.
- Rehabilitation Centers:Skilled nursing and physical therapy facilities integrate motion-tracking wearables for functional recovery protocols.
Hospitals hold installed capacity. Home care providers are climbing the fastest.
Technology:
Connectivity standard selection determines power budget, range, and interference resilience, with sub-1 GHz medical body area networks gaining preference in dense residential deployments.
- Bluetooth:Low-energy protocols at 2.4 GHz ISM enable wrist-worn health trackers with multi-year battery life. Apple and Qualcomm drive silicon integration that compresses per-unit radio costs for consumer-scale manufacturing.
- Cellular:LTE-M and NB-IoT channels provide wide-area coverage for diagnostic carts and implantable sensors requiring continuous cloud connectivity. FCC rulings on sub-6 GHz spectrum coexistence determine which medical device standards achieve clinical adoption lock-in.
- Wi-Fi:Hospital-grade 802.11 networks support high-bandwidth telemetry for multi-parameter bedside monitors.
- NFC:Near-field protocols enable tap-to-pair device provisioning and medication authentication workflows.
Bluetooth holds installed capacity. Cellular is gaining share fastest.
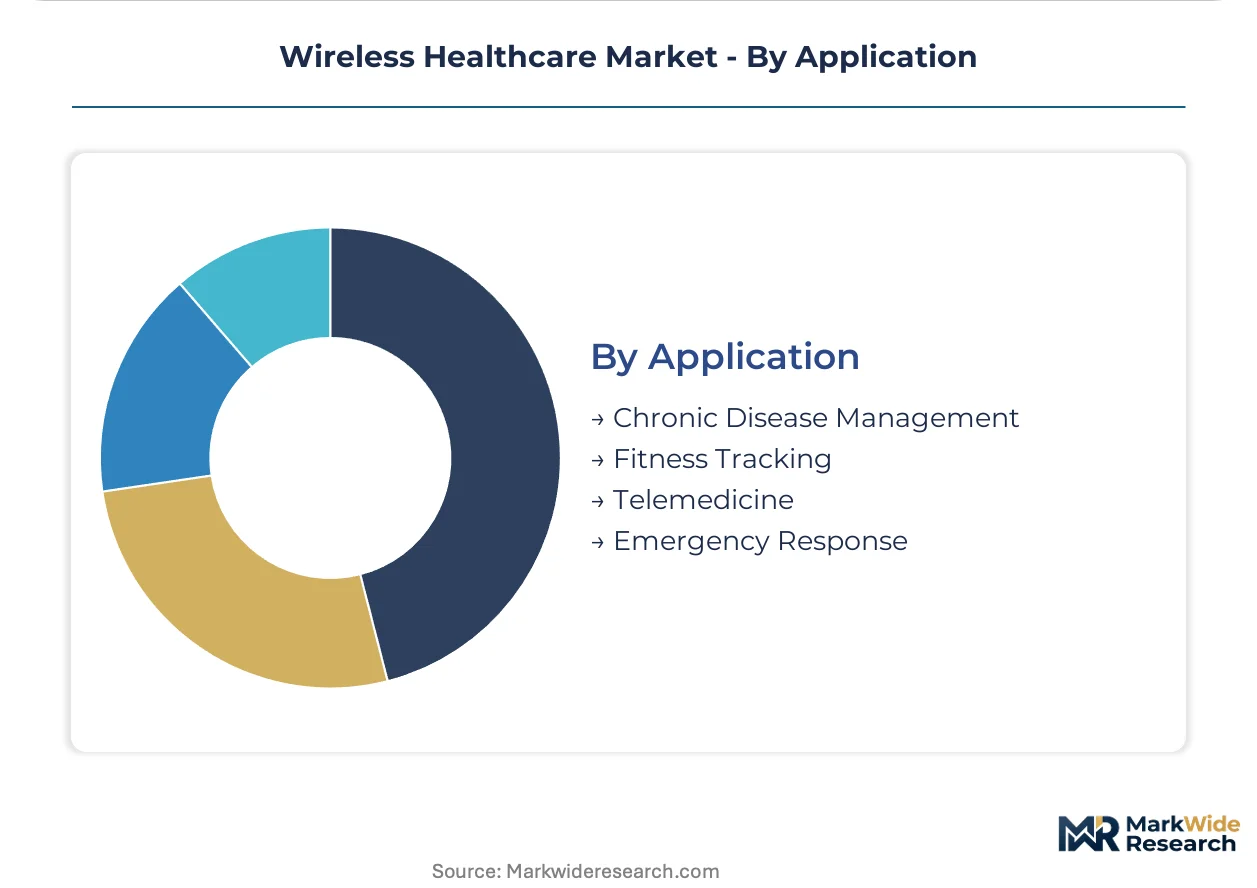
Application:
Clinical-grade applications command premium pricing against consumer wellness tracking, as FDA cybersecurity documentation and HIPAA interoperability rules reshape certification requirements.
- Chronic Disease Management:Continuous glucose monitors, cardiac telemetry systems, and pulmonary function sensors transmit clinical-grade data through protected spectrum allocations. Germany's statutory health insurance digitization mandate creates institutional demand for interoperable platforms routing encrypted data to electronic health record systems.
- Telemedicine:Synchronous video consultation and asynchronous store-and-forward diagnostic imaging extend specialist access. Rural health networks in Alaska deploy cellular-connected carts to bridge geography-constrained care gaps.
- Fitness Tracking:Consumer wellness devices aggregate activity metrics without clinical-grade accuracy requirements.
- Emergency Response:Fall detection and automated alert systems connect patients to emergency services through redundant connectivity paths.
Chronic disease management holds installed capacity. Telemedicine is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems prioritize FDA-cleared telemetry for Medicare reimbursement compliance, while German providers emphasize GDPR-compliant interoperability with statutory insurance digitization mandates. Japanese deployment patterns concentrate on aging-population remote monitoring distinct from the wearable-centric adoption in North American home care markets.
United States
Hospital value analysis committees in Texas and Florida consolidate purchasing authority for wireless telemetry platforms that reduce 30-day readmission penalties under episode-based payment models. FDA premarket cybersecurity guidance mandates encrypted over-the-air update architectures, extending design validation cycles. The Boston-Cambridge corridor anchors implantable sensor development with specialized biomedical RF engineering talent pools.
Germany
Statutory health insurance digitization mandates create institutional demand for interoperable patient monitoring platforms routing encrypted physiological data to electronic health record systems. EU MDR technical documentation requirements and GDPR jointly constrain cross-border patient data routing, forcing region-specific cloud architectures. The Munich-Stuttgart industrial corridor concentrates medical device manufacturing with embedded connectivity expertise.
Japan
PMDA Shonin certification requirements shape device design for cardiac telemetry and neurostimulator systems serving the world's oldest population demographics. METI funding for national digital health infrastructure accelerates deployment of home-based remote monitoring for post-acute care transitions. The Kansai region around Osaka anchors manufacturing partnerships between consumer electronics conglomerates and specialized medical device fabricators.
United Kingdom
NHS England procurement frameworks prioritize wireless monitoring solutions demonstrating measurable reductions in emergency department boarding times and hospital length-of-stay. MHRA post-Brexit regulatory divergence from EU MDR creates parallel certification pathways for network-connected diagnostics. The Oxford-Cambridge-London golden triangle concentrates digital health venture capital and clinical validation partnerships.
South Korea
MFDS regulatory pathways for software-as-a-medical-device accelerate commercialization timelines for AI-enhanced arrhythmia detection algorithms. National health insurance reimbursement for remote patient monitoring expands addressable markets for cellular-connected diagnostic platforms. The Seoul Capital Area anchors conglomerate-led health technology divisions with captive semiconductor fabrication capabilities.
Wireless Healthcare Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in wireless healthcare, with hospital-grade telemetry vendors and consumer-scale sensor manufacturers occupying distinct competitive planes. Semiconductor conglomerates with RF-integrated circuit design capabilities supply foundational connectivity silicon to downstream device OEMs. Strategic differentiation concentrates on three archetypes: FDA-cleared medical hardware specialists, consumer electronics platforms with health-tracking extensions, and telecommunications infrastructure providers enabling cellular-connected care delivery. Competitive moves center on M&A targeting biomedical engineering talent and strategic partnerships securing spectrum allocation advantages in sub-6 GHz bands.
Within the integrated medical hardware tier, GE HealthCare Technologies Inc. and Siemens Healthcare GmbH exemplify hospital-grade telemetry specialists with established regulatory affairs infrastructure spanning FDA 510(k) and EU MDR pathways. Qualcomm Technologies, Inc. anchors the foundational silicon layer, supplying low-power wireless protocols that enable implantable sensor miniaturization. Apple Inc. occupies a distinct position bridging consumer-scale manufacturing economics with health-tracking functionality expansion.
| Leading Market Players |
|---|
| GE HealthCare Technologies Inc. |
| Siemens Healthcare GmbH |
| AT&T Inc. |
| Cisco Systems, Inc. |
| Qualcomm Technologies, Inc. |
| Samsung Electronics Co., Ltd |
| Verizon Communication Inc. |
| Apple Inc. |
| Philips |
| Others |
Cost & Logistics Intelligence
Twenty-two-week lead times for FDA 510(k) cleared implantable sensors concentrate pricing power among Taiwan-based RF foundry operators, while hospital procurement committees exploit volume scale to compress per-unit telemetry hardware costs. This inventory-to-certification lag structurally advantages incumbents with pre-validated supplier relationships against lean device startups facing allocation constraints.
Pricing Analysis
Long-term offtake contracts dominate hospital enterprise agreements for remote patient monitoring platforms, while spot purchasing persists for consumer-grade wearable sensors. Three-tier pricing structure across FDA-cleared medical, CE-marked clinical, and wellness-grade consumer tiers separates premium telemetry hardware from standard wearable trackers. Pricing pressure stems from Medicare episode-based reimbursement compressing capital equipment budgets, with home care providers exhibiting highest price sensitivity versus acute care value analysis committees prioritizing outcome guarantees.
Supply Chain Analysis
Ninety-day inventory buffers for sub-1 GHz medical body area network transceivers expose device makers to Taiwan, South Korea, and China foundry allocation volatility. RF-integrated circuits, lithium-polymer batteries, and medical-grade polymers constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan semiconductor manufacturing, while distribution runs through hospital GPO contracts and direct-to-provider digital health platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless healthcare hardware margins are compressing toward commodity levels, yet recurring sensor replacement cycles and subscription analytics revenue layers expand faster than device sales. This service-attach dynamic repositions competitive advantage toward platform stickiness rather than unit shipment volume.
For Market Incumbents: Consolidate biomedical RF engineering talent pools in the Boston-Cambridge corridor through targeted acquisition of implantable sensor design boutiques. Defend against pure-software entrants by deepening backward integration into secure bootloader firmware and cryptographic key provisioning infrastructure mandated by FDA cybersecurity guidance.
For New Entrants and Emerging Players: Lead with AI-enhanced arrhythmia detection at the edge for rural primary care networks in Montana, Wyoming, and Alaska lacking fiber infrastructure. Capture underserved specialist access gaps through LTE-M-connected diagnostic carts, deploying direct-to-clinic subscription models bypassing hospital value analysis committee gatekeeping.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory moat play because FDA premarket cybersecurity documentation and multi-jurisdiction certification parallelism create 8-14 month validation barriers that favor incumbents with dedicated regulatory affairs infrastructure. Watch for FCC rulings on sub-6 GHz spectrum coexistence protocols as inflection indicators determining which connectivity standards achieve clinical adoption lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Episode-based payment models reward vendors demonstrating measurable 30-day readmission reductions in heart failure populations. |
| Software Companion Development | On-device machine learning inference for cardiac event classification reduces cloud transmission costs and enables real-time clinical decision support. |
| FDA Submission | Premarket cybersecurity guidance mandates encrypted over-the-air update architectures extending design validation cycles for network-connected diagnostics. |
| CE Marking Pathway | EU MDR technical documentation requirements and GDPR jointly constrain cross-border patient data routing forcing region-specific cloud architectures. |
| Reimbursement Strategy | Medicare-certified home care agencies expand addressable markets for post-acute care transition monitoring under statutory reimbursement frameworks. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and remote patient monitoring platform executives; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and FCC spectrum allocation rulings. Bottom-up telemetry hardware shipment estimates triangulated with top-down digital health infrastructure spending forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by product type, end user, connectivity technology, and application context. CAGRs derived from regression analysis of historical Medicare reimbursement shifts, statutory insurance digitization mandates, and RF semiconductor foundry capacity expansion trajectories. Industry-specific forecast inputs incorporated PMDA Shonin certification timelines and EU MDR-GDPR convergent compliance cost structures.
The analysis sits within stated boundaries; outcomes outside current FDA cybersecurity guidance enforcement levels, Taiwan foundry allocation stability, or Medicare episode-based payment model continuity would require recalibration. Forecasts reflect documented assumptions regarding spectrum coexistence protocol adoption and hospital IT middleware integration friction. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Critical Care Patient Monitoring Products Market