
 Bedside Monitors Market | 2026-2036
Bedside Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Bedside Monitors Market Analytics
China is reconfiguring regional supply chains for critical care devices through expanded domestic manufacturing zones. Philips Healthcare leverages vertical integration across sensor modules and display systems to sustain margin control. GE Healthcare anchors North American hospital procurement networks with established service infrastructure. Mindray Medical competes aggressively on cost-engineered multi-parameter platforms for mid-tier facilities.
Bedside monitors are electrophysiological measurement systems that track heart rate, blood oxygen saturation, respiratory rate, and invasive pressures through modular parameter acquisition modules, typically displaying data on 10-15 inch high-resolution screens for continuous patient surveillance in acute care settings. Multi-parameter monitors dominate installed base value as hospitals consolidate fragmented monitoring onto unified platforms. Wireless technology segments expand fastest as telemetry-enabled devices reduce cabling hazards and enable step-down unit mobility. Portable monitors occupy niche margin pools in emergency medical services where battery endurance and ruggedization command price premiums.
FDA 510(k) clearance pathways and IEC 60601-1-8 alarm safety standards govern device commercialization, with the former mandating substantial equivalence demonstrations and the latter enforcing prioritized auditory alarm differentiation to reduce clinician desensitization. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for class IIa and above patient monitors, lengthening certification timelines for non-European manufacturers. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC 80001-1 risk management frameworks as network-connected devices proliferate across hospital IT ecosystems.
Market Dynamics
Wireless telemetry integration is compressing installation cycles and displacing hardwired architectures across tertiary hospital networks, forcing manufacturers to reconfigure hardware-software bundles around FDA cybersecurity guidance and IEC 80001-1 risk management protocols.
Growth Catalysts
- ICU bed expansion:Tertiary hospitals in the United States, Germany, and Japan are adding high-acuity capacity to serve aging patient populations with complex comorbidities requiring continuous multi-parameter surveillance.
- FDA 510(k) pathway efficiency:Substantial equivalence demonstrations for modular parameter upgrades accelerate product iteration cycles compared to de novo classification routes.
- IEC 60601-1-8 compliance:Mandated alarm safety differentiation reduces clinician desensitization and drives replacement demand for legacy auditory systems in acute care settings.
Market Restraints
- Semiconductor supply concentration:Sensor module fabrication depends on concentrated Asian foundry capacity, creating input volatility for analog front-end components.
- EU MDR clinical evidence requirements:Enhanced documentation burdens for class IIa patient monitors lengthen certification timelines and inflate regulatory compliance costs for non-European manufacturers.
- Wireless interference limitations:2.4 GHz spectrum congestion in dense hospital environments constrains real-time telemetry reliability for mobile monitoring applications.
Strategic Opportunities
- Step-down unit mobility:Telemetry-enabled portable monitors address unmet demand in intermediate care settings where patient ambulation accelerates recovery protocols.
- China domestic manufacturing zones:Expanded regional production clusters for critical care devices reduce import dependency and create localized supply alternatives.
- AI-enhanced alarm analytics:Machine learning integration with multi-parameter streams enables predictive deterioration detection, differentiating premium platform offerings.
Industry Challenges
- Embedded systems cybersecurity expertise:Hospital IT ecosystem integration demands specialized firmware engineering talent scarce among traditional device manufacturers.
- Legacy infrastructure interoperability:Proprietary data protocols in installed base systems complicate seamless connectivity with next-generation wireless platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedside Monitors Market |
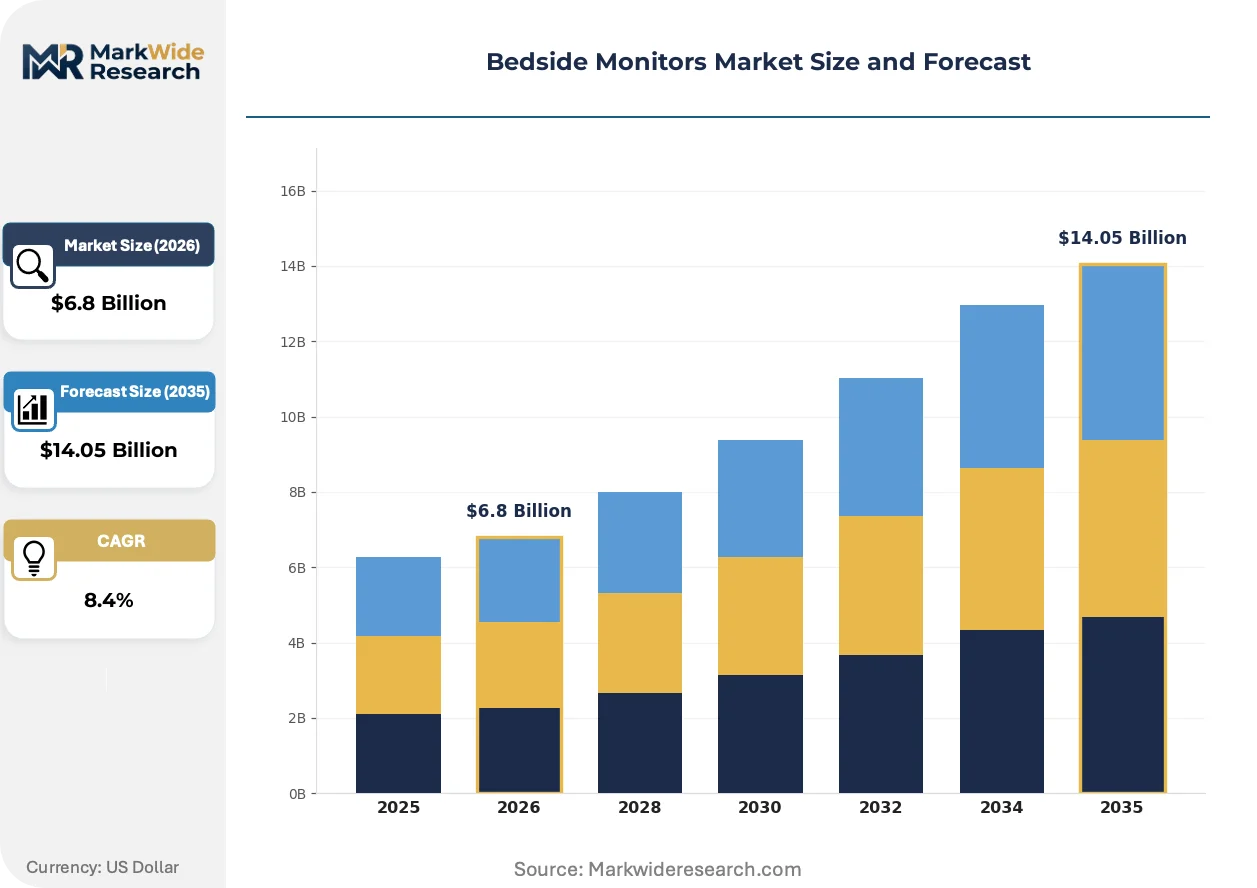
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Monitors, Portable Monitors, Multi-Parameter Monitors, Fetal Monitors End User: Hospitals, Home Care Providers, Emergency Care Units, Ambulatory Surgical Centers Technology: Wireless Technology, Analog Technology, Integrated Technology, Advanced Monitoring Systems Application: Critical Care, Post-Anesthesia Monitoring, Emergency Medical Services, Neonatal Monitoring |
| Companies Covered | Philips Healthcare, GE Healthcare, Medtronic, Mindray Medical, Nihon Kohden, Drägerwerk, Siemens Healthineers, Spacelabs Healthcare, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedside Monitors Market Evolving Landscape
Digital health infrastructure investments are reconfiguring how acute care data flows from bedside acquisition to enterprise analytics, compressing the gap between physiological measurement and clinical decision support.
Cloud-native middleware architectures are digitizing how monitoring data traverses hospital networks. Health systems in the United States and Germany are deploying these platforms to consolidate telemetry streams from dispersed units into centralized command centers. This digitizing infrastructure enables remote intensivist coverage models that extend specialist reach across rural and suburban facilities without proportional staffing expansion.
The EU Medical Device Regulation is tightening clinical evidence requirements for class IIa and above patient monitors, forcing manufacturers to generate prospective performance data rather than relying on predicate equivalence. European notified bodies are extending review timelines as they build technical competence in software-as-medical-device classifications. Asian manufacturers targeting European markets are establishing captive clinical investigation sites to satisfy MDR documentation burdens.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, treating preventive maintenance and software updates as separately negotiated line items. Large integrated delivery networks in the United States are driving this disaggregation to capture volume discounts across multi-hospital rollouts. Mid-tier facilities respond by negotiating performance-based service level agreements tied to device uptime metrics rather than fixed preventive maintenance schedules.
Bedside Monitors Market Segmentation
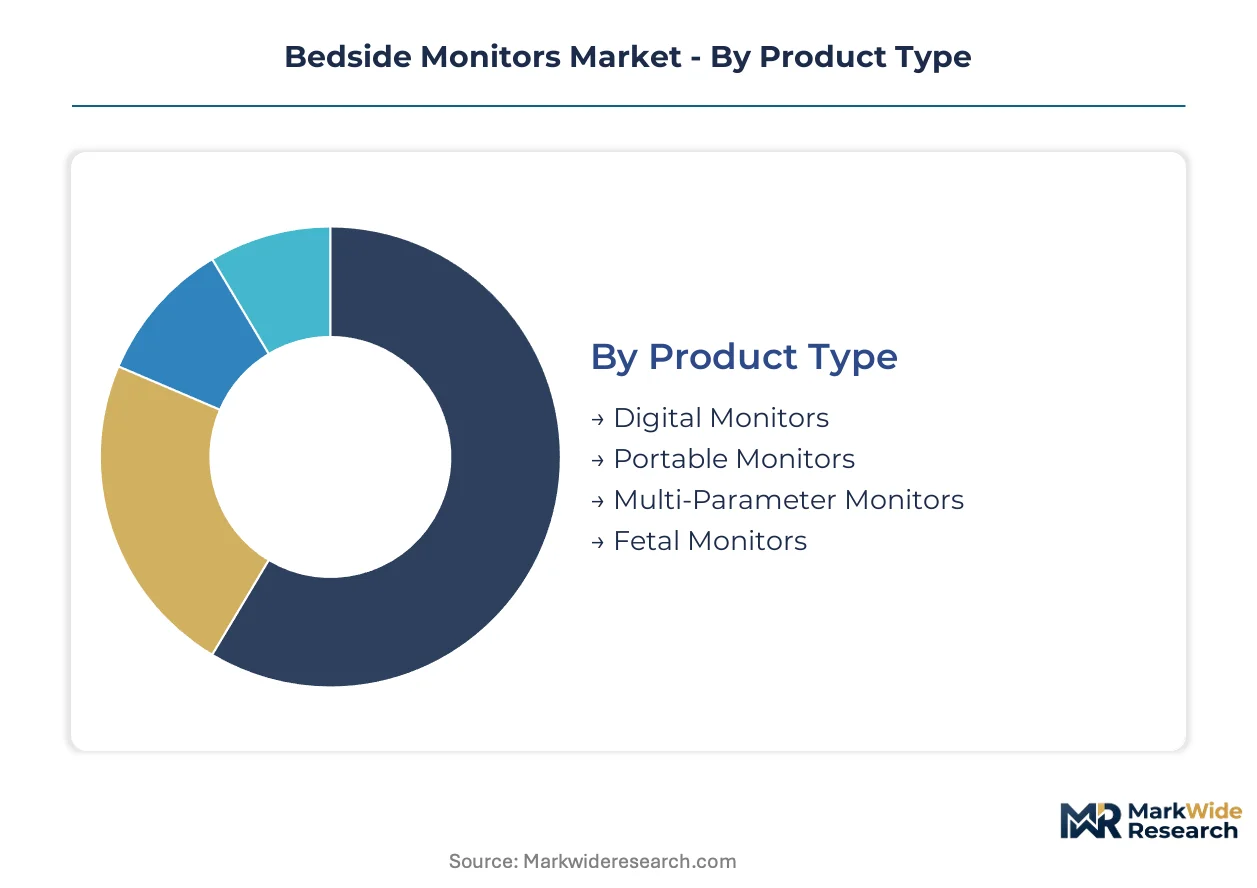
Bedside monitor segmentation reflects divergent replacement cycles across acute care infrastructure. Wireless-enabled platforms turn over every 4-6 years as cybersecurity protocols evolve, while analog installations persist for 10-15 years in cost-constrained settings. Understanding these temporal patterns guides capital allocation and aftermarket service planning.
Product Type:
Replacement velocity varies dramatically across form factors, with portable units cycling fastest due to physical wear and battery degradation while fixed installations depreciate over longer horizons.
- Multi-Parameter Monitors:Unified platforms consolidate ECG, SpO2, respiratory rate, and invasive pressure measurement through modular parameter acquisition modules. Tertiary hospitals in the United States and Germany standardize on these systems to reduce training overhead and simplify central station integration as patient acuity rises.
- Portable Monitors:Battery-powered devices with 10-15 inch displays enable patient transport and step-down unit mobility. Emergency medical services in Japan demand ruggedized enclosures and extended battery endurance, commanding price premiums over fixed installations despite smaller screen formats.
- Digital Monitors:Network-connected devices with cloud-native middleware architectures support centralized command center deployments.
- Fetal Monitors:Specialized obstetric systems track fetal heart rate and uterine contractions through ultrasound and tocography sensors.
Multi-Parameter Monitors anchors the volume base while Portable Monitors gains share at the steepest rate.
End User:
Procurement sophistication stratifies sharply across customer categories, with integrated delivery networks driving standardization while fragmented purchasers prioritize acquisition cost over total cost of ownership.
- Hospitals:Acute care facilities deploy multi-parameter platforms across intensive care, step-down, and general medical-surgical units. FDA 510(k) clearance efficiency and established service infrastructure from incumbent vendors shape procurement committee decisions in the United States.
- Emergency Care Units:Trauma centers and emergency departments require rapid-deployment monitors with defibrillation synchronization and invasive pressure capability. German tertiary hospitals are expanding high-acuity emergency capacity to address aging patient populations with complex comorbidities.
- Home Care Providers:Post-acute and long-term care settings adopt simplified telemetry devices for remote patient surveillance.
- Ambulatory Surgical Centers:Outpatient facilities prioritize compact footprint and rapid disinfection protocols.
Hospitals dominates absolute expenditure while Emergency Care Units demonstrates the most aggressive expansion trajectory.
Technology:
Architecture decisions determine connectivity scope, with wireless systems enabling enterprise integration while analog persists where electromagnetic interference or cybersecurity constraints dominate.
- Wireless Technology:Telemetry-enabled devices transmit physiological data through 2.4 GHz or 5 GHz spectrum to central station receivers. IEC 80001-1 risk management compliance and FDA cybersecurity guidance reshape firmware development priorities as hospital IT ecosystem integration deepens.
- Advanced Monitoring Systems:AI-enhanced platforms apply machine learning to multi-parameter streams for predictive deterioration detection. Japanese health systems are piloting these capabilities to extend intensivist coverage across dispersed facilities without proportional staffing expansion.
- Analog Technology:Hardwired architectures persist in electromagnetic-sensitive environments such as magnetic resonance imaging suites.
- Integrated Technology:Hybrid platforms combine local display with optional wireless transmission for flexible deployment.
Wireless Technology commands the largest installed base value while Advanced Monitoring Systems climbs fastest in revenue contribution.
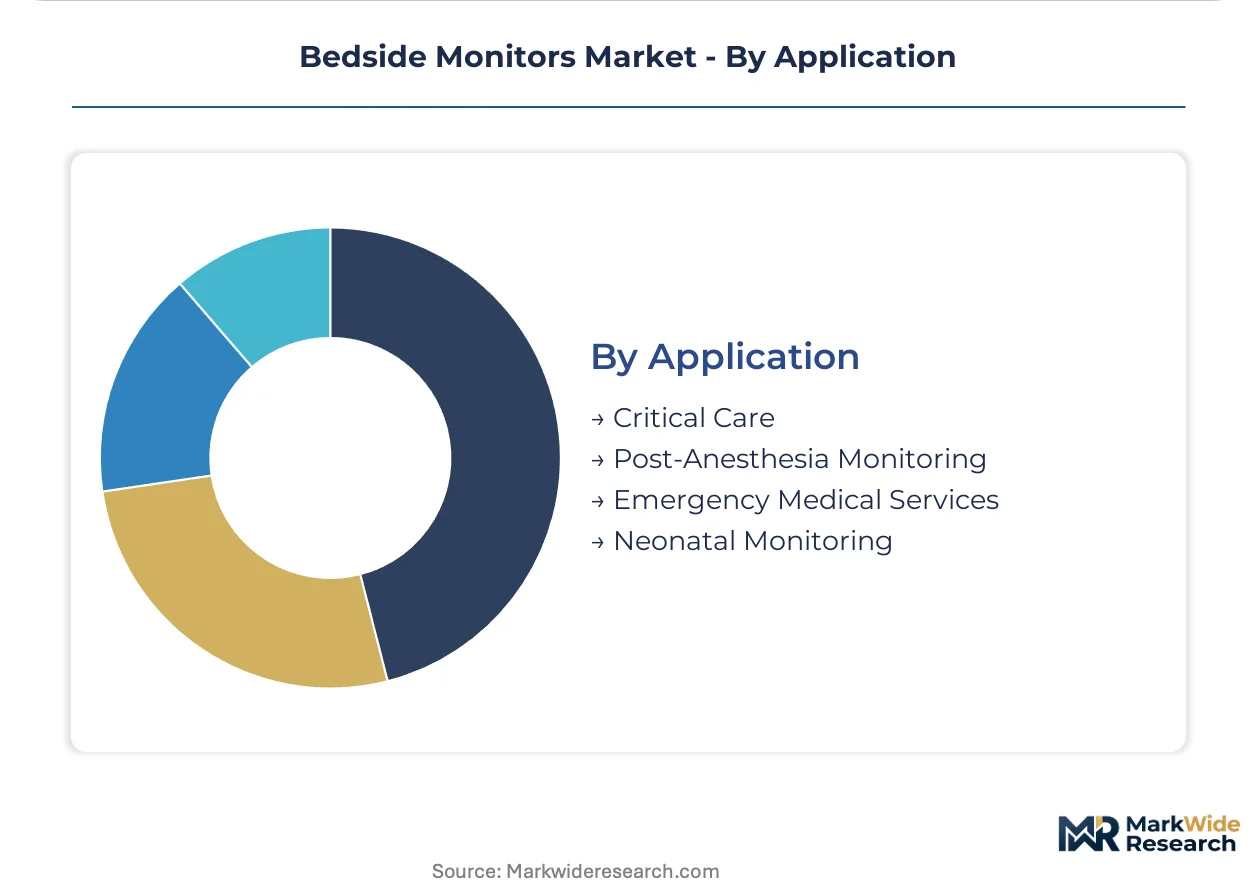
Application:
Clinical use case dictates performance requirements, with continuous surveillance settings demanding full parameter suites while intermittent monitoring accepts simplified configurations.
- Critical Care:Intensive care and coronary care units require invasive pressure monitoring, arrhythmia detection, and multi-lead ECG analysis. EU MDR clinical evidence requirements for class IIa devices lengthen certification timelines for non-European manufacturers targeting this high-value segment.
- Neonatal Monitoring:Specialized systems for premature and term infants incorporate apnea detection, transcutaneous oxygen monitoring, and reduced alarm thresholds. Japanese tertiary hospitals are expanding neonatal intensive care capacity to address low birth weight trends.
- Post-Anesthesia Monitoring:Recovery units prioritize respiratory rate and oxygen saturation surveillance during emergence from anesthesia.
- Emergency Medical Services:Pre-hospital settings demand ruggedization, rapid startup, and extended battery operation.
Critical Care generates the highest revenue per bed while Neonatal Monitoring expands most quickly in unit shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for critical care equipment, while Shanghai Pudong International Airport's cold-chain cargo terminals anchor Asia-Pacific supply velocity for temperature-sensitive sensor modules.
United States
Integrated delivery networks in Texas and Florida are expanding ICU bed capacity to serve aging populations with complex comorbidities. FDA 510(k) clearance pathways for modular parameter upgrades accelerate product iteration cycles compared to de novo routes. The Minneapolis-St. Paul corridor concentrates device manufacturing and health system procurement headquarters.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are adding high-acuity emergency capacity for aging patient cohorts. EU MDR clinical evidence requirements for class IIa patient monitors lengthen certification timelines for non-European manufacturers. The Baden-Württemberg region hosts precision sensor fabrication clusters serving multi-parameter platform assembly.
China
Domestic manufacturing zones in Jiangsu and Guangdong provinces are expanding production capacity for critical care devices to reduce import dependency. NMPA regulatory harmonization with international standards accelerates market access for locally manufactured equipment. The Yangtze River Delta corridor concentrates display system and analog front-end component supply.
Japan
Health systems in Kanto and Kansai regions are piloting AI-enhanced monitoring platforms to extend intensivist coverage across dispersed facilities. PMDA consultation procedures for software-as-medical-device classifications guide firmware development priorities. The Nagoya industrial corridor anchors neonatal intensive care device specialization for low birth weight trend response.
India
Corporate hospital chains in Maharashtra and Karnataka are standardizing on multi-parameter platforms to reduce training overhead across expanding bed networks. CDSCO medical device rules for class B and C patient monitors impose quality management system requirements on importers. The Delhi-Mumbai Industrial Corridor is attracting contract manufacturing investments for cost-engineered portable monitor assembly.
Bedside Monitors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor modules and display subsystems. The vendor base stratifies across three tiers: diversified health technology conglomerates with captive service infrastructure, mid-scale specialists competing on cost-engineered configurations, and regional assemblers serving price-sensitive procurement committees. Two dominant competitive moves are reshaping positioning: backward integration into analog front-end component supply to secure margin control, and strategic partnerships with hospital IT vendors to ease cybersecurity compliance burdens.
Among diversified health technology conglomerates, Philips Healthcare and GE Healthcare exemplify platform integrators with established North American service networks. Siemens Healthineers occupies a position within the European-centered tier, while Mindray Medical represents the cost-engineered specialist archetype targeting mid-tier facility procurement in Asia-Pacific and emerging markets. These three anchors illustrate how geographic origin and organizational scale map to distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Mindray Medical |
| Nihon Kohden |
| Drägerwerk |
| Siemens Healthineers |
| Spacelabs Healthcare |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Jiangsu province's expanding domestic manufacturing zones for critical care devices are compressing landed costs for sensor modules and display systems, translating into pricing leverage for cost-engineered platform assemblers serving mid-tier hospital procurement committees across Asia-Pacific.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across bedside monitor categories, separating premium multi-parameter platforms with modular upgrade capabilities from standard fixed installations and economy analog systems lacking wireless telemetry. Price differentiation hinges on IEC 60601-1-8 alarm safety certification grade and after-sales service bundling, with unbundled maintenance contracts accelerating as integrated delivery networks negotiate volume discounts. Cost compression in the standard tier intensifies because semiconductor input volatility and EU MDR clinical evidence documentation burdens inflate compliance overhead. Emergency medical services in Japan demonstrate the least price sensitivity, accepting ruggedization premiums, while ambulatory surgical centers in India exhibit acute acquisition-cost focus with minimal total-cost-of-ownership evaluation.
Supply Chain Analysis
Analog front-end semiconductor fabrication feeds from concentrated foundry capacity in Taiwan, South Korea, and China, with sensor module assembly tethered to Yangtze River Delta display subsystem clusters. Critical inputs span precision ECG electrodes, pulse oximetry LED-photodetector pairs, and medical-grade capacitive touch panels. Single-source vulnerability concentrates in specialized ASIC supply for multi-parameter acquisition modules. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct tender processes in Germany, and centralized Ministry of Health frameworks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive maintenance and software update subscriptions are expanding faster than hardware replacement cycles as hospital procurement committees unbundle service contracts from capital equipment purchases.
For Market Incumbents: Build captive service infrastructure moats by embedding FDA cybersecurity guidance compliance into firmware development roadmaps and anchoring multi-hospital integrated delivery network contracts with performance-based uptime guarantees. Philips Healthcare and GE Healthcare exemplify this defensive positioning against cost-engineered specialists from Asia-Pacific threatening mid-tier facility penetration. Backward integration into analog front-end component supply secures margin control against foundry concentration risk. For New Entrants and Emerging Players: Pursue step-down unit mobility segments where telemetry-enabled portable monitors address unmet demand for patient ambulation protocols, with Japanese health systems piloting AI-enhanced platforms as the most penetrable entry point. Emergency medical services in India offer secondary white-space opportunity given corporate hospital chain standardization drives. A software-as-medical-device go-to-market angle bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because cloud-native middleware architectures and subscription-based alarm analytics are reconfiguring acute care data flows toward enterprise analytics platforms. Acquisition targets should cluster around embedded systems cybersecurity specialists with IEC 80001-1 risk management expertise. The signal to watch is FDA guidance evolution on network-connected device post-market surveillance requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Philips Healthcare anchors North American procurement networks through established service infrastructure and GPO contract penetration. |
| Software Companion Development | AI-enhanced alarm analytics differentiate premium platforms by enabling predictive deterioration detection across multi-parameter streams. |
| CE Marking Pathway | EU MDR clinical evidence requirements for class IIa devices force manufacturers to generate prospective performance data rather than predicate equivalence. |
| FDA Submission | 510(k) substantial equivalence demonstrations accelerate modular parameter upgrade cycles compared to de novo classification routes. |
| Reimbursement Strategy | Remote intensivist coverage models enabled by telemetry consolidation support favorable procedural coding for centralized command centers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at device manufacturers, then refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and semiconductor trade flow data. Bottom-up installed base modeling and top-down expenditure triangulation anchored volume and value estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation modeled across product type, end user, technology architecture, application, and regional regulatory cluster dimensions. CAGRs were derived from replacement cycle analysis and capacity expansion trajectories. Forecast inputs incorporated ICU bed expansion rates in tertiary hospitals and wireless telemetry adoption curves in step-down units.
Sensitivities concentrate around semiconductor supply disruption, EU MDR certification timeline extensions, and FDA cybersecurity guidance enforcement intensity. Cross-checking against hospital capital expenditure surveys and medical device import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Heart Rate Monitor Market